Author: admin

  • Establishing Diversity, Equity and Inclusion As The Norm In All Workplaces

    Establishing Diversity, Equity and Inclusion As The Norm In All Workplaces

    A well-coordinated team is a true asset to any organisation. According to research on team dynamics and performance, diverse and inclusive teams tend to make better decisions and are more innovative.

    Striving to increase workplace diversity is not an empty slogan — it is a good business decision.

    Diversification and equity initiatives are critical to a company’s success. However, these aspects don’t mean anything in the absence of an inclusive workplace. So the question becomes – how do employers establish a workplace that prioritises all three elements?

    Diversity, Equity & Inclusion In the workplace

    Diversity in the workplace usually involves people from different backgrounds, ethnicities, genders, ages working together without any disparagement. It usually refers to a gender ratio that is balanced, but it can also refer to people of non-binary genders. As a result, it can be defined as a balanced representation of all genders in any workplace.

    On the other hand, equity is the value of being fair and equal based on individual contributions. There may be some confusion as to the difference between equity and equality. While equality means being equal to everyone by providing the same benefits to all, equity is an organisation’s ability to offer flexi-benefits according to individual needs so that they are able to reach their full potential.

    Workplace equity is all about empowering employees and ensuring that everyone is on an equal footing. When organisations promote equity in the workplace, they gain a competitive advantage by employing a diverse workforce. There is equal opportunity when there is equity.

    Inclusion is the state that provides each and every employee with a sense of belonging despite gender racial and age differences. Workplace inclusion efforts help to give traditionally marginalised groups, even those with physical or mental disabilities, a way to feel equal in the workplace.

    However, because we are human beings driven by emotions as much as objectivity, it is easy to fall short of what constitutes a best practice and mistakes happen. To safeguard all employees and to ensure the highest standards of diversity, equity, and inclusivity, nonetheless, I would recommend using an automated system like WorkSmartly.

    With a trusted tool that is unbiased, employers can be more assured of employees having access to equal opportunity. 

    How Organisations Can Develop Diversity, Equity & Inclusion

    Human resources, Talent management and recruitment business concept and empty copy space for your text

    Developing equitable workplaces will require sustained and prolonged efforts on the part of management and Human Resource (HR)  teams as the most effective way to implement major changes effectively is through the top-down approach. Understanding internalised biases and their effects are the first steps in building equitable work environments as everyone was brought up differently and coming from various walks of life. This leads to different work experiences.

    Everything should be colourless and generous to every employee, with a focus on matters or incidents rather than individuals. For example, companies should look to have a neutral time (example: company fiscal year) to hand out bonuses during “neutral” time periods, rather than during festive periods like Chinese New Year, Hari Raya, Deepavali as this may show bias toward a particular race.

    Additionally, recruiters should demonstrate neutrality when selecting candidates. They should hire new employees based on their performance, skills, and capabilities, not on their own culture or other factors.  Robust HR platforms like WorkSmartly filter candidate profiles and resumes according to their achievements, skills, and suitability.  This would be particularly useful here as automated systems do not run the risk of being swayed by non-work-related differences. Ultimately, this ensures transparency in an environment that prioritises growth.

    Another aspect to look forwards to is increasing digitisation which will create more opportunities for diversification. From remote work options to the rise in the gig economy, employers are no longer forced to default to traditional work practices. New generations are becoming more open and their cultural acceptance has increased due to greater exposure via  technology. For example, the way the current workforce thinks and acts is getting more unified based on the influence of social media.

    Challenges that Malaysian Employees Face in the Workplace

    Skyscrapers in Kuala Lumpur, Malaysia City Center skyline.

    More than ensuring the diversity, equity and inclusion of a workplace, I think that it is important for employers to be aware of the external challenges frequently faced by the workforce. One of them is gender inequality. To date, it has been reported that only 38% of women occupy managerial roles as compared to 62% of men in managerial positions.

    In Malaysia, 56% of women have experienced at least one form of gender discrimination in the workplace, according to the “Voices of Malaysian Women On Discrimination & Harassment in the Workplace” survey. Women’s low participation in the workforce could be due to a variety of factors, including discrimination, harassment, and a greater unpaid care burden, which affects both employees and job seekers.

    Besides that, people who have been out of work for a while have typically found it much harder to get a job. If being unemployed and finding a job weren’t hard enough already, research shows that large work history gaps are the main reasons that unemployed people aren’t getting hired. Prejudice against the unemployed isn’t limited to those who have been out of work for a long time, it can also apply to those who have recently quit or lost their jobs.

    While this has been an ongoing problem for many during the pre-pandemic period, those who faced retrenchment due to pandemic-related business closures have been particularly hard hit.

    It is also important to note that diversity, equity and inclusion can’t be achieved when there is bias in the hiring process-the number one step for organisations to build strong, long-lasting foundations. Most companies typically lean towards hiring more experienced employees rather than fresh graduates. Many employers believe that this hiring strategy makes the transition easier as they already have background experience.

    The downside to this practice, however, is that it limits the opportunities and options for fresh graduates to learn new skills and demonstrate their talents to a company, eventually resulting in an out-dated talent pool. Therefore, I urge organisations to keep their windows as open and inclusive as possible to provide younger talents with opportunities to grow, thereby making way for fresh, new ideas that could result in a breakthrough.

    It’s important to value diversity, equity, and inclusion. They make organisations stronger and more agile, and they are more important than ever in today’s rapidly changing business environment. Leaders who want to make significant progress should apply universal principles with care to their unique cultural and strategic circumstances. It’s important to consider the context.

    This article is written by Victor Phang, CEO and Founder of WorkSmartly

    About WorkSmartly

    WorkSmartly is an end-to-end HR solution that is designed specifically for HR processes throughout the employees’ work life cycle. It began as iTalent in 2008 before being rebranded to WorkSmartly in 2018. With 8 offices globally and more than 200 clients including several Fortune 500 companies, WorkSmartly is aspiring to be the leading enterprise HR-tech provider globally. Among WorkSmartly’s clients are EasyParcel, Emart, Exabytes, MDEC, PETRA Mobilia, Pgeon, Roche, See Hup and Sony.
  • ESG Investing And The 3 Steps To Build An ESG Portfolio

    ESG Investing And The 3 Steps To Build An ESG Portfolio

    In the past two years, we have seen the stellar ascent of environmental, social and governance (ESG) factors in the investment realm. Formerly a niche term popular amongst sophisticated and institutional investors, ESG investing has now found itself pushed into the mainstream and embedded firmly into public consciousness.

    Global investors have become more aware about the broad sustainability challenges that we face in the world today as the pandemic exposes the wider rifts in society. However, a lack of standardisation coupled with overuse of the term has created a lot of confusion about what ESG actually entails.

    Here is a closer look at ESG investing (sometimes interchangeably referred to as sustainable investing) and how investors can get started.

    Definition of ESG

    As alluded earlier, ESG are a set of non-financial factors that investors or fund managers use to assess the sustainability of a company through three distinct lenses namely environment, social and governance.

    Environmental factors consider the company’s stewardship of natural resources including conservation of the environment as well as reducing its carbon footprint.

    Social factors examines the company’s relationship and treatment of all its stakeholders including suppliers, customers, staff and the wider community it operates in.

    Governance deals with the company’s set of policies and procedures related to its corporate governance to ensure clear lines of accountability between shareholder and management. These include safeguards to avoid conflict of interests such as the presence of independent boards as well an audit or remuneration committee.

    By evaluating all three factors, investors can then screen out potential investments especially if they pose a material impact to the company’s operations and its financials.

    Such information can be typically gleaned through the company’s annual report where enhanced disclosure guidelines require companies to provide information about its key sustainability indicators such as environmental and social footprint.

    Steps to Building an ESG Portfolio

    The first challenge for investors looking to dip their toes in the ESG arena is finding out where to begin. Given how large the investment universe has grown, it is important to take a methodical approach and establish several things first at the outset.

    Step 1: Identify Investment Objective and Intent

    The first question you need to ask is your investment intent and objective in wanting to incorporate an ESG strategy in your portfolio. There may be some introspection required to unpack your motivations to understand the specific causes or issues that you are prepared to invest/not invest in.

    It is an important step because this would determine how deep you would go in this specific route:

    • Is this a strategy to add diversification and reduce asset correlation?
    • Are you looking to gain exposure to specific themes like green energy?
    • Are there certain causes that you deeply believe in and want to include in your portfolio through purpose-driven solutions?
    • Alternatively, do you want to embrace ESG wholeheartedly as an investment philosophy and want a pure ESG portfolio?

    All investors have different goals and objectives which would in turn influence their degree of involvement in ESG.

    On one end of the spectrum, investors may not be ESG-aware and does not consider ESG factors at all in their investment decisions. On the other end, investors are fully on-board with ESG and want it fully ingrained in their portfolio. More often than not, they are situated somewhere in between.

    Wherever you find yourself, it is okay to pick a point to start and then move along the spectrum as and when you feel comfortable.

    Step 2: Which Approach Suits You? 

    Hand of human holding green earth ESG icon for Environment Social and Governance, World sustainable environment concept.

    Once you have uncovered your motivation to get started in ESG, it is now time to explore which approach suits you best.

    Very broadly, ESG funds are grouped according to the following categories depending on the strategy it employs:

    Negative screening is an exclusion strategy where companies with poor ESG scores are sieved through and ruled out from the portfolio’s investable universe. Common exclusions include those companies with a poor track record in environmental management or with a history of labour malpractices.

    Values-based funds such as Shariah-compliant funds also employ a negative screen to filter out companies that to not adhere to the principles of the faith such as gambling or alcohol.

    Positive screening seeks out companies with a strong ESG score to be included in the portfolio’s holdings. Companies are often benchmarked against their peers or the industry’s best practices in choosing the cream of the crop. Companies that are actively committed to improving their ESG scores may also be considered by the fund manager.

    Thematic funds often use a positive screen to choose best-in-class companies involved in specific investment themes like decarbonisation or climate change.

    However, both positive and negative screening are typically regarded as two sides of the same coin and are used concurrently by fund managers.

    ESG integration is the inclusion of material ESG factors on top of traditional financial metrics in the investment decision making process. For example, a company’s emission data are evaluated alongside other financial measures to assess potential risks or opportunities. A more encompassing approach, ESG integration gathers data from multiple sources with an aim to deliver better risk-adjusted returns.

    This approach is often used for funds which may not even have an explicit sustainability mandate or objective such as traditional equity or bond funds. This is because more investors realise that ESG integration offers enhanced risk management by identifying the mid-to-long term risks that could hurt the stock’s fundamentals. For instance, companies that have poor labour practices face increased risk of lawsuits, customer order cancellations as well as reputational damage.

    Impact investing refers to funds or investment solutions designed to produce specific outcomes that are beneficial to society or the environment, alongside financial returns. It has a more explicit intent to generate social or environmental returns such as development of clean energy or microfinancing. Types of investments include green bonds or sustainability-linked bonds which are earmarked to finance specific projects or initiatives.

    Depending on your investment objective, either one or a combination of the above approaches might suit your portfolio needs. There is no one-size-fits-all approach when it comes to ESG investing as the requirement of each portfolio hinges on very personal choices and values. It is all a matter of aligning the outcomes you want and your investment objectives.

    Step 3: Make a Plan to Invest

    Mutual fund investors can then integrate ESG into their portfolios either by:

    • introducing ESG specific themed funds; or
    • integrating ESG factors into their investment analysis for all funds.

    With a growing array of ESG funds spanning different strategies and asset classes, there is plenty to choose from. Malaysian investors can find a list of sustainable and responsible Investment (SRI) funds on the Securities Commission Malaysia website.

    Like picking any fund to invest, it is crucial that investors understand the fund’s objective and strategy by reading up its prospectus and product highlight sheet. Be on the lookout for greenwashing red flags in funds that make unwarranted or ambiguous claims.

    Ensure that you actually understand what the fund aims to do and its strategy in achieving those outcomes. Is it to avoid certain industries or companies? Does it aim to make an impact in a sector?

    Investors should also ensure the ESG characteristics of the holdings are also consistent with the fund’s claims. Traditional tools and resources in fund selection can help in ensuring that you’re picking the right fund for you by looking at its ESG rating and profile of its holdings.

    Why ESG?

    ESG, Environmental, Social and Governance printed in blue with two rubber stamps over white background. Corporate responsibility concept.

    ESG or sustainable investing provides a platform for investors to demonstrate their personal values and play a role in financing assets that are contributing positively to environmental and social causes.

    Besides that, ESG investing also offers several distinct advantages to investors in terms of enhanced risk management as well as a differentiated driver of returns.  Companies with higher ESG scores could mean more ethical business practices that leads to improved stakeholder engagement as well as staying on the right side of governments/regulators.

    In recent times, we have seen the share price of companies with poor ESG practices being punished as global fund managers shun these companies. Many see ESG investing as a structural trend that will persist as long as social and environmental imbalances exist and there is a desire to address these gaps.

    Invest with Purpose

    The myth that investors have to pick between investing according to their values and sacrificing performance is an old one. Studies have shown that over the long-term, ESG funds can lead to improved returns and lower volatility overall. So, investors don’t have to worry about making trade-offs.

    With a variety of solutions available in the market, investors can invest with purpose to reap rewards that go beyond just financial returns.

    About the Author

    Lee Sheung Un is a Communications Officer at Affin Hwang Asset Management. A millennial, he is still finding that balance between wealth, freedom and purpose. Views expressed are his own.

  • 3 Market Trends That An Investor Should Look Out For In 2022

    3 Market Trends That An Investor Should Look Out For In 2022

    The world is recovering from the pandemic and global economy is poised to be fueled by the normalisation of economic activity globally. Over here in Malaysia, we just opened up our international borders and is seen as a good sign for our economic growth.

    As a smart investor, we need to be aware of the market trends that are happening all around us.

    Let’s hear from Germaine Share who is the Director of Manager Research at Morningstar, on the 3 market trends that an investor should look out for in 2022.

    1. ESG (Environmental, Social, and Governance)

    Environmental, social, and governance (ESG) investment Organizational growth. Wooden cube with symbol of esg concept

    We continued to see growing interests in sustainable investing as investors become increasingly aware of ESG issues, and some of them believe it would lead to better investment outcomes.

    Global sustainable fund assets grew to US$2.74 trillion as of 2021-end, up 53% from a year ago, according to Morningstar’s quarterly sustainable fund flows report. There are now almost 6,000 sustainable funds globally. Inflows grew as well, driven by continued investor interest in environmental, social, and governance issues and by regulation.

    In Malaysia, despite a small base, locally domiciled ESG funds expanded by 50% over 2021 to US$877.1 billion. There were record 13 sustainable fund launches in 2021, compared to just two launches a year earlier. We see the rising number of ESG fund launches not unique to Malaysia, but a global trend on the back of greater ESG awareness amongst investors with the importance of climate change agenda championed by various governments.

    As sustainable investing becomes more mainstream, we see more regulators in Asia launching practical guidelines to help avoid greenwashing and importantly, to better inform investors when they consider investing in ESG funds.

    2. Inflation

    For many years, inflation has not been a major concern for investors given the low interest rates and decent market returns. This year, the risk is real. Inflation is at 30-year highs in the US. Higher inflation tends to lead to higher interest rates, which hurt corporate profits and cause losses for bond holders.

    Equity investors’ total return can also be in jeopardy: their dividend payments are worth less, and their earnings can suffer from higher input costs, particularly if they are not in a position to pass along higher prices to their consumers. As earnings come under pressure, so can their ability to generate inflation-beating returns.

    There are many assets suited for inflation protection, such as short-duration bonds or cash, high-yield bonds or inflation-protected bonds, or stocks that are either positively correlated to inflation, for example energy stocks, or high-quality names with high degrees of pricing power that can pass along rising input costs. 

    3. Yield

    Coin on wooden table in front of green bokeh background. coins a concept of investment and saving moneys.

    With negative yields on government bonds (after adjusting for inflation) across developed government-bond markets and corporate credit spreads at multi-year lows, the global fixed-income universe is looking at paltry returns.

    In comparison, Asian and emerging market bonds continue to offer a reasonable yield for income-seeking investors who are comfortable with taking more risk.

    About the author

    Germaine Share is the Director of Manager Research at Morningstar

  • Here’s The Reason Why Kenanga Investors Won This Coveted Morningstar Award

    Here’s The Reason Why Kenanga Investors Won This Coveted Morningstar Award

    Congratulations to Kenanga Investors Berhad for winning the Best Malaysia Large-Cap Equity Fund. In a tough market last year, Kenanga manages to put in a stellar performance and outperform all others.

    We spoke to Lee Sook Yee, Chief Investment Officer of Kenanga Investors Berhad to share more about their secret for success.

    Key Factors Behind The Success Of This Fund?

    We are honoured to have received this award from Morningstar. This award reflects our team’s dedication and perseverance to continuously go above and beyond for our clients.

    As a bottom up stock picker, our investment is underpinned by comprehensive fundamental research combined with a relative value approach to create superior risk adjusted returns.

    In formulating a company’s investment thesis, we usually run channel checks on the company’s competitive advantages and also attempt to model out the growth drivers. Some of the key areas we look at include management quality, sustainable business model, industry dynamics and balance sheet strength.

    By consistently applying this strategy, our funds have achieved continuously outperforming returns throughout the last 3,5 and 10 years.

    Strategies To Maximise The Chance Of Success For The Fund

    Half recovering from the pandemic-stricken crisis, 2021 presented both challenges and opportunities. One of the biggest challenges was having to grapple with the lingering impact of the pandemic, as persistent waves of Covid resurgence triggered intermittent lockdowns and containment measures, which when happened pulled the markets down with them.

    Although such corrections became less intense as vaccination gathered pace, new sources of fear took shape in the form of worries over rising inflationary pressure attributed to severe supply chain disruption, talent and component shortage, power rationing which impacted our investments in varying degree.

    We navigated through these speed bumps by constantly reviewing our investment theses to make sure they stayed relevant, identified the “relative winners” from sectors which were deemed resilient, consistently-growing and reasonably priced. Tech sector was one key sector which ticked most boxes and contributed immensely to our outperformance last year.

    Can We Expect New Investment Products By Kenanga Investors?

    We look forward to expanding our Kenanga Sustainability Series, a suite of multi-asset class products rooted in sustainability considerations to advance long-term financial growth for investors and to generate social and financial value for surrounding communities, in 2022. We introduced the first fund under this series in 2021 which was the Kenanga Sustainability Series: Frontier Fund. It provides investors with a range of opportunities in boosting not only the future development curve through the reduction of carbon emissions, new medical discoveries that may propel patient empowerment, and greater societal benefits while driving sustainable returns.

  • PB Asia Equity Fund (PBAEF) and Public Islamic Alpha-40 Growth Fund (PIA40GF) Wins It Again For Public Mutual

    PB Asia Equity Fund (PBAEF) and Public Islamic Alpha-40 Growth Fund (PIA40GF) Wins It Again For Public Mutual

    Congratulations to Public Mutual for another double win for the second successive year. It is no easy feat to achieve, considering the tough market in 2021.

    On hand to share more insights on their success, we spoke to Chiang Kang Pey, Deputy Chief Executive Officer of Public Mutual.

    Key Factors Behind These Two Wins?

    Our key strategy behind both wins is our adherence to a fundamental investment approach of focusing on companies with sustained earnings, strong financial positions and proven track records. Despite the elevated levels of market volatility in 2021, the portfolios of our winning funds – PB Asia Equity Fund (PBAEF) and Public Islamic Alpha-40 Growth Fund (PIA40GF) – were rebalanced accordingly in line with the changing trends in the respective markets, sectors and industries that the funds were invested in.

    Steps Taken For Best Chance Of Continued Growth?

    In 2021, PBAEF, which focuses its investments in the Asian markets, locked in profits from selected growth stocks and positioned in semiconductor-related stocks within the Asian region which benefitted from the shortage of chips amid supply chain disruptions and China’s localisation trend. In addition, the fund’s performance was lifted by its holdings of North Asian technology and electric vehicle-related stocks which ride on the structural trends of digitalisation and the increased focus on cleaner energy solutions.

    Meanwhile, PIA40GF, which focuses its investments in the domestic market, continued to capitalise on technology and basic materials stocks which stood to benefit from the long-term digitalisation trend as well as the strength in commodity prices. The fund also locked in gains from selected technology stocks at the end of 2021 amid concerns over the potential rise in global interest rates.

    To ensure the long-term growth of our funds, we constantly assess and monitor the long-term prospects of our investee companies’ business models and strategies – including their pricing power, market dominance, growth potential as well as the competitive landscape. These strategies have proven to work well for the performance of our funds.

    Strategies That Have Shifted In Line With Market Forces?

    Despite the decline in the severity of symptoms for the newer Covid-19 Omicron variant, the evolving nature of this virus could mean that potentially new and unpredictable variants may emerge. Nevertheless, barring unforeseen circumstances, the global economy is anticipated to continue on its path towards recovery amid the easing of movement restrictions and the re-opening of international borders as governments increasingly transition towards policies to ‘live with Covid’.

    Tightening monetary policies by global central banks, global supply chain disruptions as well as sanctions triggered by the current geopolitical conflict between Russia and Ukraine have also led to elevated levels of volatility in global financial markets this year.

    That said, the domestic and Asian markets – which PIA40GF and PBAEF focus their investments on – are less exposed to the geopolitical risks in Europe. As such, both funds will continue to invest in selected recovery plays within the local and regional markets such as the financial, energy and commodities sectors, as well as selected consumer discretionary and leisure stocks.

    The funds will also continue to position for the long-term growth potential of the technology sector which will benefit from the increasing adoption of digital products and services as well as the rise of automation, online shopping and hybrid/ remote working arrangements.

    Upcoming Trends For Investors?

    Global markets may continue to experience volatility and uncertainties in the short term amid the normalisation of monetary policies by major central banks in response to elevated inflation levels, as well as the current Russia-Ukraine conflict which has exacerbated global supply chain disruptions and inflationary pressures. Meanwhile, the performance of the China stock market will depend on whether the Chinese government will continue to implement policies on sectors such as technology and real estate which may impact their profitability or earnings visibility.

    In addition to the recovery plays which will benefit from the re-opening of international borders and the lifting of social-distancing restrictions, investors are expected to focus on sectors that are more defensive such as utilities and consumer staples amidst the uncertainty surrounding the global economic outlook. Sectors that will benefit from the impact of high inflation such as the commodity, basic materials and energy sectors which have staged a strong performance compared to the broader markets thus far this year may also continue to outperform if inflationary pressures remain elevated.

    Over the longer term, sectors that possess structural growth prospects such as those driven by the trends of digitalisation and the push towards greener energy solutions are also expected to do well. The rising adoption of cloud computing, artificial intelligence, cybersecurity, e-commerce, electric vehicles and lower-carbon solutions is expected to drive sustainable earnings growth for companies in these segments in the years ahead. The valuations of such growth-oriented stocks have also fallen on profit-taking activities amid higher bond yields; thus providing buying opportunities for investors who have a longer-term investment horizon.

    Plans And Strategies For 2022?

    We will remain committed to our fundamental-based approach and long-term investment strategies which have served us well in delivering consistent returns to our unitholders over the long term. Given the volatile markets amid uncertainties surrounding the Russia-Ukraine conflict and its impact on global growth and inflation, we have adopted a portfolio comprising growth and value stocks.

    We will continue to monitor developments in the global markets so as to re-deploy our funds’
    cash holdings when opportunities arise.


  • Morningstar Announces Winners for 2022 Morningstar Fund Awards Malaysia

    Morningstar Announces Winners for 2022 Morningstar Fund Awards Malaysia

    KUALA LUMPUR, 7 April 2022 — Morningstar Asia Limited, a subsidiary of Morningstar, Inc. (NASDAQ: MORN), a leading provider of independent investment research, has announced the winning funds for its 2022 Morningstar Fund Awards Malaysia.

    The annual Morningstar Malaysia Fund Awards recognise retail funds that have added the most value for investors within the context of their relevant peer group in 2021 and over longer time periods. Morningstar selects the winners using a quantitative methodology, along with a qualitative overlay. Weightings to one-, three-, and five-year risk-adjusted performance are factored into the methodology.

    Wing Chan, Morningstar’s Head of Manager Research, Europe and Asia Pacific, remarked: “Our 2022 winners have proven themselves to be excellent stewards of investors’ capital. They have demonstrated their abilities to navigate through market volatility and deliver excellent returns over the longer term. We applaud all winners for their outstanding achievements.”

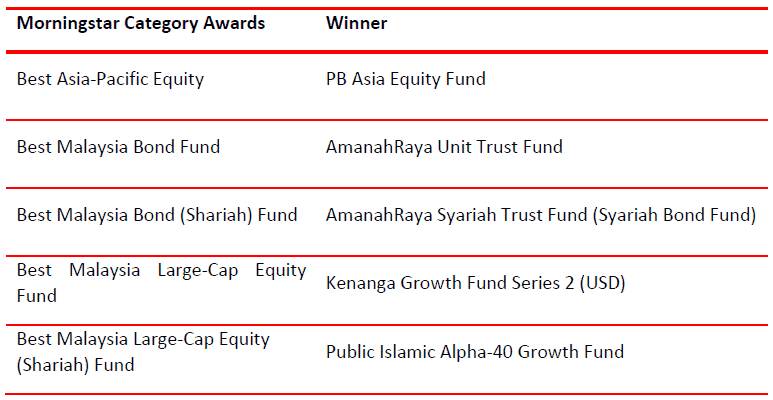
    The 2022 Morningstar Awards winners in Malaysia are:

    Methodology

    The Morningstar fund category awards are based on Morningstar fund data as of 31 December 2021. The awards methodology emphasises the one-year period, but funds must also have delivered strong three- and five-year returns after adjusting for risk within the awards peer groups in order to obtain an award. In selecting winners, fund returns are adjusted for risk using the Morningstar Risk, a measure which imposes a higher penalty for downside variation in a fund’s return than it does for
    upside volatility. For the full methodology, please click here. The full methodology for the awards is available here.

    Morningstar Asia Limited is a subsidiary of Morningstar, Inc., a leading provider of independent investment research in North America, Europe, Australia, and Asia. The Company offers an extensive line of products and services for individual investors, financial advisors, asset managers and owners, retirement plan providers and sponsors, and institutional investors in the debt and private capital markets. Morningstar provides data and research insights on a wide range of investment offerings, including managed investment products, publicly listed companies, private capital markets, debt securities, and real-time global market data. Morningstar also offers investment management services through its investment advisory subsidiaries, with approximately US$265 billion in assets under advisement and management as of Dec, 31. 2021. The Company has operations in 29 markets.

    For more information, visit www.morningstar.com/company. Follow Morningstar on Twitter @MorningstarInc.

    ©2022 Morningstar, Inc. All Rights Reserved.

  • Digital Art (NFT), Is It A Prudent Investment Or A Bubble Waiting To Burst?

    Digital Art (NFT), Is It A Prudent Investment Or A Bubble Waiting To Burst?

    If you have paid any attention to investing news over the past year, you would almost certainly have come across the term NFT (non-fungible token). Often linked to digital art, it is responsible for some of last year’s biggest investment headlines, with jaw-dropping amounts being spent on them.

    But what exactly is an NFT?

    In A Nutshell

    As the phrase “non-fungible” suggests, it is a one-of-a-kind, irreplaceable token that acknowledges a person’s ownership over a digital asset. Think of it as a digital certificate that recognises ownership, similar to a certificate of authenticity for valuable artwork or timepieces. Although NFTs are commonly linked to art, it can be used to prove ownership of any digital assets such as memes, songs or even tweets!

    The assets being sold can be freely viewed, or even saved to their own devices, by anyone, which is often what detractors point at when denouncing NFTs. However, just like how there are knockoff versions of famous art pieces, there is only ever one original, which is where it gets its perceived value.

    Like cryptocurrencies, owners of assets are documented on a publicly shared ledger, also known as the blockchain, that cannot be tampered with or altered by any single individual or party. Any changes to this ledger must be acknowledged and ratified by all members of the blockchain before being made permanent, making it close to impossible to tamper with.

    The most popular platform to buy or list NFTs is OpenSea but there is a raft of competing marketplaces that are all aiming to carve their own slice of a very lucrative pie. Local NFT marketplaces have also sprung up, with Pentas.io being the most prominent.

    Do They Have Any Use?

    Metaverse and Blockchain Technology Concepts. Person with an Experiences of Metaverse Virtual World via Smart Phone. Futuristic Tone. Conceptual Photo

    Although copies can be made of these digital artworks (memes, tweets, music etc.), the NFT is the sole acknowledgement of who is the “owner” of the piece. Art has long been used as a store of value, and this easily extends to digital art, with the value stored in the certificate of ownership.

    But whether this has any tangible value depends solely on the market. Many are of the belief that NFTs are in a bubble, including artists themselves.

    Digital artist Beeple, also known as Mike Winkelmann, holds the current record for the most expensive NFT, with his piece EVERYDAYS: THE FIRST 5000 DAYS, auctioned off by Christie’sforUS$69,346,250, but he thinks that NFTs are a bubble waiting to burst.

    Speaking to the New York Times Sway podcast last year, he said “This stuff will absolutely go to zero.”

    He believes the key aspect of NFTs is proving ownership which is why popular pieces trade for millions.

    “The more something is widely shared, the more popular it becomes, the more valuable it will become.”

    “When you go to The Louvre and take a picture of the Mona Lisa and share it on the internet no one is like ‘Wow, I just devalued the Mona Lisa.’”

    However, he does believe NFTs serve a purpose and that an eventual bubble burst will simply remove the deadweight, much like how the dotcom bubble did not cripple the internet’s functionality and its now ubiquitous influence on the world.

    Money-Spinning Endeavours

    Jack Dorsey, the former CEO of Twitter, sold his first ever tweet on the platform as an NFT for just over 1,630 ETH or US$2.9 million to Malaysian businessman Sina Estavi, the CEO of Bridge Oracle. Famous memes have also been put up for sale for life-changing amounts, with originators eager to strike while the iron is hot.

    The trend is already being jumped on by local artists as well. Graffiti artist Abdul Hafiz Abdul Rahman, better known as Katun, sold two NFT collections in August 2021, titled Apes Stand Strong, with a limit of 50 pieces (1 ETH each) and Mystical Fruits, an open edition that sold 776 pieces at 0.1 ETH each. This raised a total of 127.6 ETH (over RM1.6 million at the time, now worth over RM2.1 million at the time of writing).

    Another well-known local artist, Red Hong Yi, sold her Doge to the Moon NFT for 36.3 ETH (approx. RM325,000 at the time, now worth RM620,000 at the time of writing) in July 2021, while local rapper Namewee made 209 ETH (approx. RM3.5 million) from selling 100 NFTs of his song Go NFT in November.

    Many buyers of NFTs also immediately list it at a higher price in a bid to make a quick profit. Whether these prove to be prudent investments or not, it is clear that there is a demand for NFTs, either for speculative purposes or as stores of wealth.

    What is less certain though is whether NFTs are a bubble or if it will ever become a popular method of investment. Whatever happens, digital natives are making moves and it is up to the rest of the world to get up to speed or possibly be left behind.

    NFTs In Numbers To Date

    • Number of NFTs sold: 19,390,873
    • Total sales of NFTs: US$13.95 billion
    • Average value per sale: US$719.77
    • Primary sales: 11,244,153
    • Secondary sales: 8,146,720
    • Active market wallets: 1,510,331
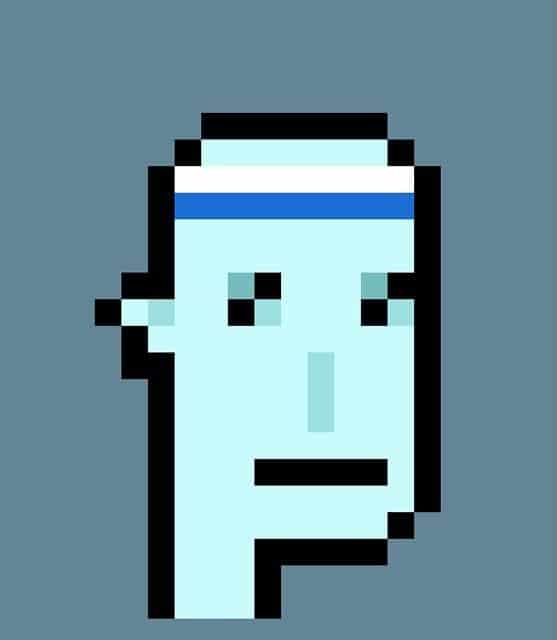
    • Most popular project (volume): CryptoPunks – US$1.8 billion
    • Most expensive NFT sold (ETH): CryptoPunks (Ͼ #3100) – 4,200 ETH
    • Most expensive NFT sold (US$): EVERYDAYS: THE FIRST 5000 DAYSBeeple (aka Mike Winkelmann)US$69,346,250

    Statistics are accurate as of December 2021.

  • Higher Minimum Wages Causes Unemployment And Steep Inflation? Not Necessarily

    Higher Minimum Wages Causes Unemployment And Steep Inflation? Not Necessarily

    The Malaysian experience seems to suggest that raising the minimum wage has been good for us.

    The need to implement minimum wages is based on the protection it offers to workers at the lowest income strata. These often tend to be workers from groups often marginalised in society such as youth workers and women. They may not have the bargaining power to demand higher wages without direct government intervention.

    For several decades there was a near-consensus among economists that raising minimum wages just like any other floor would substantially reduce employment. Some persist on the potential employment costs argument. However, that view has changed where a majority now view a significant rise to be a good idea.

    To understand the shift, it is important to appreciate the natural experiments conducted by Nobel Laurette David Card, who found that increasing minimum wages did not lead to increased unemployment[1]. In fact, it was found to lift many out of poverty and benefit those in the bottom half, including those making more than the minimum wage[2].

    There are those who view the implementation of a higher minimum wage as harming low-wage workers as it is an artificial value imposed by the government rather than determined via market forces. This is because those with lower skills or experience tend to have lower productivity levels. Hence, a higher cost structure would put-off hiring of these workers rather than employing them at lower wages until they become more experienced.

    However, my opinion is that the wage policy in Malaysia should be based on the domestic context. In 2013, the minimum wage was first set to be at RM 900 per month for West Malaysia and RM 800 for East Malaysia. The rate has since gone up in stages over the years. About a decade later, it is set to reach RM 1,500 per month effective 1st May 2022.

    This seems to be a fair rate given that the International Labour Organisation reported that the average minimum wage around the world for developing and emerging nations to be about 67% of the median wage[3].  At the end of 2019 before the pandemic, according to the Department of Statistics Malaysia (DOSM), the median income in Malaysia was at RM 2,442 where the minimum wage was set at RM 1,200 (about 49%). However, according to data from DOSM, the pandemic has lowered the median income to RM 2,206, a minimum wage of RM 1,500 represents about 68% which is in-line with the global average. Given that the economy is expected to see a strong rebound of more than 5.5% in 2022, the median wage can be expected to surpass 2019 levels by 2024. This would eventually represent a minimum wage representing 60% of the median wage.

    Research on the implementation of previous minimum wage levels in Malaysia shows that it tends to increase labour productivity, act as a motivator, and reduce employee turnover[4]. In fact, longer terms studies have shown that it reduces unemployment and increases labour participation rates[5]. Research also documents that the previous increase in 2016 also did not result in any significant reduction in labour demand[6].

    There have been views that increase of minimum wages may lead to inflationary pressures. For example, if a restaurant owner is suddenly forced to pay his workers RM 1,500 instead of RM 1,200, he needs to raise the price of his product to account for this increase in costs.

    malaysia people holding flag celebrating independence day together

    But in the Malaysian context, it is likely that most employees in urban areas are already being paid close to the proposed rate of RM 1,500. Thus, there might be very little additional price pressure in these areas.  It is likely that the new rate would account for the difference in wages and costs in urban versus rural areas, in-line with the current approach.

    In addition, inflation tends to be insignificant as a determinant of employment in Malaysia[7]. In fact, research in Malaysia shows that labour markets in Malaysia tend to follow the efficiency-wage theory where the increase of costs (of higher wages) would be recouped through greater productivity as well as increased employee retention[8]. Thus, inflationary pressures are unlikely to be severe, given that increased productivity would then counter the potential increase in price levels. Thus, it seems that the new higher rate may point towards a positive picture overall.

    However, given the potential that it may harm SMEs which are unable to offer higher wages, there is a need to explore a mechanism beyond minimum wages going forward. Imposing minimum wage laws puts the role of reducing poverty on the business owner. But a different approach via social welfare programmes for low-wage workers would allow all taxpayers to share the financial burden.  Among areas that would be beneficial to B40 households would include part cover for housing costs, healthcare as well as childcare costs.

    About the Author

     Professor Dr Hafezali bin Iqbal Hussain is the Head of Research at the Faculty of Business and Law, Taylor’s University and a member of the Centre for Industrial Revolution and Innovation (CIR4I). Taylor’s Business School is the leading private business school in Malaysia for Business and Management Studies based on the QS World University Rankings by Subject 2021 edition.


    [1] Microsoft Word – aea3.docx (nber.org)

    [2] Minimum Wages and the Distribution of Family Incomes – American Economic Association (aeaweb.org)

    [3] Global Wage Report, 2020-21.

    [4] Minimum Wage Policy: Is There Any Impact on Low Skilled Workers in Electrical and Electronics Companies in Malaysia? | International Journal of Business and Society (unimas.my)

    [5] http://myscholar.umk.edu.my/bitstream/123456789/2586/2/ICBT2020_039_MW.pdf

    [6] Minimum Wages: Helping or Hurting Producers? | SpringerLink

    [7] ICBT2020_039_MW.pdf (umk.edu.my)

    [8] The effect of real wages and inflation on labour productivity in Malaysia: International Review of Applied Economics: Vol 28, No 3 (tandfonline.com)

  • What Protection Does A High-Net-Worth Individual Needs?

    What Protection Does A High-Net-Worth Individual Needs?

    Insurance plans for high-net worth individuals are often beyond what is available to the everyday man.

    For many Malaysians, the importance of insurance is drilled into their minds early on in their lives or careers, and it is likely that most have a friend or relative that is an insurance agent. However, in terms of pure numbers, insurance penetration in the country is still low.

    A survey commissioned by Zurich Malaysia last year showed that 38% of Malaysians remain uninsured; another survey conducted by the Health Ministry in 2020 found that only 22% of Malaysians had personal health insurance.

    According to Dennis Chin, director at Harveston Wealth Management, life insurance needs usually start with self-protection such as medical cost and critical illnesses, which is then followed by financial security for family such as family income protection and credit protection.

    And while it may be the norm to be uninsured, for high-net-worth individuals (HNWI), this is likely to border on sacrilege!

    “For HNWI, the abovementioned is essential as well even though they have more financial resources to take care of the medical bills and family income need,” says Chin.

    He adds that the typical insurance planning for such individuals goes beyond personal risk as there are often other assets and collateral that may be used as guarantors in business borrowings, for example if a key person in the business suddenly leaves.

    “These borrowings will risk their personal assets being used for paying off in the event of sudden departure of the key person in the business or guarantor for the loan.”

    Protection For HNWI

    The main difference when it comes to insurance coverage for HNWI usually comes down to two things – the required sum assured and the type of risk.

    If the person requires RM10 million in life coverage, insurance plans can come in the form of offshore universal life policies denominated in US dollars while also being more cost efficient. Such offshore policies are not accessible to lower/middle income individuals as the minimum sum assured is usually beyond reach, often starting at US$500,000 and above.

    dennis chin harveston hnwi“This type of plan may offer different health and financial underwriting requirements which are offered differently by insurance companies locally,” says Chin.

    He shares that “asset protection is also essential” for HNWI as they tend to own wide varieties and classes of assets. Typically, such assets would include real estate, jewellery, or art collections to name just three. Often, these may also make up the bulk of their net worth.

    For example, a standard house insurance will not hack it when it comes to covering a bungalow that is constructed with exotic woods and expensive, custom-made furniture and fittings. Special coverage will be required for such a home in the event of fire or burglary explains Chin.

    “Therefore, the scope of insurance needs for HNWI is much wider than lower- and middle-income individuals,” he adds.

    Healthcare is another area in which HNWI are usually well-covered in. For those that travel regularly around the world, international medical coverage is key in order to counter the risk of being forced to seek medical services in a foreign country.

    “This type of medical plan comes with high medical limit in US dollars and the premium is also payable in US dollars as well,” he shares.

    “It also provides peace of mind while travelling globally as usually it comes with services on international consultation for medical services and evacuation back to their home country.”

    For The Next Generation

    HNWI with highly sought-after professional skills may also choose to take “future economic value” into consideration when setting up their life coverage. For example, in the event that a person is no longer able to work through total or permanent disability, or death, this will ensure that his or her projected earnings over a set number of years will be paid out to the family.

    There are notable examples of celebrities doing this, such as footballer Cristiano Ronaldo getting insured for £90 million in 2009, while singer Taylor Swift reportedly insured her legs for US$40 million in 2015.

    Chin explains that utilising insurance as a tool for wealth management is not a foreign concept to HNWI, with family trusts and family offices usually set up for wealth preservation for the benefit of the next generation and even beyond.

    Insurance For Wealth Creation

    Once the basic protection needs covering medical costs or critical illnesses are in place to ensure future financial security for HNWI, “a large sum assured is usually a tool in wealth management for wealth creation” Chin says.

    Alvin Yap, managing director at A.D. Financial, adds, “For family offices, insurance is also treated as a tool for estate planning, risk diversification and even wealth creation.”

    He gives an example on how a patriarch owning several offshore real properties may purchase life insurance with proceeds to cover any tax liabilities (e.g. inheritance tax, etc.) upon his demise, ensuring that the offshore real properties will be transferred to his family office smoothly after his passing.

    Using another example, he says, “Let us assume a matriarch purchases life insurance and makes it a point that the family office will manage and invest the insurance proceeds which will be treated as an education fund for many generations to come. She bequeaths her personal wealth to her children and her family office manages the insurance proceeds (education fund) upon her demise.”

    The mechanics of a family trust makes it useful for liquidity purposes as “insurance proceeds will be paid directly to the family trust”, providing an immediate source of cash flow to beneficiaries of the trust as opposed to individual nominees.

    “This is because in the event the nominee does not survive as well, the insurance paid out will fall into estate which can only be used after obtaining grant of probate,” highlights Chin.

    This can also help to prevent any squabbles among beneficiaries when the head of the family passes on. It is not uncommon to hear of huge lawsuits which entail siblings and other family members fighting in court to claim their piece of the pie. Hence, in most families, there will be a need for such a structure to be in place.

    To illustrate this point, Chin uses a scenario where there are multiple properties to be passed down to several beneficiaries.

    “What if these properties are not identical and each of them carries a different value? This might create some issues about fairness whereby the value of inheritance of each beneficiary is not the same,” he says.

    “In this case, a method of wealth equalisation can be adopted by buying life insurance that eventually creates the cash to compensate those beneficiaries that inherited lower value properties.”

    Charitable Endeavours

    Apart from taking care of their families, many HNWIs also engage in the practice of philanthropy through monetary gifts or donations to those in need, utilising the mechanics of life insurance to achieve this purpose.

    “Apart from donating existing resources and funds, such as allocating a pre-determined amount of profit from businesses, one can plan by using life insurance proceeds to make charitable donations,” explains Chin.

    “There are many family offices which have a foundation in place for philanthropy purposes, consisting of existing assets and cash, as well as life insurance.”

    “By paying premiums from existing resources every year, this eventually increases the assets in the 

    foundation by claiming the sum assured for charity purposes which can help more people,” he adds.

    What Are Family Offices?

    HNWI often have a family office to manage their financial affairs, but not much is known to the general public. We speak to Alvin Yap, managing director at A.D. Financial, to learn more.

    alvin yap a.d. financial hnwi

    Smart Investor: Can you describe how the various structures of family offices work?
    Alvin Yap: Family office is originally from the concept of preserving generational family wealth for European royalty and it is increasingly popular among high and ultra-high net worth Asian families. However, there is still much puzzlement as to what defines them and their primary functions.

    Briefly, a family office is about effectively preserving, growing and transferring wealth across generations. It can be treated as a legal entity that houses professionals in various areas such as administration, legal, investment, corporate finance, real estates and so forth to achieve the abovementioned primary functions. Some family offices are more investment oriented; others could be driven by philanthropic causes. In terms of establishments, there is single-family office servicing one individual family and also, multi-family office that service several families benefiting from economies of scale.

    SI: Can you explain the role that insurance plays in family offices as a form of generational wealth management or preservation?
    AY: Primarily, insurance is used to mitigate financial damages caused by loss of life or properties. For family offices, insurance is also treated as a tool for estate planning, risk diversification and even wealth creation.

    SI: How do you determine the type and amount of insurance coverage that different family offices require?
    AY: It can be complex but it all boils down to family business needs and family lifestyle.

    In Malaysia, term life insurance can be purchased as keyman insurance, meaning insuring the key person such as the owner or someone who is critical to the business; some family offices will source for offshore term life insurance that comes with a lower premium. There is also a variety of universal life insurance that offer very low initial cash outlay for insurance premium or options to fund the premium with movable/ immovable assets and many other flexible premium financing features. Family offices take advantage of these features and purchase universal life with very high insurance coverage.

  • Insurance Affordability vs Need, 6 Factors You Should Consider

    Insurance Affordability vs Need, 6 Factors You Should Consider

    How can you determine your insurance requirements for better financial risk management?

    We often encounter young members of the workforce looking to embark on their financial planning journey with a simple life insurance coverage. This move should be lauded as it makes a lot of sense to play defense before offense, so to speak. To kick start the conversation, the question of affordability will inadvertently crop up – how much can you afford to pay? While this is a practical approach for young career starters, is there a more optimal way to determine your insurance needs for better financial risk management?

    Before sharing some thoughts on risk mitigation needs that should be addressed by leveraging on insurance tools, perhaps it is best that I briefly touch on the types of life insurance coverage that individuals can consider.

    The most basic is to address concerns in the event of death. The idea is that should financial dependents and family members face a premature or untimely departure of a main breadwinner, there will be a financial payout to help the next of kin recover from this setback by ensuring that living expenses and financial commitments can continue to be met with minimal disruptions for an extended period thereafter.

    Related to this is the need to provide financial relief if the breadwinner is still alive but no longer able to generate income due to a total and permanent disability (TPD).

    In this scenario, funding is required to replace the revenue of the income earner while also considering any additional living expenses that can arise due to the disability.

    The third area is for critical illness (CI) needs where a lump sum is paid to the insured if there is a diagnosis of a covered serious illness. This payment can be used to fund non-hospitalisation related medical expenses as well as rising living expenses to aid a faster recovery.

    It is no secret that medical inflation is rising rapidly. The escalating medical costs and the fact that life expectancy is prolonging means that it is more important now than ever to have our own hospitalisation & surgical (H&S) coverage (also known as medical card). Lastly, we are also exposed to the risk of all forms of accidents that might partially incapacitate us for a short period or permanently. Personal accident (PA) coverage provides payment for accidental related risks.

    Having an appreciation of these five types of coverage will enable us to address our personal risk management need through insurance planning more comprehensively. However, as alluded to earlier, trying to address these areas based on affordability alone might give one a false sense of having effective risk mitigation in place.

    So how then should one go about calculating the more accurate amount of insurance coverage for the respective funding needs?

    1. Family Income

    Family income refers to the amount of money required to provide sufficient levels of funds to surviving financial dependents, so long as they remain financially reliant on the breadwinner. This will need to cover expenses such as living expenses for the whole family including dependent parents (ideally until the youngest child reaches the age of 25 and for nonworking spouse for their remaining life expectancy), education fees and related costs for minor children up till tertiary education and insurance premiums for family members.

    It can include funeral expenses and estate administration costs of the deceased also. The sum of these costs will give you a more precise indication of the amount required for death insurance coverage.

    2. Income Replacement

    This refers to the need for funding if one is no longer able to work due to TPD and is calculated based on how much expenses are incurred in a year for normal living expenses. In the ideal scenario, the calculation should be from now till one’s life expectancy. However, this could be a tall order for most people, particularly young employees, as such a simple guideline is that TPD coverage should amount to at least five years of income or until one’s retirement age (assuming that one is able to fund retirement expenses separately).

    3. Debt Cancellation

    For those who have outstanding loans, especially a mortgage on the family home, or any other loans, this may reduce the amount of money the family will receive and should be considered. Some clients will expect investment properties to be sold while others would prefer to transfer the assets to their loved ones free from encumbrance.

    As such, depending on your wishes, you should consider the loan cancellation needs to ensure that your estate has sufficient funds to pay off these loans as well as providing the required funding for the family. You have the option to self-insure (if there are sufficient assets to settle the loan) or transfer that risk to the insurance company. The sum assured needed can be provided for utilising potentially cheaper products such as a term insurance policy over the outstanding loan period.

    4. Critical Illness

    If you are diagnosed with CI, you may need to stop work temporarily to undergo the necessary treatment and take a break to have a successful recovery. If you need to cover your living expenses during the recovery period due to concerns over non-covered medical expenses or higher cost of living, then CI funding will help to defray these expenses. To ensure that you are not over-paying in premiums for this need, you can use the rule of thumb to providea sum assured of between 3-5 years of your current annual income.

    5. Medical Expenses

    As mentioned earlier, medical costs particularly for private hospitalisation needs is rising. While one can depend on public hospitals for treatment, it is better to have alternatives via the private medical route. We do have some clients who work with multinational companies providing comprehensive medical card coverage and question the need for their own medical card.

    However, our advice is always to obtain your own medical card early so that the premiums are lower while you are in better health. Purchasing one only upon retirement may make you ineligible (due to pre-existing medical conditions) or having to pay a hefty premium due to your age or loading due to medical factors. Ideally one should have a medical card providing a room and board of at least RM200 with an annual medical limit of minimum RM1 million and no lifetime limit.

    6. Personal Accident

    Lastly, one should also have coverage for the risk of accidental injury, TPD or accidental death which may not be covered by the above policies. It does not help that the statistics do not favour the young – a higher percentage of youths meet with accidents resulting in the inability to carry on employment, permanent disablement or even death.

    One should not only rely on payment from SOCSO for accidental claims as there are terms and conditions to be met. Often forgotten (as they are rarely sold due to low premium costs), PA policies are generally very cost effective especially with the attractive renewal bonus offered. Similarly, you can use the guideline of providing a sum assured of between 3-5 years of your current annual income for this need as well.

    In summary, the path to having the right insurance coverage is indeed a balancing act of sorts. Too much, and you might make it more daunting to save and invest to achieve your desired financial goals. If you are underinsured, then you or your dependents might be in a financial quandary. So good on you for getting the ball rolling by purchasing insurance policies based on what you can currently afford as a
    fresh member of the workforce, but do recognise that you will need to review your needs over time to ensure that you have an effective financial risk management plan in place.

    About the author

    Felix Neoh CFP CERT TM is the director of financial planning at Finwealth Management Sdn Bhd and can be contacted at enquiry@finwealth.com.my.

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth