Author: Media OutReach Newswire

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    Margin recovery and record earnings underscore the Jollibee Group’s growth momentum, as Jollibee Canada prepares to nearly double its network over five years

    Key Highlights:

    • Record quarterly earnings: Net income attributable to equity holders of the parent company rose 5.7% year over year to Php3.4 billion, or approximately US$55 million, marking the Jollibee Group’s highest quarterly NIAT on record, supported by margin recovery from first-quarter cost pressures and improved operating leverage.
    • Sustained global sales growth: System-wide sales increased 14.2% year over year, driven by continued demand across the Group’s Philippine and international businesses and growth across its global brand portfolio.
    • Strong North American performance: Jollibee North America system-wide sales grew 21.6%, while same-store sales increased 8.6%; Smashburger same-store sales grew 7.0%, underscoring momentum in one of the Group’s key international growth markets.
    • Canada expansion strengthens the North America growth platform: New plans add 26 locations in British Columbia and Edmonton to Jollibee’s existing 28-restaurant Canadian network, positioning the brand to nearly double its Canada footprint over the next five years.
    • Expanding global store network: The Jollibee Group’s store network increased 6.4% year over year to 10,767 stores across 33 countries, with franchised stores accounting for approximately 70% of gross new openings.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, the resilience of its global brand portfolio, continued healthy consumer demand, and positive system-wide sales growth across all regions.

    The Jollibee Group’s system-wide sales increased 14.2% year-on-year, driven by continued demand across its Philippine and international businesses and growth across its global brand portfolio. The Group recorded Php3.4 billion in net income attributable to equity holders of the parent company, its highest quarterly NIAT on record.

    North America continued to deliver strong performance during the quarter. Jollibee’s system-wide sales increased 21.6%, while same-store sales grew 8.6%. Smashburger also delivered 7.0% same-store sales growth, reflecting continued momentum across the Group’s North American portfolio.

    Canada is emerging as an important growth market for Jollibee, with planned expansion in British Columbia and Edmonton set to strengthen the brand’s national footprint. Together, these plans would add 26 restaurants — 16 in British Columbia and 10 in Edmonton — to Jollibee’s existing network of 28 restaurants in Canada.

    If completed as planned, these commitments would nearly double Jollibee’s Canadian network over the next five years, while laying the foundation for further expansion across the country.

    The Jollibee Group’s global store network increased 6.4% year-on-year to 10,767 stores across 33 countries,. Of these, 501 stores were across North America at the end of the second quarter, spanning Jollibee, Chowking, Red Ribbon, Smashburger, Milksha, The Coffee Bean & Tea Leaf, and Tim Ho Wan.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    North America continued to deliver strong performance during the quarter. Jollibee’s North American system-wide sales increased 21.6%, while same-store sales grew 8.6%. Smashburger also delivered 7.0% same-store sales growth, reflecting continued momentum across the Group’s North American portfolio.

    The International segment expanded by 25.4% in system-wide sales, led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee NA grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    Full Year 2026 Guidance

    For full year 2026, the Jollibee Group expects its underlying sales momentum to remain resilient. It is maintaining its guidance for system-wide sales growth of 8%-12% and store network growth of 5%-10%, supported by continued demand across key markets and disciplined execution across its global brand portfolio.

    At the same time, the Jollibee Group is updating certain operating assumptions. Full year same-store sales growth guidance is being revised to 3%-4%, while the gross new store opening target is being updated to 1,000-1,100 stores. Despite the lower gross opening target, the Jollibee Group continues to expect overall store network growth to remain in line with its previous guidance, reflecting ongoing portfolio optimization and the timing of store openings and closures.

    Capital expenditures are now expected to be in the range of Php13.0 billion (approx. US$212 million) to Php15.0 billion (approx. US$244 million). Operating income growth guidance is revised to 10%-15%, reflecting the updated same-store sales assumptions, the revised expansion assumptions, continued transition-related costs for China and Smashburger, and the still-dynamic cost environment.

    The Jollibee Group’s confidence is supported by growth catalysts that provide a stronger foundation for sustained performance over the medium term, including continued international expansion, a growing base in key markets such as North America, and ongoing portfolio optimization initiatives. Recent developments in Canada, Vietnam, and China illustrate the Group’s ability to pursue high-quality growth across markets with different growth profiles and strategic priorities.

    Jollibee Vietnam has emerged as one of the Jollibee Group’s strongest international growth engines, leading the category in sales and ranked as the No. 1 quick-service restaurant brand in Vietnam by Euromonitor International in its Consumer Foodservice 2026 study. In Q2 2026, Jollibee achieved system-wide sales growth of 47.6% and same-store sales growth of 17.9%, supported by disciplined execution and continued network expansion, with 19 new stores opened in the first half of the year. Attractive unit economics, with store payback of less than four years, reinforce confidence in the sustainability of future growth. Its strong market position, operating performance, and customer engagement were further recognized through awards for Best Companies to Work for in Asia 2026 and Best Social & Commerce Integration in Vietnam.

    In China, the franchise ratio has increased significantly to 62% today from 14% in 2016, reflecting continued progress toward a more scalable and asset-light operating model. Its largest brand, Yonghe King, has achieved a franchise ratio of 65% and is targeting 70% by the end of 2026, with a medium-term target of up to 95%. Yonghe King’s new stores typically achieve payback in approximately two years.

    The Jollibee Group remains focused on pursuing high-quality growth opportunities that generate attractive returns on invested capital, with disciplined capital allocation and capital-light expansion continuing to guide its growth strategy.

    Other Developments

    Recognition for Global Brand Influence

    The Jollibee Group was named to TIME’s 100 Most Influential Companies of 2026, where it was recognized as a “fried chicken phenom.” The Company was also included in the inaugural TIME100 Companies: Industry Leaders list as one of the Top 10 companies in the Food & Drink category.

    In July, the Jollibee Group was included in Fortune’s Southeast Asia 500 list, reinforcing its position among the region’s leading companies. Jollibee was also recognized by USA Today as having the Best Fast Food Fried Chicken, further strengthening the brand’s global consumer relevance and reinforcing its leadership in great-tasting food.

    Sustainability and ESG Progress
    The Jollibee Group continued to advance its sustainability agenda and strengthen its ESG initiatives. For the second consecutive year, the Company received the 3G Excellence in Sustainability Reporting Award 2026, recognizing its commitment to transparent and meaningful sustainability disclosures.

    The Company’s Danao commissary was also awarded LEED Gold certification under LEED v4.1 ID+C: Commercial Interiors, becoming the first manufacturing facility in the Philippines to achieve LEED certification for interior design and construction. The recognition reflects the Jollibee Group’s ongoing investment in more sustainable and future-ready operations.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.

    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with affiliates and franchisees operating over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.

    To learn more about Jollibee Group, visit

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Group’s record quarter reflects margin recovery and strong international growth, including 23.0% global system-wide sales growth from Hong Kong-founded Tim Ho Wan.

    Key Highlights:

    • Record quarterly earnings: NIAT increased 5.7% year-on-year to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record.
    • International business accelerates: International system-wide sales increased 25.4%, reflecting broad-based growth across the Group’s global portfolio.
    • Hong Kong-founded Tim Ho Wan sustains global momentum: Tim Ho Wan delivered 23.0% system-wide sales growth globally in Q2, underscoring the continued international relevance of the brand.
    • Expanding global platform: The Jollibee Group’s store network increased 6.4% year-on-year to 10,767 stores across 33 countries, with international stores accounting for the majority of the network.
    • Positive performance across key markets: Same-store sales growth remained positive in several international markets, including North America, Vietnam, and Korea.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, the resilience of its global brand portfolio, continued healthy consumer demand, and positive system-wide sales growth across all regions.

    In Hong Kong, Jollibee continued to expand its presence with 24 stores at the end of the second quarter, while system-wide sales grew 36.6% year-on-year. This formed part of the broader momentum across the Jollibee Group’s international portfolio, which grew 25.4% in system-wide sales during the quarter.

    Among the Group’s international brands, Tim Ho Wan delivered 23.0% system-wide sales growth globally in Q2, underscoring continued momentum for the Hong Kong-founded brand as it expands its international footprint. The brand had 83 stores globally at the end of the second quarter, contributing to the Jollibee Group’s growing international restaurant network.

    The brand’s performance formed part of broader growth across the Group’s International segment, which expanded 25.4% in system-wide sales during the quarter. The segment was led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee North America (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the international business’ system-wide sales (“SWS”).

    The Group’s Philippine business also continued to contribute to overall growth, with system-wide sales increasing 5.7%, supported by Mang Inasal (+10.7%) and Jollibee (+6.6%).

    The Jollibee Group recorded Php3.4 billion (approx. US$55 million) in net income attributable to equity holders of the parent company (NIAT), up 5.7% year-on-year and the highest quarterly NIAT on record. Consolidated revenues increased 10.7% year-on-year, while system-wide sales grew 14.2%.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Global Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    The International segment expanded by 25.4% in system-wide sales, led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.
    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.

    To learn more about Jollibee Group, visit

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    Strong international sales momentum, disciplined pricing, and margin recovery helped drive the Jollibee Group’s record-high quarterly earnings.

    Key Highlights:

    • Record enterprise performance: Jollibee Group delivered record quarterly NIAT of Php3.4 billion, up 5.7% year-on-year, with consolidated revenues rising 10.7% and system-wide sales increasing 14.2%, supported by improving margins and continued business momentum.
    • International business drives growth: International system-wide sales grew 25.4%, reflecting broad-based momentum across the Group’s Asian and global restaurant portfolio, including Highlands Coffee, Compose Coffee, Tim Ho Wan, Jollibee North America, and Milksha.
    • Asia remains a key growth platform: Strong same-store sales growth in Vietnam, Highlands Coffee, and Compose Coffee highlights the continued strength of the Group’s core Asian growth markets.
    • Vietnam emerges as a major growth engine: Jollibee Vietnam delivered 47.6% system-wide sales growth in Q2 and opened 19 new stores in the first half, supported by strong unit economics and continued network expansion.
    • Global footprint continues to expand: The Jollibee Group increased its store network by 6.4% year-on-year to 10,767 stores across 33 countries, with franchised stores comprising approximately 70% of the network.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, resilient consumer demand, and continued momentum across its international restaurant portfolio.

    The Jollibee Group’s International segment grew 25.4% in system-wide sales in Q2, led by strong performances from Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%).

    Growth across key Asian markets was particularly notable. Jollibee Vietnam delivered 17.9% same-store sales growth, while Highlands Coffee grew 11.5% and Compose Coffee grew 12.4%, contributing to the broader momentum of the Group’s International segment.

    The Group’s Philippine business also continued to provide a strong foundation for overall performance, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    The Jollibee Group recorded Php3.4 billion (approx. US$55 million) in net income attributable to equity holders of the parent company (NIAT), up 5.7% year-on-year and the highest quarterly NIAT on record. Consolidated revenues increased 10.7% year-on-year, while system-wide sales grew 14.2%.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Global Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    The International segment expanded by 25.4% in system-wide sales, reflecting broad-based growth across the Jollibee Group’s international portfolio. Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    Asian markets continued to deliver strong performance during the quarter. Jollibee Vietnam grew 17.9% in same-store sales, while Highlands Coffee grew 11.5% and Compose Coffee grew 12.4%. These results contributed to the broader momentum of the Group’s International segment.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    Full Year 2026 Guidance

    The Jollibee Group’s confidence is supported by growth catalysts that provide a stronger foundation for sustained performance over the medium term, including continued international expansion, a growing base of committed franchisees in key markets such as North America, and ongoing portfolio optimization initiatives. Recent developments in Vietnam and China illustrate the Group’s ability to pursue high-quality growth across markets with different growth profiles and strategic priorities.

    Jollibee Vietnam has emerged as one of the Jollibee Group’s strongest international growth engines, leading the category in sales and ranked as the No. 1 quick-service restaurant brand in Vietnam by Euromonitor International in its Consumer Foodservice 2026 study. In Q2 2026, Jollibee achieved 47.6% system-wide sales growth and 17.9% same-store sales growth, supported by disciplined execution and continued network expansion, with 19 new stores opened in the first half of the year. Attractive unit economics, with store payback of less than four years, reinforce confidence in the sustainability of future growth.

    In North America, Jollibee recently signed its first multi-unit development agreement in British Columbia, following a 10-store development agreement for the Edmonton market. Together, these agreements add 26 committed franchise locations to Jollibee’s existing Canadian network and are expected to nearly double the brand’s Canadian footprint over the next five years if completed as planned. The developments also provide a foundation for further expansion across the country.

    In China, Jollibee Group’s franchise ratio, comprising Yonghe King, Hong Zhuang Yuan, Jollibee Hong Kong, and Jollibee Macau, has increased significantly to 62% today from 14% in 2016, reflecting continued progress toward a more scalable and asset-light operating model. Its largest brand, Yonghe King, has achieved a franchise ratio of 65% and is targeting 70% by the end of 2026, with a medium-term target of up to 95%. Yonghe King’s new stores typically achieve payback in approximately two years.

    The Jollibee Group remains focused on pursuing high-quality growth opportunities that generate attractive returns on invested capital, with disciplined capital allocation and capital-light expansion continuing to guide its growth strategy.

    Other Developments

    Recognition for Global Brand Influence

    The Jollibee Group was named to TIME’s 100 Most Influential Companies of 2026, where it was recognized as a “fried chicken phenom.” The Company was also included in the inaugural TIME100 Companies: Industry Leaders list as one of the Top 10 companies in the Food & Drink category.

    In July, the Jollibee Group was included in Fortune’s Southeast Asia 500 list, reinforcing its position among the region’s leading companies. Jollibee was also recognized by USA Today as having the Best Fast Food Fried Chicken, further strengthening the brand’s global consumer relevance and reinforcing its leadership in great-tasting food.

    Sustainability and ESG Progress

    The Jollibee Group continued to advance its sustainability agenda and strengthen its ESG initiatives. For the second consecutive year, the Company received the 3G Excellence in Sustainability Reporting Award 2026, recognizing its commitment to transparent and meaningful sustainability disclosures.

    The Company’s Danao commissary was also awarded LEED Gold certification under LEED v4.1 ID+C: Commercial Interiors, becoming the first manufacturing facility in the Philippines to achieve LEED certification for interior design and construction. The recognition reflects the Jollibee Group’s ongoing investment in more sustainable and future-ready operations.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.

    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.

    To learn more about Jollibee Group, visit

  • Ping An Digital Bank Celebrates 6th Anniversary with Exclusive 3 Hong Kong and 3SUPREME Collaboration

    Ping An Digital Bank Celebrates 6th Anniversary with Exclusive 3 Hong Kong and 3SUPREME Collaboration

    Unveils Cross-Sector Rewards with Up to HK$2,600 Early Bird Savings on Designated Handset

    HONG KONG SAR – Media OutReach Newswire – 8 September 2026 – Ping An Digital Bank (International) Limited (“Ping An Digital Bank”) marks its 6th anniversary through a cross-sector collaboration alongside 3 Hong Kong and 3SUPREME, mobile brands of Hutchison Telecommunications (Hong Kong) Limited (“HTHK”). The joint initiative debuts an exclusive dual promotion designed to elevate customers’ smart digital financial and mobile communications experiences, adding further excitement to Ping An Digital Bank’s suite of 6th-anniversary celebrations!

    Mr. Ronald Iu, Chief Executive of Ping An Digital Bank, said, “As Ping An Digital Bank celebrates its 6th anniversary, our retail banking segment continues to experience rapid growth, a testament to the long-standing trust and support of our customers. On this special occasion, we remain dedicated to thinking ahead and going the extra mile for our customers. Collaborating with 3 Hong Kong and 3SUPREME allows us to combine the strengths of both parties, empowering customers to upgrade to the latest digital products while enjoying seamless and high-quality retail banking services.”

    New Handset Rewards: HK$400 Upon Account Opening, Mobile Plan Subscription and Handset Purchase Up to HK$2,600 in Early Bird Savings

    From now until 30 November 2026, eligible customers1 who successfully open a Ping An Digital Bank personal savings account using the designated promotion code [3HKPA] will receive a HK$400 cash rebate2 from Ping An Digital Bank.

    To reward first movers, an exclusive early bird offer is available from now until 17 September 2026. Eligible customers1 will enjoy a waiver of the HK$500 prepayment amount3 from 3 Hong Kong and 3SUPREME, alongside handset discounts of up to HK$2,2003. Combined with the HK$400 cash rebate2 from Ping An Digital Bank, customers can unlock total savings of up to HK$2,600.

    Deposit Rewards: Enjoy 16% p.a. 1-Month HKD Time Deposit Interest Rate

    Additionally, new Ping An Digital Bank customers4 who open a Ping An Digital Bank personal savings account on or before 30 September 2026, and successfully place a 1-month HKD time deposit can enjoy an attractive annual interest rate of 16%5,6 on their first HK$100,000 deposit. This enables customers to effortlessly lock in privileged high-yield returns while upgrading to the new handset.

    Looking ahead, Ping An Digital Bank will continue to uphold its vision of “Always with You, Always Ahead.” Dedicated to thinking ahead and going the extra mile, the Bank will actively explore cross-industry synergies and continuously enhance its diversified suite of financial products and services to deliver superior digital financial experiences for customers.

    1 Eligible Customers refer to customers who have never held any account with Ping An Digital Bank, successfully open a savings account with promotion code “3HKPA” during the Promotion Period, subscribe to, renew or upgrade to a designated 3 Hong Kong / 3SUPREME service plan with a minimum contract period of 24 months and hold a valid Hong Kong Identity Card or Exit-Entry Permit for Travelling to and from Hong Kong and Macau at the time of such subscription, renewal or upgrade during the Promotion Period (from 7 September 2026 to 30 November 2026) , and successfully purchase a designated handset on or before 31 March 2027.

    2 HK$ 400 cash rebate is available only to Eligible Customers who satisfy all relevant requirements. Each Eligible Customer can enjoy the HK$ 400 Cash Rebate and other offers once only. The Cash Rebate and other offers are non-transferable and cannot be exchanged for cash or other gifts. Cash Rebate will be credited to the savings account of eligible customer on or before 31 May 2027.

    3 The waiver of HK$ 500 prepayment amount, up to HK$2,200 discount upon purchase of a designated 3HK handset model, designated service plans, designated handset models, and other designated 3HK offers are provided and managed by 3 Hong Kong / 3SUPREME, and are subject to relevant terms and conditions.

    4 New Ping An Digital Bank customers refer to customers who have never held any account with the Bank and successfully open a savings account during the 1 September 2026 to 30 September 2026 using a promotion code obtained through any channels.

    5 The 16% p.a. HK$ Time Deposit rate offer will be displayed on the Time Deposit page in the Ping An Digital Bank’s personal mobile banking app within 3 working days (excluding Saturdays, Sundays and public holidays) after successful account opening.

    6 HKD Time Deposit interest rate is calculated daily on the basis of a 365-day year and is subject to the Bank’s decision from time to time.

    Ping An Digital Bank is not the supplier of any products or services provided by 3 Hong Kong / 3SUPREME and shall not be liable for any matters relating to the quality, supply, use, payment, refund, handset collection, warranty or after-sales services of 3 Hong Kong / 3SUPREME’s products or services. Offers subject to the relevant terms and conditions. For details, please refer to the “Ping An Digital Bank x 3 Hong Kong / 3SUPREME New Customer Exclusive HK$400 Cash Rebate Promotion Terms and Conditions” and “New Customer Time Deposit High Interest Offer Programme Terms and Conditions”

    Hashtag: #平安數字銀行 #PingAnDB #3HK #3Supreme

    The issuer is solely responsible for the content of this announcement.

    Ping An Digital Bank

    Ping An Digital Bank (International) Limited (“Ping An Digital Bank,” “PingAnDB”) is a wholly-owned subsidiary of Lufax Holding Ltd (“Lufax”) (SEHK: 6623; NYSE: LU) and a member of Ping An Insurance (Group) Company of China, Ltd. (“Ping An”) (SEHK: 2318; SSE: 601318). Ping An Digital Bank was granted a banking licence by the Hong Kong Monetary Authority in May 2019 to offer retail banking and business banking services. Backed by Ping An’s advanced technology, Ping An Digital Bank is elevating banking experience, serving customer in Hong Kong and the Greater Bay Area, establishing itself as Ping An Group’s comprehensive financial platform in Hong Kong.

    Hutchison Telecommunications (Hong Kong) Limited

    Hutchison Telecommunications (Hong Kong) Limited (“HTHK”), a leading mobile operator in Hong Kong, offers diverse and advanced mobile telecoms services under the 3 Hong Kong, 3SUPREME, SoSIM and MO+ brands, addressing different needs of the consumer market. HTHK is also dedicated to developing business and enterprise solutions under the 3Business brand in the corporate market spanning mobile commerce, information technology, smart city, the Internet of Things and big data. HTHK channels the latest technologies into innovations that set market trends and steer industry development.

  • Amber Beila’s ‘Within’ Named Only Beauty Finalist in Hashtag Asia Awards Facebook Category

    Amber Beila’s ‘Within’ Named Only Beauty Finalist in Hashtag Asia Awards Facebook Category

    Marking a milestone for Singapore’s beauty industry, Amber Beila’s “Within” campaign has been named a Hashtag Asia Awards 2026 finalist in the Best Social Media Campaign: Facebook category. The recognition comes as the skincare sanctuary celebrates its anniversary with a new skincare collection and recent expansion on Orchard Road.

    SINGAPORE – Media OutReach Newswire – 7 September 2026 – Amber Beila has been named the only beauty brand shortlisted in the Best Social Media Campaign: Facebook category at the Hashtag Asia Awards 2026, organised by Marketing-Interactive. Built around stories of confidence, “Within” leads the brand into its next chapter, alongside a signature four-piece skincare collection launch and a second Orchard Road outlet at The Heeren.

    Amber Beila's "Within" campaign, a Hashtag Asia Awards 2026 finalist, alongside its four-piece Luminous Series.
    Amber Beila’s “Within” campaign, a Hashtag Asia Awards 2026 finalist, alongside its four-piece Luminous Series.

    Redefining Beauty Through Personal Confidence

    Singapore’s beauty industry is navigating greater consumer caution around trust, transparency and brand communication. As audiences grow more wary of influencer-led promotion and increasingly value relatable voices, Amber Beila places personal stories of everyday confidence at the heart of its brand storytelling. Through “Within”, the brand follows three people navigating different life chapters, from putting themselves first to ageing with confidence, reflecting its wider focus on personalised skincare and confidence beyond appearance.

    Expanding the Vision Behind “Within”

    This trajectory of placing everyday confidence at the centre is reflected in Amber Beila’s showing at the Hashtag Asia Awards 2026. In the Best Social Media Campaign: Facebook category, “Within” was shortlisted against established names from the property, food manufacturing and social advocacy sectors, making Amber Beila the only beauty brand among the four-campaign finalist field.

    Returning for its fifth edition, the awards span 42 categories reflecting emerging audience behaviours and platform trends. Judges highlighted this year’s shortlisted work for its strategic rigour, calculated creative risks and effective amplification, alongside its ability to balance commercial objectives with emotional resonance and measurable brand impact.

    Building on this recognition, Amber Beila is extending its confidence-led approach through the four-piece Luminous Series, together with existing signature facials such as the Deep Pore Cleansing Facial, and a second Orchard Road outlet at The Heeren.

    “Over the years, we have seen our customers become more informed and intentional about how they care for their skin. Our Signature Skincare Collection was created to extend the Amber Beila experience beyond our salons, giving customers thoughtfully developed products that complement their professional treatments and become part of their everyday skincare routine,” said Ms Agatha Lee, Operations Director of Amber Beila.

    Together, these developments carry the “Within” message forward, reinforcing the belief that every story deserves to be seen.

    Hashtag: #AmberBeila

    The issuer is solely responsible for the content of this announcement.

    About Amber Beila:

    Established in 2012, Amber Beila is a beauty salon offering personalised facials and body care for a range of skin and body concerns. Its team combines skincare knowledge, beauty technology and sensory rituals to tailor each session to individual needs across four locations in Singapore. For more information, please visit:

  • From Sleeping in a Car to Owning a Fleet of Limousines: The Story of Titanium Limousines

    From Sleeping in a Car to Owning a Fleet of Limousines: The Story of Titanium Limousines

    SINGAPORE – Media OutRech Newswire – 8 September 2026 – Titanium Limousines, a Singapore-based luxury transport company, marks over a decade in business built on a founder’s journey from financial rock bottom to serving some of the country’s highest-profile transport needs.

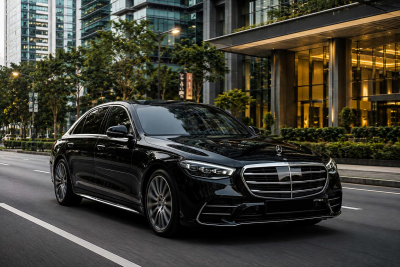
    Mercedes S Class Limousine Car in Singapore
    Mercedes S Class Limousine Car in Singapore

    Founded in 2012 by Mr Shah, Titanium Limousines began with a single vehicle and a $30,000 down payment funded almost entirely by his mother’s life savings. At the time, Mr Shah was unemployed, in debt, and driving other operators’ cars around the clock, often sleeping in the vehicle between jobs, just to stay afloat.

    “If I take this, I can’t fail,” Mr Shah recalled telling himself the day his mother handed him her savings. That principle has shaped the company ever since.

    From that single car, Titanium Limousines grew steadily, one vehicle at a time. Into a fleet serving corporate clients, event organisers, and families across Singapore. Over the years, the company has provided vehicles for foreign delegations and royalty, escorted by Traffic Police outriders, maintained ongoing arrangements with five-star hotels, and coordinated transport for major concerts and large-scale events.

    The business was not without setbacks. When Singapore’s borders closed during the Covid-19 pandemic, bookings disappeared overnight and much of the fleet sat idle for nearly a year. Mr Shah returned to driving personally to rebuild operations from the ground up, a pattern of hands-on resilience that has defined the company since its earliest days.

    Today, as ride-hailing apps have reshaped how people book transport, Titanium Limousines has positioned itself around what technology alone cannot replace: reliability, accountability, and a level of service built on direct, personal trust rather than an algorithm. The company offers airport transfers, corporate and VIP transport, and even wedding limousines, with a fleet spanning Mercedes S-Class, E-Class, and V-Class vehicles, Toyota Alphard/Vellfire, and larger vehicles for group travel.

    “Transportation isn’t simply about getting someone from one point to another,” Mr Shah said. “It’s about delivering peace of mind, consistency, and the confidence that every journey is handled with care.”

    Hashtag: #titaniumlimousines

    The issuer is solely responsible for the content of this announcement.

    About Titanium Limousines

    Titanium Limousines is a Singapore-based luxury chauffeur and limousine service founded in 2012, offering airport transfers, corporate transport, VIP and event logistics, and wedding limousine services across Singapore.

  • HiDream.ai Launches HiDream-O1-Embodied, Extending Its Native Omni-Modal World Model Strategy into Physical Interaction

    HiDream.ai Launches HiDream-O1-Embodied, Extending Its Native Omni-Modal World Model Strategy into Physical Interaction

    HiDream-O1-Embodied tops RoboColiseum’s Robustness leaderboard, highlighting the model’s ability to maintain stable performance under complex real-world conditions

    BEIJING, CHINA – Media OutReach Newswire – 8 September 2026 – HiDream.ai has officially launched HiDream-O1-Embodied, an embodied world model designed to advance physical interaction for embodied intelligence. Built on HiDream.ai’s native omni-modal technology strategy, the model enhances robots’ physical perception, dynamic prediction, and execution capabilities, enabling more robust interaction with the physical world.

    Picture.png

    The launch marks an important step in HiDream.ai’s broader effort to connect image, video, 3D, and action modalities within a unified architecture. By extending its world model capabilities from understanding and reasoning to action and execution, HiDream.ai is building a closed-loop technical foundation for native omni-modal intelligence.

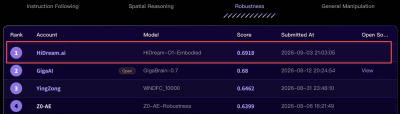
    Alongside its release, HiDream-O1-Embodied made its debut on RoboColiseum, an embodied intelligence model evaluation platform. The model ranked No. 1 on the platform’s Robustness leaderboard, achieving an average score of 0.692.

    “We believe a complete world model foundation requires three core capabilities: omni-modal representation, causal reasoning, and physical-world modeling — all centered on the ability to express, understand, and generate within the real world,” said Ting Yao, CTO of HiDream.ai. “From the beginning, HiDream.ai’s native omni-modal world model architecture was designed to support unified representations across modalities, including action. The release of HiDream-O1-Embodied marks a critical milestone in our technology roadmap, as we move from simulating the world to enabling AI to operate in the real world.”

    HiDream-O1-Embodied Tops RoboColiseum’s Robustness Leaderboard with a Score of 0.692

    RoboColiseum is a standardized simulation benchmark for embodied intelligence models, designed to provide a multidimensional and reproducible evaluation framework. Through high-fidelity simulation tasks that closely approximate real-robot performance, the platform helps developers assess model strengths and limitations while continuously tracking progress across the field.

    Open to universities, research institutions, model developers, and researchers worldwide, RoboColiseum continuously updates its evaluation results with the goal of establishing a reliable benchmark for embodied models.

    Built on high-fidelity simulation environments that closely mirror real-world conditions, RoboColiseum evaluates models across four major dimensions: instruction following, spatial understanding, robustness, and general-purpose manipulation. These dimensions are assessed through four capability leaderboards and 78 high-fidelity simulation tasks.

    Since entering internal testing, RoboColiseum has attracted dozens of leading models from China and abroad. Among its evaluation dimensions, Robustness is widely regarded as one of the most challenging. It measures a model’s stability and generalization under non-ideal conditions by varying backgrounds, lighting, materials, robot initial states, camera positions, and image quality, while also introducing diverse paraphrases of instructions.

    In other words, this is not a test conducted in the “greenhouse” of a lab environment. It is designed to evaluate how well a model performs when faced with the kinds of uncertainty, variation, and interference that robots are likely to encounter in the real world.

    HiDream-O1-Embodied ranked first on the Robustness leaderboard with a score of 0.692, supported by HiDream.ai’s native omni-modal foundation. A native omni-modal world model provides an inherent basis for cross-modal understanding, generation, and action. At the execution level, HiDream-O1-Embodied introduces advances across three core capabilities, enabling more precise instruction understanding, more reliable perception, and stronger resistance to environmental interference.

    Language Understanding: Moving Beyond Keyword Matching

    Traditional robots often interpret language instructions at the level of keyword matching. A robot may understand “Bring me the cup,” but change the phrasing to “Get me a cup” or “Hand me the cup,” and it may fail to respond correctly. HiDream-O1-Embodied covers an equivalent instruction space encompassing diverse verbs, sentence structures, and expressions. Rather than being constrained by specific wording, it focuses on the underlying intent. No matter how an instruction is phrased, the model can move beyond the literal wording and accurately identify what the user actually means.

    Visual Perception: Multi-View Collaboration for Greater Reliability

    In the physical world, a robot’s visual input is rarely ideal. Camera positions may shift, calibration accuracy can change over time, and individual visual feeds may be obstructed or disrupted. HiDream-O1-Embodied integrates information from multiple viewpoints, allowing different visual channels to complement one another rather than relying on a single fixed perspective. When part of the visual information becomes inaccurate or temporarily unavailable, the model can still leverage other viewpoints to understand the scene, assess the task, and continue execution. This transforms the system from one where “a single failure causes the entire system to fail” into one where “local limitations do not prevent the system from operating as a whole.”

    High Fault Tolerance: Learning to Execute Reliably in an Imperfect World

    Most models are trained primarily on “perfect” data — clear images, complete frames, and standardized viewpoints. The real world, however, rarely provides such ideal conditions. Changes in lighting, image degradation, occlusion, signal fluctuations, and scene variation are all common challenges robots face during real-world operation.

    HiDream-O1-Embodied proactively introduces a wide range of non-ideal conditions during training. By repeatedly exposing the model to incomplete, noisy, and unstable information, the system learns to make reliable decisions based on limited visual cues.

    This approach means the model is not optimized solely for peak performance under ideal conditions. Instead, it is designed to maintain stable task execution in complex, dynamic environments. Its fault tolerance is not limited to any single type of visual anomaly. When faced with changes in lighting, object appearance, scene layout, or visual quality, the model can make more flexible use of available information and reduce the impact of environmental variation on execution.

    For HiDream-O1-Embodied, the real measure of capability is not simply whether it performs well when everything is clear, but whether it can continue to complete tasks reliably when conditions are far from ideal.

    Model + Data: Building a “Real-World Foundation + Generative Augmentation” Data Production Paradigm

    The ability to perform reliably under imperfect conditions does not emerge by chance. It points to a fundamental challenge in embodied intelligence: the cognitive boundaries of a model are largely shaped by the data it can access.

    High-quality embodied data remains one of the scarcest and most decisive resources in the field. HiDream.ai’s dual-driven “model + data” strategy is a key factor behind the performance of HiDream-O1-Embodied on the Robustness leaderboard.

    The core breakthrough lies in making data production an integral part of model iteration. To achieve this, HiDream.ai has developed a “real-world foundation + generative augmentation” data production paradigm. Instead of passively consuming existing data, the model actively participates in creating and refining the data it needs to improve.

    A collaboration with Noitom provides a representative example. Using Noitom’s high-precision human motion-capture data as the real-world foundation, HiDream.ai leverages its native omni-modal capabilities to achieve 100x-scale data augmentation and refinement.

    Starting from a single real-world motion sample, the model can generate physically consistent video variations by changing variables such as background environments, lighting conditions, object forms, and scene configurations. This produces a large and diverse set of training samples while preserving underlying physical constraints.

    The key to this mechanism is that the model acts as both the “student” and the “teacher.” It generates targeted training samples based on the capabilities it needs to improve, creating a growth flywheel in which data and models continuously reinforce one another. This data-model flywheel helps HiDream-O1-Embodied maintain exceptional robustness when confronted with severe disturbances and real-world variability.

    HiDream.ai’s Native Omni-Modal World Model Matrix Continues to Take Shape

    Less than a month ago, HiDream.ai launched HiDream-O1-World, an interactive world model that took the top spot on the Navi sub-leaderboard of WBench, an interactive video world model benchmark, with an average score of 80.9.

    Interactive world models address “understanding and reasoning,” enabling AI to develop a comprehensive understanding of space, time, motion, and object relationships in digital environments. Embodied world models, by contrast, address “operation and execution,” enabling AI to perform real-world tasks in physical environments. Together, the two form a powerful complement to one another and lay a solid foundation for the development of native omni-modal world models.

    As Dr. Tao Mei, Founder and CEO of HiDream.ai, previously noted, the key to the next generation of foundation model competition lies not in improving the capabilities of individual modalities alone, but in moving from single-modal to multimodal intelligence, and ultimately toward natively unified omni-modal intelligence.

    From HiDream-O1-Image to HiDream-O1-World and now HiDream-O1-Embodied, HiDream.ai is steadily building a model family spanning vision models, interactive world models, and embodied world models. This not only demonstrates the expanding capabilities of its native omni-modal technology across multiple domains, but also reflects the technology’s strong capacity for intrinsic evolution.

    At a pivotal moment when advances in world model technology are accelerating, HiDream.ai is continuing to accelerate innovation and push the field forward.

    Hashtag: #HiDreamAI

    The issuer is solely responsible for the content of this announcement.

  • iFAST Hong Kong and J.P. Morgan Asset Management Partner to Expand Discretionary Portfolio Solutions for Wealth Advisers

    iFAST Hong Kong and J.P. Morgan Asset Management Partner to Expand Discretionary Portfolio Solutions for Wealth Advisers

    HONG KONG SAR – Media OutReach Newswire – 8 September 2026 – iFAST Financial (HK) Ltd (“iFAST Hong Kong”), a wholly-owned subsidiary of iFAST Corporation Ltd, today announced an expansion of its Discretionary Portfolio Management Solutions (DPMS) lineup in Hong Kong with the launch of two new portfolios powered by J.P. Morgan Asset Management (“JPMAM”), with the portfolios officially available to wealth advisers and their clients from August 2026.

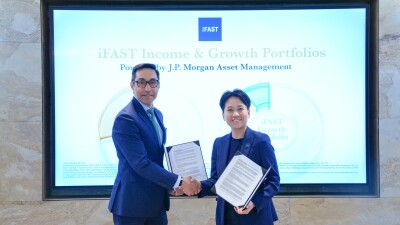
    (From left) Supreet Bhan, Head of Hong Kong Intermediary Business, J.P. Morgan Asset Management; and Glory Lau, General Manager, Platform Services, iFAST Financial HK
    (From left) Supreet Bhan, Head of Hong Kong Intermediary Business, J.P. Morgan Asset Management; and Glory Lau, General Manager, Platform Services, iFAST Financial HK

    The collaboration underscores iFAST Hong Kong’s commitment to its Business-to-Business (B2B) partners, giving wealth advisers and their clients access to a professionally managed investment solution that saves time and broadens choice.

    “Partnering with J.P. Morgan Asset Management allows us to bring institutional expertise to advisers and their clients here in Hong Kong. By outsourcing alpha generation through our DPMS, advisers can focus on nurturing trusted client relationships while delivering comprehensive financial planning.” said Ms Glory Lau, General Manager, Platform Services of iFAST Hong Kong.

    The DPMS advised by JPMAM leverages JPMAM’s comprehensive range of active ETFs globally, giving investors access to active management at a lower cost.

    “Our approach to active investing is grounded in extensive global research and a disciplined asset allocation process that’s been tested across market cycles. By partnering with iFAST, we’re making our leading actively managed ETF capabilities and portfolio solutions available to iFAST’s clients in Hong Kong. We look forward to helping iFAST’s clients pursue long-term objectives through the model portfolios striving for diversification, robustness across market cycles, and more consistent outcomes,” said Yuejue Jin, Asia Head of Multi-Asset Solutions, J.P. Morgan Asset Management.

    Empowering Advisers, Enhancing Client Experience

    The new DPMS portfolios give wealth advisers using iFAST Hong Kong platform greater choice and flexibility to align client portfolios with specific goals and risk profiles, while removing much of the administrative workload that typically consumes adviser and client time. Beyond asset allocation advisory services, JPMAM also provides investment insights and trainings, adding to iFAST Hong Kong’s adviser enablement ecosystem of exclusive content, courses, and events.

    Hashtag: #iFAST #JPMAM #Business #Finance


    The issuer is solely responsible for the content of this announcement.

    About iFAST Corporation Ltd.

    iFAST Corporation Ltd. (“iFAST Corp”, Stock code: AIY) is a digital banking and wealth management platform, with assets under administration (AUA) of S$36.13 billion as at 30 June 2026. Incorporated in 2000 in Singapore and listed on the SGX-Mainboard in December 2014, the Group is also present in Hong Kong, Malaysia, China, the UK and the US.

    The Group’s B2B platforms serve more than 980 financial advisory companies, financial institutions, banks and internet companies with over 15,300 wealth advisers across its markets. The Group offers access to over 29,600 investment products including mutual funds, bonds, stocks, ETFs, and insurance products, as well as services including wealth management solutions, online discretionary portfolio management services, banking services, pension administration, trust services, research and investment seminars, fintech solutions, banking, and investment administration and transaction services.

    iFAST Corp entered the Hong Kong market in 2007. iFAST Financial (HK) Limited is a fintech wealth management platform and a wholly-owned subsidiary of iFAST Corp. iFAST Financial (HK) Limited holds Type 1, 4, and 9 licences issued by the Securities and Futures Commission (SFC) and is a registered Mandatory Provident Fund (MPF) Intermediary under the Mandatory Provident Fund Schemes Authority (MPFA).

    The Group’s mission statement is, “To help investors around the world invest globally and profitably”.

    For more information, please visit or

  • New Research Reveals How Asia’s Wealthiest Families Give

    New Research Reveals How Asia’s Wealthiest Families Give

    Global research explores how newer wealth, continued business ownership, and family stewardship influence philanthropic practices among Asia’s wealthiest families

    • Roughly 94 percent of Asia‘s wealthiest families are first- or second-generation wealth holders
    • Approximately 95 percent of Asia’s wealthiest families retain control of the businesses that generated their wealth

    SINGAPORE – Media OutReach Newswire – 8 September 2026 – As private wealth continues to expand globally and an estimated US$74 trillion is expected to transfer between generations over the next 20 to 25 years, understanding how wealthy families approach philanthropy is becoming increasingly important. New research from The Bridgespan Group, based on analysis of 186 of the wealthiest individuals and families across 20 economies spanning Asia, Africa, Europe, and the Americas, sheds light on how the world’s wealthiest families give, what they fund, how they organise their philanthropy, and how they seek to create change.

    Supported by Bridgespan’s Funders Council comprising the Institute of Philanthropy, The Rockefeller Foundation, and the Gates Foundation, and with contributions from the Financial Services Development Council and Wealth Management Institute, High-Impact Family Philanthropy: What Makes Family Giving Distinctive marks the third year of the High-Impact Philanthropy series, building on previous research on institutional philanthropy and corporate giving.

    “This research comes at a pivotal moment for family philanthropy, especially as private wealth continues to grow,” said Xueling Lee, co-author and partner at Bridgespan. “Our research helps fill a knowledge gap on how the world’s wealthiest families organise their philanthropy and pursue impact, and finds distinguishing characteristics in Asia.”

    In Asia, where founders and second-generation leaders often remain closely involved in the businesses that generated their wealth, philanthropy is frequently connected to broader questions of stewardship, business ownership, succession, and community engagement. The research finds that these differences are shaped by factors including the relative newness of wealth, continued business ownership, and the close connection between family, business, and philanthropy. Bridgespan’s research on corporate giving highlights this dynamic: founder- or family-linked companies account for 11 of Asia’s 20 largest corporate funders, compared with four among the world’s 20 largest corporate funders.

    “Beyond the scale of their giving, many families bring a long-term perspective, deep personal commitment, and relationships across sectors built over decades,” said Brian San, secretary-general of the Institute of Philanthropy. “These qualities are particularly relevant in Asia, where family-owned businesses remain a powerful force and philanthropy is often closely connected to family stewardship, business leadership, and community engagement. The report highlights how these characteristics can help families catalyse collaboration, support innovation, and contribute to meaningful impact over time.”

    “This research confirms what we have seen firsthand: family philanthropy has driven some of today’s boldest solutions and most pioneering research. These funders are uniquely positioned to take risks and build coalitions that can solve big, complex problems at their root,” said Deepali Khanna, senior vice president and head of Asia (division) at The Rockefeller Foundation. “Some of the work we are proudest of, like the Global Energy Alliance for People and Planet, started because family philanthropies were willing to commit early and jointly at a time when no single institution could have carried it alone.”

    While the report finds that wealthy families around the world share many common philanthropic behaviours, it also identifies several characteristics that distinguish family philanthropy in Asia.

    • Asia’s wealth is newer: Approximately 94 percent of wealth held by Asia’s wealthiest families sits with first- or second-generation wealth holders, compared with roughly 85 percent in high-income economies outside Asia. The relative newness of wealth influences how wealth is held, the degree of family involvement in operating businesses, the availability of liquid assets, and the form philanthropy takes.
    • Asian families retain tighter control of their businesses: Approximately 95 percent of Asian families maintain control of the businesses that generated their wealth, compared with roughly 68 percent outside Asia. Where wealth remains closely tied to an operating business, philanthropic decisions often sit alongside broader considerations such as government relationships, succession planning, and reputation.
    • Families fund remarkably similar issues across regions: Education, health, and support for marginalised and vulnerable populations are among the top issues supported by wealthy families. In Asia, families are more likely to support elderly care, religion, and sports, while families from other regions more frequently fund science and technology initiatives, including those related to artificial intelligence.
    • Few families publicly report outcomes from their giving: More than 80 percent of families in Asia publicly report outputs from their giving, such as schools built or teachers trained, compared with just 45 percent of high-income families outside Asia. However, outcome reporting, such as learning gains or graduation rates, remains uncommon across all groups.

    Beyond examining how families give, the companion report How the World’s Wealthiest Families Give explores approaches that help families translate their resources and influence into meaningful and sustained impact:

    1. Taking risks others cannot or will not: Families often have the autonomy to move from decision to deployment more readily than institutional or corporate funders. In Singapore, for example, the Lien Foundation made a decade-long push into early childhood development, a sector that few had championed when it began. Its sustained work alongside government and other stakeholders contributed to broader sector development over time.
    2. Facilitating collective action: Families with trusted relationships across sectors can bring together stakeholders who might not otherwise gather, helping fragmented efforts to evolve into coordinated action. In 2024, the Jollibee Group Foundation, led by Tony and Grace Tan Caktiong, partnered with the Provincial Government of Basilan, the Zuellig Family Foundation, and the League of Corporate Foundations to expand its school feeding programme. Together, the partnership supports the delivery of nutritious meals to nearly 25,000 children in 250 schools.
    3. Mobilising multiple types of capital: A family with authority across philanthropic and investment decisions may be able to move capital across different instruments with fewer external negotiations, board approvals, or fiduciary obligations to outside investors.

    Download the full reports:

    Hashtag: #TheBridgespanGroup #Bridgespan #CSR #ESG #Philanthropy #FamilyPhilanthropy #InstituteofPhilanthropy

    The issuer is solely responsible for the content of this announcement.

    About The Bridgespan Group

    The Bridgespan Group () is a global nonprofit that collaborates with social change organisations, philanthropists, and impact investors to make the world more equitable and just. Bridgespan’s services include strategy consulting and advising, sourcing and diligence, and leadership team support. We take what we learn from this work and build on it with original research, identifying best practices and innovative ideas to share with the social sector. We work from locations in Boston, Delhi, Johannesburg, Mumbai, New York, San Francisco, Singapore, and Washington, DC.

  • MIHAS Knowledge Hub Expands into Year-Round Platform to Power Export Growth in Global Halal Markets

    MIHAS Knowledge Hub Expands into Year-Round Platform to Power Export Growth in Global Halal Markets

    KUALA LUMPUR, MALAYSIA – Media OutReach Newswire – 8 September 2026 – To accelerate the global competitiveness of Malaysian exporters, the MIHAS Knowledge Hub has evolved into a year-round trade intelligence platform since 2021. Moving beyond the traditional four-day exhibition framework, the initiative introduces AI-driven content curation, year-long digital programming, and modern multimedia formats to deliver real-time, actionable market insights directly to local businesses.

    The Yayasan Pembangunan Ekonomi Islam Malaysia (YAPEIM) has joined this year’s strategic initiative to uplift the 2026 platform, bridging the gap between market intelligence and export action. It features four distinct knowledge-sharing pillars designed for every stage of the exporter journey:

    • Prelude & “Meet the Experts” Webinars: A digital-first series starting as early as August 2026 to guide exporters through market entry requirements, compliance, and international trade facilitation mechanisms.
    • Pocket Talk: Concise, high-impact physical sessions focused on emerging industry trends, rapid innovation, and practical market solutions delivered live by Halal trade experts.
    • #SembangBlog / #SembangSantai Podcast: A new flagship live podcast format bringing a conversational edge to MIHAS 2026, featuring industry pioneers, leaders, and changemakers sharing real-world business journeys and bold ideas for the future Halal economy.


    • Power Talk (The Finale): Taking place on 23 September 2026 at 10:00AM at MITEC Kuala Lumpur, this flagship session features corporates leaders from DHL Express, UOB Malaysia, and Farm Fresh. The panel will address supply chain resilience, e-commerce fulfilment, trade financing, and strategies for navigating geopolitical headwinds.

    The expansion builds on the success of the 2025 edition, which drew 2,000 participants across 23 physical sessions and 16 international “Meet the Experts” webinars that featured 74 industry experts, connecting local businesses directly with trade experts across ASEAN, East Asia, the Middle East, Europe, and the Americas.

    Beyond strategy, the platform acts as a direct preparation runway for MATRADE’s flagship International Sourcing Programme (INSP), equipping local sellers with the market data and confidence required to convert B2B meetings into signed export contracts.

    MATRADE Chief Executive Officer, YBhg. Dato’ Indera Abu Bakar Yusof said, “Export success today depends not only on having quality products and services, but also on understanding international market dynamics, buyer expectations, regulatory requirements, and emerging trends. These are key success factors in gaining market access globally.”

    “The MIHAS Knowledge Hub helps businesses bridge that gap by connecting them with industry experts, buyers, and policymakers who provide practical, actionable insights. By introducing more accessible formats such as live podcasts alongside our technical sessions, we are making critical market intelligence easier to engage with and apply,” he added.

    MIHAS 2026 takes place from 23 to 26 September 2026 at MITEC, Kuala Lumpur. Malaysian exporters, SMEs, and industry stakeholders are invited to register early to access exclusive trade insights, expert networks, and global business opportunities via the official MIHAS website.

    Hashtag: #MIHAS

    The issuer is solely responsible for the content of this announcement.

    Malaysia External Trade Development Corporation (MATRADE)

    The Malaysia External Trade Development Corporation (MATRADE) is the national trade promotion agency under the Ministry of Investment, Trade and Industry (MITI), mandated to develop and promote Malaysia’s exports to the world. Through its network of domestic and overseas offices, MATRADE supports Malaysian companies in building export capabilities, accessing new markets, and strengthening Malaysia’s position in international trade.

    MIHAS Knowledge Hub

    MIHAS Knowledge Hub is the knowledge and thought leadership platform of the Malaysia International Halal Showcase (MIHAS). Through webinars, expert forums, market briefings, and digital content, the platform provides businesses with insights and practical knowledge to support export growth and participation in the global halal economy.