The Securities Commission Malaysia (SC) has introduced a framework that will benefit dealer’s representatives (DRs) in the capital market. The new framework, which took effect on 14 April 2023, will allow them to expand their scope of activities and roles beyond just dealing in securities.
The SC recognises the importance of promoting competition and enhancing the quality of services in the capital market. In this regard, this framework will also provide DRs greater flexibility to develop their careers and meet the evolving needs of investors.
In addition to facilitating share transactions for their clients, DRs who meet certain requirements can apply for additional licenses to engage in a variety of activities, such as investment advice, financial planning, restricted dealing in unit trust and dealing in private retirement schemes. The new framework also removes the requirement for DRs to be employed on a full-time basis.
These flexibilities are only available to DRs who have been licensed for more than five years and meet the competency requirements for the relevant regulated activity. To ensure effective supervision and oversight of DRs performing these additional regulated activities, they are required to be undertaken within the same broking firm or within its group of companies.
The expansion of DRs permitted activities is facilitated through amendments to Chapter 4 of the Licensing Handbook. The Licensing Handbook and accompanying FAQ are available on the SC website here.
About the Securities Commission Malaysia
The Securities Commission Malaysia (SC), a statutory body reporting to the Minister of Finance, was established under the Securities Commission Malaysia Act 1993. It is the sole regulatory agency for the regulation and development of capital markets. The SC has direct responsibility for supervising and monitoring the activities of market institutions, including the exchanges and clearing houses, and regulating all persons licensed under the Capital Markets and Services Act 2007. More information about the SC is available on its website at www.sc.com.my. Follow the SC on twitter at @SecComMy for more updates.
In the first article in our series, we took a closer look at the current financial attitudes and behaviours of millennials and Gen Z Malaysians. Based on findings from ICMR’s nationwide survey, we highlighted that the investment behaviours of young investors could be grouped into three categories linked to differences in their income, financial knowledge or confidence, and risk tolerance.
Beyond these individual differences, it is also important to understand how broader social trends and structural issues could shape investment preferences and behaviours. This includes media consumption trends, as young investors increasingly turn to digital sources of information, which could impact how they make financial and investment decisions.
Online Channels Are Preferred Sources
The Internet or online resources are the most popular source of information on investment products, reported by 69% of respondents in ICMR’s survey. Within this group, Facebook/Instagram (75%), websites/blogs (68%), and YouTube (65%) are the most frequented online platforms. The preference for online sources of information is particularly more prevalent among those under 30 years old.
These findings are unsurprising as the younger generations grew up during the Internet age and feel more comfortable conducting their online lives. Millennials generally led the adoption of new technology, and a McKinsey study in the Asia Pacific found that 50 to 60% of the primary influence in brand decisions for Gen Zs comes from social media and online sites.
Figure 1: Source of Information (Data Source: ICMR)
But while online platforms like Instagram and YouTube provide an opportunity to reach out directly to millennials and Gen Zs, they do not always reach those who, ironically, may need this information the most. Although the Internet is abundant with resources catered for different levels of financial literacy, most of these resources still require users to seek out this information actively.
“I know there [are] a lot of videos out there, but I find most of it boring or too long. I tune out after a few minutes. I just want something easy to understand. It helps if I don’t have to seek it out actively.”
– Haris, 25, journalist
Confirmation Bias In New Social Networks
In contrast to other social platforms, TikTok delivers content to its users using a recommendation system. What users see on their TikTok feed is less determined by who they follow but curated by an algorithm based on their interests. Some respondents interviewed by ICMR mentioned they came across financial education videos on TikTok even without actively seeking financial information online.
Social networks that deploy recommendation systems thus provide a promising opportunity to reach target segments that do not actively seek out financial information. Nonetheless, these same segments might not have the right skills or knowledge to assess the trustworthiness of all the financial content they come across and determine the most suitable information for themselves.
For instance, the #fintok hashtag on TikTok (which has had more than 500 million views at the time of writing) includes everything from basic budgeting tips to advice on specific stock picks. Just as too little information can impact decision-making, too much information can lead to selective information filtering due to confirmation bias or the tendency to reinforce pre-held beliefs.
“I’ve never looked for financial information before, I don’t consider myself very financially literate. But I saw a TikTok video on money-saving tips and then slowly started watching more personal finance content there. My friends and I also started talking about property investments and passive income after watching it on TikTok.”
Farish, 30, Cafe manager
#FinTok, also known as Financial TikTok, is a subcommunity of TikTok users who provide advice, education, and discussions on personal finance via short video clips (Image Source: SECCL)
By applying behavioural concepts to financial decision-making, we can better understand how investors become susceptible to scams. Social preferences refer to the notion that community members’ and peers’ savings and investment decisions have a causal effect on individual decisions through social interactions or pressures for conformity, acceptability, and social identity.
Leveraging social preferences might help engage investors but can make them more susceptible to misinformation and herding behaviour. Herding behaviour is when people do what others do instead of using their information or making independent decisions. This could lead to individuals being involved in scams, misled, or creating investment bubbles.
For example, Malaysia’s Ombudsman for Financial Services (OFS) said in 2020 that the rise of financial scams is due to scammers using social engineering tactics to exploit victims’ financial insecurities during the pandemic. Since social networks provide access to a wealth of personal information, scammers use this data to target and manipulate consumers with higher vulnerability easily.
In behavioural economics, social preferences describe the human tendency to care about not only one’s material payoff but also the reference group’s payoff (Image Source: iStock / oatawa)
Developing Financial Literacy As The Way Forward
In today’s fast-paced and information-overloaded environment, it is becoming more important for young investors to improve their financial literacy proactively. The rise of non-traditional and unregulated sources of information means investors need to take ownership of their financial decisions with the right skills, knowledge, and tools to make better investments.
Fortunately, many online financial courses and training are available for individual capacity-building. Leveraging behavioural insights can also provide new ways to think about managing finances. Developing an awareness of their biases and how they can be exploited can help young investors build safer, more strategic long-term investing habits.
This article is part of a content series by the Institute for Capital Market Research (ICMR). Follow ICMR’s Facebook page to stay updated on behavioral tips and insights for better investing habits. To learn more about ICMR’s research on millennials and Gen Z, visit www.icmr.my or download the full report.
About the Authors
Datin Aida Jaslina Jalaludin, Head of Research, ICMRNadhirah Ibrahim, Research Analyst, ICMR
Strategic petroleum reserves exist in the care of governments around the world. The largest and unheard of by most retail investors is the U.S. Strategic Petroleum Reserve. Today, we will look closer at the oil market and your investment.
The U.S. Strategic Petroleum Reserve (SPR) is one of the world’s largest crude oil stockpiles. Conceived as a defensive weapon against geopolitical crises in the ’70s, the SPR’s purpose and function have evolved. It is a massive stockpile of crude oil based mostly in four major locations around the Gulf Coast.
The SPR is a “tremendously unique asset” and argues that U.S. Congress-mandated sales are ill-conceived. The SPR is a defensive weapon against geopolitical crises, and its purpose and function have evolved. Energy investors need to know about today’s volatile oil market and how it affects the SPR.
The Oil Market And Your Investment: Why Is US SPR Important?
The SPR is important because it provides a strategic and economic advantage for the United States. It is a defensive weapon against geopolitical crises, and its purpose and function have evolved. The SPR’s importance lies in its ability to cushion against sudden oil supply disruptions and price spikes. It also provides a strategic advantage by allowing the U.S. to respond to global oil market disruptions with greater flexibility and speed.
The SPR has been used to mitigate the impact of oil supply disruptions caused by geopolitical crises. For example, it was used during the Gulf War in 1991 and Hurricane Katrina in 2005. During the Gulf War, the U.S. released oil from the SPR to offset the loss of oil supplies from Iraq and Kuwait. During Hurricane Katrina, the SPR was used to help refiners in the Gulf Coast region affected by the hurricane to maintain operations.
The Oil Market And Your Investment: How Does US SPR Work?
The SPR works by storing crude oil in underground salt caverns in four major Gulf Coast locations. The SPR has a current capacity of 713.5 million barrels of crude oil. The Department of Energy (DOE) manages the SPR and is responsible for maintaining the stockpile. The DOE also has the authority to release oil from the SPR in response to supply disruptions or other emergencies threatening the U.S. economy or national security.
The Oil Market And Your Investment: Difference Between SPR and OPEC+
The U.S. Strategic Petroleum Reserve (SPR) is a massive stockpile of crude oil based mostly in four major locations around the Gulf Coast. It was conceived as a defensive weapon against geopolitical crises in the ’70s, and its purpose and function have evolved.
On the other hand, OPEC+ is a group of oil-producing countries that includes members of the Organization of the Petroleum Exporting Countries (OPEC) and non-OPEC countries. The group was formed in 2016 to coordinate oil production and stabilize prices.
The SPR is a stockpile of crude oil owned by the U.S. government and used to help stabilize oil prices during times of crisis. OPEC+ is a group of countries working to coordinate oil production and stabilize prices.
The Oil Market And Your Investment: Weakening US Dollar May Further Impact Price Of Oil & Inflation
The weakening of the US dollar can lead to an increase in commodity prices, especially crude oil prices. This can lead to inflation as higher oil prices can lead to higher transportation costs and higher prices for goods and services. The Federal Reserve aims to keep inflation under control by adjusting interest rates. The Federal Reserve may increase interest rates to slow economic growth and reduce inflation if inflation rises too much. However, if inflation remains low, the Federal Reserve may keep interest rates low to encourage economic growth.
So, a weakening US dollar can lead to higher commodity prices and inflation. The Federal Reserve aims to keep inflation under control by adjusting interest rates.
Carley Garner, Senior Commodity Strategist discussed on Bloomberg Television recently, has put US$80 oil price is pivotal. A close above US$81 likely leads prices into the high US$90.00s. Such as positive seasonality and speculators having plenty of buying power. In such an environment, the fundamental stories everyone has been talking about will matter.
The Oil Market And Your Investment: Rising Inflation And Your Investment
Inflation can affect investment returns. Inflation also impacts the returns that an investor earns on the investments he or she makes. Therefore, the concept of inflation-adjusted or real returns is important for all investors to comprehend.
Put simply, real return = nominal return less inflation.
Inflation lowers your returns and has led some investors to favor high-return investments and investments with inherent value, like real estate. It also has some investors keeping as little money as possible in the bank because money constantly loses value.
The Oil Market And Your Investment: What Should You Do?
Asset allocation is an investment strategy that balances risk and reward by dividing an investment portfolio among asset categories such as stocks, bonds, and cash. The goal of asset allocation is to minimize risk while maximizing returns. It is important because it helps investors diversify their investments and reduce the impact of market volatility on their portfolios. By investing in a mix of assets that have different levels of risk and return, investors can achieve a more stable return over time.
Asset allocation can be done differently depending on an investor’s goals, risk tolerance, and investment horizon. Some investors prefer a more aggressive approach with a higher percentage of stocks in their portfolio, while others prefer a more conservative approach with a higher percentage of bonds and cash.
It is important to note that asset allocation does not guarantee a profit or protect against loss. However, it can help investors achieve their long-term financial goals by reducing risk and increasing returns over time.
Rather than putting everything into the oil market and your investment, perhaps it is time to look at other commodities as an alternative. One such alternative is investing in gold, where Carley Garner further adds the price of gold could potentially break out the US$2,100 level with the best target towards US$2,600 by or before 2024. She projected that such a move is possible with two main factors, the weaker dollar and political uncertainty.
Well, there you have an update about the oil market and your investment.
Mukhriz Mangsor is currently the Head Global Market Strategist at Quantdynamic Research Company. His expertise includes financial education, financial institutions, and property trading with clients, including Brunei, Canada, Malaysia, Singapore, and the United States firms.
Have you ever gone grocery shopping without a checklist? Most of the time, you have a hard time deciding which items to buy first, which results in buying things that are not your priority. It will be a waste when you purchase something, but you don’t need it then.
It is similar to investing; you must know how to create your stock watchlist. Otherwise, you will be wasting time and money buying stocks that are not good.
What Is A Watchlist?
According to Investopedia, a watchlist is a set of securities an investor monitors for potential trading or investing opportunities.
A watchlist will help you personalize your list with stocks you are interested in.
How To Create Your Stock Watchlist?
How to create a stock watchlist is not the main issue. But how to create your stock watchlist that is efficient is more important. You need to create your stock watchlist and make sure that it is an effective one.
An effective watchlist will save you time when selecting which stocks to buy and helps investors select stocks easier. Below are a few ideas on how you can create your stock watchlist.
Different exchanges may have different numbers of sectors. A country with a bigger economy usually has more industries and thus has more sectors. It can be seen in big countries such as the United States, China, and the United Kingdom.
In Bursa Malaysia, there are 13 sectors available. An easy way to build a watchlist is by sectors. When there is any sentiment play or theme play, investors can easily open their watchlist and select stocks based on the watchlist created.
For example, an oil & gas sector watchlist may consist of companies that run businesses downstream, midstream, and upstream. A watchlist will make your life easier whenever a catalyst is related to sectors.
Besides that, some investors may be interested in a particular sector. The technology sector is the sector that has been attracting a lot of investors. This is due to the growth potential in that sector. If you are one of them, you may consider building a watchlist with technology counters.
Watchlist By Strategies
Some investors might have a watchlist based on their trading or investment strategies. In this type of watchlist, your criteria for stocks might include the following:
Traders with multiple investment objectives can create a few watchlists based on the period they will hold the stocks.
1. Short-term watchlist
List of stocks that you are monitoring closely every day.
2. Mid-term watchlist
List of stocks you monitor and wait for the right timing to enter. Once bought, these stocks will be kept in the portfolio for a few weeks or months.
3. Long-term watchlist
List of stocks you plan to buy and keep for a long time, for example, more than a year. This watchlist can be a list of stocks with strong fundamentals, consistently giving out dividends and blue-chip stocks.
How To Create Your Stock Watchlist In The CGS-CIMB iTrade Platform
If you have an account with CGS-CIMB and are unsure how to create a watchlist, below are the steps to follow.
Click on Watchlist. Next, click Create Watchlist.
Enter your watchlist name in the box provided. You can set the watchlist according to sectors or businesses.
Click on View Watchlist to view the watchlists that you have created.
Type the stock that you wish to put in your watchlist.
Right-click on the stock name and click on Add to Watchlist.
Click on the downward arrow and select your watchlist. The stock can be viewed in the watchlist that you select, making it easier for you to search in the future.
You can always rename your watchlist and delete your watchlist.
In conclusion, it is a smart action if you have more than one watchlist. If you already have a trading account, create your stock watchlists to save time. If you are busy with work, that is not an excuse, as you can build your watchlist even after working hours when you are chilling and have some free time.
The Institute for Capital Market Research Malaysia (ICMR) today launched its latest research report titled “New Age Vulnerabilities: Understanding Investor Vulnerability within the Malaysian Context”. Based on its findings, the report highlights that Malaysians experience overlapping vulnerability drivers that impair their ability to make sound financial decisions. As a result, they are more likely to fall victim to scams, be inadequately prepared for retirement, and face everyday difficulties while investing.
ICMR’s research was motivated by the need to develop a comprehensive and empirically informed understanding of how Malaysians experience vulnerability in their investment journeys. Many investors today are at risk of suffering fraud, financial exploitation, or the effects of unsuitable investments due to the changing nature of financial services, financial decision-making, and access to information. Indeed, 84% of surveyed respondents said they had received advice on financial products that turned out to be a scam and 36% had lost monies to a scam.
ICMR groups the key drivers of investor vulnerability into three broad categories based on their characteristics: situational (changing circumstances), investor behaviour and accessibility to financial products and services, as well as issues related to the industry. These categories were informed by a benchmarking exercise that compared definitions used by local and global regulators. A nationwide quantitative survey was then implemented alongside qualitative focus group discussions to better understand the investing experiences of Malaysians.
The study found a wide majority of respondents being exposed to behavioural and access drivers (93%), followed by situational drivers (54%) and industry-related drivers (51%). Within the first category, 64% felt either financially unstable or living paycheck-to-paycheck, hence experiencing mental stress. As for situational drivers, 61% felt negatively impacted by difficult events like job loss, income shock, or the deaths of close relatives. Meanwhile, 70% experienced difficulties in engaging with financial service providers, including unsuitable pricing or terms.
Nonetheless, the findings also indicate that different types of vulnerability are frequently overlapping and closely interconnected – meaning that financial distress is not always attributable to a particular cause. The experiences within each vulnerability category are as diverse as the experiences of vulnerability across the group as a whole. Moreover, financial or investment scams have cut across all groups of the surveyed population, with those susceptible driven greatly by greed and herding behaviour from the influence of family or friends.
The third Capital Market Masterplan (CMP3) launched by the Securities Commission Malaysia (SC) in 2021 mentions the “identification and assessment of vulnerable investors” as a top priority over the next five years for “enhancing focus on protecting investors against vulnerabilities”. As such, ICMR’s research seeks to assist the SC’s enhancement of investor frameworks and protection efforts for reducing the harm experienced by vulnerable investors, as well as provide context for firms to deal with vulnerable clients and provide appropriate levels of care.
In this regard, ICMR recommends a dual and systematic approach to address investor vulnerability in the Malaysian context. Firstly, there is a need to build financial resilience across the population by addressing intersectional vulnerabilities, which include both structural and behavioural barriers. This must then be complemented with a targeted approach to deal with vulnerable investors, including enhanced suitability assessments and regulatory oversight as well as educational and training programmes.
“Our research has shown that vulnerability drivers can impact Malaysian households and individuals at many different life stages, situations, health levels, even different investment experiences. The combination of behavioural and structural issues goes beyond the ambit of any single regulator or agency, which is why there is a need for a whole-of-nation approach across jurisdictions. In line with this, behavioural insights including the trigger points identified by ICMR should be incorporated into every stage of a policy cycle for more effective implementation”, said Datin Azleen Osman Rani, Director of ICMR.
ICMR’s survey was distributed from April to June 2022 to 2,019 respondents across East and West Malaysia, aged between 18 – 70 years old. Hard recruitment quotas were used to ensure a representative sample of age, racial, and monthly household income distribution akin to the Malaysian Department of Statistics’ Census. To provide additional context to the quantitative survey responses, qualitative interviews were conducted from July to September 2022 with five targeted focus groups between the ages of 25 – 66 years old.
Young people matter. With older generations increasingly reaching retirement age, millennials and Gen Z are becoming increasingly important to the economy. They are now the largest generational cohorts, with the power to influence consumer and market trends over the next decade. But these younger generations face challenges, including digitalization and a fast-changing job market.
Given the sheer size and potential of millennials and Gen Z, the Institute for Capital Market Research Malaysia (ICMR) recently conducted a nationwide study to understand better their issues, challenges, and behaviours regarding personal finance and investing. This article looks closely at ICMR’s research data and what it tells us about the next generation of Malaysian investors.
Not All Young Investors Are Alike
As with any generation, young investors are not a monolithic group – their individual needs and preferences differ due to various factors, from life stage to upbringing to income. ICMR’s survey, distributed to 1,500 respondents, found that millennials and Gen Z Malaysians can be categorized into three groups, each with unique characteristics.
22% of respondents formed Group A, comprised of those not investing in investment products. Meanwhile, Group B, making up 33% of respondents, only invests in Amanah Saham Nasional Berhad (ASNB) funds and/or unit trusts. The remaining 45% making up Group C, invests in various other investment products not limited to just ASNB and unit trusts.
Figure 1: Three different categories of respondents (Source: ICMR)
Although millennials and Gen Z investors generally share attitudinal and cultural similarities that separate them from older generations – there are also distinct demographic and behavioural differences between the three groups of young investors identified by ICMR. These differences can be understood in demographics and income, financial literacy and risk tolerance, and income allocation.
Demographics And Income
Regarding demographics, there are more females in Group A and B, whereas 60% of Group C are males. A higher proportion from the East Coast does not invest (Group A), while Group C has a higher proportion from the Central region. Moreover, although Malays comprise only 58% of total respondents, they form the majority of those who do not invest (63%).
More notably, there are differences in household income levels between all three groups. While 69% of Group A earn less than RM5,000 in monthly household income, 56% of Group B earn between RM3,000 – RM7,000. Meanwhile, respondents who fall under Group C were found to have significantly higher incomes, with 31% having household incomes above RM10,000.
Figure 2: Demographic and Income Differences Between Groups (Source: ICMR)
Nonetheless, in-depth responses of individuals via qualitative interviews with ICMR suggest that the level of disposable income matters more than earned income. Some interviewees felt they could start investing while making RM3,000 a month, while others only felt comfortable after earning RM7,000 a month. But all interviewees agreed that they are more likely to invest if their disposable income increases.
“I recently changed jobs and got a pay rise, and it’s been much easier for me to invest now. Before this, even though I was getting decent pay for my age, I found it hard because I enjoy my lifestyle like going out for meals with friends, and that’s not something I’m willing to give up”
Roshan, 28, consultant
Financial Literacy And Risk Tolerance
ICMR’s research suggests a link between financial knowledge, financial confidence, and risk tolerance with the likelihood of investing and the kind of products invested in. For instance, someone who does not know much about financial matters and has little financial confidence is also unwilling to take risks – hence not investing and falling into Group A.
This could also explain behavioural differences between Group B, which invests only in ASNB funds or unit trust products, and Group C, which invests in other capital market products. The first unit trust company in Malaysia was set up in 1959. This might be why retail investors are most comfortable with unit trust products, considering their long history in Malaysia.
Figure 3: Financial Literacy and Risk Tolerance Levels Between Groups (Source: ICMR)
Additionally, many investors who only invest in ASNB funds or unit trust products (Group B) tend to be less risk tolerant and financially confident. In contrast, those who invest in other capital market products like shares or cryptocurrency, which are perceived to be riskier, tend to have higher risk tolerance levels and feel more financially confident.
“I have an ASNB account, although allocations can be hard for a Chinese. I consider the money in ASNB and my unit trust savings because they’re safer. I have some foreign shares and some cryptocurrency, which I consider investing. I make sure I keep 60 – 70% of my money in the safer options and make sure they’re on regulated platforms, and then I’m happy to take more risks with the other investments”
Han Cheong, 32, civil servant
Income Allocation
Behavioural shifts across the groups are also reflected in ICMR’s survey results on income allocation. A higher percentage of Group C stated that they set aside amounts for investing only (27%) or separate amounts for savings and investing (30%). On the other hand, a higher percentage in Group B stated that they set aside money for savings only (52%).
This indicates a shift in mental accounting from Group B to Group C, with those who invest in other capital market products being more likely to distinguish between saving and investing. Mental accounting refers to the tendency to mentally sort out funds into separate accounts, affecting how a person thinks about their spending.
Figure 4: Income Allocation Between Groups (Source: ICMR)
Complementing the survey data above, findings from ICMR’s qualitative interviews also suggest that many young Malaysians perceive safer investment products as “savings.” In contrast, riskier products are perceived as “investing.” This tendency concerns their own personal risk assessments and methods of mentally dividing their money.
“I opened an ASB account and took out an RM50,000 ASB loan because my mother said I should. I pay the loan monthly, but I honestly have no idea how it works. I didn’t know until now that I could also put money regularly into my account if I wanted to”
Haris, 25, journalist
Catching Up With Young Investors
ICMR’s research findings on young investors highlight that many factors are linked to one’s investment behaviour, including income, financial knowledge or confidence, and risk tolerance. Policymakers and industry players should avoid a “one-size-fits-all” approach when dealing with millennial or Gen Z investors and instead adopt more nuanced or tiered policies and products.
As for young investors who are still unsure or not confident about investing, leveraging behavioral insights to incorporate the right tools, self-awareness, and techniques to navigate their personal finances can help. Understanding their biases and using heuristics (mental shortcuts) to simplify the investment decision-making process will encourage safer and more strategic investing habits for the long term.
This article is part of a content series by the Institute for Capital Market Research (ICMR). Follow ICMR’s Facebook page to stay updated about behavioral tips and insights for better investing habits. To learn more about ICMR’s research on millennials and Gen Z, visit www.icmr.my or download the full report here.
About the Authors
Datin Aida Jaslina Jalaludin, Head of Research, ICMRNadhirah Ibrahim, Research Analyst, ICMR
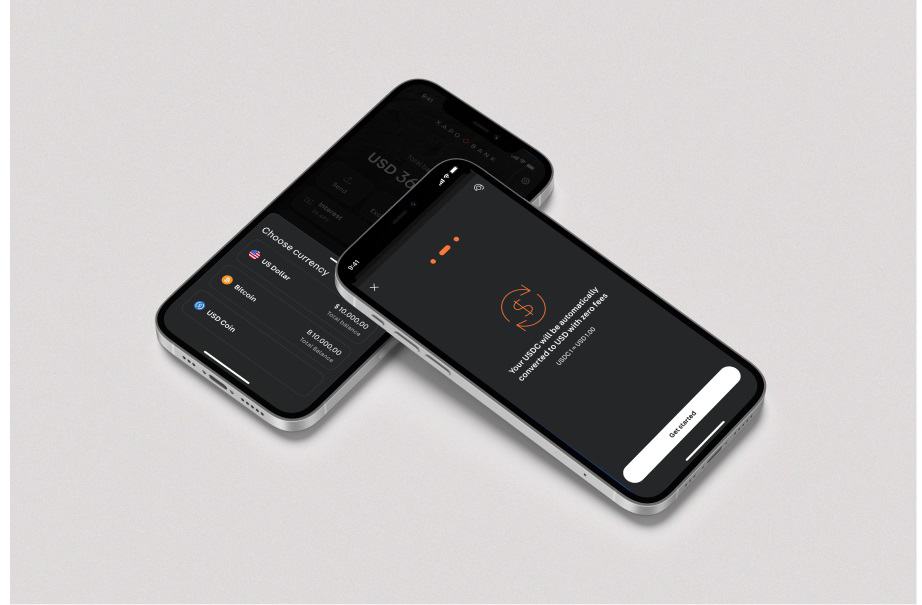
Xapo Bank, a leading Bitcoin custodian and licensed private bank, has collaborated with Circle, a global financial technology company helping money move at internet speed, to become the first licensed bank in the world to integrate USDC payment rails as an alternative to SWIFT. USDC is a digital dollar, also known as a stablecoin, that provides a faster and more efficient way to send and receive money around the globe, 24/7, including weekends, in under an hour.
By adding outrails to its existing USDC onramps, Xapo Bank enables members to bypass costly and time-consuming SWIFT payments and instead deposit and withdraw with no fees charged by Xapo Bank. The bank is offering a 1:1 conversion rate from USDC to USD. All USDC deposits at Xapo Bank are automatically converted to USD, meaning members can benefit from a 4.1% annual interest rate return on deposits.
A fully licensed and regulated bank, Xapo Bank is a member of the Gibraltar Deposit Guarantee Scheme (GDGS) and guarantees its members’ USD deposits up to *$100,000 USD equivalent. Ensuring member protection, Xapo Bank does not stake any crypto deposits or have any exposure to surrounding crypto markets as all deposits are automatically converted to USD held by the bank.
Unlike traditional banks, Xapo Bank does not lend and therefore does not rely on fractional reserve banking to make money as its core business model. Instead, Xapo Bank has all its customers’ funds in reserve and invests in short-term liquid assets to pass the interest earned to its customers.
Seamus Rocca, CEO of Xapo Bank, said: “Xapo Bank’s USDC payment rails mark a watershed moment in financial history, combining the speed and cost efficiency of the digital dollar with the security guarantees of a licensed private bank. Enabling auto-converted USDC deposits and withdrawals at Xapo Bank gives crypto members a safe haven for their savings. Running 24/7, including weekends, we eliminate the anxiety of keeping your money in exchanges and the hassle of expensive offramps into traditional banks.”
“Xapo Bank was built to protect members’ savings. Unlike many traditional banks, we do not offer customer loans; all of our customers’ money is held dollar for dollar on our balance sheet. It is invested in very short-dated, highly credit-rated money market instruments and short-term bonds. We pass that benefit to our members through a 4.1% interest rate, paid daily.”
“We charge our members an honest membership fee of $150 USD that helps us recover our overheads and means we don’t have to rely on paying almost no interest to our members or use hidden fees to make money. We give the benefit of more than 80% of the yield we generate back to our members.”
Xapo Bank is constantly striving to grow its payment rails options, offering members additional currency choices managed with the security of a fully-regulated bank. The USDC news comes after last week’s announcement that Xapo Bank had integrated with the Faster Payment System (FPS) to activate support for GBP settlement for account deposits and withdrawals. Earlier this month, the bank also announced an integration with Bitcoin’s Lightning Network, in collaboration with Lightspark.
*Xapo offers 4.1% interest on US dollar deposits, which are protected by the GDGS up to €100,000 EUR (i.e. circa $106,673 at current exchange rates).
Xapo Bank is a leading Bitcoin custodian and a fully licensed private bank. Founded in 2013, Xapo became one of the most trusted Bitcoin custodians in the industry, providing users with a secure platform to store and transact with their cryptocurrency. Evolving into Xapo Bank, it became the first crypto company in the world to obtain a banking license and has since expanded its offerings to include Savings accounts. It has future ambitions of offering Wealth Management and a full suite of private banking services like secured lending and asset protection among its future ambitions. With this expansion, Xapo is poised to become one of the leading private banks in the world, offering clients a level of security, privacy, and flexibility that is unmatched in the traditional banking industry.
About Circle
Circle is a global financial technology firm that enables businesses of all sizes to harness the power of digital currencies and public blockchains for payments, commerce and financial applications worldwide. Circle is powering always-on internet-native commerce, payments, and custody and is the issuer of USDC and EUROC. Circle’s open and programmable platform and APIs make it easy for organisations both large and small to run their internet-scale business, whether it is managing their internal treasury, making international payments, or automating supply chains. Learn more at https://circle.com
About Faster Payments
The Faster Payments Service (FPS) is a secure payments network that allows banks in the UK to send payments faster. It works by allowing banks on the network to electronically and securely transfer money between each other, with near-instant availability of funds. It is available 24 hours a day, 365 days a year. FPS’s benefits include faster processing time for payments, reduced costs and increased customer satisfaction.
About Lightning Network
The Lightning Network is a decentralised network on the Bitcoin blockchain that enables instant, low-cost payments across a network of participants. The Lightning protocol makes use of the security and liquidity of the Bitcoin network to create a secure network of participants who are able to transact bitcoin at high volume and high speed with low cost and instant settlement.
The Securities Commission Malaysia (SC) is pleased to announce the release of its Annual Report 2022 (AR 2022), the Audit Oversight Board Annual Report 2022 (AOB Report 2022), and the inaugural Capital Market Stability Review 2022 (CMSR 2022).
The SC Chairman, Dato’ Seri Dr. Awang Adek Hussin, said the Malaysian capital market remained orderly and continued to finance the economy, with total funds raised hitting a record high of RM179.4 billion. This exceeded the 5-year pre-pandemic average of RM121.4 billion.
The 2022 performance, led by a record amount of corporate bond and sukuk issuances, was achieved despite increased global market volatility and headwinds. Globally, the capital market registered weaker performance in 2022 with the continued tightening of financial conditions in major markets, inflationary pressures, and the repercussions of the Ukraine war.
Dato’ Seri Dr. Awang Adek said the continued resiliency of the Malaysian capital market highlighted the value of exercising prudence and shared accountability while capitalising on growth prospects that arise. “This approach allows the market to better manage risks, preserves overall financial resilience and stability, and supports economic growth,” he said.
AR 2022 highlights the SC’s efforts in promoting market integrity, investor protection, and the development of the Malaysian capital market. This ensured the capital market’s role in financing sustainable development, while facilitating continued innovation to address emerging risks and challenges.
Among the key highlights outlined in AR 2022 are:
Equity crowdfunding (ECF) and peer-to-peer financing (P2P) platforms continue to facilitate the funding needs of micro, small and medium enterprises (MSMEs), with the total funds raised recording an increase of 26% from RM1.4 billion in 2021 to RM1.7 billion in 2022. Since their inception, ECF and P2P have helped 7,218 MSMEs raise over RM4.4 billion.
The Islamic capital market (ICM) comprising total sukuk outstanding and Shariah-compliant equity market capitalisation, saw a marginal increase by 0.6% compared to the previous year. The ICM has increased at a compound annual growth rate (CAGR) of 4.2%, driven by the increase in total sukuk outstanding (9.3% p.a) while Shariah-compliant equities remained relative flat (0.1% p.a.). Ongoing efforts to broaden and deepen the ICM were made, including the issuance of the Guidelines on Islamic Capital Market Products and Services to facilitate efficient access to the ICM ecosystem.
The capital market continues to prioritise good corporate governance and sustainability practices. As of 1 March 2023, 30% of the top 100 public listed companies (PLCs) are led by women, and all top 100 PLCs have at least one-woman director on the board.
To address scams and unlicensed activities, the SC had established an internal task force. The establishment of an internal task force is a proactive measure to ensure that such activities are identified and dealt with in a timely manner. In 2022, 185 websites were blocked and 304 new entries were added to the SC’s Investor Alert List, compared to 143 websites and 134 new entries in 2021.
In 2022, the SC took criminal and civil actions related to various serious breaches such as disclosure breaches, securities fraud and unlicensed activities which resulted amongst others, numerous criminal convictions and RM12.9 million in total fines.
Three Special Feature articles are published in AR 2022:
Towards Greater Investor Protection: Understanding Investors’ Vulnerabilities
Reinvigorating Capital Formation for Sustainable Economic Development
Behavioural Insights to Address Retirement Savings Inadequacy.
Audit Oversight Board Annual Report 2022
During the year, the AOB inspected 56 audit engagements carried out by 52 individual auditors from 21 Audit Firms. On an annual basis, the AOB inspects the Major Audit Firms which collectively audit PLCs that represent 73.5% of the total number of PLCs and 95.3% of the total market capitalisations of PLCs in Malaysia. In 2022, the AOB also conducted targeted inspections aimed at responding to emerging risks in a timely manner.
Highlights of the AOB Report 2022 include:
The AOB continues with its supervisory rigour by leveraging data analytics to identify key risks and specific areas of concern in the market. The number of audit firms inspected during the year increased by 50%.
To strengthen the oversight role of Audit Committees (ACs), the AOB engaged with 973 ACs from 773 PLCs through its ‘Conversation with Audit Committees’ session. The AOB strongly believes effective oversight by strong, knowledgeable, and independent ACs of PLCs can enhance audit quality.
In 2022, the AOB engaged with 84 senior partners of AOB-registered audit firms to understand the challenges faced by the profession and ensure that timely regulatory measures are put in place to improve audit quality.
To strengthen the audit profession’s capabilities, the AOB and the Malaysian Institute of Certified Public Accountants (MICPA) held workshops to assist audit firms with the implementation of the International Standards on Quality Management, which became effective on 15 December 2022. These workshops provided practical examples of how audit firms should design their quality management systems based on the nature and circumstances of the firm and the engagements they perform.
During the year, the AOB took six enforcement actions against auditors for breaching the relevant auditing and ethical standards. The actions included prohibitions and monetary penalties totaling RM383,500.
The AOB’s enforcement actions are subjected to Judicial Reviews by the auditors and the AOB has managed to successfully defend its actions in the Courts thus far. During the year, the Federal Court unanimously ruled in favour of the SC and the AOB in respect of a Judicial Review initiated by aggrieved auditors. The decision further reinforces the robustness of the AOB’s enforcement framework.
Capital Market Stability Review 2022
The CMSR, which outlines overall risk assessments on various components of the Malaysian capital market, revealed that, while the domestic market continued to be affected by the confluence of global and local factors, it was able to operate in a fair and orderly manner, with no systemic stability concerns observed.
Key observations from the report include:
Domestic equity market was impacted by global volatility which affected market sentiment amid healthy local retail and foreign investor participation.
Liquidity in equities continued to be supported by both local and foreign investors.
Corporate bond default rate remained low.
Fund managers had in place robust liquidity risk management processes to ensure sufficient liquidity to manage potential increase in redemption.
For PLCs, most sectors recorded higher earnings in 2022
In the digital asset space, average trading value has declined and domestic digital assets remain small compared to the equity market.
Moving Forward
Dato’ Seri Dr. Awang Adek said some of the areas of focus in 2023 include regulatory reforms, enhancing the fundraising ecosystem, advancement of the ESG agenda, facilitation of technology adoption and improving of corporate governance.
The SC will also prioritise sustainability and talent development to ensure the capital market continues to contribute to broader social and environmental goals.
“As we look towards the future, the SC remains committed to pursuing initiatives that will further strengthen Malaysia’s capital market, and enhance its role as a catalyst for economic growth and development,” he said.
The Securities Commission Malaysia (SC), a statutory body reporting to the Minister of Finance, was established under the Securities Commission Malaysia Act 1993. It is the sole regulatory agency for the regulation and development of capital markets. The SC has direct responsibility for supervising and monitoring the activities of market institutions, including the exchanges and clearing houses, and regulating all persons licensed under the Capital Markets and Services Act 2007. More information about the SC is available on its website at www.sc.com.my. Follow the SC on twitter at @SecComMy for more updates.
Standard Chartered Saadiq held its inaugural Islamic Financial Markets Forum recently, in conjunction with its 30th anniversary of Islamic banking.
Having hosted more than a hundred participants from the financial services industry, the forum aimed to create a platform for key industry practitioners and regulators to share ideas and views to bring about greater understanding on Islamic banking and finance. As a leading international Islamic bank, Standard Chartered Saadiq offers a comprehensive Shariah-compliant product suite and an unmatched Islamic network spanning Asia, Africa and the Middle East.
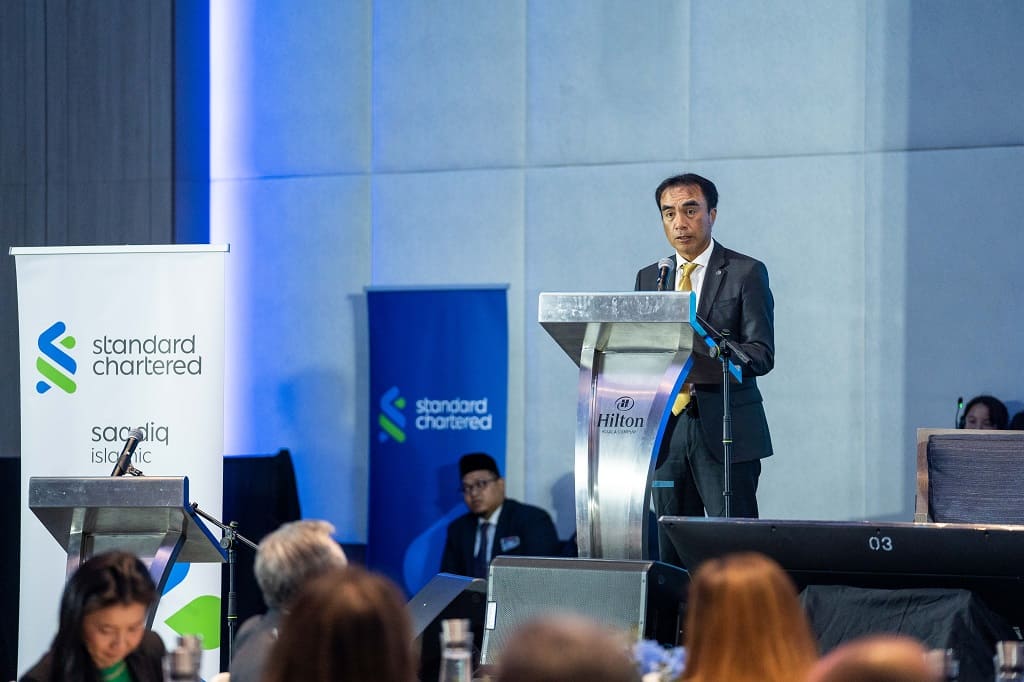
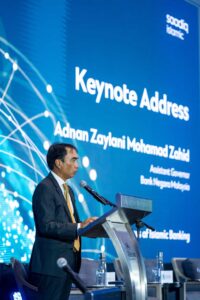
During his keynote address, Bank Negara Malaysia Assistant Governor Adnan Zaylani Mohamad Zahid (pictured) spoke on the importance of advancing the Islamic finance market through thought leadership and innovation, “Islamic finance remains a top priority in the Financial Sector Blueprint to strengthen Malaysia’s value proposition as an international gateway for Islamic finance.”
“The outlook for the Malaysian Islamic financial market in the next five to 10 years is generally positive, pointing towards continued growth and development as well as Malaysia remaining as a major global Islamic financial centre.”
“With the growing maturity of the Islamic financial sector in Malaysia, Bank Negara Malaysia also believes that the industry is now well positioned to drive the broader Malaysia as an Islamic Financial Centre (MIFC) agenda. The MIFC Leadership Council, a joint initiative of Bank Negara Malaysia and the Securities Commission Malaysia will provide thought leadership, and drive strategy formulation and implementation to enhance Malaysia’s position as an international gateway for Islamic finance. It is envisioned that the Council will also evolve into a fully industry-led structure that will be better able to respond to – and capitalise on – global opportunities in Islamic finance. We are confident that with stronger industry stewardship, we will be able to foster greater market dynamism and growth.”
However, he added, “The Islamic finance sector indeed still has some way to reach its full potential based on these values to fulfil contemporary economic and social needs.”
“Therefore, new initiatives are needed to empower and advance the Islamic finance system by emphasising on the principle of driving growth, wider participation, and equitable wealth distribution, and not only focused on company and conglomerate profits.”
The full text of Bank Negara Malaysia Assistant Governor Adnan Zaylani Mohamad Zahid’s keynote address during the Standard Chartered Islamic Financial Markets Forum 2023 can be found here.
Standard Chartered Malaysia
Standard Chartered Bank, a member of the Standard Chartered Group, was established in Malaysia in 1875. As Malaysia’s first bank, Standard Chartered leads the way through product innovation, consistent and strong growth performance and sustainability initiatives. The Bank provides a comprehensive range of financial solutions to corporates, institutions and individuals through its network of branches across Malaysia. The Bank has an Islamic banking subsidiary, Standard Chartered Saadiq; a global shared services centre, Standard Chartered Global Business Services; a sales arm, Price Solutions and an offshore facility in Labuan. Standard Chartered employs over 7,000 employees in all its Malaysian operations.
Standard Chartered
We are a leading international banking group, with a presence in 59 of the world’s most dynamic markets, and serve clients in a further 64. Our purpose is to drive commerce and prosperity through our unique diversity, and our heritage and values are expressed in our brand promise, here for good.
Standard Chartered PLC is listed on the London and Hong Kong Stock Exchanges.
After a tough year for equity and bond investors in 2022, investment opportunities are starting to emerge with markets beyond the US looking more and more compelling. Asia is a diverse region with many different economies, of which each market is in its economic cycle. This means that selectivity in terms of markets and sectors is key.
In particular, we believe three main factors are steering the Asia Pacific (APAC) investment markets in 2023:
China’s reopening and potential growth;
Recessionary risks in developed markets; and
US dollar strength moderates.
Service-Driven Recovery To Support Growth As Mainland China Reopens
Early indications are that mobility and economic activity have started to rapidly normalise following the easing of Covid restrictions in mainland China. For instance, we have already seen a strong uptick in travel activities within and from mainland China. The return of holidaymakers is expected to bring about positive knock-on effects to various sectors around the region, with companies from the hotel, casino, airlines, as well as consumer discretionary retail industries set to benefit. The release of pent-up demand may also appear in the form of “revenge spending” and the impact may funnel to property companies that own shopping malls.
In contrast with much of the world, inflation is not a concern for mainland China. The headline rate was 1.8% year-on-year in December 2022, below the 3% target rate. Low inflationary pressure has given the People’s Bank of China the room to cut its policy rate and the loan prime rate over the past year.
Separately, since the fourth quarter of 2022, government authorities have started to lend support to the domestic real estate market with an aim to encourage healthy development within the sector. Besides rolling out measures to ensure a timely delivery of presold homes, different governmental bodies have introduced coordinated policies to expand financing channels for stressed private property developers to ease their financial pressure.
Since the economic outlook for mainland China has clearly improved, its service-driven recovery could drive GDP growth of 6.2% in 2023 and 4.5% in 2024. With China’s sheer size, stronger economic activity may mechanistically lift the overall GDP in Asia, and the overall growth globally (forecasted at 1.9%. for 2023).
Recessionary Risk In Developed Markets Could Mean Opportunities For Asia
Although our latest forecast has pointed to a less pessimistic outlook, uncertainties over growth and inflation in the US and other developed markets persist.
We continue to believe that the US is heading towards a recession in the second half of 2023 due to tighter monetary policy, even though the degree will not be as grim as previously thought. While we expect the US Federal Reserve (Fed) to continue its rate hiking cycle in 2023, the pace would be more moderate for rates to reach a trough of 3.25% by mid-2024.
After a prolonged period of strong execution, underlying US margins are now at record levels. As negative operating leverage kicks in, companies may feel pressure on their earnings, which may lead the Asia Pacific investment markets to outperform.
Elsewhere, in the UK, a recession is also still on the cards as higher inflation and interest rates, along with austere fiscal policy, dampen the outlook. We expect its economy to see an outright contraction of 0.8% in 2023. Potential risks include high energy costs, labour shortages and disruption to supply chains. Meanwhile, the eurozone economy is likely to be largely stagnant, although it is expected to avoid recession because the relief on household incomes and inflation should fall back more quickly within the year.
Yet, it is not all bad news. Historically, the best opportunities for equities have occurred in the midst of recessions. From a valuation perspective, Asian equities are currently outshining its peers in the West. Improved market sentiment, as well as China’s economic recovery are also likely going to lend support to the markets regionally. These factors combined have led us to hold a more positive view towards Asian investments.
Asian Currencies To Find More Stable Footing As USD Softens
Given the importance of the dollar for global investments, it is important to also look at where the currency is heading. The US dollar has reached its peak and divergence in global central bank policy is likely to put pressure on the currency to depreciate further.
Although there are signs that both headline and core inflation in the US is on a downward trend, its domestic labour market is still tight, which supports restrictive monetary policy for longer. If the Fed shifts to a less aggressive tightening pace and pivots to a pause, there could be some softening in the US dollar. In turn, Asian currencies will be able to find a more stable footing and therefore provide a more favourable environment for Asian bonds, especially those in the local currency space.
The Reserve Bank of Australia raised borrowing costs to a 10-year high in February 2023 and New Zealand’s central bank. On the other hand, the Bank of Korea may be one of the first central banks in APAC to halt its hiking cycle.
For APAC markets that are still in a phase of raising interest rates, it would favour investors to select sectors with a positive correlation to bond yields, such as banks and, in some cases, selected consumer names.
A Flexible Investment Approach Remains Key In Times Of Regime Shift
We are entering a new regime in policy and market behaviour after a 40-year cycle of deflation. With risks associated with the recession, geopolitics, inflationary pressure and the global energy crisis continuing to add to macroeconomic uncertainty, investors will need to change how they value assets, find investment opportunities, and manage risks.
To navigate through market uncertainty, we believe holding safe haven assets such as US Treasuries and cash can help cushion any potential volatility, whilst alternative assets like gold can act as a diversifier.
Nonetheless, taking a flexible approach that accounts for growth and income should help investors build a more resilient portfolio that can shield them from potential headwinds.
By Chloe Shea, Investment Director, Multi-Asset, Schroders