Category: What’s News Asia

Corporate News from Media OutReach Newswire

  • AMAP Platform Showcases Spatial Intelligence at Qwen Conference Thailand 2026

    AMAP Platform Showcases Spatial Intelligence at Qwen Conference Thailand 2026

    BANGKOK, THAILAND – Media OutReach Newswire – 8 September 2026 – On September 4, Qwen Conference Thailand 2026 was held in Bangkok, bringing together industry leaders, developers, AI creators, government organizations, universities, and technology partners to explore advances in AI and the future of AI-powered industries.

    AMAP Platform, Alibaba’s global provider of spatial intelligence and location-based solutions, joined the conference to share its technologies and real-world applications in global location services and spatial intelligence with businesses and developers from Thailand and around the world.

    At the event, AMAP Platform’s Head of Overseas Business presented the company’s global strategy for spatial intelligence and highlighted solutions across key industries, including two-wheeler mobility, logistics and delivery, and travel.

    For two-wheeler mobility, AMAP Platform provides multilingual POI search, motorcycle route planning, restricted-road avoidance, ETA estimation, and navigation, helping businesses deliver smarter and more efficient mobility experiences.

    For logistics and delivery, location services support key stages across the delivery lifecycle, from order planning and delivery operations to network optimization, helping businesses improve delivery efficiency and operational decision-making.

    For travel, multilingual POI search, multimodal route planning, and real-time navigation support a seamless journey from destination discovery to on-the-go navigation.

    AMAP Platform is also expanding spatial intelligence into a broader range of industries, including e-commerce and AIoT. Through standardized, easy-to-integrate location services, AMAP Platform enables businesses worldwide to embed mapping and spatial intelligence into their products and operations, unlocking new opportunities for business growth and AI-powered industry innovation.

    Hashtag: #AMAPPlatform

    The issuer is solely responsible for the content of this announcement.

  • Wuhan takes its cultural showcase abroad at Duisburg China Festival

    Wuhan takes its cultural showcase abroad at Duisburg China Festival

    DUISBURG, GERMANY – Media OutRech Newswire – 8 September 2026 – The 2026 Duisburg China Festival kicked off here on Friday afternoon, with participation from some Chinese and German cities, aimed at strengthening ties between the two countries.

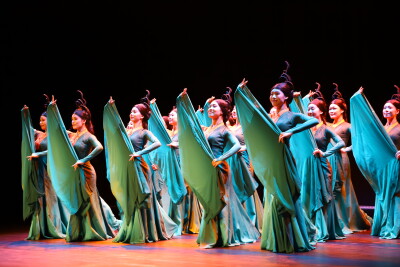
    At the opening gala of the 2026 Duisburg China Festival, artists from the Wuhan Song and Dance Theatre performed the dance piece "White Clouds and Yellow Crane Are My Hometown."
    At the opening gala of the 2026 Duisburg China Festival, artists from the Wuhan Song and Dance Theatre performed the dance piece “White Clouds and Yellow Crane Are My Hometown.”

    The three-day festival features a wide range of cultural booths and interactive zones showcasing traditional Chinese cuisine, culture and contemporary art.

    On Friday evening, top-tier performing arts troupes from Wuhan, capital city of central China’s Hubei Province, jointly staged the festival’s opening gala. Nearly 40 artists presented more than a dozen distinctive programs spanning Peking opera, Hanju opera, Chuju opera, acrobatics, and ethnic song and dance.

    The Duisburg China Festival is a vivid expression of exchange between China and Germany, allowing Germans to experience and understand China up close, said Chang Haitao, acting consul general of the Chinese Consulate General in Dusseldorf.

    In 1982, Duisburg and Wuhan became sister cities, the first of its kind between Germany and China. The two cities have maintained close people-to-people and economic exchanges, forging a bond between them ever since.

    Impressed by the performance of the Chinese artists, Duisburg Mayor Soeren Link said that the opening gala was unforgettable for its standard, quality, richness, and the many different facets it presented.

    Duisburg attaches great importance to its sister-city relationship with Wuhan and hopes to continue strengthening German-Chinese friendship as well as exchange and dialogue between the two sides, said Link.

    Markus Teuber, commissioner for China affairs at the Mayor’s Office of Duisburg, said the rich array of theatrical, song and dance performances brought by Wuhan offered German audiences an excellent window into Chinese culture, and expressed hope that the two cities will continue to deepen cultural exchange in the future.

    For Yang Jing, deputy director of the Wuhan Municipal Bureau of Culture and Tourism, the presence of Wuhan city at the festival “marks an important step in Wuhan culture’s global outreach.”

    The Duisburg China Festival is an annual signature cultural event for the city, injecting fresh grassroots momentum into the development of German-Chinese friendship.

    Hashtag: #DuisburgChinaFestival

    The issuer is solely responsible for the content of this announcement.

  • FEV Consulting recognized by Forbes and Statista as one of the world’s best management consulting firms

    FEV Consulting recognized by Forbes and Statista as one of the world’s best management consulting firms

    AACHEN, GERMANY – Newsaktuell – 8 September 2026 – FEV Consulting has once again been recognized among the world’s leading management consulting firms. The company has been included in the World’s Best Management Consulting Firms 2026 ranking by Forbes and Statista. The recognition highlights FEV Consulting’s international consulting expertise and underscores its successful expansion as a global partner for technology-driven transformation.

    Following its inclusion in Forbes' global rankings in 2022 and 2023, FEV Consulting has once again been recognized by Forbes and Statista in 2026 - earning a place in both the America's Best Management Consulting Firms and World's Best Management Consulting Firms rankings. Source: Forbes / FEV
    Following its inclusion in Forbes’ global rankings in 2022 and 2023, FEV Consulting has once again been recognized by Forbes and Statista in 2026 – earning a place in both the America’s Best Management Consulting Firms and World’s Best Management Consulting Firms rankings. Source: Forbes / FEV

    This latest distinction adds to a series of prestigious international recognitions. Earlier this year, FEV Consulting was also named to the America’s Best Management Consulting Firms 2026 ranking by Forbes and Statista. Previously, the company was included in Forbes’ global rankings in 2022 and 2023. Its renewed inclusion reaffirms FEV Consulting’s position as an internationally recognized management consulting firm.

    “Being recognized once again by Forbes and Statista reinforces our commitment to helping organizations around the world navigate complex transformation with a unique combination of strategic expertise, deep technological understanding, and execution excellence,” said Alexander Nase, Global Managing Director of FEV Consulting.

    FEV Consulting supports organizations worldwide in transforming their business models, products, and operations. The company combines strategic consulting with the deep technology and engineering expertise of the FEV Group, enabling customers to master the defining transformation challenges of our time—from decarbonization, software-defined products, and artificial intelligence to advanced robotics and the development of resilient mobility, energy, and industrial systems.

    FEV Consulting’s approach combines strategic vision with technical feasibility. Clients benefit from consulting services that integrate market, technology, and regulatory expertise with hands-on experience gained from engineering, development, and validation projects. The result is practical, implementation-oriented solutions that deliver measurable business impact.

    The ranking is based on independent surveys of industry experts and clients. Firms are evaluated on criteria including professional expertise, industry knowledge, and client recommendations.

    Press release download: https://fev.group/473fd1
    Hashtag: #FEVConsulting #ManagementConsulting #Forbes

    The issuer is solely responsible for the content of this announcement.

  • HOYA Lens Singapore Launches MiYOSMART iQTF, Advancing Myopia Control for Children

    HOYA Lens Singapore Launches MiYOSMART iQTF, Advancing Myopia Control for Children

    New-generation spectacle lens combines D.I.M.S. Technology with Triple Enhanced Design, with 9 out of 10 children showing no clinically relevant myopia progression* in the first 12 months of wear

    SINGAPORE – Media OutRech Newswire – 8 September 2026 – HOYA Lens Singapore has launched MiYOSMART iQTF, introducing its most advanced myopia control spectacle lens and the latest evolution of its established MiYOSMART platform.

    Newly launched in Singapore, MiYOSMART iQTF builds on MiYOSMART lenses, which feature Defocus Incorporated Multiple Segments (D.I.M.S.) Technology and are clinically proven to slow myopia progression by an average of 60%3. By combining D.I.M.S. Technology with the new Triple Enhanced Design (TED), MiYOSMART iQTF delivers greater myopia control effectiveness for children who need more.

    In a randomised controlled clinical trial (RCT) of 196 schoolchildren in Hong Kong aged 4 to 12 years with myopia, 9 out of 10 children wearing MiYOSMART iQTF showed no clinically relevant myopia progression* in the first 12 months of wear1,2.

    The findings underscore the importance of managing myopia early in childhood, particularly as myopia can progress during a child’s growing years. For parents, identifying and managing myopia early provides an opportunity to address its progression at a critical stage of a child’s development.

    This is particularly important for children who develop myopia at a younger age. The clinical findings for MiYOSMART iQTF demonstrated myopia control efficacy in children as young as four years old for the first time with D.I.M.S. Technology-based spectacle lenses1. The research highlights the potential to manage early-onset myopia at a time when it can progress rapidly and the risk of longer-term impact is highest.

    Myopia control spectacle lenses offer parents a non-invasive option for supporting their children’s myopia management while providing the vision correction they need for everyday activities. MiYOSMART iQTF builds on this approach with an enhanced spectacle lens design developed specifically to deliver stronger myopia control outcomes.

    “At HOYA Vision Care, we imagine a world without myopia. This milestone is truly a generational leap in myopia control and represents an important step toward the vision we are committed to shaping for children around the world. Until today, no trial conducted on a myopia control spectacle lens has shown this level of effectiveness in controlling the condition,” said John Goltermann Lassen, CEO of HOYA Vision Care.

    “Our mission is to improve life through vision by continuously raising the standard of care in myopia control, ensuring that thoughtful innovation and craftsmanship translate into meaningful clinical benefits for children and support eye care professionals’ practice.”

    Triple Enhanced Design (TED): Activated, Powerful and Extended

    MiYOSMART iQTF builds on D.I.M.S. Technology with Triple Enhanced Design (TED), featuring three key enhancements designed to drive greater myopia control effectiveness in children2:

    Activated: Defocus segments are positioned closer to the geometric centre of the spectacle lens and are intended to continuously activate a “sweet spot”4 on the near-peripheral retina — referred to by HOYA as the Smart Zone — identified by several studies as highly responsive to the myopic defocus signal that regulates myopia progression5,6.

    Powerful: Higher defocus power delivers a stronger myopic defocus signal.

    Extended: An extended treatment zone provides more extensive coverage of the child’s peripheral visual field, even with larger frames.

    These enhancements build on the established D.I.M.S. Technology platform, with MiYOSMART iQTF representing the most advanced evolution of MiYOSMART, a technology backed by more than 100 peer-reviewed scientific publications7.

    Options for Different Needs and Lifestyles

    MiYOSMART iQTF is available in four options:

    • Clear
    • Clear with HOYA Full Control Coating
    • Chameleon Photochromic
    • Chameleon Photochromic with HOYA Full Control Coating

    The Chameleon Photochromic options adapt to changing light conditions, darkening in sunlight to help reduce glare and fading back to clear indoors. This supports visual comfort as children move between classroom learning and outdoor activities, while providing protection against UV rays.

    For added protection, HOYA Full Control Coating combines anti-reflective and scratch-resistant properties with blue light reduction, UV protection and an antibacterial treatment that helps limit bacterial growth on lens surfaces. Its water-, dirt- and dust-repellent properties also make the lenses easier to maintain during everyday wear.

    With the introduction of MiYOSMART iQTF in Singapore, HOYA Vision Care continues to advance its myopia control portfolio through research, clinical evidence and spectacle lens innovation designed to support children and eye care professionals.

    Learn more about MiYOSMART iQTF: https://www.hoyavision.com/sg/vision-products/myopia-management/miyosmart-iq/
    Find an eyecare practitioner: https://www.hoyavision.com/sg/find-eye-care-practitioner/

    Hear what other parents say about MiYOSMART: https://miyosmart.com.sg/

    END-

    References:

    *Outcomes for myopic children aged 4 to 12 years and may vary per age group and other parameters at the start of MiYOSMART iQTF treatment. Clinically relevant myopia progression is a change in cycloplegic spherical equivalent refraction of ≥-0.50D.

    “Smart Zone” is a marketing term used by HOYA when referring to a near-peripheral retinal zone shown to respond to myopic defocus. It is not a standard clinical or scientific term.

    1. Tse D.Y., Hon Y., Chun R. K., Leung T. W., Leung D. K. Y., To C. H., Lam C SY. Myopia Control Efficacy of Defocus Incorporated Multiple Segments Spectacle lens with Triple Enhanced Design: 12-month randomized controlled trial. Abstract 2523, ARVO 2026 Annual Meeting, Denver, USA. https://eppro02.ativ.me/web/index.php?page=IntHtml&project=ARVO26&id=4486941 (accessed date 03.04.2026).
    2. HOYA data on file. HOYA MiYOSMART iQTF spectacle lens clinical outcomes. 04/2026.
    3. Myopia progression (SER) by 59% and axial elongation (AL) decreased by 60% compared with those wearing SV lenses.Lam CSY, Tang WC, Tse DY, Lee RPK, Chun RKM, Hasegawa K, Qi H, Hatanaka T, To CH. Defocus Incorporated Multiple Segments (DIMS) spectacle lenses slow myopia progression: a 2-year randomised clinical trial. British Journal of Ophthalmology. Published Online First: 29 May 2019.
    4. Swiatczak B, et al. Retinal “sweet spot” for myopia treatment. Sci Rep. 2024;14:26773.
    5. HOYA data on file. MiYOSMART spectacle lens commercial data. 04/2026.
    6. Smith III EL, Arumugam B, Hung LF, et al. Eccentricity-dependent effects of simultaneous competing defocus on emmetropization in infant rhesus monkeys. Vision Res. 2020;177:32-40. DOI: 10.1016/j.visres. 2020.08.003.
    7. HOYA Vision Care. Confidence Through Evidence. 2026. Available from: https://www.hoyavision.com/vision-products/miyosmart/evidences/. (Accessed: 16.04.2026).

    Hashtag: #visioncare #myopia #HOYAvisioncare #myopiasingapore #childmyopia

    The issuer is solely responsible for the content of this announcement.

    HOYA Vision Care

    For over 60 years, HOYA Vision Care has been a global leader in the eyeglass lens industry. The company is dedicated to providing innovative vision care solutions for every stage of a patient’s life. With a presence in over 50 countries, HOYA Vision Care has a leading position in myopia management category and a proven expertise in advanced lens designs, high performance photochromic technologies and high-quality AR coatings. HOYA Vision Care’s solid market portfolio includes HOYA, Vision Ease, SEIKO and PENTAX optical lenses, as well as innovative products such as MiYOSMART myopia control lenses for children, Hoyalux iD MySelf individualized progressive lenses and the Sensity range of photochromic lenses. The company employs over 20,000 employees worldwide with large scale production facilities in Asia, Europe, and the US and 38 local Rx laboratories globally. For more information, please visit

    About HOYA Corporation

    Founded in 1941 in Tokyo, Japan, HOYA is a global technology and med-tech company, and a leading supplier of innovative high-tech and medical products. HOYA is active in the fields of healthcare and information technology, providing eyeglasses, medical endoscopes, intraocular lenses, optical lenses, as well as key components for semiconductor devices, LCD panels and HDDs. With over 150 offices and subsidiaries worldwide, HOYA currently employs a multinational workforce of over 35,000 people. For more information, please visit

  • TP named Frost & Sullivan’s 2026 Asia-Pacific Company of the Year in Customer Experience Management Services

    TP named Frost & Sullivan’s 2026 Asia-Pacific Company of the Year in Customer Experience Management Services

    SINGAPORE – Media OutReach Newswire – 8 September 2026 – Global digital business services leader TP (ex-Teleperformance) has been named Frost & Sullivan’s 2026 Asia-Pacific Company of the Year in Customer Experience Management Services, the analyst firm’s top honor recognizing the market participant that exemplifies visionary innovation, market-leading performance and customer care. TP was recognized for combining AI orchestration, operational discipline, and measurable customer impact across Asia-Pacific.

    TP named Frost & Sullivan's 2026 Asia-Pacific Company of the Year in Customer Experience Management Services

    Frost & Sullivan credited TP’s ability to move AI from experimentation into live operations, which Frost identified as one of the most urgent gaps in the industry. TP applies AI across the service delivery lifecycle to help teams become productive faster and improve service quality at scale. This starts with AI-enabled recruitment and onboarding, extends into simulation-based training that helps customer experts build proficiency before handling live interactions, and continues through workforce management and AI-assisted coaching. In quality assurance, TP now reviews every transaction rather than the small sample the industry has traditionally relied on, sharpening coaching precision, compliance visibility and operational learning.

    “As AI becomes embedded into customer operations, enterprises need outcome-based models that orchestrate AI and human agents to improve productivity and deliver measurable business value,” said Dave Rizzo, President and CEO, APAC, TP. “TP designs workflows that use AI to elevate human work, while linking productivity gains to the business outcomes clients want to achieve. Being named Frost & Sullivan’s Asia-Pacific Company of the Year recognizes the progress we are making in delivering that transformation for clients across the region.”

    Frost & Sullivan highlighted TP’s work with a major hospitality brand in Singapore as an example of this approach in practice. The engagement went beyond operational delivery to integrate technology across legacy and modern systems, while also implementing an AI-enabled knowledge platform that delivers trusted, context-aware answers to customer inquiries across multiple operational teams and lines of business. Together, these capabilities supported a broader redesign of the service infrastructure behind a high-touch, premium customer experience. Beyond individual client engagements, TP’s operations across Asia-Pacific play a dual role in TP’s strategy as both a delivery engine and a business development engine in a high-growth demand market. Frost & Sullivan noted that TP’s regional footprint enables it to respond to different language, regulatory, cultural, and operational requirements.

    “The company’s centers of excellence in Asia-Pacific contribute to the development of solutions across AI, machine learning, natural language processing, analytics, and automation. This gives the region a role beyond labor delivery. It becomes a capability engine for global transformation,” said Krishna Baidya, Vice President, ICT Practice, Frost & Sullivan.

    Frost & Sullivan also highlighted TP’s approach to reframing the traditional onshore-versus-offshore debate. Across Asia-Pacific, TP supports offshore, nearshore, onshore and hybrid delivery models, using technology and local market capabilities to balance cost efficiency, service quality, language requirements and regulatory needs. This flexibility allows TP to tailor delivery models to the realities of individual markets rather than relying on a single approach.

    With operations in close to 100 countries and services spanning more than 170 markets, TP combines global scale with regional delivery depth, technology and human expertise. Across Asia-Pacific, this is translating into measurable outcomes, including an agentic triage use case that reduced referral-to-booking turnaround from approximately 24 hours to minutes while improving booking conversion. The recognition reflects how TP is evolving its digital business services for the next phase of AI-enabled transformation while keeping human oversight, empathy, judgment and relationships central to the service model.

    Hashtag: #TP


    The issuer is solely responsible for the content of this announcement.

    AboutTP in SINGAPORE

    TP in Singapore is part of the , a global leader in digital business services which consistently seeks to blend the best of advanced technology with human empathy to deliver enhanced customer care that is simpler, faster, and safer for the world’s biggest brands and their customers. The Group’s comprehensive, AI-powered service portfolio ranges from front office customer care to back-office functions, including high-value digital transformation services, collections and operations consulting. It also offers a range of specialized services such as interpreting and localization, visa and consular services, and recruitment process outsourcing services. The teams of multilingual, inspired, and passionate experts and advisors, spread in close to 100 countries, as well as the Group’s local presence allows it to be a force of good in supporting communities, clients, and the environment.

    For more information: .

  • MAYFEYR Launches MAYFEYR Mirror, Bringing Designer Fashion to Life

    MAYFEYR Launches MAYFEYR Mirror, Bringing Designer Fashion to Life

    The AI-powered experience brings designer fashion to life, helping shoppers visualise complete looks before making a purchase.

    SINGAPORE – Media OutReach Newswire – 8 September 2026 – MAYFEYR, the Singapore-based online luxury fashion platform, launched MAYFEYR Mirror, an AI-powered styling experience designed to address one of online fashion’s most familiar moments: when a shopper finds a piece they love but isn’t sure how it will look on them. MAYFEYR Mirror was created to help shoppers visualise pieces before making a purchase.

    At launch, MAYFEYR Mirror works across every item available on MAYFEYR, spanning more than 200 luxury brands. Moving beyond static product images, it allows shoppers to see selected pieces as complete looks, helping them explore styling combinations before making a purchase decision.

    MAYFEYR Mirror allows shoppers to:

    • Bring designer pieces to life through immersive visualisation
    • Build complete looks by styling items with complementary accessories
    • Explore different styling scenarios across curated backgrounds and settings
    • See how pieces work together as complete looks
    • Make more confident purchase decisions before checkout

    Luxury purchases are rarely made based on a single product image. Shoppers often consider how a piece could be styled, whether it complements their existing wardrobe, and if it suits the occasion before deciding to buy.

    MAYFEYR Mirror was created to make that decision-making process more intuitive. By moving beyond static product images, it helps shoppers visualise complete looks and explore styling possibilities, making it easier to understand how pieces come together before making a purchase.

    “Luxury shopping has always been about more than simply choosing a product. It’s about imagining how a piece fits into your personal style and your wardrobe and the occasions you’ll wear it. That moment of uncertainty is something every online shopper experiences,” said Kelvin Teo, Founder and CEO of MAYFEYR.

    “With MAYFEYR Mirror, we’re moving beyond static product images by bringing designer pieces to life. Our goal is simple: to make shopping for luxury online feel more intuitive, more immersive and ultimately help shoppers make purchase decisions with greater confidence.”

    MAYFEYR Mirror is initially available to members of the MAYFEYR Insider Circle, MAYFEYR’s community of existing customers, with broader availability planned as the experience continues to evolve.

    The launch marks another step in MAYFEYR’s ambition to build a more intuitive online luxury shopping experience, combining access to brand-new, in-season designer fashion with technology that helps shoppers discover, style and shop with greater confidence.

    Hashtag: #MAYFEYRMirror #LuxuryFashion #DesignerFashion #AIFashion #VirtualStyling #FashionTechnology #SingaporeFashion


    The issuer is solely responsible for the content of this announcement.

    About MAYFEYR

    MAYFEYR is a Singapore-based online luxury fashion platform offering access to brand-new, in-season designer fashion from more than 200 leading European luxury brands. With over 20,000 items available, MAYFEYR helps shoppers discover and purchase authentic luxury fashion with greater convenience and confidence.

    As part of its commitment to reimagining the online luxury shopping experience, MAYFEYR continues to build technology and digital experiences that help shoppers visualise, style and purchase with greater confidence.

    For more information, visit

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    Margin recovery and record earnings underscore the Jollibee Group’s growth momentum, as Jollibee Canada prepares to nearly double its network over five years

    Key Highlights:

    • Record quarterly earnings: Net income attributable to equity holders of the parent company rose 5.7% year over year to Php3.4 billion, or approximately US$55 million, marking the Jollibee Group’s highest quarterly NIAT on record, supported by margin recovery from first-quarter cost pressures and improved operating leverage.
    • Sustained global sales growth: System-wide sales increased 14.2% year over year, driven by continued demand across the Group’s Philippine and international businesses and growth across its global brand portfolio.
    • Strong North American performance: Jollibee North America system-wide sales grew 21.6%, while same-store sales increased 8.6%; Smashburger same-store sales grew 7.0%, underscoring momentum in one of the Group’s key international growth markets.
    • Canada expansion strengthens the North America growth platform: New plans add 26 locations in British Columbia and Edmonton to Jollibee’s existing 28-restaurant Canadian network, positioning the brand to nearly double its Canada footprint over the next five years.
    • Expanding global store network: The Jollibee Group’s store network increased 6.4% year over year to 10,767 stores across 33 countries, with franchised stores accounting for approximately 70% of gross new openings.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, the resilience of its global brand portfolio, continued healthy consumer demand, and positive system-wide sales growth across all regions.

    The Jollibee Group’s system-wide sales increased 14.2% year-on-year, driven by continued demand across its Philippine and international businesses and growth across its global brand portfolio. The Group recorded Php3.4 billion in net income attributable to equity holders of the parent company, its highest quarterly NIAT on record.

    North America continued to deliver strong performance during the quarter. Jollibee’s system-wide sales increased 21.6%, while same-store sales grew 8.6%. Smashburger also delivered 7.0% same-store sales growth, reflecting continued momentum across the Group’s North American portfolio.

    Canada is emerging as an important growth market for Jollibee, with planned expansion in British Columbia and Edmonton set to strengthen the brand’s national footprint. Together, these plans would add 26 restaurants — 16 in British Columbia and 10 in Edmonton — to Jollibee’s existing network of 28 restaurants in Canada.

    If completed as planned, these commitments would nearly double Jollibee’s Canadian network over the next five years, while laying the foundation for further expansion across the country.

    The Jollibee Group’s global store network increased 6.4% year-on-year to 10,767 stores across 33 countries,. Of these, 501 stores were across North America at the end of the second quarter, spanning Jollibee, Chowking, Red Ribbon, Smashburger, Milksha, The Coffee Bean & Tea Leaf, and Tim Ho Wan.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    North America continued to deliver strong performance during the quarter. Jollibee’s North American system-wide sales increased 21.6%, while same-store sales grew 8.6%. Smashburger also delivered 7.0% same-store sales growth, reflecting continued momentum across the Group’s North American portfolio.

    The International segment expanded by 25.4% in system-wide sales, led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee NA grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    Full Year 2026 Guidance

    For full year 2026, the Jollibee Group expects its underlying sales momentum to remain resilient. It is maintaining its guidance for system-wide sales growth of 8%-12% and store network growth of 5%-10%, supported by continued demand across key markets and disciplined execution across its global brand portfolio.

    At the same time, the Jollibee Group is updating certain operating assumptions. Full year same-store sales growth guidance is being revised to 3%-4%, while the gross new store opening target is being updated to 1,000-1,100 stores. Despite the lower gross opening target, the Jollibee Group continues to expect overall store network growth to remain in line with its previous guidance, reflecting ongoing portfolio optimization and the timing of store openings and closures.

    Capital expenditures are now expected to be in the range of Php13.0 billion (approx. US$212 million) to Php15.0 billion (approx. US$244 million). Operating income growth guidance is revised to 10%-15%, reflecting the updated same-store sales assumptions, the revised expansion assumptions, continued transition-related costs for China and Smashburger, and the still-dynamic cost environment.

    The Jollibee Group’s confidence is supported by growth catalysts that provide a stronger foundation for sustained performance over the medium term, including continued international expansion, a growing base in key markets such as North America, and ongoing portfolio optimization initiatives. Recent developments in Canada, Vietnam, and China illustrate the Group’s ability to pursue high-quality growth across markets with different growth profiles and strategic priorities.

    Jollibee Vietnam has emerged as one of the Jollibee Group’s strongest international growth engines, leading the category in sales and ranked as the No. 1 quick-service restaurant brand in Vietnam by Euromonitor International in its Consumer Foodservice 2026 study. In Q2 2026, Jollibee achieved system-wide sales growth of 47.6% and same-store sales growth of 17.9%, supported by disciplined execution and continued network expansion, with 19 new stores opened in the first half of the year. Attractive unit economics, with store payback of less than four years, reinforce confidence in the sustainability of future growth. Its strong market position, operating performance, and customer engagement were further recognized through awards for Best Companies to Work for in Asia 2026 and Best Social & Commerce Integration in Vietnam.

    In China, the franchise ratio has increased significantly to 62% today from 14% in 2016, reflecting continued progress toward a more scalable and asset-light operating model. Its largest brand, Yonghe King, has achieved a franchise ratio of 65% and is targeting 70% by the end of 2026, with a medium-term target of up to 95%. Yonghe King’s new stores typically achieve payback in approximately two years.

    The Jollibee Group remains focused on pursuing high-quality growth opportunities that generate attractive returns on invested capital, with disciplined capital allocation and capital-light expansion continuing to guide its growth strategy.

    Other Developments

    Recognition for Global Brand Influence

    The Jollibee Group was named to TIME’s 100 Most Influential Companies of 2026, where it was recognized as a “fried chicken phenom.” The Company was also included in the inaugural TIME100 Companies: Industry Leaders list as one of the Top 10 companies in the Food & Drink category.

    In July, the Jollibee Group was included in Fortune’s Southeast Asia 500 list, reinforcing its position among the region’s leading companies. Jollibee was also recognized by USA Today as having the Best Fast Food Fried Chicken, further strengthening the brand’s global consumer relevance and reinforcing its leadership in great-tasting food.

    Sustainability and ESG Progress
    The Jollibee Group continued to advance its sustainability agenda and strengthen its ESG initiatives. For the second consecutive year, the Company received the 3G Excellence in Sustainability Reporting Award 2026, recognizing its commitment to transparent and meaningful sustainability disclosures.

    The Company’s Danao commissary was also awarded LEED Gold certification under LEED v4.1 ID+C: Commercial Interiors, becoming the first manufacturing facility in the Philippines to achieve LEED certification for interior design and construction. The recognition reflects the Jollibee Group’s ongoing investment in more sustainable and future-ready operations.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.

    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with affiliates and franchisees operating over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.

    To learn more about Jollibee Group, visit

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Group’s record quarter reflects margin recovery and strong international growth, including 23.0% global system-wide sales growth from Hong Kong-founded Tim Ho Wan.

    Key Highlights:

    • Record quarterly earnings: NIAT increased 5.7% year-on-year to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record.
    • International business accelerates: International system-wide sales increased 25.4%, reflecting broad-based growth across the Group’s global portfolio.
    • Hong Kong-founded Tim Ho Wan sustains global momentum: Tim Ho Wan delivered 23.0% system-wide sales growth globally in Q2, underscoring the continued international relevance of the brand.
    • Expanding global platform: The Jollibee Group’s store network increased 6.4% year-on-year to 10,767 stores across 33 countries, with international stores accounting for the majority of the network.
    • Positive performance across key markets: Same-store sales growth remained positive in several international markets, including North America, Vietnam, and Korea.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, the resilience of its global brand portfolio, continued healthy consumer demand, and positive system-wide sales growth across all regions.

    In Hong Kong, Jollibee continued to expand its presence with 24 stores at the end of the second quarter, while system-wide sales grew 36.6% year-on-year. This formed part of the broader momentum across the Jollibee Group’s international portfolio, which grew 25.4% in system-wide sales during the quarter.

    Among the Group’s international brands, Tim Ho Wan delivered 23.0% system-wide sales growth globally in Q2, underscoring continued momentum for the Hong Kong-founded brand as it expands its international footprint. The brand had 83 stores globally at the end of the second quarter, contributing to the Jollibee Group’s growing international restaurant network.

    The brand’s performance formed part of broader growth across the Group’s International segment, which expanded 25.4% in system-wide sales during the quarter. The segment was led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee North America (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the international business’ system-wide sales (“SWS”).

    The Group’s Philippine business also continued to contribute to overall growth, with system-wide sales increasing 5.7%, supported by Mang Inasal (+10.7%) and Jollibee (+6.6%).

    The Jollibee Group recorded Php3.4 billion (approx. US$55 million) in net income attributable to equity holders of the parent company (NIAT), up 5.7% year-on-year and the highest quarterly NIAT on record. Consolidated revenues increased 10.7% year-on-year, while system-wide sales grew 14.2%.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Global Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    The International segment expanded by 25.4% in system-wide sales, led by Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking, (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%). Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.
    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.
    To learn more about Jollibee Group, visit

  • The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    The Jollibee Group Reports Record Q2 2026 Results, with Margin Recovery from Controlled Pricing and Record-High Quarterly Net Income Attributable to Equity Holders of the Parent Company

    Strong international sales momentum, disciplined pricing, and margin recovery helped drive the Jollibee Group’s record-high quarterly earnings.

    Key Highlights:

    • Record enterprise performance: Jollibee Group delivered record quarterly NIAT of Php3.4 billion, up 5.7% year-on-year, with consolidated revenues rising 10.7% and system-wide sales increasing 14.2%, supported by improving margins and continued business momentum.
    • International business drives growth: International system-wide sales grew 25.4%, reflecting broad-based momentum across the Group’s Asian and global restaurant portfolio, including Highlands Coffee, Compose Coffee, Tim Ho Wan, Jollibee North America, and Milksha.
    • Asia remains a key growth platform: Strong same-store sales growth in Vietnam, Highlands Coffee, and Compose Coffee highlights the continued strength of the Group’s core Asian growth markets.
    • Vietnam emerges as a major growth engine: Jollibee Vietnam delivered 47.6% system-wide sales growth in Q2 and opened 19 new stores in the first half, supported by strong unit economics and continued network expansion.
    • Global footprint continues to expand: The Jollibee Group increased its store network by 6.4% year-on-year to 10,767 stores across 33 countries, with franchised stores comprising approximately 70% of the network.

    METRO MANILA, PHILIPPINES – Media OutRech Newswire – 8 September 2026 – Jollibee Foods Corporation (PSE: JFC) and its subsidiaries (the “Jollibee Group”), today reported record second-quarter earnings for 2026, reflecting a clear margin recovery from first-quarter cost pressures, resilient consumer demand, and continued momentum across its international restaurant portfolio.

    The Jollibee Group’s International segment grew 25.4% in system-wide sales in Q2, led by strong performances from Highlands Coffee (+46.7%), Jolli-K’s Compose Coffee (+39.7%), Europe, Middle East, Asia, and Australia (EMEAA) brands Jollibee and Chowking (+25.3%), Tim Ho Wan (+23.0%), Jollibee NA (+21.6%), and Milksha (+12.4%).

    Growth across key Asian markets was particularly notable. Jollibee Vietnam delivered 17.9% same-store sales growth, while Highlands Coffee grew 11.5% and Compose Coffee grew 12.4%, contributing to the broader momentum of the Group’s International segment.

    The Group’s Philippine business also continued to provide a strong foundation for overall performance, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    The Jollibee Group recorded Php3.4 billion (approx. US$55 million) in net income attributable to equity holders of the parent company (NIAT), up 5.7% year-on-year and the highest quarterly NIAT on record. Consolidated revenues increased 10.7% year-on-year, while system-wide sales grew 14.2%.

    “Our second-quarter results demonstrate the continued strength of the Jollibee Group’s global brand portfolio and the resilience of consumer demand across our key markets,” said Ernesto Tanmantiong, Global Chief Executive Officer of JFC. “We delivered healthy system-wide sales growth across all regions, supported by strong contributions from both our Philippine and international businesses, continued same-store sales growth, and ongoing expansion of our global store network.

    “The breadth of our growth reflects the relevance of our brands, the strength of our value offerings, and the trust that customers continue to place in us. As we expand our presence in key markets and build a stronger global platform, we remain focused on serving more customers, strengthening our brands, and creating sustainable long-term value for our stakeholders.”

    Second Quarter Performance: Sequential Recovery and Sustained Growth

    The Jollibee Group’s second-quarter performance is best understood by first looking at the sequential recovery from Q1 cost pressures, followed by the year-on-year growth that demonstrates the continued strength of the business.

    The discussion below first presents the quarter-on-quarter improvement in revenues, margins, and earnings, then places that recovery in the context of the Jollibee Group’s sustained year-on-year growth across its global portfolio.

    Sequential Recovery: Quarter-on-Quarter Profitability Improvement

    Quarter-on-quarter comparisons demonstrate the strength of the Jollibee Group’s recovery from the first quarter. Consolidated revenues increased by 12.2% versus Q1 2026, supporting a 25.3% increase in gross profit, a 56.1% increase in operating income, and a 130.5% increase in NIAT.

    The margin recovery was also visible within the quarter. Gross profit margin improved to 18.5% in Q2 from 16.5% in Q1 and strengthened from 17.3% in April to 19.0% in June, indicating that the Group’s pricing and recovery actions are gaining traction even as the operating environment remains affected by elevated commodity, logistics, and other supply chain-related costs.

    Operating leverage improved as the quarter progressed. Operating income margin increased to 7.2% in Q2 from 5.2% in Q1, while NIAT margin nearly doubled to 4.0% from 1.9%. By June, operating income margin had reached 9.1% and NIAT margin had reached 6.2%, providing a stronger exit rate entering the second half of 2026.

    Reported profitability for the quarter was affected by Php239.0 million (approx. US$3.9 million) in transition-related costs, covering store closure and lease termination costs associated with the ongoing turnaround of Yonghe King and Smashburger toward predominantly franchised business models. These costs are aligned with the Jollibee Group’s continuing efforts to strengthen the long-term quality, scalability, and profitability of its portfolio.

    Commenting on the Group’s sequential margin recovery and second-quarter earnings momentum, Richard Shin, Global Chief Financial and Risk Officer of JFC and Chief Executive Officer of Jollibee Group International Business, said:

    “The second quarter represents an important step forward in our earnings momentum. Pricing actions implemented beginning in April, together with productivity, sourcing, and cost discipline initiatives, contributed to the recovery in gross profit margins and supported stronger operating income and NIAT margins.

    “Sequentially, gross profit increased by 25.3%, operating income rose by 56.1%, and NIAT more than doubled versus Q1 2026, reflecting both cost recovery and stronger operating leverage from sustained topline growth.

    “These portfolio actions involve near-term transition costs but are expected to support stronger long-term profitability, scalability, and overall portfolio quality.

    “While the operating environment remains dynamic, our second-quarter performance demonstrates our ability to respond decisively, improve profitability, and continue investing for long-term growth. We enter the second half with stronger momentum, a continued focus on sustaining margin recovery, and continued confidence in the long-term growth prospects.”

    Sustained Growth: Year-on-Year Business Momentum

    On a year-on-year basis, consolidated revenues increased 10.7%, while system-wide sales grew 14.2%, underscoring sustained demand across the Jollibee Group’s global brand portfolio.

    Financial Data Quarter 2 (Unaudited) 1H 2026 (Unaudited)
    2026 2025 % Change 2026 2025 % Change
    System Wide Sales 130,809 (~$2,132) 114,542 (~$1,867) 14.2 244,673 (~$3,987) 217,738 (~$3,549) 12.4
    Revenues 85,908 (~$1,400) 77,626 (~$1,265) 10.7 162,455 (~$2,648) 147,852 (~$2,410) 9.9
    Operating Income 6,165 (~$100) 6,058 (~$99) 1.8 10,112 (~$165) 10,882 (~$177) (7.1)
    EBITDA 11,995 (~$195) 11,174 (~$182) 7.3 21,303 (~$347) 20,964 (~$342) 1.6
    Net Income 3,519 (~$57) 3,416 (~$56) 3.0 4,928 (~$80) 5,914 (~$96) (16.7)
    Net Income Attributable to Equity Holders of the Parent Company 3,395 (~$55) 3,211 (~$52) 5.7 4,867 (~$79) 5,617 (~$92) (13.3)
    Earnings Per Share – Basic 2.949 (~$0.048) 2.788 (~$0.045) 5.8 4.183 (~$0.068) 4.857 (~$0.079) (13.9)
    Earnings Per Share – Diluted 2.955 (~$0.048) 2.780 (~$0.045) 6.3 4.191 (~$0.068) 4.843 (~$0.079) (13.5)

    Note: (1) Amounts in Million Pesos except for per-share data
    (2) Systemwide sales (SWS) is a management metric and is not part of the audited financial statements
    (3) US$ amounts are presented for informational purposes using the exchange rate of PHP 61.36/US$1, applied consistently to comparative periods for comparability.

    The International segment expanded by 25.4% in system-wide sales, reflecting broad-based growth across the Jollibee Group’s international portfolio. Shabu All Day, the Jollibee Group’s newest Korea-based brand under Jolli-K, contributed 5% to the International business’ SWS.

    Asian markets continued to deliver strong performance during the quarter. Jollibee Vietnam grew 17.9% in same-store sales, while Highlands Coffee grew 11.5% and Compose Coffee grew 12.4%. These results contributed to the broader momentum of the Group’s International segment.

    The Philippine business also delivered continued growth, with system-wide sales increasing 5.7%, supported by strong contributions from Mang Inasal (+10.7%) and Jollibee (+6.6%).

    SSSG for the quarter grew 2.7%, with the Philippine business up 1.3% and the international business up 4.4%. In the Philippines, SSSG growth was mainly supported by higher spend per transaction. While traffic was affected by a strong prior-year base that benefited from election-related spending, trends improved over the course of the quarter, reaching broadly flat levels in June.

    Several international markets delivered positive performance during the quarter, particularly North America, where Jollibee grew 8.6% and Smashburger grew 7.0%; Vietnam, where Jollibee grew 17.9% and Highlands Coffee grew 11.5%; and Korea, where Compose Coffee grew 12.4%.

    Operating income increased year-on-year, supported by higher revenues and the initial benefits of pricing and margin recovery actions implemented during the quarter. NIAT rose by 5.7% to Php3.4 billion (approx. US$55 million), the highest quarterly NIAT on record, while earnings per share increased by 5.8% to Php2.949 (approx. US$0.048), reflecting the Group’s stronger bottom-line performance.

    EBITDA increased by 7.3% year-on-year, driven by the Philippine business, where EBITDA grew by 12.8%, partly offset by a 0.4% decline in International EBITDA. The decline in International EBITDA was impacted by store closure and lease termination costs related to Smashburger and Yonghe King.

    JFC increased its global store network by 6.4% year-on-year to 10,767 stores. This reflected 461 gross new store openings and the addition of 172 stores from the acquisition of Shabu All Day, partly offset by 207 store closures during the first half.

    Of the gross new store openings, 323 stores, or approximately 70%, were franchised, keeping the Group’s franchised ratio at 70%. The total store network comprised 3,516 stores in the Philippines and 7,251 stores internationally, including 602 in China, 340 in North America, 455 in EMEAA, 1,062 under Highlands Coffee mainly in Vietnam, 1,097 under CBTL, 358 under Milksha, 3,098 under Compose Coffee, 156 under Shabu All Day, and 83 under Tim Ho Wan.

    Full Year 2026 Guidance

    The Jollibee Group’s confidence is supported by growth catalysts that provide a stronger foundation for sustained performance over the medium term, including continued international expansion, a growing base of committed franchisees in key markets such as North America, and ongoing portfolio optimization initiatives. Recent developments in Vietnam and China illustrate the Group’s ability to pursue high-quality growth across markets with different growth profiles and strategic priorities.

    Jollibee Vietnam has emerged as one of the Jollibee Group’s strongest international growth engines, leading the category in sales and ranked as the No. 1 quick-service restaurant brand in Vietnam by Euromonitor International in its Consumer Foodservice 2026 study. In Q2 2026, Jollibee achieved 47.6% system-wide sales growth and 17.9% same-store sales growth, supported by disciplined execution and continued network expansion, with 19 new stores opened in the first half of the year. Attractive unit economics, with store payback of less than four years, reinforce confidence in the sustainability of future growth.

    In North America, Jollibee recently signed its first multi-unit development agreement in British Columbia, following a 10-store development agreement for the Edmonton market. Together, these agreements add 26 committed franchise locations to Jollibee’s existing Canadian network and are expected to nearly double the brand’s Canadian footprint over the next five years if completed as planned. The developments also provide a foundation for further expansion across the country.

    In China, Jollibee Group’s franchise ratio, comprising Yonghe King, Hong Zhuang Yuan, Jollibee Hong Kong, and Jollibee Macau, has increased significantly to 62% today from 14% in 2016, reflecting continued progress toward a more scalable and asset-light operating model. Its largest brand, Yonghe King, has achieved a franchise ratio of 65% and is targeting 70% by the end of 2026, with a medium-term target of up to 95%. Yonghe King’s new stores typically achieve payback in approximately two years.

    The Jollibee Group remains focused on pursuing high-quality growth opportunities that generate attractive returns on invested capital, with disciplined capital allocation and capital-light expansion continuing to guide its growth strategy.

    Other Developments

    Recognition for Global Brand Influence

    The Jollibee Group was named to TIME’s 100 Most Influential Companies of 2026, where it was recognized as a “fried chicken phenom.” The Company was also included in the inaugural TIME100 Companies: Industry Leaders list as one of the Top 10 companies in the Food & Drink category.

    In July, the Jollibee Group was included in Fortune’s Southeast Asia 500 list, reinforcing its position among the region’s leading companies. Jollibee was also recognized by USA Today as having the Best Fast Food Fried Chicken, further strengthening the brand’s global consumer relevance and reinforcing its leadership in great-tasting food.

    Sustainability and ESG Progress

    The Jollibee Group continued to advance its sustainability agenda and strengthen its ESG initiatives. For the second consecutive year, the Company received the 3G Excellence in Sustainability Reporting Award 2026, recognizing its commitment to transparent and meaningful sustainability disclosures.

    The Company’s Danao commissary was also awarded LEED Gold certification under LEED v4.1 ID+C: Commercial Interiors, becoming the first manufacturing facility in the Philippines to achieve LEED certification for interior design and construction. The recognition reflects the Jollibee Group’s ongoing investment in more sustainable and future-ready operations.

    ~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

    Forward-Looking Statement Disclaimer

    The foregoing disclosure contains forward-looking statements that are based on certain assumptions of Management and are subject to risks, opportunities, and unforeseen events. Actual results could differ materially from those contemplated in the relevant forward-looking statement, and JFC gives no assurance that such forward-looking statements will prove to be correct, or that such intentions will not change. This press release discloses important factors that could cause actual results to differ materially from JFC’s expectations. All subsequent written and oral forward-looking statements attributable to JFC, or any person acting on behalf of JFC, are expressly qualified in their entirety by the above cautionary statements.

    Hashtag: #JollibeeGroup

    The issuer is solely responsible for the content of this announcement.

    About Jollibee Group

    Jollibee Foods Corporation (PSE: JFC) (the “Company”) is one of the world’s fastest-growing restaurant companies, driven by its purpose of spreading joy through superior taste. It manages and operates a portfolio that includes 20 brands (the “Jollibee Group”) with over 10,700 stores and cafés across 33 countries.

    The Jollibee Group’s portfolio includes nine (9) wholly-owned brands (Jollibee, Chowking, Greenwich, Red Ribbon, Mang Inasal, Yonghe King, Hong Zhuang Yuan, Smashburger and Tim Ho Wan), five (5) franchised brands (Burger King, Panda Express, Yoshinoya, Common Man Coffee Roasters, and Tiong Bahru Bakery in the Philippines), and ownership stakes in other key brands like The Coffee Bean and Tea Leaf (80%), Compose Coffee (70%), Shabu All Day (70%), bubble tea brand Milksha (51%), and SuperFoods Group that operates Highlands Coffee (60%) The Company also has membership interests in Tortazo, LLC, along with Chef Rick Bayless, for Tortazo in the U.S., and in Botrista, a leader in beverage technology.

    The Jollibee Group’s global sustainability agenda, Joy for Tomorrow, underscores its commitment to sustainable business practices across food safety, employee welfare, community support, good governance, and environmental responsibility, among others. These focus areas are aligned with the United Nations Sustainable Development Goals (UN SDGs).

    The Company has been recognized as the Philippines’ Most Admired Company by the Asian Wall Street Journal, named one of Asia’s Fab 50 Companies, and listed among Forbes’ World’s Best Employers and Top Female-Friendly Companies. The Company is also a five-time Gallup Exceptional Workplace Award recipient and featured in TIME’s World’s Best Companies and Fortune’s Southeast Asia 500 List.

    To learn more about Jollibee Group, visit

  • Ping An Digital Bank Celebrates 6th Anniversary with Exclusive 3 Hong Kong and 3SUPREME Collaboration

    Ping An Digital Bank Celebrates 6th Anniversary with Exclusive 3 Hong Kong and 3SUPREME Collaboration

    Unveils Cross-Sector Rewards with Up to HK$2,600 Early Bird Savings on Designated Handset

    HONG KONG SAR – Media OutReach Newswire – 8 September 2026 – Ping An Digital Bank (International) Limited (“Ping An Digital Bank”) marks its 6th anniversary through a cross-sector collaboration alongside 3 Hong Kong and 3SUPREME, mobile brands of Hutchison Telecommunications (Hong Kong) Limited (“HTHK”). The joint initiative debuts an exclusive dual promotion designed to elevate customers’ smart digital financial and mobile communications experiences, adding further excitement to Ping An Digital Bank’s suite of 6th-anniversary celebrations!

    Mr. Ronald Iu, Chief Executive of Ping An Digital Bank, said, “As Ping An Digital Bank celebrates its 6th anniversary, our retail banking segment continues to experience rapid growth, a testament to the long-standing trust and support of our customers. On this special occasion, we remain dedicated to thinking ahead and going the extra mile for our customers. Collaborating with 3 Hong Kong and 3SUPREME allows us to combine the strengths of both parties, empowering customers to upgrade to the latest digital products while enjoying seamless and high-quality retail banking services.”

    New Handset Rewards: HK$400 Upon Account Opening, Mobile Plan Subscription and Handset Purchase Up to HK$2,600 in Early Bird Savings

    From now until 30 November 2026, eligible customers1 who successfully open a Ping An Digital Bank personal savings account using the designated promotion code [3HKPA] will receive a HK$400 cash rebate2 from Ping An Digital Bank.

    To reward first movers, an exclusive early bird offer is available from now until 17 September 2026. Eligible customers1 will enjoy a waiver of the HK$500 prepayment amount3 from 3 Hong Kong and 3SUPREME, alongside handset discounts of up to HK$2,2003. Combined with the HK$400 cash rebate2 from Ping An Digital Bank, customers can unlock total savings of up to HK$2,600.

    Deposit Rewards: Enjoy 16% p.a. 1-Month HKD Time Deposit Interest Rate

    Additionally, new Ping An Digital Bank customers4 who open a Ping An Digital Bank personal savings account on or before 30 September 2026, and successfully place a 1-month HKD time deposit can enjoy an attractive annual interest rate of 16%5,6 on their first HK$100,000 deposit. This enables customers to effortlessly lock in privileged high-yield returns while upgrading to the new handset.

    Looking ahead, Ping An Digital Bank will continue to uphold its vision of “Always with You, Always Ahead.” Dedicated to thinking ahead and going the extra mile, the Bank will actively explore cross-industry synergies and continuously enhance its diversified suite of financial products and services to deliver superior digital financial experiences for customers.

    1 Eligible Customers refer to customers who have never held any account with Ping An Digital Bank, successfully open a savings account with promotion code “3HKPA” during the Promotion Period, subscribe to, renew or upgrade to a designated 3 Hong Kong / 3SUPREME service plan with a minimum contract period of 24 months and hold a valid Hong Kong Identity Card or Exit-Entry Permit for Travelling to and from Hong Kong and Macau at the time of such subscription, renewal or upgrade during the Promotion Period (from 7 September 2026 to 30 November 2026) , and successfully purchase a designated handset on or before 31 March 2027.

    2 HK$ 400 cash rebate is available only to Eligible Customers who satisfy all relevant requirements. Each Eligible Customer can enjoy the HK$ 400 Cash Rebate and other offers once only. The Cash Rebate and other offers are non-transferable and cannot be exchanged for cash or other gifts. Cash Rebate will be credited to the savings account of eligible customer on or before 31 May 2027.

    3 The waiver of HK$ 500 prepayment amount, up to HK$2,200 discount upon purchase of a designated 3HK handset model, designated service plans, designated handset models, and other designated 3HK offers are provided and managed by 3 Hong Kong / 3SUPREME, and are subject to relevant terms and conditions.

    4 New Ping An Digital Bank customers refer to customers who have never held any account with the Bank and successfully open a savings account during the 1 September 2026 to 30 September 2026 using a promotion code obtained through any channels.

    5 The 16% p.a. HK$ Time Deposit rate offer will be displayed on the Time Deposit page in the Ping An Digital Bank’s personal mobile banking app within 3 working days (excluding Saturdays, Sundays and public holidays) after successful account opening.

    6 HKD Time Deposit interest rate is calculated daily on the basis of a 365-day year and is subject to the Bank’s decision from time to time.

    Ping An Digital Bank is not the supplier of any products or services provided by 3 Hong Kong / 3SUPREME and shall not be liable for any matters relating to the quality, supply, use, payment, refund, handset collection, warranty or after-sales services of 3 Hong Kong / 3SUPREME’s products or services. Offers subject to the relevant terms and conditions. For details, please refer to the “Ping An Digital Bank x 3 Hong Kong / 3SUPREME New Customer Exclusive HK$400 Cash Rebate Promotion Terms and Conditions” and “New Customer Time Deposit High Interest Offer Programme Terms and Conditions”

    Hashtag: #平安數字銀行 #PingAnDB #3HK #3Supreme

    The issuer is solely responsible for the content of this announcement.

    Ping An Digital Bank

    Ping An Digital Bank (International) Limited (“Ping An Digital Bank,” “PingAnDB”) is a wholly-owned subsidiary of Lufax Holding Ltd (“Lufax”) (SEHK: 6623; NYSE: LU) and a member of Ping An Insurance (Group) Company of China, Ltd. (“Ping An”) (SEHK: 2318; SSE: 601318). Ping An Digital Bank was granted a banking licence by the Hong Kong Monetary Authority in May 2019 to offer retail banking and business banking services. Backed by Ping An’s advanced technology, Ping An Digital Bank is elevating banking experience, serving customer in Hong Kong and the Greater Bay Area, establishing itself as Ping An Group’s comprehensive financial platform in Hong Kong.

    Hutchison Telecommunications (Hong Kong) Limited

    Hutchison Telecommunications (Hong Kong) Limited (“HTHK”), a leading mobile operator in Hong Kong, offers diverse and advanced mobile telecoms services under the 3 Hong Kong, 3SUPREME, SoSIM and MO+ brands, addressing different needs of the consumer market. HTHK is also dedicated to developing business and enterprise solutions under the 3Business brand in the corporate market spanning mobile commerce, information technology, smart city, the Internet of Things and big data. HTHK channels the latest technologies into innovations that set market trends and steer industry development.