How do you plan for your retirement?
How early should you start planning for your retirement?
(The answer may shock you!)
What are some of the proven retirement methodology that works?
How do you diversify your funds, savings, and assets to create more wealth and ultimately, becoming financially independent or financially free?
Today, we talked to a few experts, from the council and certified financial planner on how they help their clients plan and execute their retirement planning.
If you want to learn from the pros on how they do it, then keep on reading!

“As in all successful ventures, the foundation of a good retirement is planning,”
Generally, there are 2 types of fundamental retirement plan for the Malaysian workforce, your EPF and pension scheme if you’re a government servant.
News has again and again saying that these plans alone will not be enough.
Why?
- We live longer, we have a longer lifespan than ever before due to medical and technology advancements.
- Inflation. Cost of living goes higher, year by year, and so does your day-to-day expenditure, healthcare cost, children education cost and so on.
Now, let’s see what our experts have to say –
Yap Ming Hui From Whitman Independent Advisors
This is a very common issue – Most of our clients realized that they may not have enough savings for their golden age when they’re about to retire. (That would be a little too late.)
Worse still, escalating costs of children private education can easily drain your savings, especially for those who have two to three children.
Solution?
- Start saving for your future self the moment you start earning an income, no matter how small the amount. If not now, then when?
- Stay investing in the stock market regardless of the bull or bear market with a time frame of 20-30 years. (Invest for long term)
- Researching and educating yourself to invest in a solid and quality investments (Whether it’s stock or unit trust) is a MUST before making such a decision to avoid scams.
- Channel 30% of your gross income into a pension fund (mandatory 11%+ additional 19%). Of course, the quantum very much depends on your age, financial commitment or desirable retirement lifestyle.
- Another one simple assessment method is to do holistic financial planning via our free iWealth mobile app which could assess your current situation, your desired lifestyle and how much you need to be financially independent.
- Always prioritize not to lose your hard-earned money. For example, choosing a regulated investment, diversify into different asset classes, and set your own investment criteria, discipline, and strategy, and stick to it (If it works) no matter what.
Linnet Lee from the Financial Planning Association of Malaysia
If you expect to spend 30 years living in retirement, you should start accumulating your nest egg 30 – 40 years in advance, a great effort to start planning when you start working.
There are two ways of planning for retirement:
Capital Expense Method:
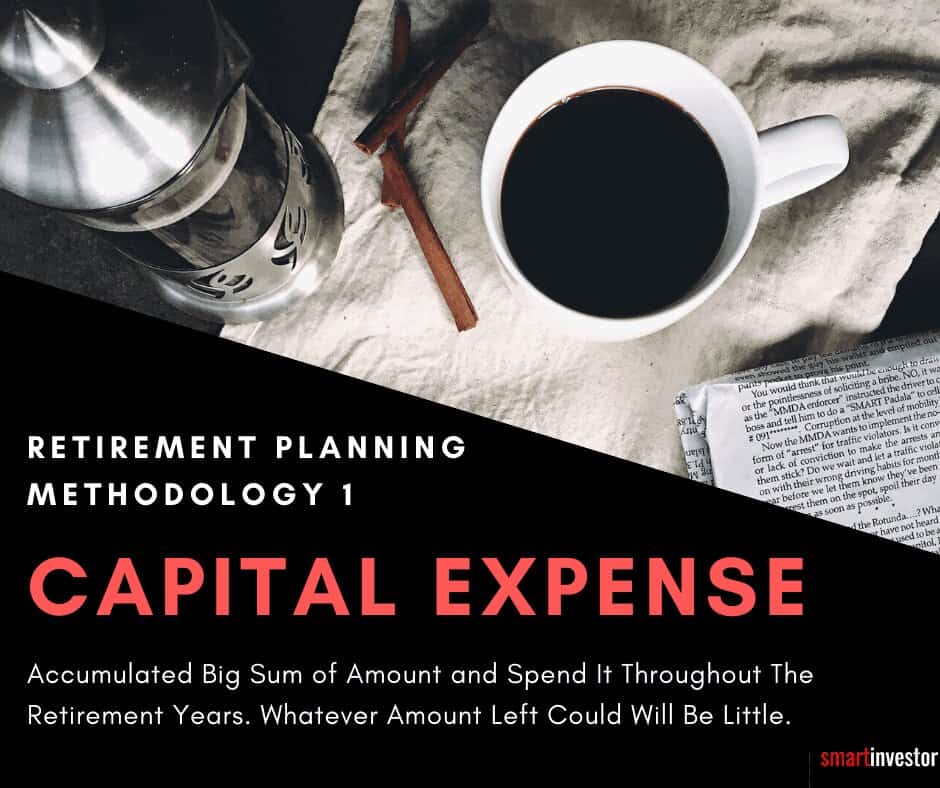
Whatever you saved for retirement (the capital), you will utilize during your retirement and estimate that upon death, the amount left is minimal.
This requires active management during retirement to ensure that the money is enough (the assumption is your money continues to work when you retire).
Capital intact method:
You accumulated huge sum of capital and live based on the interest and dividends received during retirement.
This capital you accumulated over the years can be passed down to your loved ones as a legacy.
So now, what you need is to identify suitable types of investment tools based on your risk appetite.
Other quick tips from Linnet Lee:
- Consider late retirement if you are still healthy and energetic.
- Consider keeping a minimalist retirement lifestyle.
- Start investing in dividend-yielding investment vehicles such as
a. Real Estate Investment Trusts (REITS)
b. Exchange-traded Funds (ETF)
c. Stocks
d. Unit Trust Funds
e. Private Retirement Schemes (PRS) - Ensure sufficient health protection through own savings plus insurance/takaful policies.
- Best work with a financial planner to prevent costly financial mistakes.
- Factor in cost that might incur more during retirement such as:
- home refurbishment/wear and tear
- maintenance of the family cars
- Purchase of healthcare products
- Closely monitor your investment portfolio from time-to-time to best match your risk profile and lifestyle changes.
- Avoid Scams that offer unbelievably high and quick returns.
Bryan Zeng from FA Advisory
One day, you will retire. The matter is when.
Are you planning for it?
Living in uncertain and turbulent times like now, external changes that are beyond your expectations will continue to happen.
Is your retirement fund robust and flexible enough to last through your retirement years?
We are talking about 20 – 30 years at least.
If you have not started your retirement planning, start now.
Take action to maximize your retirement savings while you are young and fit to actively earn income, make time and compound interest your best friend as money-making leverage for you.
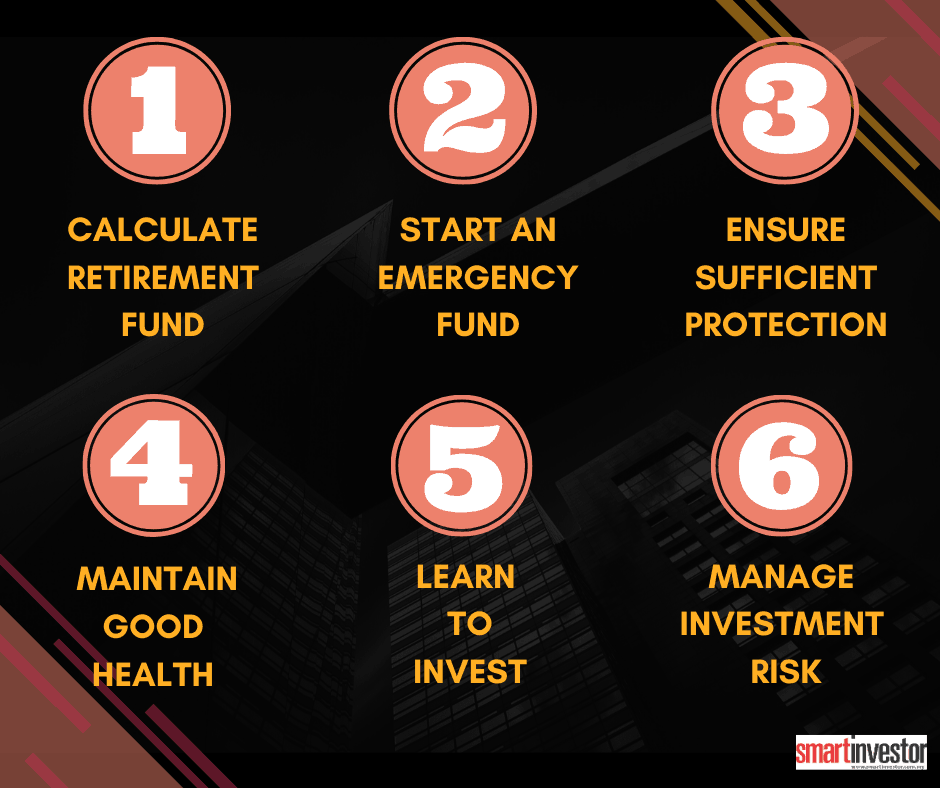
Key actions that you can start taking are:
- Setting up an emergency fund
- Paying off debts
- Get sufficient insurance protection (trust me, medical inflation over 10% will wipe off your savings in months)
- Maintain a healthy lifestyle.
- Make efforts to improve your medical conditions if you are Obese, Overweight or Pre-diabetes. These health situations are reversible and would save on your future medical bills.
- Diversify your investment portfolio, consider alternatives to EPF.
Yes, these steps sound simple yet hard to be done.
Some strategies that you can take to make it happen are:
- Track and reduce your spending.
- Increase savings
- Create a second and third streams of income.
- Delay in retirement.
- Look for investment products that match your risk-return profile as well as being highly liquid with low or zero tax applicable.
- Simple investments with low capital outlay are his favourite.
Derick Tan from Association of Financial Advisers Malaysia
The best time to start investing for retirement is always “Now”. The sooner we start, the earlier we can achieve our retirement goals while undeniably having more choices to choose from.
Some keywords related to retirement planning and selection of investment instruments are:
- Long term regular savings
- Sustainable growth of your funds
- Diversified portfolio of your investment
As the world economy is uncertain and the market situation is unpredictable, Derick advises that you should place 70% – 80% of your savings in fixed income or money market asset classes, while the balance 20% – 30% can be channeled into equity class that invests in the Asia Pacific and China.

While the EPF’s management team has performed a good job in managing the retirement fund, you cannot depend solely on EPF savings for retirement. So, look into the following:
- How much EPF savings would you accumulate by the time you retire?
- How much fund is needed for your desired retirement lifestyle?
- What are your investment criteria to achieve your retirement goals?
- What are the pros and cons of each investment you have?
- Are you diversifying your investment into different asset classes or funds to manage potential investment risk factors?
In summary, you will need to have the right blend of knowledge and skill to profit from investment products, i.e. by fully comprehending the cut loss mechanism or even switching or topping up to average down to maintain long-term accumulation growth.
Phang Kar Yew from Malaysian Financial Planning Council (MFPC)
Planning for retirement is a long term journey. It takes a long term vision, long term commitment and long term investment strategy to be successful.

It is well-documented that over 90% of investment returns are generated through asset allocation.
As such, a portfolio of investments is required since asset allocation is all about spreading your investments across a variety of asset classes.
For those who do not have funds or technical skills to invest in the stock market directly, unit trust investment managed by professional managers with market diversification is a good start.
Do remember that you should be clear of your investment objectives, risk-return profile and manage your expectations over the investment performance.
Alternatively, investing in property can be a good choice.
Investing in real estate provides an excellent capital gain opportunity whilst enabling recurring rental income.
However, risks associated with real estate investment are higher than other investment instruments too.
Note: You should assess the property location, monthly installment amount, property price and the rental income before committing yourself to a property.
Investment properties with positive cash flow after deducting the cost of renting it out are rare gems.
Is there an alternative plan in place to cover the loan installments if the property could not be rented out for a long period?
If you can’t afford to have any unexpected downturn to the huge financial commitment, you should think ten times before you commit to it.
An exit plan is equally important as it could impact or limit the investment choices available for your retirement portfolio.
WHAT ABOUT YOU?
Have you started your own retirement planning strategy? What are some other tips that you can share with us? Let us know!