The COVID-19 pandemic outbreak shows an increasing trend of hackers and scammers stealing information and financial data since many business operations have shifted to global scale, and consumers have an increased dependence on online payment systems.
This is true for cryptocurrency or crypto investments. But why is crypto scams in Malaysia still on the rise despite countless news regarding it that have made headlines both worldwide and nationwide?
The possible reason behind this is the attractive and fast return of investment. Success stories of those who are lucky enough to succeed in this investment became the fascination for others to do the same.
After all, crypto investments do exist and are real. In Malaysia, the potential is massive as our financial industry is accelerating into Fintech and digitalisation as portrayed in the Bank Negara Malaysia (BNM) Financial Sector Blueprint 2022-2026 and Malaysia Fintech Report 2022.
Shariah wise, the legitimacy and the nature of trade plays a big role in determining whether an investment is permissible or otherwise. It is reminded that Muslims are prohibited to invest in something which contains element of gambling or an investment which involved speculation in its nature of trading.
The importance of the legitimacy and nature of investment, in relation to the works of Imam Al-Ghazali, was described in his Magnum Opus, Kitab Ihya Ulumuddin. Al-Ghazali mentioned that the understanding of Fiqh is crucial as the action taken in making investments are properly managed and done according to the Shariah.
Checklist On Crypto Scams In Malaysia
It is best to refer to the two checklists below before getting involved in any crypto investments, or you may expose yourself to crypto scams in Malaysia.
1. Checklists regarding investment and investing in crypto:
Study the investment model, risk, and return to see whether it is reasonable.
Muslims can check regarding the Fatwa given on cryptocurrency investments and if it is permissible, check further if there are any circumstances where a crypto investment is considered impermissible? There are many other pointers given by the Shariah Advisory Council (SAC) regarding Islamic investments.
When in doubt, you can check with the Compliance Officer from Bank Negara Malaysia, Securities Commission Malaysia (SC), Ministry of Domestic Trade and Consumer Affairs, Cybersecurity Malaysia or other relevant authorities regarding the licensing status of the local or foreign investment company or find out if there are any latest warning issued regarding cryptocurrency investments.
2. Checklists in identifying and avoiding crypto scams in Malaysia:
You could contact the National Scam Response Centre (NSRC) if you realised you had been scammed and provide the authorities with the relevant details.
To check whether the investment account has any police report record linked to its bank account number. This can be done through the website of the Royal Malaysia Police Commercial Crime Investigation Department, which is supported by Bank Negara Malaysia (BNM), Ministry of Domestic Trade and Consumer Affairs (MDTCA) alongside with the Ministry of Communication and Multimedia Commission (MCMC).
When the transaction amount is suspicious, the Bank officers might stop it for the purpose of due diligence. Be cautious if the Bank officer advice you not to proceed with the transaction without providing any specific reason. They usually have the basic background detail regarding the account you were transferring money to. If you had transferred the money and regretted it, you may call the Bank immediately to cancel it.
Although praise should be given to ‘financial advocates’ who hunt after scammers personally in real life, prevention is better than cure. In this case, it is better to be an informed investor. Hopefully the checklists above can prevent you from becoming a victim of crypto scams in Malaysia.
About the Author
Azah Atikah Anwar Batcha has an Accounting, Finance, Auditing, and Islamic Finance background. She has worked with two of the Big four firms prior to pursuing her postgraduate studies at University of Technology Malaysia (UTM), Kuala Lumpur. She can be contacted at aaabwrite@gmail.com
We have seen it before. The business looks legit and takes on paid orders from customers. Then the business suddenly folds and absconds with all the money. Thus, the name ‘fly-by-night’. It is one of the oldest and simplest ways to operate a scam. But people still fall for it.
In the murky world of cryptocurrencies, this takes on a whole new meaning with rug pull.
“If I Die, I Won’t Completely Die”
Gerald Cotten built a platform that was once the top destination for crypto investors in Canada and the first to be licenced as a money service business by the country’s anti-money laundering authority. At one point, it was processing 90% of crypto trading volumes there.
Everyone loved Gerald. He looked like the guy you’d hangout for drinks in a bar, with giggly boyish charms and a knack for big boys’ toys.
Barely one month after his wedding in a Scottish castle, he allegedly faked his death while traveling to Jaipur, India. He was only 30 years old.
It was two weeks before Christmas 2018. He and he alone had access to a billion ringgit’s worth of crypto belonging to over 76,000 investors!
The cause and circumstance of his death were mysterious to say the least. It launched a media and doxxing frenzy. He was seemingly healthy and died from what local doctors claimed to be Crohn’s disease – which is generally not fatal. It begged the question why he chose to travel without medical precaution.
His name was misspelt on the death cert, no autopsy was done, and the funeral was ‘closed casket’. His will was signed a few days before his death, naming his newlywed wife as the executor and sole beneficiary.
According to some internet sleuths, Jaipur is known to be a mill for fake death certs. Plastic surgeries are also on hand to give the undead a new face. Back home, investigators dug into Gerald’s books and found a massive Ponzi scheme, while investors sought to dig up his corpse to verify it was him. It became clear that he was in grave financial trouble (pun intended) during his final months with the motive to run.
This exit scam or rug pull is immortalised in crypto folklore and the fraud bible, and perfectly summed up by the quote from surrealist master Salvador Dali: “Si muero, no muero por todo” or “If I die, I won’t completely die.”
As we go deeper into the DeFi (decentralised finance) part of the cryptoverse, exit scams have become the weapon of choice. They contributed 37% of all crypto scam revenue in 2021, surging from 1% in 2020!
They are much faster: the average active period for each scam was 70 days in 2021, down from 192 in 2020. And they have a catchy new name: “rug pull”, like when the rug is quickly pulled from underneath and makes you fall.
The tactics used to rug pull investors are creative. In Compounder, the smart contract used for the investment was injected with a few lines of malicious code to drain out the funds. Investors could do nothing but watch and be left holding the bag.
In SushiSwap, the founder cashed out all his tokens at a high after successfully sucking billions in liquidity from a rival platform with a cloned blockchain protocol – this is called a ‘vampire attack’ as liquidity is the lifeblood.
In Squid Game (no relation to the Netflix show), the token created so much hype off a popular meme but flash-crashed when the founders pull out – from peak of US$2861 to a fraction of a cent, in 10 minutes! The token was intentionally designed with exit barriers which made it harder to sell and fueled market panic as everyone is reeling from the rug pull.
In more recent news, the fugitive owner of Thodex, the top exchange in Türkiye was arrested after a grand ~RM10 billion rug pull. He shut down the exchange by faking cyber-attacks, locked up the funds of 391,000 investors, and fled overseas with a USB drive. He faces up to 40,000 years in jail.
In the conventional world, what you see is what you get. But crypto is invisible. Which is all the more reason for you to know what you’re getting into. The vast majority of investors do not read the technical code before they buy crypto, not because they don’t want to but they don’t know how to.
Even with safeguards like security audits, timelocks, burnt keys, and what-nots, it is not failsafe. Many high-profile scams were audited by reputable firms! Worse, most of these scammy founders are anonymous – pushed proudly as a selling point rather than warning sign since the whole industry is founded by a phantom named Satoshi Nakomoto!
Only detailed forensics can tell you what went wrong. The real truth is found in the digital fingerprints. Even then, you won’t be completely safe from rug pull.
For those of you who tend to have FOMO (fear of missing out), you missed nothing. Instead, please enjoy the JOMO of not losing money as seen above. Crypto is not for everyone. There are other less risky products out there to aim your FOMO. It is better to invest in what you know or to stay within your “circle of competence”, as Warren Buffet would say.
Crypto is a great invention, but is in continuous iteration, and you can afford to wait it out until the products improve and mature over time. Do remember to make your due diligence or you could become a victim of rug pull.
Edmund Yong is the managing partner of Celebrus Advisory and appointed by MDEC as part of its Talent Expert Network (formerly known as Digital Expert Panel) for blockchain technology. Members of the public with similar experiences and who are looking for investigative and forensic services in digital assets from authorised representatives, or to support their litigation efforts, can contact the CEO of Imperium Universe at jason@imperiumuniverse.xyz.
With many uncertainties coming our way such as the recession and general election, there are a lot of jittery investors out there. Throw in volatility, rising inflation, hikes in interest rates, and we have ourselves a storm in the coming year.
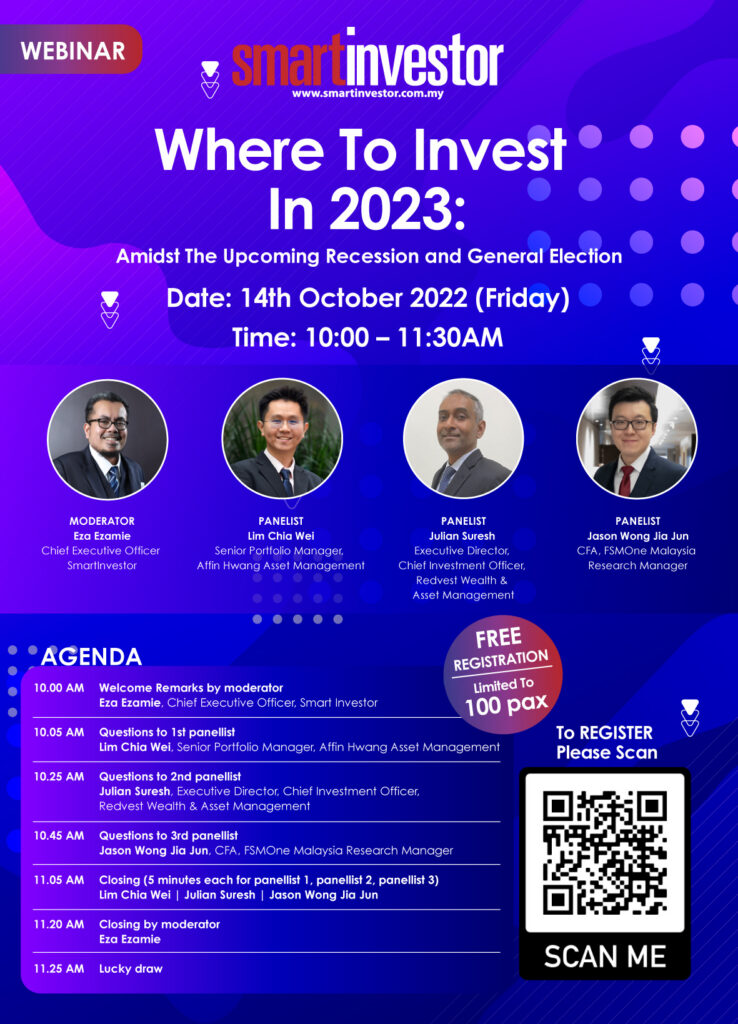
With that, Smart Investor organised and moderated the webinar ‘Where To Invest In 2023’ attracting hundreds of participants where they attended a fruitful session and discussion between three industry experts sharing their thoughts and views.
The panel was made up of three industry experts: Lim Chia Wei, a senior portfolio manager at Affin Hwang Asset Management; Julian Suresh, the executive director and chief investment officer at Redvest Wealth & Asset Management; and Jason Wong Jia Jun, CFA and research manager at FSMOne Malaysia.
Where To Invest In 2023
We started off with the question: “The dreaded R-word is popping up again and haunting investors. Do you think we are headed for a recession and how do you think Asia will weather through the crisis this time? Could we see a repeat of 1997 or something milder?”
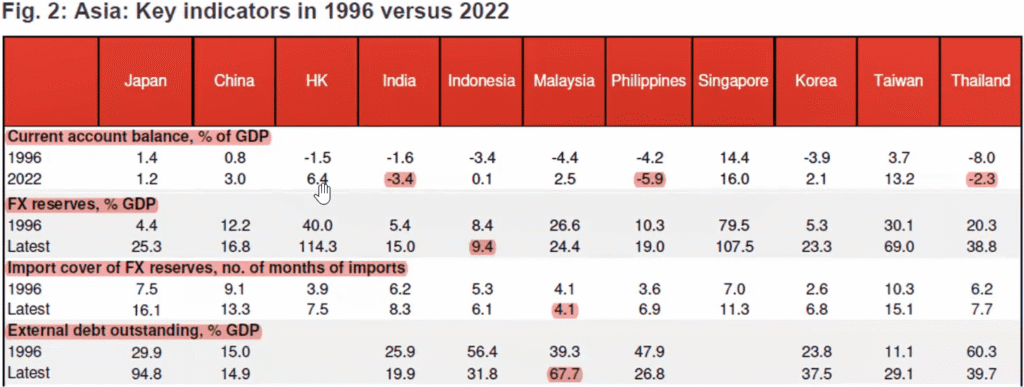
Chia Wei states that we might go into recession in the next six to twelve months down the road, but it would not be as bad as previous recessions. He also shares that most Asian countries are in a much better position in 2022 as compared to 1996, with better current account balances, as a result of a better performing Gross Domestic Product (GDP) in countries such as Singapore, Taiwan, Hong Kong, Malaysia, Korea, and Indonesia. The number of Forex reserves is also highlighted with Hong Kong, Singapore and Thailand showing the way.
Next, we ask the question: “What other key events are you keeping an eye for in 2023? Are there any black swans on the horizon?”
Chia Wei responded: “The stock market has declined a lot and is nearing the bottom, with the bear market already in the US and Asia. The stock market will always bottom out and rebound before the end of a recession.”
To spot the end of a recession, he advises us to look out for the potential easing of inflation and bond yields to go down from a very high level. We should also watch out for a weaker US Dollar (USD), that will see Asian stock markets recovering.
He also cautions us to be aware of the potential escalation of the Russia-Ukraine conflict or the potential of an embargo on oil exports which could cause a spike in oil prices. This will in turn cause the bond yield to rise and with the strengthening of USD, this will have a negative effect on most investment assets.
With such a backdrop of impending uncertainties, one must be asking what can we do next? How do you position your portfolios? Specifically, we ask: “What are some of your sector preferences and which ones do you think would be vulnerable in this environment?”
“We are currently underweight on certain sectors such as banking, semiconductors, and commodities; these industries tend to suffer more during a recession. We are overweight on defensive sectors, such as consumer and health care,” answered Chia Wei.
When the recession bottoms out in 2023, he suggests revisiting and taking a closer look at the aforementioned industries (banking, semiconductors, commodities). But he also warns that we might hit the bottom only in 2024, if things don’t do too well.
Chia Wei also shares a recent positive indicator being the Consumer Price Index (CPI) measuring the change in the price of goods and services from the perspective of the consumer. It is key to measure changes in purchasing trends and inflation. Even though the CPI is bullish, inflation is expected to remain high in the United States (US).
Malaysia is also expected to further hike up interest rates, but on a more gradual basis. This would give the Malaysian economy more time to digest, especially with higher monthly instalments such as housing loans that will increase gradually. But the slower hike in interest rates as compared to the US with its aggressive hikes, will make the USD stronger against the Malaysian Ringgit.
Which brings us to the question about the USD. “What is going on with the strong USD? What causes it to go up?”, we ask our next panellist Julian Suresh to explain further.
Julian Suresh, Executive Director and Chief Investment Officer, Redvest Wealth & Asset Management
According to Suresh, there are a lot of factors causing the USD to rise against most major currencies around the world. Some of the factors include the Russia-Ukraine conflict, high CPI numbers in the US leading to high inflation, and global growth concerns or the looming recession.
The USD is moving within expectation, and with the Federal Reserve expected to hike up interest rates, we shall see the USD continue to strengthen. And if each rise in interest rates is higher than expected, that would see the USD strengthen even further.
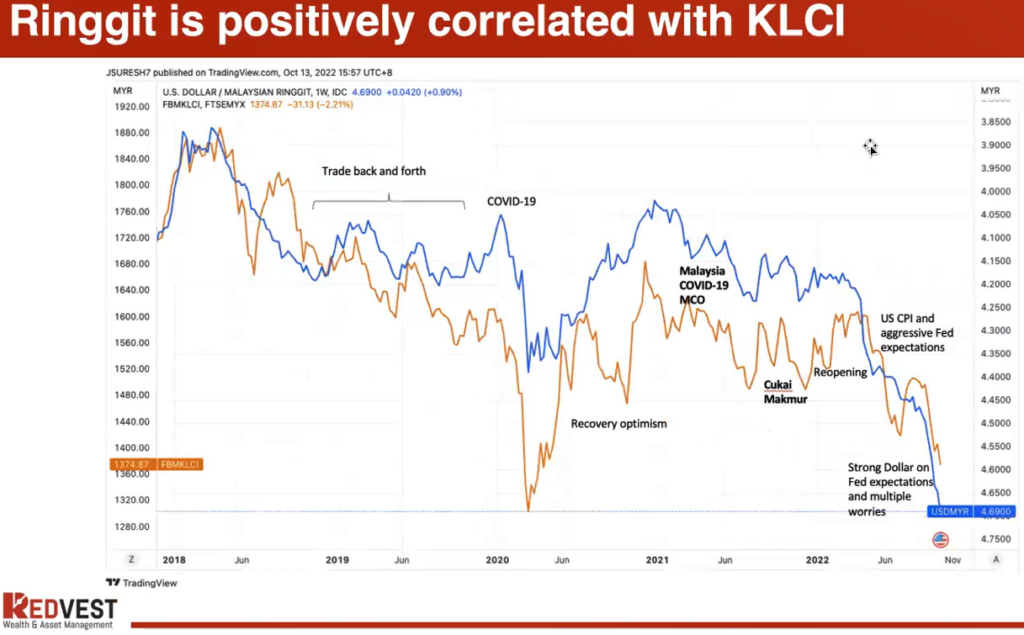
With the Ringgit also being positively correlated with KLCI, the bear market hitting our local stock market has also contributed to the poor Ringgit performance.
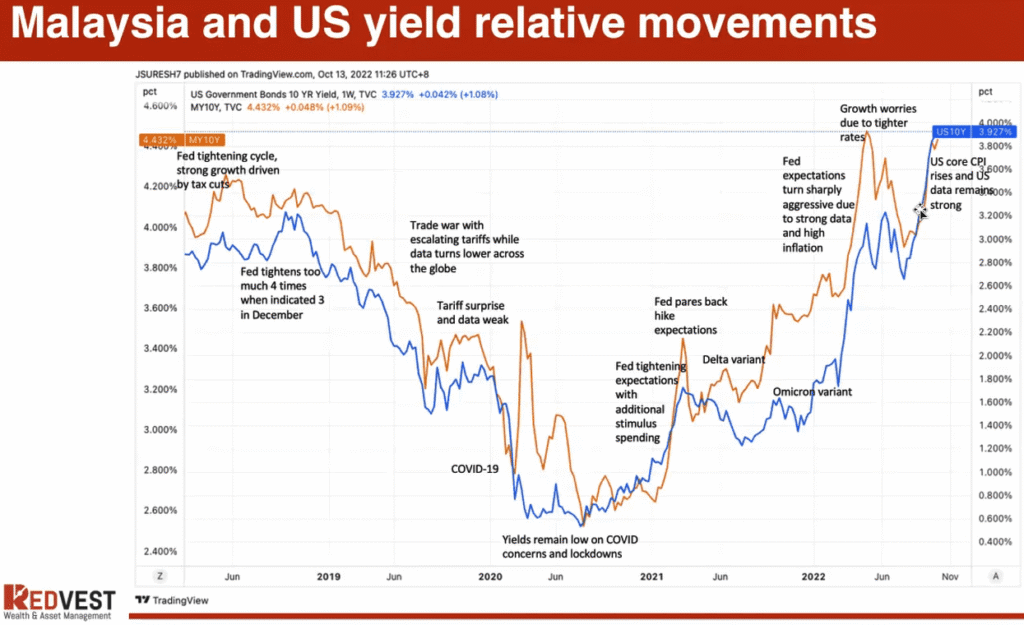
But all is not gloom though, as the bond market is a good alternative to invest. With Malaysia and US bond yields moving closely together, it seems that it will only get higher in the near future. Perhaps everyone is seeking shelter from the current bear market that is hitting the world’s stock market.
But if interest rate hikes are getting more aggressive, it will cause the bond yields to fall. At this point we can look to our local stock market, which has a lot of upsides and liquidity.
Answering a question posed by one of the participants on where to invest in 2023 following the movement of the USD, Suresh answered, “We should first look at the expected US data, whether it will rise or fall. If the USD falls, then the stock market is a good choice to invest.”
But if you take a closer look at the stock market, the S&P 500 might have dropped a lot, but it is still chalking up decent gains over the past few years. As compared to our FBM KLCI which has been underperforming badly.
Even though the USD might be strengthening, our Ringgit has been performing stronger against other major currencies such as the Japanese Yen, Pound Sterling, and Euro.
“The Malaysian market should bounce back by next year, and we are actually doing pretty well,” Suresh optimistically replies when asked about his outlook on 2023.
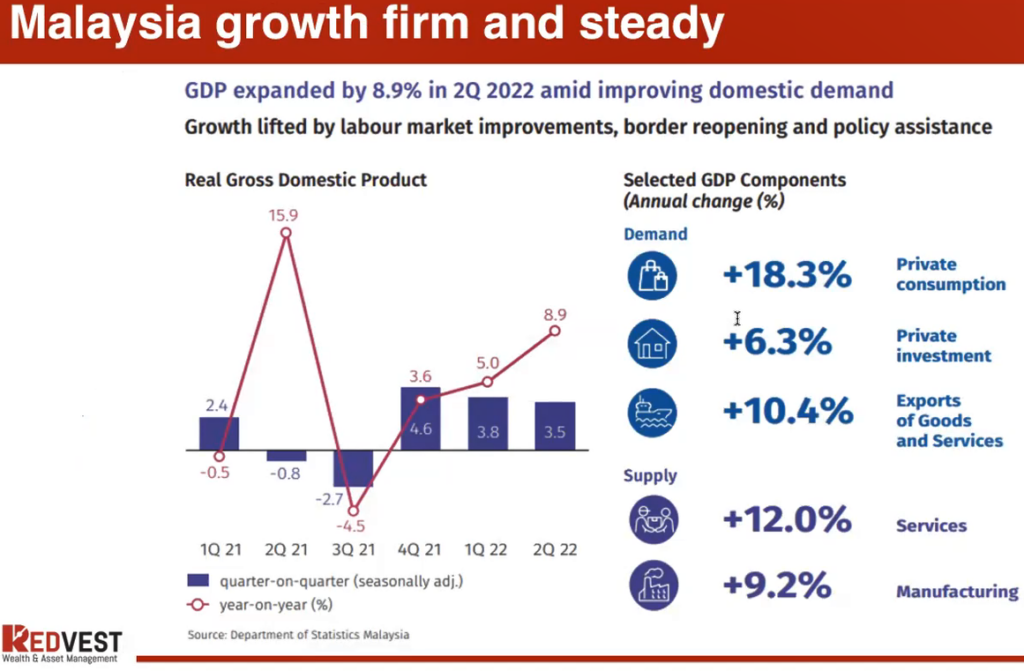
Our GDP is growing and there’s also an increase in supply and demand in selected sectors.
“It is not about what the new government will be doing, but it is what state the new government will be facing,” said Suresh.
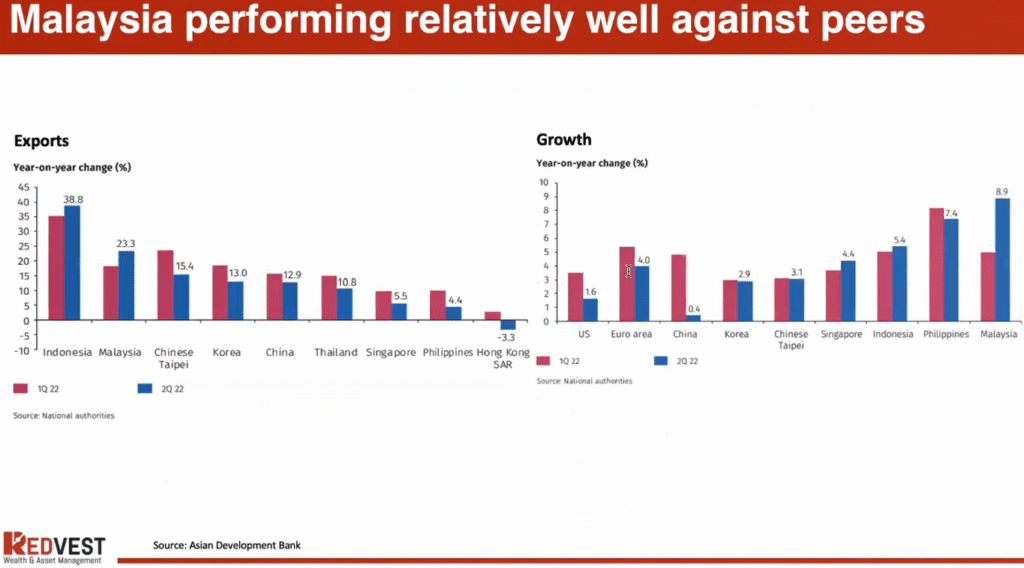
He advised us to be mindful of our risk profile and to diversify our portfolios since there would be a lot of potential once the market recovers. In terms of exports, Malaysia came in second best behind Indonesia, but we managed to beat other countries such as Taiwan, Korea, China, Thailand and even Singapore.
In terms of growth, Malaysia is leading the pack, beating the likes of Singapore, US, Europe and even China.
We then welcomed our third and final panellist, Jason Wong Jia Jun, CFA and research manager at FSMOne Malaysia to share his thoughts on whether Malaysia is still a good market to invest in.
Jason Wong Jia Jun, CFA, Research Manager, FSMOne Malaysia
“From a portfolio perspective, Malaysia is a good market to invest in, due to its low correlation with the global market. Malaysian equities have a lower correlation coefficient with the global equities at 0.54 and the Asia ex-Japan market at 0.38,” he also optimistically answers, relying on good data.
Having Malaysian equities in your portfolio will help reduce volatility and boost risk-adjusted returns.
Even though FBM KLCI is trading sideways, certain sectors have shown good performances such as the financial and energy sector. Local fund managers have also been able to give good returns, as they tend to be able to pick the right stocks – especially in the Small & Medium Cap companies.
Jason also shares his thoughts about Malaysia’s market outlook for next year: “The Malaysian market has been disappointing this year, but we are still doing relatively good against other markets. Next year will be better as the Malaysian economy has been growing at a healthy pace, and next year our economy will be even better as forecasted by the International Monetary Fund (IMF).”
Fundamentally our companies are expected to be doing better with the solid backdrop of our improving economy next year. Earnings are expected to recover next year with double digit growth as compared to this year.
The financial sector will benefit directly from an increase in Overnight Policy Rate (OPR), and the OPR is expected to rise further. The financial sector will enjoy more than 15% growth in 2023 due to the widening net interest margin and improved investment income, as well as higher bond yields.
Our Malaysian stock market is currently trading at a very attractive level, with the FBM KLCI targeted to hit 1,600 points by end of 2023.
“Yes, there are some turbulences caused by both external and internal factors, but the sentiment will turn favourably once some of the catalysts are in place. This includes a reduction in inflation, the eventual resolve of the Russia-Ukraine conflict, and the reopening of China’s international borders”.
With the good news ahead, the question on everyone’s minds is: “Should we keep on investing despite the gloomy prospect of recession next year? If yes, where to invest in 2023?”
Jason responded with a resounding, “Yes! We must be greedy when others are fearful.”
Now is a good time to be back in the market, after it has suffered such a big drop. There are a lot of buying opportunities for long-term investors. Apart from Malaysia, the Asia ex-Japan market is also another good opportunity to invest in. The tourism sector is starting to pick up, and we can now see many tourists traveling in and out of Asian countries.
Next up is China, where they are doing the exact opposite of what others are doing. They are currently cutting down on interest rates and coming out with stimulus. The recovery of China will have a positive impact for the Asian region, especially Malaysia as we have a strong link with China. The disappointment in earnings for Asia will be less severe, as the downward impact has been priced-in most major Asian equities. Plus, the valuation is much more attractive due to the massive retracement that had taken place.
Now You Know Where To Invest In 2023?
The panellists also highlighted that the market is nearing its bottom, and next year we should see the market recover. The dreaded recession might not be as bad as we expect it to be, so just hang in there for as little as a few more months or for longer which is at best, another year or two.
You might also want to hold onto your cash, stay liquid and wait it out, as ‘cash is king’. But ultimately, it all depends on your risk profile and the strategy that you use.
Global economies have faced a number of challenges in recent months, leading to depressed stock market returns. The ongoing Russia-Ukraine war continues to have ripple effects on the global economy. And although most countries have gone back to business as usual following the peak of the COVID-19 pandemic, the virus is probably not going to fully disappear.
In addition, China’s “Zero-COVID” policy has been weighing on economic activity there. Other well-known market challenges include rising inflation and interest rates, as well as the surging US dollar.
Despite these headwinds, emerging economies continue to prove their resilience. We believe it is now a compelling time to consider emerging markets equities, even as many investors are less focused on the asset class.
Conventional And Consistent Policies
Policies in emerging markets have generally been more conventional and consistent than those of developed markets, which we believe will ultimately lead to more robust economies relative to their own history and relative to developed markets. In contrast to developed markets in the post-global financial crisis period, emerging economies did not experiment with negative interest rates.
They have generally had upward-sloping, traditional yield curves over the past decade. During the recent pandemic, policymakers in emerging markets generally did not pursue very aggressive fiscal support plans, which means they did not blow up their sovereign balance sheets. Contrast this with developed markets like the United Kingdom, for example, which pursued aggressive fiscal expansions.
As inflation began to accelerate post-pandemic, emerging economies were also preemptive in tightening interest rates. Thus, while the United Kingdom, the eurozone and the United States are still trying to catch up with rising inflation, many emerging economies have largely completed their tightening cycles.
Brazil, for example, started tightening in March 2021, and has made 12 consecutive rate hikes. Inflation has been decelerating there in recent months, leading the central bank to pause its hiking cycle in September. The US Federal Reserve, meanwhile, did not start raising rates until March of 2022.
In addition, emerging economies are typically less leveraged at the sovereign, corporate and household levels. For example, in Mexico, the household debt-to-gross domestic product (GDP) ratio is only 16%, compared with the United Kingdom’s ratio of around 90%. 1
At the stock level, emerging markets offer investors opportunities in high-quality and high-growth companies. They are home to some of the most innovative, technology-oriented companies in the world—companies that are building the digital architecture around us. These include hardware and software suppliers as well as semiconductor manufacturers.
Some are even responsible for the transition to decarbonization. Many emerging market companies are global leaders in the production of electric vehicles and electric batteries, and in renewable energy such as in solar manufacturing.
Attractive Valuations
Emerging market equity valuations are trading at near historic discounts versus the developed world. In our analysis, the relative profitability between these two asset classes does not warrant the current 45% discount on a price-to-book basis.2
Also, relative to its own 15- to 20-year history, emerging markets as an asset class is one of the few that looks cheap to us. The MSCI Emerging Markets (EM) Index, a benchmark representing the asset class, is now trading at close to 10 times forward earnings, compared to around 18 times for the US S&P 500 Index (S&P 500).3
Increased Dividends And Buybacks
Emerging market companies have recently been increasing their dividends. They have been using their cash flows to distribute dividends to shareholders rather than deploying capital given uncertain growth outlooks. Company managements have also been seeing value in their equities, resulting in increased buyback activity.
In our opinion, these increases are temporary. In this volatile environment, these dividends and buybacks are appreciated, but we would prefer companies invest in their own businesses for secular growth opportunities.
While we believe the persistence of high dividend levels is unlikely to remain at the current 4% level, there has been a sea change in how emerging market companies think about capital optimization and balance sheet management.4
Over the past 20 years, approximately 2.5% of annualized total returns of 9% have come from dividends. 5 Thus, there has been dividend support to the asset class, which many investors may not realize.
Increasing Optimism
Over the long term, we are increasingly optimistic about emerging market economies. Despite the current environment of slowing growth, rising inflation and geopolitical issues globally, we have confidence in both the emerging markets asset class and our strategies.
We continue to seek high-quality business with solid balance sheets, competitive advantages and attractive valuations.
Sources
1. Sources: CEIC, “Mexico Household Debt: % of GDP,” June 2022. CEIC, “United Kingdom Household Debt: % of GDP,” June 2022.
2. Source: Factset. Price-to-book ratio is a financial ratio used to compare a company’s current market value to its book value.
3. Sources: MSCI, Nasdaq. The MSCI EM Index is a free float-adjusted, market capitalization-weighted index designed to measure the equity market performance of global emerging markets. The S&P 500 is a market capitalization-weighted index of 500 stocks designed to measure total U.S. equity market performance. Indexes are unmanaged and one cannot directly invest in them. They do not include fees, expenses or sales charges. Past performance is not an indicator of future results. See www.franklintempletondatasources.com for additional data provider information.
4. Source: Factset.
5. Source: Factset, FTEME.
About the Author
Andrew Ness, Portfolio Manager, Franklin Templeton Emerging Markets Equity
Quantitative and algorithmic trading is a field in finance that deals with high-frequency trading. A large number of people from all over the world are flocking to this field. It is a highly competitive field and requires an in-depth knowledge of the financial markets, advanced mathematics and coding skills.
Because of their capability to rapidly process huge volumes of information and forecast future market trends, quant traders have seen an increase in development in recent years.
Algorithmic trading is a type of automated trading that uses mathematical models to execute trades. Algorithmic trading is a form of automated trading that uses algorithmic techniques to generate, monitor and execute financial trades.
Most aspects of finance have been automated, and securities trading is not any different. Algorithms are intended to help with trading automation, and stock exchanges rely on them. Because of the speed of execution and reduced operating costs, institutional investors as well as big finance companies prefer algorithmic trading.
In these kinds of trades, there is no human intervention. Rather, these trades are carried out in accordance with pre-written guidelines.
Algorithmic trading reduces intermediaries, aids in increasing order execution speed and gives traders a sense of security and reliability. As can be seen, the market for Algorithmic Trading is steadily developing and playing a crucial role for traders.
Because of its vast use of statistical equations in strategy development, it aids in making fact-based decisions. It assists in achieving optimal results by quickly and accurately calculating and analysing trade orders. Furthermore, it reduces the reliance on emotions as well as other judgements by making decisions based on data.
It investigates various market indicators and market conditions that influence trading strategies. As a result, it continuously monitors and tracks trading activities in the event of market changes. Algorithms are programming languages that carry out different orders and directions.
It aids in the reduction of manual mistakes that could happen in trading due to a variety of aspects. As a result, it develops and executes strategies based on both historical and real-time data.
It also minimises issues and mistakes that could lead to risks. It accelerates trading activities and facilitates different stages in order to execute strategies on time.
It also facilitates decision-making by employing high-frequency systems which help address intricate math equations.
Even an experienced trader would also require a few seconds to place a trading order. That’s a lot of time for the price to move significantly in this age of high-frequency trading. In that time frame, the algorithm will already have placed and secured thousands of orders.
Human precision and efficiency limitations can cost endless possibilities.
Accuracy
In algorithmic trading, the strategies are accurate most of the time when it comes to dealing with operational aspects of trading. For example, while filling in the order details, humans can commit errors due to loss of concentration or other factors like emotions.
Back-testing
Automation is widely used not only for trade execution but also for strategy validation. To evaluate the performance of any strategy used in live markets, it is tested and tried on historical data. This is referred to as backtesting the strategy.
Backtesting provides critical information about the strategy’s past performance.
Why Algorithmic Trading Is Growing Rapidly?
Algorithmic trading has risen to prominence over the last few years. It is credited with the accomplishment of some of the best functioning and efficient hedge funds. Algorithmic trading, untainted by the emotional state of people and inhibiting response time, executes trading commands rapidly and accurately.
Some of the most crucial reasons why people want to learn algorithmic trading:
Placing jobs in the field of Financial Technology
Developing a data-driven approach to trading
Setting up one’s own algo trading desk
Reducing manual-related risks in trading
Risk management
Trading is happening in microseconds and even nanoseconds. A single millisecond accounts for millions of dollars in net sales annually from market trades. Aside from ease of use and customization, some of the many beneficial characteristics of Algorithmic trading include confidentiality, speed, and accuracy.
Conclusion
Algorithmic trading provides traders with numerous opportunities. It broadens horizons in order to achieve the best possible results for trading activities. Furthermore, the use of algorithms results in the systematic execution of trade orders. It also helps to eliminate any psychological or emotional preconceived ideas.
It offers viable alternatives by streamlining tasks as well as executing trades adequately. By undergoing an algorithmic trading course, you can enhance your skills and abilities in trading.
Algorithmic trading is a trading revolution. Furthermore, as a result of Algorithmic trading, traders and their techniques are emerging. Traders use mathematical and statistical methods to devise a strategy for expanding their purview.
As a result of trading breakthroughs, traders must consistently learn and acclimate to a changing market. In consideration of the diverse advancements that drive the industry, it is essential to build skill sets. Traders must also be aware of the advanced technology and variables that influence their financial activities.
Dive into the wonderful world of Algorithmic Trading today!
The Securities Commission Malaysia (SC) today announced new digital-related initiatives to spur the growth of the capital market and help support the country’s economic recovery.
The initiatives will pave the way for further liberalisation of the capital market and allow Micro, Small and Medium Enterprises (MSMEs) and Mid-Tier Companies (MTCs) better access to funding to grow their businesses.
The new initiatives include opening the alternative financing markets to new players to cater for the growing demands by MSMEs and MTCs.
The SC Chairman Dato’ Seri Dr. Awang Adek Hussin said it is essential to support the post-pandemic recovery journey of MSMEs and MTCs in terms of their financing needs, as well as their continued innovation and growth potential. MSMEs and MTCs collectively contribute more than half of the country’s GDP and are integral to Malaysia’s future growth and economic sustainability.
“Digitalisation of the market is a key priority for the SC so that market participants are able to adapt to digital trends and use technologies which will promote innovation with new business models and products/services including broadening access to market-based financing in a more efficient manner,” he said at a news conference announcing four new initiatives.
The four initiatives are:
A. Scaling up MSME Access to Financing
Since the introduction of the regulatory frameworks for alternative financing platforms such as Equity Crowdfunding (ECF) and Peer-to-Peer (P2P) financing, these market-based innovations have broadened access to capital for MSMEs and innovative new businesses.
As of June 2022, a total of RM3.5 billion in capital has been raised through 41,000 successful campaigns by over 5,400 MSMEs since the frameworks’ inception.
To further harness the potential of ECF and P2P financing platforms, the SC will open new applications for the following:
1. Registration of new ECF and P2P market operators with Shariah solutions and value propositions
The initiative will catalyse innovation in Shariah offerings to further facilitate access to funding needs of MSMEs through alternative fund-raising digital platforms. Building on from the SC’s Islamic fintech accelerator programme (FIKRA), this measure will also enhance Islamic fintech ecosystem and further strengthen the Islamic capital market proposition. It also aims to foster the growth of MSMEs in the halal economy while allowing greater access to investments for all capital market participants.
2. Registration of new P2P operators focusing on the offering of debt-based financing instruments by MTCs and other larger companies.
The capital market plays an integral role in offering tailored and effective funding solutions to catalyse the growth of companies at every stage of their development. This measure will now allow MTCs to seek debt-based financing directly from investors, while reducing the number of intermediaries involved in the process.
Most MTCs have been largely self-reliant in financing their business growth, especially since they have outgrown existing financing avenues for MSMEs but are still too small for traditional public markets.
B. Encouraging innovation and building capabilities through digitalisation
Towards promoting and facilitating greater and faster digital transformation of the capital market, the SC is moving forward with its digital agenda to increase investor participation and develop more synergistic capital market ecosystems. The SC will introduce the following initiatives:
3. Registration of new Recognised Market Operators-Digital Asset Exchange (RMO-DAX) to facilitate regulated digital asset investments
As investment in alternative assets is becoming more prevalent, the SC continues to promote responsible innovation within the digital asset space, while ensuring adequate protection of the interests of investors. This initiative enables investors to invest via regulated avenues and facilitates the entry of platforms with differentiated value propositions.
Currently, there are only four RMO-DAX operators registered with the SC. Allowing more and greater variety of players to enter the market increases capital market vibrancy by widening the number and types of exchange platforms available for investors to invest in, and that is also safe and secure.
4. Establishment of a RM30 million Digital Innovation Fund (DIGID) to encourage digitalisation of the capital market
Recognising the key role that capital market intermediaries play in the evolution of the digital capital market and to invest in the industry’s future growth, DIGID will co-fund innovative projects that utilise technology to enable new and competitive propositions for the Malaysian capital market.
DIGID aims to encourage smaller capital market players to adopt innovative digital solutions and the development of industry-wide solutions impacting capital raising and investment activities.
Interested parties are invited to submit their applications beginning 1 January 2023. Successful candidates will receive funding on a reimbursement basis after meeting agreed-upon milestone deliverables. The funding amount will cover up to 70% of approved qualifying expenses, capped at RM500,000 per project.
Interested parties are invited to engage with the SC on applications for the digital platforms – ECF, P2P and DAX – from 1 November 2022. The updated guidelines and forms will be made available from 15 November 2022.
Information on the new measures, including guidelines and application forms, will be updated on the SC’s website. Interested parties are advised to periodically refer to the SC’s website and future announcements.
Every investment comes with its own risks. If someone told you to invest in an investment that doesn’t have any risk, then you better run away. But what if there’s a way for better investment risk management?
Let’s see at some of the ways to manage risk as per below:
1. Age
Basically the younger you are, the more risks you can take. This is because you can afford to make mistakes while you are still young. But the older you get, the closer you are to retirement age, then you can afford fewer mistakes.
When you are in your 20’s or 30’s, go for riskier investments such as crypto, equities and futures market. Embracing the ‘high risk high return’ concept, you should be able to take on higher risks.
But when you are in your 40’s or 50’s, and with 10-20 years left of working life, then you should be looking at more stable investments that are not high risk and not having low returns. Investing in robo-advisor, ETF, unit trust, REIT can give a rather consistent return if you stay invested for the rest of your 10-20 years before retirement.
Let’s move on to the next step in investment risk management.
2. Current Family Situation
When you are single and young, you have less commitment and can tolerate more risks. You have a lot of time to learn, study and grow compare to someone who is already retiring.
If you are a young and newly married couple, you should also be able to tolerate more risks towards achieving your financial goals.
However, couples contemplating divorce and couples with many kids should be more risks adverse and opt for lower risks.
3. Current Income Source
If you and your spouse are both working, then you can invest in riskier investment vehicles for a better investment risk management.
For example, the one with the more stable income, with good employment medical and retirement benefits can enable the other spouse more flexibility and take more risk for higher investment returns. Or you can also consider starting a new business which can pay off handsomely.
But you should also consider your commitments and expect the worse, just in case the investment doesn’t go well.
Whereas for families that only have one breadwinner, you shouldn’t be taking higher risk when it comes to investment.
The rule of thumb when it comes to investing is that you need to have an emergency fund first. Once you have six months of your monthly salary being put aside, then you can take on higher risks with your investments.
If you don’t have an emergency fund, then you shouldn’t be taking high risks. Think of an exit plan and play out the worst case scenario.
But if you have huge debts, especially credit cards and personal loan, then it is better you clear off the debts with higher interest rates first.
Take for example credit card that charges 15% to 18% per annum, can you find a ‘safe’ investment vehicle that can give you more than 18%?
If no, then it is best if you settle your outstanding credit card debts before moving on to higher risk investments.
5. Protection
Another good way for investment risk management is to take a good look at your protection’s coverage. Make sure that you are well covered for unexpected events such as sickness, hospitalization, disability or premature death.
Ensure you already have sufficient insurance coverage, before undertaking higher risk investments. Because your family can be spared from a financial disaster should something bad were to happen to you.
The final step in investment risk management, is how well you can sleep at night, and not having to worry about how your investment is doing.
It is not worth to invest in high risk assets when you are concerned about it losing value, let alone losing your sleep over it.
Will you be able to survive should it collapse and you lose all your money?
If the answer is no, then you should be investing elsewhere that can give you a peace of mind.
You Are In Control Of Your Own Investment Risk Management
At the end of the day, you know yourself better than everyone. Once you know your risk profile, then you can better manage your own investment risk management. If anything, do your own due diligence before investing your hard-earned money.
Make sure you understand the risks involved, and don’t only focus on the potential return that it might bring.
Bored of the usual investment vehicles such as stocks, ETF (Exchange Traded Fund), bonds, unit trusts, robo-advisors, properties and the rest? Looking for something else?
With alternative investments, there are plenty of other options that you can consider to invest in. But just like any other investments, don’t just go diving in without first taking the time to understand what it’s all about.
Warren Buffett reminded us that we must not invest into something that we don’t even understand. Otherwise it will be just like gambling, rather than investing.
You have to know yourself first, know your risk tolerance, know how much capital that you can invest, whether it is a lump sum or you can invest every month. With this knowledge in hand, you will be able to sleep soundly at night. Because you then understand what investment is all about, the risks involved, and the potential return from the investment over the years.
Why Alternative Investments?
Normally an individual will start looking for alternative once he or she have exhausted the current options. Which usually means that the person have already invested in traditional investment vehicles such as the stock market, unit trusts and properties. It is mainly a strategy to further diversify their investment portfolio.
Or it could also be that the current investment options that are available could be the investment horizon is too long or the potential returns are not high enough. There’s no stopping you from going for alternative investments, as long as you know what you are getting yourself into.
One of the popular alternative invesments is peer-to-peer (P2P) financing. It allows entrepreneurs and small businesses to unlock capital in small amounts from a pool of individual lenders. It means that you can borrow money without having to go through a bank.
There’s also equity crowdfunding (ECF) which is an innovative form of alternative fundraising that allows small businesses to raise capital from the public. As you may have noticed the word equity here, this means that the investors will get some equities, which effectively makes them shareholders of the company.
Both P2P and ECF are alternative sources of funding that offer access to fi nancing to the micro, small and medium enterprises. They disrupt the traditional banking system by enabling businesses to obtain capital from a pool of investors via an online platform.
The key difference between P2P financing and ECF is that in ECF, you become a shareholder of the company that you invest in.
Of those considering alternative investments, cryptocurrency is currently gaining attention as the most popular asset class. It started with the birth of Bitcoin in 2009, and it has also been referred to as digital gold.
Last year Bitcoin’s performance outperformed every other asset classes and was the biggest winner, however this year, the crypto market comes crashing down. From its height of US$69,000 in November 2021, to the low of US$17,500 in June 2022, it is defi nitely not for the faint hearted.
Then who could forget how Luna (one of the top 10 cryptocurrency at the time) lost almost 100% of its value in just a few days time. It sent shockwaves through the market and this leads to panic all over.
We all heard of the concept, ‘high risk high return’. One of the reasons that alternative investments are gaining popularity, is on the high return aspect of it. But are you willing to take the risks associated with it?
High risk investments can be a part of your investment portfolio as it can help grow your wealth. However, it is crucial to understand the existing risks involved and decide whether it is aligned with your investment objectives. Finally, remember not to put all your eggs into one basket to ensure you minimise risk to your capital.
Do take note that your risk profile, commitments and requirements may also change throughout the years and you may want to adjust your investment portfolio and exposure to high risk investments accordingly.
With the rise of inflation and higher interest rates, it presents a challenge to investors all over the world. It is also challenging to find good investments these days.
Smart Investor spoke to Datuk Wira Ismitz Matthew De Alwis, Executive Director & Chief Executive Officer, Kenanga Investors Berhad to find out more about the challenging global equity markets as well as his thoughts on alternative investments.
Navigating The Challenging Global Equity Markets
Smart Investor: What are the challenges that you and the investors are currently facing, now that we are witnessing the rise of inflation and higher interest rates?
Datuk Wira Ismitz Matthew De Alwis: Global equity markets have been particularly challenging in recent times, due to rising inflation, monetary tightening and geopolitical conflicts. As the post pandemic re-opening has progressed across the globe in 2022, many have felt the effects of higher infl ation due to the clash between a rebound in demand and supply shortages.
The global equity market was further weakened by the Russia-Ukraine geopolitical conflict. In response, central banks have tightened monetary policy in an effort to control the rise in inflation. These factors have negatively affected asset prices, as liquidity is drained from the system and the cost of capital increases.
Globally, companies have been affected by high inflation rates through both rising cost and lower demand as consumers scale back on discretionary spending. Local companies were also impacted, especially those companies with export-based revenue and those that have imported raw materials. Additionally, rising risk aversion also dampens fund flows and general investor sentiment.
Generally, we have adopted a defensive portfolio stance in light of the challenging global equity market, with over-weights on sectors that have pricing power, resilient demand and will also benefit from higher interest rates. These include selected companies in the financials, consumer and industrials weakness as an opportunity to deploy capital to companies where long-term fundamentals still remain solid such as the technology sector.
SI: Is it still a good time to invest in stocks or unit trusts, despite the challenging global equity market? How to select the good ones to invest for long term?
IMDA: Unit trust funds remain an excellent choice of investment as it has a low entry point, provides diversification at a reasonable cost, and is usually expertly managed by licensed professionals. There is also an abundance of choice when it comes to unit trusts as investors can select their pick based on their risk tolerance and investment objectives.
More recently, due to the surge in interest towards impact investing, investors have also begun to divert their attention towards businesses that aim to generate specific beneficial social or environmental effects in addition to just financial gains.
Aside from that, factors such as fund strategy, asset allocation, and sector allocation will also come into play during the investment decision process. Ultimately, investors should perform their own due diligence on all the variables laid out in front of them, and make an informed decision to pick the investment tool that would best suit their own personal objectives.
SI: Why would anyone be interested to invest in alternative investment such as P2P, ECF and crypto?
IMDA: Alternative investments can offer investors several traits that are not commonly found in traditional investments such as equities or bonds. These typically include one or more of the following attributes: long term, high risk, or illiquid investments that are associated with higher returns; low correlation with traditional assets to deliver diversification benefits; inflation-hedging benefits; and scalability.
Alternatives will be able to encompass a wide range of asset classes, including private equity real estate and private equity infrastructure funds, secondary funds, and private debt funds. Just like the traditional counterparts, alternative investments also differ from each other from its volatility, risk, and returns.
Cryptocurrency is the current trending topic no matter the age group from millennials to experienced investors. It is especially popular due to its nature (low fees, unaffected by fluctuating interest rates and a global market place without geographical restrictions) and the rise of popular tech culture in the media. Its rising popularity can also be attributed to its innovative blockchain technology, which promotes extreme security for its users and offers unrivalled transparency in the case of its fully auditable and accurate ledger of transactions.
On the other hand, it is also widely famous for its outrageous volatility, as seen in the recent meltdown of TerraUSD (one of the world’s largest stable coins) which is seen as the less volatile variant of cryptocurrencies**.
My most repeated advice to anyone wanting to dive into any forms of investment is to always conduct their own research regardless of experience level, as it is their own money and their sole responsibility to know where it is being invested into. Tune out the noise in the market and focus on reputable news to formulate your own conclusions. Consistent self-education is one of the most powerful tools anyone can practice as it enables us to not solely rely on third-party information which may or may not provide us with a false sense of the market.
SI: What does Kenanga Investors have to offer in terms of alternative investments? Is this something that the company has yet to explore?
IMDA: As the alternative investments pioneer within the Malaysian market, we are able to offer sophisticated and diversified investment instruments for the modern-day investor. From the conservative to the more dynamic investor profile, our alternative instruments are an additional source of uncorrelated returns, the key to success being a delicate balance of the right manager and the right strategy in line with one’s investment profile.
For Kenanga Investors’ Alternative Investments, we do look at various opportunities and asset classes. E.g. private equity (direct investments into private companies), wholesale funds (launch of Kenanga Sustainability Series, with the most recent being the Kenanga Sustainability Series: High Yield Bond Fund, the Kenanga Global Unicorn Series and the Kenanga Global Multi Asset Fund) and asset-backed high-yielding notes.
From investment advice to bespoke alternative investment portfolio management, our expertise lies in alternative strategies with varying degrees of liquidity to complement or bolster an investor’s existing portfolio.
We are confident that our growing presence within the alternative space has added depth to the products and services offered to our investors, enabling both retail and institutional investors to capture market opportunities in a volatile environment.
SI: With so many legitimate investment schemes out there, why do you think people still fall for scams?
IMDA: Some people still fall for financial or investment scams regardless of the amount of legitimate investment schemes due to one crucial factor, lack of patience. They are often discouraged by the slow process of capital gains or accumulation of returns in legitimate investment schemes.
Therefore, when a get-rich-quick scheme presents itself, they often fall to temptation and suffer high amounts of losses to their valuable savings. These scams often exploit the human weakness of instant gratification where they promise quick and higher returns.
SI: What are some of your plans in the near future?
IMDA: Since 2021, we have steadily been releasing a series of funds that follows Kenanga Investors’ sustainable and socially-responsible investing roadmap such as the Kenanga Waqf Al-Ihsan Fund and our suite of multiasset products, Kenanga Sustainability Series. The Series was conceptualised in wake of the ever-growing demand for ESG adoption among companies by investors, especially post pandemic.
We are excited for the future as we will be introducing fresh new funds in the KSS line-up which will further provide our investors with a more robust portfolio stemming from ESG analytics which captures new opportunities aside from standard qualitative and quantitative metrics. In respect of this, we are also looking to enhance our Shariah-compliant investment experience by adding value-added products and services to stimulate the local impact investing landscape.
Alongside our intention to have more ESG products in our lineup, we will also be looking at converting existing selected funds (both global and domestic) to meet the threshold required to qualify as ESG relevant.
With multiple successful product launches, a dedicated team of professionals in deal sourcing and idea generation, and an intricate network of relationships with expert alternative partners all over the world, we have achieved what we set out to do, bridging the gap between retail investors and more sophisticated forms of products which were previously only available to institutional or accredited investors.
Everyone loves it when it comes to investing. Seems like we can never get enough of it, although our capital might not be that big. Here are some investment tips for beginners that you can apply for a steady growth despite the market’s uncertainties.
1. Set Your Goals
They say if you fail to plan, then you are planning to fail. The first investment tips for beginners, is begin by listing down all your financial goals such as:
Saving up for a property
Retire at age 55
Sending your child to private university
Travel the world
Everyone have their own goals in life. Be specific with what you want, and allocate the funds to each goals.
For example you need:
RM100,000 as down payment and renovation costs to purchase a property
RM5,000 per month living expenses each month when you retire
RM100,000 as tuition fees and living costs for your child when entering university
RM100,000 fund to be used to travel to Europe and United States during the summer
Graph 1: The Cost of Market Timing The Risk of Missing the Best Days in Market, 2000 – 2019. Source: Morningstar, 2020
According to a research by Morningstar, investors who stayed in the market for all 5,035 trading days achieved a compound annual return of 6.1%. However, that same investment would have returned 2.4% had it missed only the 10 best days of stock returns.
Further, missing the 50 best days would have produced a loss of 5.5%. Although the market has exhibited tremendous volatility on a daily basis, over the long term, stock investors who stayed the course were rewarded accordingly.
That’s why it is important to invest regularly either each week or each month instead of trying to find the best time to go in the market. Because even the most seasoned professional investors can’t get the timing right, what chances do we have?
Even when faced with an uncertain market, the best thing to do is keep on investing. Allocate a certain amount from your salary to invest. A good figure to start is 10%, if your salary is RM10,000 per month – make sure you invest RM1,000 each month.
3. Portfolio Diversification
“Don’t put all your eggs in one basket”
This words of wisdom can’t be much further than the truth, and is very important as one of the best investment tips for beginners. You should be diversifying your portfolio into several low-risk instruments with low returns, medium-risk instruments with medium returns, and high-risk instruments with high returns.
Still remember the RM1,000 per month investment that you are allocating each month, which is 10% of your salary?
You can split it into:
RM250 into crypto
RM250 into equity (stock market)
RM250 into REIT (property)
RM250 into fixed income (fixed deposits)
Crypto and equity are high-risk investments, REITs are medium-risk while fixed income are low-risk.
Either crypto or stocks, you should be looking at those with great fundamentals. For crypto, the stablecoins are the ones to invest for long term, Bitcoin, Ethereum, Binance Coin (BNB), Ripple, Solana are good choices.
Bitcoin is the grandfather of crypto, Ethereum and Solana are mostly used for NFT, BNB being used on Binance the world’s largest exchange, while Ripple are used for real-time gross settlement system, currency exchange and remittance network.
As for stocks, you can use one of the most popular fundamental analysis – 5 Magic Numbers:
Earnings Per Share (EPS)
Price-to Earnings Ratio or P/E Ratio (PE)
Return On Equity (ROE)
Net Tangible Asset (NTA)
Dividend Yield (DY)
By using the 5 Magic Numbers, you will be able to filter companies with resilient earnings, strong track record and ability to pay dividend.
5. Invest For Long Term
The final investment tips for beginners, is that I can’t emphasize enough on the importance of investing for long term. Instead of looking for short term gains, have a more longer term view when it comes to investing.
Ignore all the hypes of current investment that is making waves, instead go for the tested and tried instruments. All investments have their ups and downs, and if it can go up very fast, it can also go down in a flash.
Well there you go with some of the best investment tips for beginners that you can probably use as part of your investment strategies. Just be patient and keep on investing regularly, you should be able to reap what you sow and meeting your financial goals.