Category: Investments

  • Fundamental Analysis vs Technical Analysis

    Fundamental Analysis vs Technical Analysis

    There is a prolonged debate on the superiority of both analyses, or in short: fundamental analysis vs technical analysis. I can recall my days as a derivatives dealer where some clients prefer to read news, while others like to draw charts.

    But for sure both types of analyses have their own merits as it measures the price trajectory of the markets.

    What Is Fundamental Analysis?

    Fundamental analysis refers to analysing the information from the news and reports. The investors will assess the information in hands and make attempts to predict the direction of the asset’s price.

    What Is Technical Analysis?

    The technical analysis on the other hand is a price action strategy. The investors will evaluate the market breadth based on the readings of price trend patterns, indicators and oscillators; then draw a conclusion on future market sentiment. So, based on the definition, which is more appropriate and why?

    The news have heterogeneous impacts on the financial markets. A group of markets may receive the same news, but the investors will react differently. The COVID-19 news for instance, may trigger a bearish sentiment but the magnitude of impacts on the financial markets in the developed and emerging markets will be different. Therefore, it is crucial that the investors to understand how the asset price in their portfolio moves.

    According to the empirical finance, generally there are three main stages of asset movement which are called information arrival, co-movement and volatility. At the stage of information arrival, investors receive and react on the information upon receiving them.

    In the second phase, the asset influences the other assets or markets. Next, when there is the absence of news, but the price is constantly moving, we call it the stage of volatility.

    Fundamental Analysis vs Technical Analysis

    To decide on when to use the fundamental or technical analyses, the investors need to know their portfolios well such as the sensitivity to news and the movement of interrelated markets. Applying the fundamental analysis needs a good knowledge of portfolio sensitivity.

    The best example is the stock’s beta to index. The fundamental analysis is best to use in the first and second stage. While some commodity markets like energy and agriculture futures, the investors are depending on the EIA and USDA reports however the information on production numbers and demand will not being released so frequently.

    In this case, it is preferably to use fundamental analysis to determine the market sentiment thereafter technical analysis is used to time the entry and exit.

    By and large, fundamental and technical analyses are tactical in investment and trading. The investors should assess the market sentiment based on the news, and time their entry using the price charts. It is worth to note that regardless of trends, either bearish or bullish, the price will not move linearly.

    There must be the phases of corrections, retracement, rebounds and reversals amidst of the major trend. The news may set path for the major trend, but the trading motivations of buyers and sellers determine the intertemporal price dynamics.

    So in the case of fundamental analysis vs technical analysis, which one do you prefer? They say if you are an investor, then you should use fundamental analysis. If you are a trader, then you should be using technical analysis. Or can we use both?

    About the Author

    Dr. Ahmad Danial is a Certified Financial Technician (CFTe) and Senior Lecturer in Finance at Department of Economics and Financial Studies, UiTM Puncak Alam. He has over 10 years’ experience in the financial markets before hopping into the academia. His areas of expertise include financial contagion, trading in stocks and derivatives markets, price discovery, hedging strategy, Econophysics and technical analysis. He can be reached at danialzainudin@uitm.edu.my.

  • What Is Greenwashing, And What To Do About It?

    What Is Greenwashing, And What To Do About It?

    In the most recent “Making An Impact” podcast episode, Claire Herbert, ESG Manager for Schroders APAC, discusses with Anastasia Petraki, Schroders’ ESG Investment Director, the topic of greenwashing, concerns around this issue, and solutions that address it.

    Elaborating on why investors are concerned about greenwashing and the implications of the rise in climate and investment product disclosures in the Asia Pacific, Anastasia Petraki, ESG Investment Investor, Schroders, shared:

    “First, if we are talking about greenwashing at an activity or company level, the risk is a misallocation of capital. This means that money intended for sustainable purposes goes to activities that are not really sustainable. This leaves less money for those activities that can create a more sustainable economic system. So, the economy does not progress, which harms confidence in sustainable investing.

    Second, if we are talking about greenwashing at an investment product level, then the risk is mis-selling. That is, people buy products that are making promises that they can’t possibly deliver. This is a failure of consumer protection. Indirectly, it also robs sustainable activities of necessary funding.

    [Climate and investment product disclosures] have a dual objective here in the Asia Pacific. The first one is to create an environment that makes it easier to channel private investments toward products and services that will make the economy sustainable faster. The second is to help prevent greenwashing.

    Regulators and policymakers are making transparency the number one priority for sustainable finance because, similar to investors, they see a lack of common understanding and data as a potential barrier to further growth in the market.”

    Adding on to Anastasia’s remarks on disclosures, Claire Herbert, ESG Manager, APAC at Schroders, commented:

    “There is also the big question about whether these disclosures and this additional transparency help.

    Environmental, Social and Governance cover a broad set of factors, and different metrics will bear different importance depending on the product type you are looking at or the investor’s priorities and preferences. It’s not easy for regulators to decide which metrics to disclose because more information is great. Still, we don’t want to overburden companies and fund managers with administrative disclosures, especially when methodologies and understanding of all of this are still in their early stages.

    Even with all the new disclosures, we still see a lack of understanding and trust. Consumer research tends to indicate that retail investors either don’t engage with this information or don’t understand product disclosures and end up looking at the individual underlying holdings as a “shortcut”. So, if you hold company ‘X’ in your fund and I’ve just read an article about a controversy involving company ‘X’, then I might not think you’re sustainable.

    In the same vein, many investors turn to third-party ratings as a “second opinion” or to get some external validation on stuff being reported by a company or investment product. If that rating seemingly lines up with what’s being said, then that’s all good, but if not, there is a risk that people assume there’s something wrong with the reporting rather than something wrong with the rating. And let’s not forget here that ratings are just another subjective opinion on ESG, not the be-all and end-all for deciding what is or isn’t sustainable.”

    Schroders’ “Making An Impact” podcast series features our thought-leaders sharing their insights on various Environmental, Social and Governance (ESG) investment topics in easily digestible audio content.

    All podcast episodes are available on the Schroders website and Spotify.

  • Best Investment In Malaysia

    Best Investment In Malaysia

    Is there such a thing as the best investment in Malaysia? Is there an investment vehicle that is suitable for everyone?

    But before we begin, let’s first understand what investment is all about.

    “Investment is the dedication of an asset to attain an increase in value over a period of time. Investment requires a sacrifice of some present asset, such as time, money, or effort.”

    -Wikipedia

    We invest in order to grow our money. Because our time is limited where we can only earn an active income in a limited way, investment can unlock this limitation. The earlier we start investing, the bigger the returns in the long run. There are also investment that can give us income in the form of dividend or interest.

    I’m sure you have heard of the saying, “High risk, high return”. It means that in order to get a higher return, we need to take higher risk.

    So again this begs the question, what is the best investment in Malaysia?

    I’m afraid to disappoint you, but the answer is there is none. There’s no such as thing as the best investment in Malaysia.

    This is because we are all different. Our age is different, our time horizon is different, our risk tolerance is different and how much capital we have is different from one another.

    The same goes with, what’s the best food in Malaysia? Is it nasi lemak? Roti canai? Char kway teow? Everyone will have their own preference.

    Even if everyone voted nasi lemak as our best food in Malaysia. But then which nasi lemak? The one in KL? Or in Penang? Or the one in Johor?

    What is more important here is that, the so-called best investment in Malaysia is the one that fits our needs. Let’s say we have another 20 years of working life, the investment is more of a long-term game rather than for a quick gain.

    For a fresh graduate, he may want an investment that can start with as little as RM100. Which can then slowly increase the amount once he got a better pay.

    But for a high net worth investor, he might decide to invest in painting, with the cheapest painting costing upwards of a few thousand Ringgit.

    Best Investment In Malaysia

    For some, the answer might be in unit trust. Or ETF (exchange-traded fund) or even ASB (Amanah Saham Bumiputera), since the individual might not have the necessary knowledge and skills to select a stock on his own. He does not have the Technical Analysis know-how on when is the best time to buy a stock. Or his risk tolerance is low, can’t even sleep well when his portfolio is in the red.

    Whereas an active stock trader will have no problem cutting his losses when things don’t go his way. He accepts that there are risks involved, and follow strictly the trading plan. But for even the best stock trader, surely he would have some investment in property for example, where he can earn a rental income consistently. This would come in handy when he decides to call it a day and live a rather boring life.

    Portfolio diversification is crucial, as the popular saying that goes “Don’t put all your eggs in one basket.”

    Essentially, we need to be investing in a basket of portfolio, ranging from the lowest risk all the way to the highest risk.

    • Low risk investments, such as fixed deposit, Amanah Saham Bumiputera (ASB), Amanah Saham Wawasan 2020 (ASW) and Tabung Haji
    • Medium risk investments, such as unit trust, mutual funds, robo-advisors, ETF and property
    • High risk investments, such as stocks, futures and crypto

    So the answer to the best investment in Malaysia will be different for you and me.

  • Financial Planning In The Crypto Age

    Financial Planning In The Crypto Age

    A very simple definition of Financial Planning is the process of managing our resources to help us achieve our life goals. Now that we are in the cryptocurrency age, how do embrace crypto in our financial planning?

    It is a process which we proactively look at our financial situation and determine the better routes which can allow us to use these resources to help us accomplish what we hope to have to call it a good life.

    Many people seem to think that when we have got a financial plan done, we have done financial planning, and hence we can then on our way to become richer, and retire early, or sending our children to study abroad.

    The truth is that financial planning is a process but not a touch-and-go activity that produces a document called financial plan. Life is full of changes, so any plan we make today will always be challenged or need to change in response to the actual situation in life.

    Financial Wreck Caused By The Pandemic

    For instance, no financial plan will have predicted COVID-19 and prepare everyone for the Movement Control Order (MCO) and all the consequences from having these shutdowns in the past two years.

    Our money is one of the resources we have that can be used to help us accomplish our goals, and money itself is not the goal.

    If our reason to invest in good deals or engage in financial planning conversation is to have more money, this reason itself invites more questions than being an answer.

    “More money for what?”

    “More money to do what?”

    “Why do you need to have more?”

    To have more, there’s a trade-off that we must accept.

    More Work = More Money = Less Rest

    For example, to earn more, one must work more, to work more, it could mean one has to let go of time for rest, or to not spend more time with loved ones, or not able to enjoy activities that they like.

    It could also means taking more risk so that we have a potential higher return from our investing activity.

    So, in our pursuit for more money, we may fare better if we adopt a big-picture view but not only focus on having more money.

    Sometimes, we decide to delay, or postpone doing things we really want or hope to because we are afraid to do it. And often, it is due to our feeling of afraid we don’ that enough to ‘just do it’, or the fear of “cannot afford to”.

    This is not abnormal, and I can totally understand this emotion. When we do not know how much we need for the rest of our life, how are we able to feel we have got enough, right?

    A good financial planning process is one where we spend more time to understand the person, identify the values (what’s important for this person), then take a look at their money management habit and their net worth (what they have left after minus what they owe), then we can have an idea if this person will have enough money for the rest of their life.

    What Are Your Life’s Goals?

    This process helps us understand a few important answers, such as:

    • Do I have to reduce my spending today?
    • Should I get a side hustle to boost up my income today?
    • Do I have to take more risk on my investment?
    • Can I change my car or house without affecting my future?
    • Can I quit the job I hate and accept a new job with lower pay?
    • At what age may have a huge cashflow deficit?
    • At what point (or age) will I run out of money in the future?
    • If I lose all my investment money today, how bad will my future looks like?

    Establishing a good financial planning process can help us to bring our future to the present, and by looking at this future we can assess what are the thing we do not like so that we can make the change to it today.

    Imagine having to wait for 20 years only to find out that we will still run out of money at a certain age, versus knowing this scenario is likely to happen 20 years earlier and we have 20 years of time to change something, which route would you prefer to take?

    Through proper financial planning, we get a ‘preview’ of our future today, but at the same time, we make some assumptions of what might happen, such as inflation, potential investment return, our spending and potential future income, taxes, etc.

    Hence, one of the things we will be thinking about is where or how should we allocate our money, to what kind of asset classes. And nowadays, it is likely most people have heard of and are quite keen to understand where cryptocurrency or crypto assets can fit into their plan.

    Dawn Of The Crypto Age

    Before the emergence of crypto assets, people have allocated their savings to various types of asset classes like stocks, debts, some keep most of their savings in cash or cash equivalent, businesses, real estates, arts, collectibles, gold or silver, to name a few.

    Some of the assets have a low risk and value tend to not fluctuate too much and are ‘predictable’, while some the value may deviate quite a lot, and are considered ‘risky’.

    One of the key considerations in determining our asset allocation, is to understand if we need the investment to generate additional income, or to have the value increase in future for us to have ‘gain’.

    Essentially, crypto assets are assets that are non-income generating but more for the investment objective for capital gain.

    While it is undeniable that crypto currency has helped make many new millionaires, for this wealth to be sustained into the future, one may want to explore how this new wealth can be protected or kept, so that even if the value of the asset class reverses its course, this person will not be knocked back to the ‘pre-crypto’ life.

    Of course, it is perfectly fine if we remain having our 100% of our wealth be invested in crypto assets. However, that will also mean we tie our future financial health and possibility in life to a single asset class.

    Imagine a person putting all their savings for old age to the stock of the single company they work at, and over the course of years for whatever reason, this company went out of business, or the company’s business dropped a lot due to new competition, or innovation.

    The above example is not just pure imagination, we have seen a few big company’s gone through such trajectory before. Will this person be better off ‘putting all the eggs in different basket’ instead of ‘in the only basket’?

    It does not matter what asset classes we are thinking about, it seems that it is not a bad idea to limit our downside risk and avoid over-concentration.

    What about people who have not experienced the explosive growth or have not invested in crypto assets before?

    Diversification Is Key

    Generally, crypto assets or digital assets are one new asset class for us to incorporate to our personal investment portfolio to achieve diversification beyond the common asset classes mentioned above.

    Depending on your tolerance for risk, and your investment objective, you will then understand how expose you can be, just like on every other asset classes. A person who is conservative or cannot sleep well even with a small up and down may want to limit exposure to volatile asset class, regarding the potential upside, and vice versa.

    For asset class that can have a large swing in value, non-income-generating, it is advisable that we limit our exposure and do not over commit our wealth to it.

    However, if one decides to do so, it will be prudent to ensure that we have prepare sufficient savings that can offer us liquidity and peace of mind during challenging time in life, or when the asset value is not at a good level for us to make withdrawal.

    It is also very important that people only invest into cryptocurrency via digital assets exchanges that are operated by operators approved by Securities Commission Malaysia [1]. This ensures your investment will not fall into schemes that are unregulated or hands of scammer.

    Regardless of what we do with our money, it is important that we understand why we want to do certain thing, and how this fit into the overall big picture of our life. By having a proper asset allocation that can support our future and lifestyle, we can avoid overexpose to certain asset classes, or certain asset.

    A good financial planning process is about setting a good foundation, and manage our risk, so that we can increase our chance of living a life we consider well lived.

    [1] https://www.sc.com.my/regulation/guidelines/recognizedmarkets/list-of-registered-digital-asset-exchanges

    About the Author

    kevin neoh

    Kevin works with people to transform their relationship with money and support them to use their money to live a meaningful life.

    He is a CFP professional, a certified member of Financial Planning Association Malaysia (FPAM). Kevin can be contacted at www.kevinneoh.my

  • Robo Advisor In Malaysia, 8 Robo Advisor Platforms To Choose From

    Robo Advisor In Malaysia, 8 Robo Advisor Platforms To Choose From

    A robo advisor is a low-cost, online investing platform that uses algorithms to create and manage investment portfolios. Robo advisor in Malaysia aims to make investing simple by removing the guess-work in stock and fund picking. Normally you would answer a few questions to determine your risk profile, then you start putting in your money. The robo advisor then does the investing for you, does the rebalancing for you, does the buying and selling for you, and many more.

    A robo advisor employs technology to monitor global markets and to react to new investing opportunities. The technology analyses thousands of data points each day, incorporating information from across continents and asset classes, to develop investment portfolios, without the influence of human emotions. These portfolios aim to generate sustainable returns while managing risk.

    Benefits Of Robo Advisor

    They also do away with the traditional need to lock in funds for a set amount of time. Its user-friendliness is a positive for beginner investors, and would be a good place to learn how investing works and to understand your personal risk profile and appetite, before moving onto more hands-on and advanced investing.

    The fees charged are minimal when compared to traditional investment products, and its accessibility and low barrier to entry suggests that it is a viable alternative for individuals that are not financially savvy or have the time to pore over countless annual reports.

    Some only requires you to make an initial deposit of RM100, which makes it very accessible by most Malaysians. Then there’s also the convenience of the account opening can be done online, all by just using a smartphone.

    Getting Started With Rob0 Advisor In Malaysia

    Robot hand Artificial intelligence trading stock or forex graph global network business data concept banner background 3d illustration

    Robo advisors are automated financial advisors. They are an online tool that assists investors in picking an optimal investment portfolio according to their risk tolerance profile. Typically, robo advisors start by asking investors questions to understand their risk appetite and allocate investments based on certain algorithms.

    Once investors agree to the investment allocation, they can start funding their account and the robo advisors will purchase the underlying securities and manage their portfolio by rebalancing it periodically. Robo advisors have emerged as favorites to younger demographics due to their low account minimums, low fees, digital-only service and overall, a more efficient and timesaving offering.

    8 Licensed Robo Advisor In Malaysia

    There are now 8 licensed robo advisor in Malaysia or also known as digital investment managers (DIM) that are recognised by the Securities Commission Malaysia (SC):

    1. Akru Now Sdn Bhd
    2. BH Global Fintech Solutions Sdn Bhd
    3. GAX MD Sdn Bhd
    4. Raiz Malaysia Sdn Bhd
    5. StashAway Malaysia Sdn Bhd
    6. UOB Asset Management (Malaysia) Bhd
    7. Wahed Technologies Sdn Bhd
    8. Kenanga Investment Bank Bhd (KIBB)

    Each comes with their own product and uniqueness. Robo advisor platforms typically invest in exchange-traded funds (ETFs) which are a compilation of stocks, bonds and other investments. Most robo advisor in Malaysia tend to focus on foreign ETFs.

    You can actually start investing in robo advisor with just RM100. It is also a good habit to perform regular savings every month, so you can see your investment in robo advisor growing.

    With robo advisor, you can easily diversify your portfolio since it is investing in multiple instruments. Just like the popular saying that goes, “Don’t put all your eggs in one basket”.

  • The 101 on Alternative Offshore Investment

    The 101 on Alternative Offshore Investment

    Not many of us are aware that we can invest overseas in the form of offshore investment. An offshore investment is an investment in another country of which we are not a resident of that particular country. Offshore jurisdictions are used to pay less tax in many countries.

    We caught up with YH Wong who has over two decades of experience in the financial services industry to find out more about offshore investment.

    Q1. In the offshore world, the alternative theme has become more common. More investors are talking about including alternative investments in their portfolios. What are alternative investments and their role in portfolio diversification?

    Alternative investments are assets that are not considered conventional assets like stocks, bonds and cash. Alternative offshore investments include venture capital, private equity, hedge funds, real estate investment trusts, commodities as well as real assets such as precious metals, rare coins, wine, and art.

    If you live long enough, you see everything. Most people understand how important it is to diversify their investment portfolios. Proper diversification requires more than a traditional allocation to stocks and bonds. One of the biggest strengths of most alternative investments is their absolute performance which is often illustrated by their low correlation to certain asset classes.

    investment

    Q2. We have come across some negative articles about alternatives like hedge funds: they are risky, performance is poor, and they are suffering redemptions and some are even shutting down. What’s your view on this from your experience dealing with alternative investments?

    There is a very long education which needs to happen. There are so many wrong assumptions about hedge funds – like they are high-risk vehicles, that you will burn all your money at some stage, that they are taking too much leverage and that there are many uncalculated risks. Of course, some funds fall into some of these categories but they do not represent the entire industry.

    There is a certain mismatch of expectations in terms of performance. People really need to be clear what types of characteristics they are really looking for when they plan to use hedge funds in their portfolios. Also, please remember that even the good managers will have periods of underperformance over time.

    Another observation is that the hedge fund industry has become too crowded. Consolidation in the industry is a positive development.

    Q3. So, does this mean that hedge fund managers and strategy selection will become even more important? Can you comment on the massive IT revolution that is sweeping the offshore world?

    You are right. I’m always looking for niche strategies to generate portfolio alpha that matches the risk tolerance of my investors. A growing number of hedge fund managers today are just generating beta with very little alpha.

    Everywhere you look, the signs of change are there. I am a big fan of using technology such as Artificial Intelligence, Big Data and Quantitative Trading to take advantage of market opportunities. There are a growing number of managers that are actively embracing innovation and, in doing so, they are creating new opportunities for competitive advantage.

    Q4. What about hot-button issues like the fees?

    There are some specialist managers who don’t exist in big numbers and who actually do very interesting things that can’t be replicated easily. Under this situation, fees become less relevant because investors enjoy solid performance after fees.

    investment

    Q5. How are managers of different sizes coping with the competition in the industry these days?

    It is always easy for well-known and big names to attract assets compared to the smaller guys. Things are even more difficult for the young ones mainly due to the costs involved when setting up their whole business and fulfilling all the regulations. Without naming anyone here, most smaller managers are able to perform better than their larger competitors in most measures.

    Q6. What is the common due diligence process for any investors looking for new alternative managers?

    I am a big advocate of proper and extensive due diligence. Whether you are investing in stocks, bonds or alternative investments, always make sure you perform your due diligence.

    Due diligence should fit in independent, bottom up, qualitative, quantitative, and operational analysis. The on-going monitoring is as important as the initial due diligence. As for me, personal touch with the managers is very important where I am able to sit down with them if needed.

    Q7. The alternative investment industry is changing more than ever before, and a lot of that is driven by the regulators. Can you comment on this?

    Regulation has become much stricter at a time when the financial institutions themselves started to have more reporting and controlling. It is encouraging when you see players and regulators working together to promote and achieve something. Being part of a strong regulatory framework is an advantage for investors as well as managers.

    Q8. Some investors are talking about higher risk in the markets in the coming months. What is your advice for the average investors?

    Well, at some point we will experience a correction or even a meltdown with a real dislocation of the markets. Nobody knows what is going to happen. What you can do is proper diversification of managers, strategies and underlying factors.

    Hedge funds that can weather the storm make great sense for investors. For those looking to impress the pretty girls next door, long volatility can be an interesting diversifying strategy for portfolios.

    YH Wong has over two decades of experience in the financial services industry. His clients include high net worth investors and boutique institutions such as family offices and investment partnerships in the region. He is currently a senior partner with Satori Consultancy Ltd, a financial services company regulated by the Mauritian Financial Services Commission. He can be reached at yhwong@satoriconsultancy.com.

  • The 4 Stages Of Side Hustle For A Bigger Investment Capital

    The 4 Stages Of Side Hustle For A Bigger Investment Capital

    We are living in one of the most volatile period over the past few decades, where it feels like a series of black swan events arises back to back (to back). However, as investors, we know that in every crisis lies great opportunities. Some of us will try to time the market, and rest of us will DCA (Dollar Cost Average). All of us wants to invest when the market is low and reap theHus profit when the market recovers.

    In times where price of goods are high and employment income stays relatively stagnant, how do we allocate more capital into our investment portfolio? In this article, we will explore the best ways to start a side hustle to complement your investment capital and how to make it successful.

    What Is A Side Hustle?

    Side hustle is simply a second income that you can generate to help you to be financially free. A side hustle is any type of business that you can run while you are working on a full time job. Side hustles can be a small business that you run from your house, or they can be a big business that you run from an office.

    You can start a side hustle with minimal initial investment. It can be anything from selling your own crafts, to selling products on marketplaces, to providing a service to paying clients.

    A side hustle is a great way to make some extra money, learn new skills, and network with interesting people. 

    Now let’s look at the 4 stages of side hustle.

    1. Choosing A Side Hustle (Ideation Stage)

    Thoughtful creative asian man in glasses thinking while making post on social media, looking away, pondering or making decision, holding smartphone, choosing something in internet.

    There’s no shortage of ideas for a side hustle. The challenge is finding one that’s a good fit for you and that you can be successful with.

    Here are a few tips for choosing a side hustle:

    • Start with something you’re interested in or that you’re good at
    • Find a need that isn’t being met and fulfilled
    • Think about what you can offer that others can’t
    • Start small and grow your business gradually

    2. Building An MVP (Creation Stage)

    Once you’ve chosen a side hustle, the next step is to get started. This is where the rubber meets the road.

    This is where you need to start thinking about your MVP. What is an MVP?

    An MVP is your minimum viable product. The idea is to build a simple product that can be tested and experience by potential customers. Even though your MVP is not a finished product, it is the first version of your product.

    The goal with an MVP is to test your idea, market, and product to see if they are viable. One of the most painful experiences is to invest your heart and soul into a product that no one cares about.

    3. Getting Customers (Acquisition Stage)

    Marketing Ideas Share Research Planning Concept

    This is where things get tricky. How do you get customers?

    Getting your first 10 paying customers can be difficult. Here are a few ways that you can experiment, but bear in mind that there is no one-size-fit-all solution. 

    • Find individuals and businesses that are in need and ask them to try your service or product,
    • Work with a local business and get them to try your service,
    • Post your service or product on marketplaces like Fiverr, Shopee or Lazada,
    • List your service or products on the social media,
    • Offering a part of your service or product for free to build trust and credibility.

    You may also consider building a community around your service or product.

    Your community will be made up of people who are interested in what you sell. As you build a community around your product, you will be able to recruit people interested in your product.

    4. Growing Your Side Income (Expansion Stage)

    This stage is optional. You may treat your side income as a real business that may one day replace your full-time job, or, it can also be a side project that let’s you earn a comfortable side income while doing something you love.

    However, should you want to grow your side income, you may want to strengthen your process within your business/company from end-to-end. You may no longer rely on your notebook and your memory to handle the increased number of transactions within your business.

    There are plenty of digital tools from book-keeping to human resources to customer relationship management software. You may also want to look at business automation software that can help you with your business.

    Having a proper process in place is important because it allows you to delegate your work systematically should you wish to hire employees to help you with your business. Having a clear process makes it easier for you to monitor your team’s performance and causes less confusions between you and your employee.

    Protecting Your Hard Work

    Last but not least, let’s not forget why do we want to start a side hustle – that is to increase our investment capital. Building multiple streams of income help hedge against the sudden change of events.

    However, when times are good, remember to invest for the future. You will never know when do you need to use it.

    To sum up, investing in a side hustle can be a great way to supplement your investment capital. In return, you can get a second income that will help you to be financially free.

    Source: PlanNERD.io

    About the Author

    marshall wong insurance

    Marshall Wong is a financial planner holding licenses from the Securities Commission Malaysia and Bank Negara Malaysia. He can be contacted via email at Marshall@plannerd.io

  • US Equities: Opportunities Amid Turbulence

    US Equities: Opportunities Amid Turbulence

    Global markets are at a crossroads, reflecting deep concerns around inflation, interest rates, moderating economic growth, and elevated geopolitical uncertainty in Europe as it pertains to the Russia-Ukraine war and its potential ripple effects. Market sentiment has swung dramatically, from bullish peaks in 2021 to extremely bearish levels in recent weeks.

    Indeed, sentiment indicators are close to the lows of 2009. This is notable considering that the state of the economy today is certainly stronger than 2009, when the U.S. economy was reeling from the impact of significant financial imbalances and an imploding housing market.

    In our view, the sentiment indicators reflect anticipated economic headwinds ahead and an expectation that consensus earnings estimates could be revised lower in the coming quarters. In aggregate, we believe S&P 500 earnings growth will face pressure in the second half of the year, but should remain positive in 2022.

    Valuations have rapidly contracted over the last six months; the forward price-to-earnings (P/E) ratio of the S&P 500 Index has returned to pre-COVID-19 levels and is trading about one standard deviation below its past five-year average. Stock price pressure has largely been driven by multiple compression as interest-rate increases have impacted discount rates and, in turn, reduced what investors are willing to pay for future earnings.

    While this is appropriate to some degree, it is notable that the profitability and earnings power of many companies remain intact and earnings reports have been resilient across many sectors. In our opinion, recent volatility has created interesting opportunities in the market for long-term investors who are able to look through the near-term turbulence and focus on the growth opportunity of future years.

    In our analysis, U.S. stocks continue to trade at a premium versus other markets. In our view, these higher relative valuations reflect stronger corporate profitability, better return on equity, and more robust growth in comparison to equity markets in other parts of the world.

    While interest-rate increases can slow the economy and lead to recessionary downturns, equity markets have historically performed well in rising interest-rate environments. Over the last eight rate hike cycles dating back to the early 1990s, the S&P 500 has typically declined ahead of and going into the first interest-rate increase, but as the pace of policy tightening becomes more transparent and predictable, equity markets have tended to perform well. Looking at the last few months, the market has followed its historical pattern, but with a higher degree of downside volatility.

    Long-term secular growth trends, such as health care innovation, digital transformation and the rise of fintech, remain intact. These trends were clear beneficiaries of the COVID environment but remain deeply relevant even as economic growth moderates. We believe they will likely create productivity and profitability tailwinds for companies operating in these integral sectors.

    Outlook For Inflation: Some Pressures May Moderate

    We think the United States has probably seen the inflationary peak, but core levels of inflation may remain stubbornly high for a while. However, we believe this should moderate as supply challenges abate and pent-up demand normalizes. As it stands, we’ve already seen some moderate pullback in commodity prices including oil, lumber and copper from very elevated levels, which should ease inflationary pressure somewhat.

    It is important to note that measures of inflation, such as the Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE), are lagging indicators, with substantial backward-looking components. The more forward-looking components of inflation seem to point to some moderation. Home prices have moderated in the United States and home sales have slowed meaningfully.

    Wage inflation has slowed, and we have started to observe layoffs across some companies—early indications that the labor market is rightsizing. The auto backlog, which was primarily driven by supply chain problems, has started to recede and auto deliveries have increased. Energy prices have also receded from recent highs. Taken together, we believe these should create an environment for moderating inflationary pressure, although the effects will only be seen in headline and core inflation gauges after a lag.

    Directionally, in our opinion, inflation should continue to improve in the second half of the year and may moderate faster than market participants anticipate. This could be a net positive for risk assets as it means the U.S. Federal Reserve (Fed) may not have to move as aggressively as it had intended in the face of slowing economic momentum.

    While we think inflation will moderate, there is a strong likelihood that it will not hit the Fed’s 2% core PCE inflation target. Instead, inflation may hover around a 2%–3% range for some time, reflecting the stickier aspects of inflation that may not dissipate quickly. This will keep pressure on the Fed, in that they may keep policy settings tighter for longer.

    As it stands, we’re already seeing the effects of higher interest rates ripple through mortgage rates, auto lending rates and other consumer credit rates, which is likely to dampen aggregate demand further in the face of already moderating growth. The challenge for the Fed will be to calibrate monetary policy settings, such that it is tight enough to curtail inflation, yet not too tight that it triggers a deep and long recession. Engineering a soft landing is a tall order.

    Probability Of Severe Recession Appears Low

    We believe the probability of a severe recession in 2022 is low. Underlying economic conditions in the United States, while weaker than last year, remain healthy, in our view. Two pillars of the U.S. economy appear resilient: corporate earnings have remained relatively robust, while consumer balance sheets are solid, and debt-servicing ratios remain low. That said, earnings growth could slow and we’re likely to see a moderation of gross domestic product (GDP) growth from a fairly elevated base on a year-on-year basis.

    As long as the labor market remains healthy, where unemployment hovers around 3%–4%, it is difficult to fathom a case where we enter a recession that is anything but shallow. A technical recession—two quarters of negative GDP growth—in the next year or so is certainly possible, but ultimately it is likely to be a shallow and short-lived one, in our opinion.

    Sector Opportunities

    We have a quality basis and primarily focus on businesses with robust competitive positions, strong pricing power and healthy financials as we believe these are the companies that perform well in any market environment. Our focus on major secular themes, like digital transformation and health care innovation, invariably leads us to both established and emerging growth players in various sectors.

    Companies across the globe are focused on improving productivity, lowering costs and finding ways to widen their reach and deepen relationships with customers. These often require investments in digital technologies, digital applications, software and hardware.

    We continue to see robust demand for technology enablers from enterprises across various sectors. The outlook for digital spending remains bright as investing in digital capabilities has moved up the needs ladder for many businesses post-COVID.

    We do think that some technology players have been unfairly penalized in the recent rates-driven market correction. Many of these tech businesses are unprofitable and are likely to remain so in the near term. Being in the early stages of growth, they’re understandably focused on spending to engage the huge addressable market opportunity for their products as they grow their business.

    As active and fundamental investors who focus on the bottom-up, we continue to see healthy fundamentals among some of these businesses. They’re growing at a rapid clip and continue to acquire customers at a rapid pace. There are certain viral aspects to their businesses and existing customers are also spending more on their platforms.

    That said, we remain discerning on our exposure, focusing on software over hardware given their resilience to supply chain snarls, and favoring enterprises over consumers given that the former is a reliable source of demand and is likely to spend more on tech. We also pay close attention to unit economics in terms of the cost to acquire a customer and the return they earn on that investment. These are the businesses we believe will shine with time and grow to be the next-generation leaders in their respective sectors.

    Striking A Balance

    We seek a good balance of consistent, high-quality, name brand, best-in-class, established businesses along with exposure to next-generation leaders. To do this, we rely a great deal on our bottom-up, fundamental research capabilities and leverage our in-house team of analysts to uncover promising companies that have the potential to become market leaders. Having a constant dialogue with the companies we hold also helps us discern potential winners that may emerge in different sectors.

    As long-term investors, we typically take a three-to-five-year view when assessing opportunities. Ultimately, we believe outperformance can be generated by identifying these long-term winners rather than timing short-term trades in the market. As such, we view the current volatility as a compelling buying opportunity.

    The dramatic performance of mega-cap (companies with market capitalizations in excess of $200 billion) technology stocks, specifically Apple, Alphabet and Microsoft, relative to the broader S&P 500 Index has been a defining feature of the market environment since the onset of the COVID-19 pandemic. These three names continue to account for roughly one-sixth of the S&P 500 based on market capitalization.

    While these are very good companies, in our view there are many opportunities outside of these names that offer compelling potential for alpha generation. We believe the opportunity set outside these mega-cap names is large and robust and the real opportunity for active equity investors is to find uncovered gems that have the potential to be the next generation of market leaders.

    Gauging The Market Bottom

    We do not focus or rely on any one particular indicator to divine or predict where the market is headed next. We typically observe a range of indicators to better understand the market environment.

    Historically, overly bearish sentiment tends to signal good buying opportunities. Incrementally shallower selloffs in the stock market in response to adverse new information often tells us that a great deal of bad news is already baked in the price. We are starting to see this in sectors like tech.

    Over the next quarter, any negative earnings revisions could test this hypothesis. The reaction to companies missing earnings estimates or providing negative forward guidance on top-line earnings, costs and growth may offer insights into what outcomes the market has already priced in.

    On a macro level, seeing a sustained moderation in forward-looking inflation indicators will be crucial to pinpoint the potential top-end for interest rates, as it provides some scope for the Fed to temper the pace of monetary policy tightening. Directionally, this means less headwinds and more tailwinds for risk assets like stocks.

    For now, we think it is too early to call a market bottom, although we do think we’re close. Valuations are very supportive for many companies, and the outlook for growth and earnings has been significantly reset over the last six months, not just in equities, but also across many asset classes.

    Grant Bowers,
    Portfolio Manager, Franklin Equity Group,
    Franklin Templeton
  • Best Unit Trust In Malaysia

    Best Unit Trust In Malaysia

    With so many options when it comes to unit trust, it won’t be easy to come out with a list of the best unit trust in Malaysia. Nevertheless, here are some of the best unit trust in Malaysia.

    Source: FSMOne Recommended Unit Trusts Awards 2022/2023

    There were a total of 44 categories to emerge as the best unit trust in Malaysia. In total, there were 5 broad categories: Core Equity, Core Fixed Income, Balanced, Supplementary Portfolio and Private Retirement Scheme (PRS).

    The winner for Core Equity – Global category, goes to Manulife Global Thematic Fund by Manulife Investment Management (M) Berhad.

    The winner for Core Equity – Global (Islamic) is abrdn Islamic World Equity Fund by abrdn Islamic Malaysia Sdn Bhd.

    The winner for Core Equity – Global Emerging Markets is won by Eastspring Investments Global Emerging Markets Fund by Eastspring Investments Berhad.

    Two winners for Core Equity – Asia ex-Japan, one goes to Affin Hwang Select Asia Pacific (ex Japan) Dividend Fund by Affin Hwang Asset Management Berhad and the other goes to Principal Asia Pacific Dynamic Growth Fund by Principal Malaysia.

    We also have two winners for the Core Equity – Asia ex-Japan (Islamic) category, won by Affin Hwang Aiiman Asia (ex Japan) Growth Fund by Affin Hwang Asset Management Berhad and Principal Islamic Asia Pacific Dynamic Equity Fund by Principal Malaysia.

    For the Core Equity – Malaysia category, the two winners are Affin Hwang Equity Fund by Affin Hwang Asset Management Berhad and KAF Tactical Fund by KAF Investment Funds Berhad.

    Core Equity – Malaysia (Islamic) category have two winners as well: Affin Hwang Aiiman Growth Fund by Affin Hwang Asset Management Berhad and PMB Shariah Premier Fund by PMB Investment Berhad.

    Moving on to the Core Fixed Income, the Core Fixed Income – Malaysia category have two winners: KAF Bond Fund by KAF Investment Funds Berhad and Manulife Investment Bond Fund by Manulife Investment Management (M) Berhad.

    Core Fixed Income – Malaysia (Islamic) was won by AmanahRaya Syariah Trust Fund by AmanahRaya Investment Management Sdn Bhd.

    Next up we have the Balanced category, with Balanced – Global won by RHB Asset Management Sdn Bhd with its RHB Global Allocation Fund.

    Balanced – Asia ex-Japan winner is Principal Asia Pacific Dynamic Mixed Asset Fund by Principal Malaysia.

    Balanced – Malaysia category was won by Affin Hwang Select Balanced Fund by Affin Hwang Asset Management Berhad.

    Finally, Pheim Unit Trusts Berhad won the Balanced – Malaysia (Islamic) with its Dana Makmur Pheim.

    Under Supplementary Portfolio, the winner for Sub Regional Equity – ASEAN is Principal ASEAN Dynamic Fund by Principal Malaysia.

    Sub Regional Equity – ASEAN (Islamic) was won by ASEAN Equity Fund by Saturna Sdn Bhd.

    The Sub Regional Equity – Greater China was won by Principal Malaysia with its Principal Greater China Equity Fund.

    Sub Regional Equity – Greater China (Islamic) category winner is Eastspring Investments Dinasti Equity Fund by Eastspring Investments Berhad.

    Sub Regional Equity – Europe was won by Europe Equity Growth by AmFunds Management Berhad.

    Single Country Equity – US winner is Manulife Investment U.S. Equity Fund by Manulife Investment Management (M) Berhad.

    Single Country Equity – China category winner is RHB Asset Management Sdn Bhd with its RHB Big Cap China Enterprise Fund.

    Single Country Equity – Japan was won by Affin Hwang Asset Management Berhad with its Affin Hwang World Series – Japan Growth Fund.

    Single Country Equity – Singapore was won by Singapore Dividend Equity Fund by Nikko Asset Management Asia Limited.

    The Sector Equity – Asia ex-Japan Small to Medium Companies category winner is Affin Hwang Select Asia (ex Japan) Quantum Fund by Affin Hwang Asset Management Berhad.

    Sector Equity – Malaysia Small to Medium Companies winner is KAF Investment Funds Berhad with its KAF Vision Fund.

    Meanwhile Sector Equity – Malaysia Small to Medium Companies (Islamic) category was won by Kenanga Investors Berhad with its Kenanga Shariah Growth Opportunities Fund.

    Then we have Kenanga Investors Berhad winning the Sector Equity – Malaysia Focused with its Kenanga Growth Fund Series 2.

    The winner for Sector Equity – Global ESG (Water Theme) is Manulife Investment Management (M) Berhad with its Manulife Global Aqua Fund.

    Sector Equity – Global Healthcare category winner is Manulife Global Healthcare Fund by Manulife Investment Management (M) Berhad.

    TA Investment Management Berhad wins in the Sector Equity – Global Technology category with the TA Global Technology Fund.

    Maybank Asset Management Sdn Bhd wins in the Fixed Income – Global (Islamic) with its MAMG Global Income-I Fund.

    There were two winners in the Fixed Income – Asia ex-Japan category: Affin Hwang Asset Management Berhad with its Affin Hwang Select Bond Fund and AmFunds Management Berhad with its AmTactical Bond.

    Under the Fixed Income – Emerging Markets category, RHB Asset Management Sdn Bhd emerge victorious with the RHB Emerging Markets Bond Fund.

    Fixed Income – Malaysia (Short Duration) category saw that AmFunds Management Berhad wins with its AmIncome Plus.

    In the Fixed Income – Malaysia with Foreign Exposure category, AmFunds Management Berhad won it with the AmDynamic Bond.

    In the Private Retirement Scheme (PRS), there were a total of four categories. Affin Hwang Asset Management Berhad wins the Private Retirement Scheme – Moderate with its Affin Hwang PRS Moderate Fund.

    Next we have AIA Pension and Asset Management Sdn Bhd winning the Private Retirement Scheme – Growth category with AIA PAM – Growth Fund.

    The Private Retirement Scheme – Moderate (Islamic) category was Manulife Investment Management (M) Berhad picking it up with its Manulife Shariah PRS-Moderate Fund.

    Last but not least, Manulife Investment Management (M) Berhad wins the Private Retirement Scheme – Growth (Islamic) with its Manulife Shariah PRS-Growth Fund.

    How The Best Unit Trust Was Selected?

    The winners were chosen using a meticulous selection process that involves quantitative and qualitative criteria.

    Performance

    The most objective way to determine the quality of the fund manager is to assess the fund’s historical performance, a factor we weigh heavily in our fund selection exercise. For this, we consider both the magnitude of performance as well as the consistency of returns. In the case of new funds which feed into their overseas target funds with a longer track record, we may assess the target fund’s performance. We recommend funds which have at least a 3-year track record.

    Expense Ratio

    The expense ratio is what investors pay for the management of their fund on an annual basis. This charge is deducted from the value of the unit trust, and it takes into account all the operating expenses that a fund incurs, including its annual management fee, administration costs as well as trustee and custodian fees. Generally speaking, the lower the expense ratio, the better it is for you, because you are incurring less costs.

    Risk

    Instead of purely using standard deviation as the measure of risk, we believe that it is more appropriate to focus on how well a fund holds up during periods when the relevant markets saw substantial decline. As such, in our assessment of risk, we focus on the maximum decline of a fund over a given period, and also incorporate a measure of downside volatility, which tells us how volatile a fund is over periods when it is losing value.

    Bond Funds

    Equity funds usually track well-known stock market benchmarks, making it easier to compare funds invested in a similar region or country. Bond funds are less comparable, given their differentiated focus on credit, country selection, currency and duration. To reflect the emphasis on stability in fi xed income investments, we assign different weightings to the three quantitative parameters as shown below.

    Other Qualitative Criteria

    In addition to looking at the above-mentioned quantitative parameters, we also consider other qualitative factors in our analysis, including the fund manager’s consistency in their investment approach, the departure of key personnel as well as the stability of the management team. We also incorporate our outlook on the fi xed income market to assess the merits and disadvantages of a bond fund.

    As most of the funds which invest in other regions buy companies that predominantly have their assets and earning streams denominated in foreign currencies, there is currency risk involved. A gain in the MYR against another currency may reduce the returns of the funds exposed to other currencies, while a drop in the MYR against other currencies would increase the returns. Thus, qualitative analysis is a necessary step to distinguish
    funds with superior management ability from those which were beneficiaries of strong market or currency movements.

    As we take into account the qualitative factors, the highest scoring fund based on quantitative assessment in a particular category may not necessarily be the fund we recommend, although fund performance remains a significant factor.

    Weightage Of Quantitative Parameters

    Those are some of the best unit trust in Malaysia, but always do your own due diligence before buying any of it.

    Know your risk tolerance, time horizon and capital that you can invest in. A unit trust might be suitable for me, but might not necessarily be suitable for you or others.

  • Is Malaysia Property Still Worth To Invest In?

    Is Malaysia Property Still Worth To Invest In?

    Malaysia property might not be as hot as previous years, but the interest is still there. With the recent hike in interest rates and more hikes expected later this year, the instalment for properties will go up.

    This then begs the question as to whether Malaysia property is still a good investment?

    First of all, let’s look at some stats.

    Malaysian House Price Index

    Source: National Property Information Centre (NAPIC)

    House prices in Malaysia went up by almost 100% from 2010 to 2022 with the average price went up from RM220,154 to RM433,430.

    But there has been a steady decline in recent years caused by the pandemic where demand went down and supply going up. The concept of supply and demand has influenced Malaysia property price to a certain extent.

    Source: National Property Information Centre (NAPIC)

    The number of transactions were seen climbing up towards the end of last year before falling off a little bit.

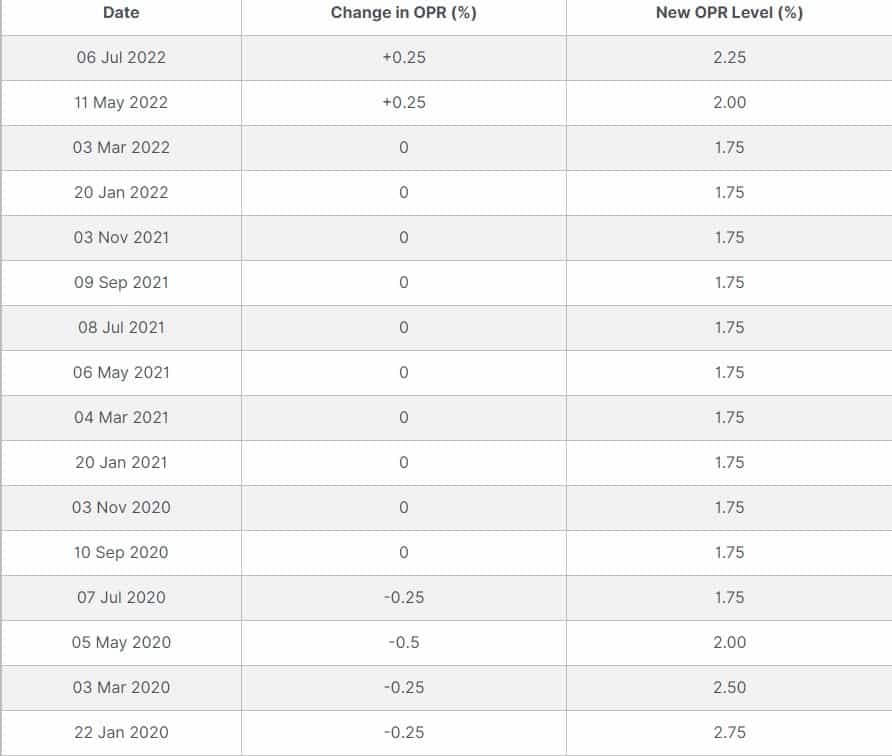
    OPR (Overnight Policy Rate) Is On The Rise

    Source: Bank Negara Malaysia

    Malaysia have been enjoying a very low interest rate since the pandemic begin. But with the recent OPR hike by Bank Negara Malaysia, this would have caused interest rate to rise, and subsequently the monthly instalment for houses to increase as well.

    Analysts are predicting a few more rounds of OPR increase to curb the rising inflation by end of this year, which could cause house purchases to cool off.

    The Rise Of Inflation

    Source: Department Of Statistics Malaysia

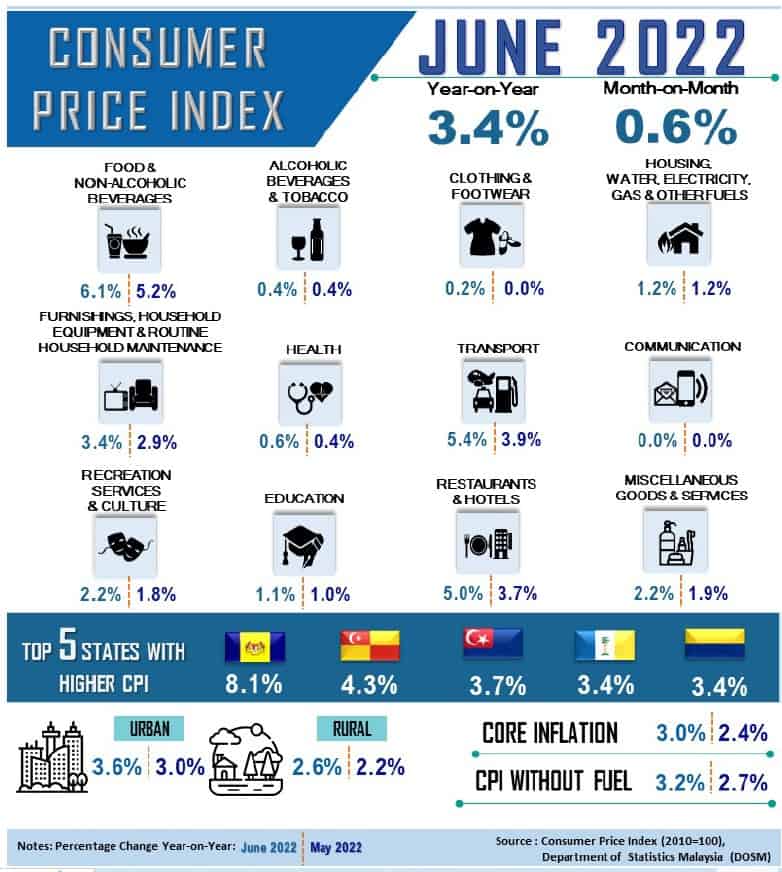
    Malaysia’s inflation increased 3.4%to 127.4 in June 2022 as against 123.2 in the same month of the preceding year. The Food index increased 6.1% and remained as the main contributor to the rise in the inflation during the month of June 2022. 

    When faced with high inflation, there will be lesser disposable income as everyone will be tightening their budget. Only those who have made the necessary preparation and is prioritizing in buying a house over other needs, will buy it.

    The others will then have to rent, so more renters are expected to be on the market.

    Ultimately only you can answer whether Malaysia property is worth investing in. Do you have the holding power? Are you able to find below market value and irresistible deals from the property market?

    As the saying goes, it is about ‘buying low and selling high’. Do your homework and remember the mantra, ‘location, location, location’.

    For more tips and tricks:

    Do you know how much is your Home Loan eligibility? Not sure how much you can borrow from the bank? 

    Get your TechRevo credit report + Home Loan Eligibility which includes:

    • Credit history up to the past 12 months [CCRIS] 
    • Bankruptcy, Legal Suits, Legal action from banks, SAA, and Trade Bureau (Section E)  
    • Max home loan eligibility calculation up to 12 mortgage favorable banks in Malaysia 
    • CCRIS + Credit report + Calculator 

    It only takes 5 minutes. Click here now to get 50% off -> https://www.smartinvestor.com.my/techrevo