RAM Ratings has maintained a stable outlook on the Malaysian insurance and takaful sector, which we expect to stay resilient in the face of a changing landscape, market volatilities and the normalisation of claims towards pre-pandemic levels. Notwithstanding headwinds, the sector is still well-capitalised to absorb potential shocks.
Against this landscape, RAM’s key expectations for the sector this year are:
▪ New business (NB) expansion of 8% for the life and family sector (2022: +3% y-o-y; 2021: +18%). ▪ Earnings recovery in the life and family takaful sector as downside risks recede. ▪ Growth in the non-life sector will be flat at best as car sales are anticipated to decline from last year’s all-time high. ▪ Non-life sector’s claims and combined ratios will normalise to pre-pandemic levels. ▪ Capitalisation will remain sound despite still-elevated market risks (capital adequacy ratio as at end-December 2022: 226%; end-December 2021: 224%)
The slower NB growth of the life and family takaful sector is attributable to a pullback in demand for investment-linked products given challenging investment conditions last year and, to some extent, the expiry of the loan repayment moratorium as the resumption of loan instalments reduced the consumption capacity of individuals. We expect NB generation to pick up pace with growth of 8% this year as expansion of the ordinary life/family segment remains strong (2022: +19%), underpinned by an increased awareness of the need for life and health protection as well as the mortgage insurance/takaful business.
Higher claims and payouts of policy benefits, having climbed 13.5% y-o-y (2021: -0.5%; 2020: +0.8%), dented the sector’s underwriting income last year. This was in line with our earlier expectations that medical claims will rise in tandem with a normalisation in the volume of medical procedures to pre-pandemic levels and medical cost inflation. Coupled with outsized investment-related losses, driven primarily by the spike in Malaysian Government Securities yields amid an environment of steep interest rate hikes, the sector’s bottom line sank to a multi-year low of RM8.6 bil (2021: RM12.9 bil; 2020: RM22.3 bil).
“Some earnings recovery is expected this year even though financial markets could still be volatile in view of global uncertainties. Fluctuations should, however, moderate from levels seen last year,” said Sophia Lee, RAM’s Co-head of Financial Institution Ratings.
The claims ratio of the non-life sector also normalised upwards (2022: 57%; 2021: 51%), largely due to increased motor claims. The weaker claims performance and a heavier cost load culminated in a loftier combined ratio of 92% (2021: 87%). “We expect the combined ratio to stay on the higher end of the 85%-95% historical range moving forward, as the claims ratio nudges closer to pre-Covid levels and margins are compressed further amid rife competition,” Lee adds. The non-life sector charted stellar growth of 12% in 2022 (2021: +3.8%; 2020: -0.1%) on account of all-time high car sales – which would unlikely repeat this year – and improved economic conditions. The sector’s growth will be flat at best in 2023.
On a separate note, Malaysian Financial Reporting Standard (MFRS) 17 Insurance Contracts, which outlines new requirements on recognition and measurement of insurance revenue and liabilities, came into effect on 1 January 2023. The complex accounting standard has entailed a major overhaul of processes and systems and will remain burdensome, with players having to maintain two books – one based on the new standard and another on the previous standard for regulatory capital purposes. “However, the profitability of insurance contracts does not change with the new standard although the manner in which revenue and profits are recognised would differ,” said RAM rating specialist Loh Kit Yoong.
The revival of mergers and acquisitions (M&A) activity after a lull may also see shifts in market dynamics, particularly in the non-life industry where there has been some degree of market consolidation after the respective AmGeneral-Liberty and Generali corporate exercises. Following the completion of FWD Group’s acquisition of a 70% stake in Gilbraltar BSN Life and news of potential M&As (Berjaya-MCIS and Tokio Marine’s plan to dispose of Southeast Asian operations) in the last few months, there could be further activity on this front.
The evolving operating landscape with ongoing structural reforms, complex MFRS 17 implementation, and increased M&As mean that players will have to up their game to stay competitive, even while navigating these challenges. The push for digital and more innovative solutions through Bank Negara Malaysia’s (BNM) financial technology sandbox – together with better financial literacy, and efforts to simplify protection products and improve affordability and accessibility – would culminate in higher insurance/takaful penetration in the long run (measured by premiums to GDP; BNM’s Financial Sector Blueprint target of 4.8%-5.0% against RAM’s 2022 estimate of 4.6%).
About RAM Rating Services Berhad (RAM Ratings)
Established in 1990, RAM Ratings is a leading credit rating agency registered under the Securities Commission’s Guidelines on Credit Rating Agencies. In addition to the provision of credit ratings for corporate bonds and sukuk and their issuers, RAM Ratings also provides research and publications on Islamic finance, fixed income and macro-economic and industry analysis as well as data analytics relating to credit risk, counterparty assessments and other related domains.
Suruhanjaya Sekuriti Malaysia (SC) mempelawa para sarjana untuk memohon penyertaan dalam Program Felo Sarjana Tamu (SIR) ke-12 dalam bidang Kewangan Islam, di Pusat Pengajian Islam Oxford (OCIS) bagi sesi akademik 2023/24.
Program SIR terbuka kepada ahli akademik atau pengamal yang berkebolehan dalam menjalankan penyelidikan gunaan secara bebas mengenai topik kontemporari yang berkait rapat dengan pasaran modal Islam.
Bidang keutamaan termasuk kewangan sosial Islam, pelaburan berimpak, teknologi kewangan, kewangan peralihan dan yang berkaitan dengan pelaburan mampan dan bertanggungjawab.
Pemohon yang mempunyai kepakaran dalam kewangan Islam dan/atau disiplin yang berkait rapat dengan pengalaman praktikal yang luas dalam bidang berkaitan adalah digalakkan untuk memohon.
Pemohon yang berjaya dijangka akan menetap selama satu tahun akademik di OCIS mulai Oktober 2023. Sebagai sebahagian daripada program, sarjana terpilih juga sesekali dikehendaki menyampaikan syarahan dan mengadakan seminar, terlibat dalam kajian kolaboratif, dan menyumbangkan tenaga kepada institusi berkaitan.
Program ini adalah sebahagian daripada usaha berterusan SC untuk memacu pembangunan global yang mampan bagi pasaran modal Islam, dengan kepimpinan pemikiran sebagai tonggak utama.
Suruhanjaya Sekuriti Malaysia (SC), sebuah badan berkanun yang melapor kepada Menteri Kewangan, ditubuhkan di bawah Akta Suruhanjaya Sekuriti 1993. Ia merupakan agensi kawal selia tunggal bagi pengawalseliaan dan pembangunan pasaran modal. SC mempunyai tanggungjawab langsung untuk menyelia dan memantau aktiviti institusi pasaran, termasuk bursa dan rumah penjelasan, dan mengawal selia semua individu yang dilesenkan di bawah Akta Pasaran Modal dan Perkhidmatan 2007. Maklumat lanjut mengenai SC boleh didapati di laman sesawangnya di www.sc.com.my. Ikuti SC di twitter di @SecComMy untuk perkembangan terkini.
Landskap pelaburan hari ini mempunyai banyak cabaran. Persekitaran ekonomi semasa yang berinflasi tinggi dan kos sara hidup yang lebih tinggi telah mengakibatkan peningkatan ketidaktentuan di dalam pasaran kewangan. Sementara itu, populasi yang semakin berumur menambah tekanan terhadap simpanan persaraan. Kesan daripada trend global ini, rakyat Malaysia menjadi semakin terdedah di dalam perjalanan pelaburan mereka.
Institute for Capital Market Research Malaysia (ICMR) telah menjalankan kajian di seluruh negara untuk lebih memahami keterdedahan zaman baru ini. Kami mendapati punca bagi kelemahan pelabur datang daripada pelbagai sudut dan boleh dikelaskan secara amnya kepada tiga kategori berdasarkan ciri-cirinya. Dalam artikel ini, kami akan meneroka kategori pertama dan yang paling biasa: tingkah laku kewangan dan kebolehcapaian.
Lebih Banyak Keputusan, Lebih Letih
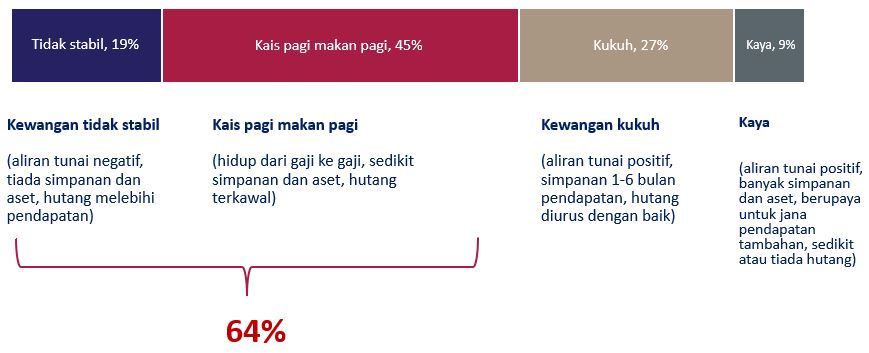
Penemuan tinjauan kami mendapati bahawa kebanyakan pelabur Malaysia mengalami kelemahan disebabkan oleh tingkah laku kewangan mereka dan kebolehcapaian terhadap produk dan perkhidmatan kewangan. 93% daripada responden yang dikaji mempunyai tiga atau lebih tingkah laku dan akses yang boleh membuatkan mereka berasa terdedah, termasuklah persepsi mereka tentang status kewangan mereka sendiri, tingkah laku simpanan dan celik kewangan.
Daripada sudut persepsi status kewangan, kebanyakan rakyat Malaysia melaporkan bahawa mereka tidak stabil daripada segi kewangan atau hidup kais pagi makan pagi, yang mempengaruhi tahap tekanan kewangan dan kesejahteraan mereka. 74% daripada mereka yang tidak stabil daripada segi kewangan dan 54% yang hidup kais pagi makan pagi, mengaku bahawa mereka sentiasa berasa tertekan dan bimbang apabila memikirkan tentang masa depan kewangan mereka.
Jadual 1: Status Kewangan Yang Dirasa (Sumber Data: ICMR)
Kajian tingkah laku terdahulu telah menunjukkan bahawa semakin banyak keputusan yang terpaksa dibuat, semakin banyak keletihan yang terhasil, seterusnya membawa kepada kualiti membuat keputusan yang semakin merosot – sebuah konsep yang dikenali sebagai keletihan keputusan. Lebih-lebih lagi, individu yang kerap mengalami tekanan kewangan cenderung mengalami keletihan membuat keputusan yang lebih teruk berbanding individu lain.
Sememangnya, 61% daripada mereka yang tidak stabil daripada segi kewangan dan 42% daripada mereka yang hidup kais pagi makan pagi mengakui bahawa mereka mengalami keletihan mental apabila memikirkan tentang perancangan kewangan dan lebih suka untuk mengikut keputusan ahli keluarga dan rakan-rakan mereka. Seperti yang ditonjolkan di dalam artikel kami sebelumnya, ini menyebabkan mereka lebih terdedah kepada penipuan, diperdaya dan mencipta gelembung pelaburan.
Tidak Cukup Simpanan Untuk Waktu Sukar
Di samping status kewangan, ICMR juga berusaha untuk memahami tingkah laku simpanan rakyat Malaysia, memandangkan betapa pentingnya untuk mempunyai simpanan yang mencukupi bagi memastikan daya tahan kewangan terhadap sebarang kejutan dalam kehidupan yang tidak dijangka. Berdasarkan panduan oleh Kumpulan Wang Simpanan Pekerja (KWSP), adalah disyorkan bahawa rakyat Malaysia mempunyai sekurang-kurangnya 20% simpanan bulanan dan 6 bulan simpanan kecemasan.
Satu andaian biasa ialah rakyat Malaysia secara amnya tidak mengetahui tanda aras simpanan ini, tetapi penemuan ICMR mencadangkan sebaliknya. Walaupun 43% responden tahu bahawa mereka harus menyimpan 20% daripada pendapatan bulanan mereka, hanya 23% yang benar-benar mengikutinya. Begitu juga dengan dana kecemasan, 34% tahu bahawa mereka memerlukan simpanan sebanyak 6 bulan atau lebih, tetapi hanya 22% yang mendakwa mempunyai jumlah tersebut untuk kecemasan.
Jadual 2: Tingkah Laku Simpanan dan Simpanan Kecemasan
Satu lagi andaian ialah mereka yang berpendapatan tinggi boleh menyimpan paling banyak, manakala tekanan kewangan biasanya dikaitkan dengan mereka yang berpendapatan rendah. Kajian kami sekali lagi mencabar andaian ini, kerana penemuan kami menunjukkan bahawa 68% responden di dalam kumpulan berpendapatan tinggi menyimpan kurang daripada 20% pendapatan bulanan mereka dan 76% mempunyai simpanan kecemasan kurang daripada 6 bulan.
Memandangkan rakyat Malaysia sedang bergelut untuk menyimpan secara tetap dan tidak mampu untuk menampung kewangan mereka semasa waktu sukar, adalah sukar untuk mengharapkan mereka untuk menunjukkan tabiat menyimpan yang lebih baik bagi matlamat jangka masa panjang seperti persaraan. Ini kemudiannya membawa kepada faktor lain yang mentakrifkan kelemahan pelabur di Malaysia – simpanan persaraan atau kekurangannya.
Kurangnya Persediaan Persaraan
Berdasarkan andaian bahawa seseorang itu akan bersara pada umur 55 tahun dan jangka hayat di Malaysia ialah 75 tahun, simpanan seseorang itu perlu bertahan sekurang-kurangnya 20 tahun. Walau bagaimanapun, apabila kami bertanya kepada responden kami berapa lama mereka menjangkakan simpanan semasa dan simpanan KWSP mereka akan bertahan selepas bersara, 75% berpendapat bahawa jumlah simpanan persaraan mereka akan bertahan kurang daripada 20 tahun yang diperlukan selepas bersara nanti.
Punca utamanya adalah disebabkan oleh kekurangan simpanan persaraan, terutamanya dalam kalangan pesara dan pekerja gig. 62% pekerja gig yang ditinjau mendakwa mempunyai simpanan persaraan kurang daripada RM50,000, dan yang lebih membimbangkan ialah 70% pesara yang dikaji mempunyai simpanan persaraan kurang daripada RM250,000 – lebih rendah daripada anggaran KWSP untuk menampung keperluan asas selama 20 tahun selepas bersara.
Jadual 3: Simpanan Persaraan mengikut Kumpulan Umur
Walaupun mereka yang berumur 40 tahun dan ke bawah cenderung untuk memenuhi aras simpanan asas persaraan seperti yang ditetapkan oleh pihak KWSP, sebaik sahaja mereka mencapai umur 41 tahun, lebih separuh daripada pencarum KWSP tidak dapat memenuhi sasaran simpanan asas bagi setiap kumpulan umur. Ini mungkin disebabkan oleh mereka mula mengeluarkan simpanan KWSP mereka untuk pinjaman rumah, pendidikan anak-anak, atau perbelanjaan kesihatan.
Bagi melengkapkan lagi penemuan tinjauan kami, ICMR turut menjalankan temu bual kualitatif dengan pesara di Lembah Klang. Mereka yang ditemu bual berkongsi bahawa mereka tidak tahu apa yang perlu dilakukan dengan jumlah besar simpanan yang boleh diakses oleh mereka selepas bersara. Akibatnya, mereka cenderung untuk melabur secara cuba-jaya dan mengikuti nasihat daripada rakan dan keluarga – di mana ramai yang dibelenggu dengan pelaburan yang gagal.
Terlalu Yakin Tentang Celik Kewangan
Walaupun rakyat Malaysia pada umumnya tidak mempunyai simpanan yang cukup dan tidak bersedia untuk bersara, penemuan ICMR juga menunjukkan bahawa mereka terlalu yakin dengan tahap pengetahuan kewangan mereka. Hanya 39% daripada responden mendapat markah 80% – 100% dalam ujian celik kewangan mudah yang disediakan oleh ICMR – tetapi 67% daripada responden mendakwa sangat yakin dengan keupayaan kewangan mereka.
Topik seperti faedah kompaun, inflasi, risiko dan pulangan, kos peminjaman dan kepelbagaian, dianggap sebagai yang paling asas untuk menguji pemahaman responden tentang beberapa konsep kewangan utama. Walau bagaimanapun, adalah membimbangkan untuk melihat 59% daripada responden yang mendapat markah lebih rendah daripada 80% (kurang daripada 4 soalan betul) berasa sangat yakin tentang keupayaan kewangan mereka.
Kesan terlalu yakin dapat diperhatikan apabila keyakinan subjektif individu terhadap keupayaan mereka sendiri lebih besar daripada prestasi objektif (sebenar). Keyakinan yang berlebihan telah dikaitkan dengan pelbagai isu. Secara umumnya, dalam kalangan pelabur, sikap terlalu yakin telah dikaitkan dengan pengambilan risiko yang berlebihan dan berkemungkinan besar menyebabkan mereka membuat keputusan kewangan yang salah.
Keyakinan berlebihan juga mempunyai kaitan dengan kecenderungan optimisme seseorang semasa membuat keputusan pelaburan atau kewangan yang lebih luas. Bias optimisme merujuk kepada kecenderungan orang ramai untuk menilai terlalu tinggi kebarangkalian kejadian positif dan merendah-rendahkan kebarangkalian kejadian negatif yang boleh berlaku kepada mereka pada masa hadapan. Pemikiran seperti ini adalah berbahaya dan sering menyebabkan pelabur membuat keputusan kewangan yang melulu.
Keterdedahan Pelabur Adalah Pelbagai
Membuat keputusan kewangan yang baik bukanlah tugas yang mudah bagi kebanyakan orang. Mereka perlu mengatasi kecenderungan berat sebelah dan mempertimbangkan kepuasan keuntungan jangka masa pendek terhadap perkara yang bermanfaat untuk jangka masa panjang. Cabaran untuk membuat keputusan kewangan yang baik menjadi lebih sukar apabila faktor seperti tekanan kewangan menghalang seseorang daripada membuat keputusan yang optimum dengan fikiran yang waras.
Namun begitu, kajian ICMR menyerlahkan bahawa ‘jenis’ kelemahan yang berbeza kerap bertindih dan berkait rapat – bermakna kesukaran kewangan tidak selalunya mudah untuk dikaitkan dengan satu ‘punca’ tertentu. Nantikan artikel kami seterusnya di mana kami meneroka bagaimana keadaan situasi dan isu berkaitan industri juga boleh menyebabkan kelemahan baru bagi pelabur Malaysia.
Artikel ini adalah sebahagian daripada siri kandungan oleh Institute for Capital Market Research (ICMR). Ikuti laman Facebook ICMR untuk mendapatkan info terkini tentang petua tingkah laku dan pandangan, untuk tabiat pelaburan yang lebih baik. Untuk mengetahui lebih lanjut mengenai kajian ICMR ke atas milenial dan Gen Z, layari www.icmr.my atau muat turun laporan penuh di sini.
Insurance is a means of protection from financial loss where a party agrees to compensate another party in the event of loss, damage, or injury; in exchange for a fee. In other words, insurance is a risk transfer mechanism where you transfer your risk to the insurance company to get coverage for any financial loss you may face due to unforeseen events. The emotional and psychological loss can never be compensated, but at least the financial loss can be compensated with insurance.
Smart Investor spoke to Fabrice Benard, CEO of Generali Insurance Malaysia Berhad and Country Head of Generali Entities in Malaysia to learn more about the current insurance landscape in Malaysia.
Fabrice Benard, CEO of Generali Insurance Malaysia Berhad and Country Head of Generali Entities in Malaysia
Smart Investor: Has the pandemic impacted the insurance industry? What’s the penetration rate for Malaysians?
Fabrice Benard: Definitely, the pandemic has impacted most economic sectors, with very few exceptions. But I would say there is an advantage in such adversity. It has presented new, emerging protection needs, and accelerated innovation, transformation and sustainability practices within the industry.
We also noticed a shifting landscape of insurance awareness during and post pandemic – where many Malaysians are becoming more informed, health conscious and aware of the importance of insurance protection. This has given us an opportunity to protect what matters, address the protection gap and actively reach out to a wider range of customers and communities.
SI: With high inflation, people have less disposable income and might have less to spend on insurance. How can they cope? And is there any help coming from the insurance industry?
FB: As a lifetime partner to our customers, part of our commitment is to bridge the protection gap and extend our protection far beyond our existing customer base. Financial inclusion is important to us, and we want to engage and educate the communities as much as possible and ensure that everyone can receive the protection they need. For example, providing instalment payment plans via our partner banks for selected products to ensure that our products remain affordable.
Besides that, it is also essential to create a value-added service ecosystem to address customer needs. This is deployed via our strong distribution network, strategic partnerships and other type of services: information, prevention, protection, assistance. We also continuously find ways to be more inclusive, yet innovative and personalised in our product offerings to target different customer segments.
For example:
We launched SmartTraveller Enhanced ― the first-in-market travel insurance in Malaysia with pandemic illness coverage up to RM350,000 in view of increasing travel protection needs due to reopening of borders.
Launched SmartMedi Outpatient ― the 1st standalone outpatient medical insurance in Malaysia that offers standalone outpatient coverage for General Practitioner / Simulated Patient clinic visits which does not require hospitalization. It is a complementary product to the In-patient coverage.
Launched Multi Medic – the 1st modular Individual Medical insurance that allows consumers to build the coverage to suit their life stages and financial needs.
The Multi Biz Protector Enhanced – a customisable and comprehensive insurance plan designed for owners of small and medium-sized businesses (SMEs) to cover their key business risks. It is a comprehensive product where most of the risk exposures are covered in this ‘one stop’ package. Customised to their needs, business owners can select their preferred protection needs.
SI: Post-Covid or Long Covid symptoms are considered chronic diseases that insurance might not cover; why is that so?
FB: Post-Covid or long Covid symptoms are common exclusions in the insurance industry. Usually, when it comes to health or medical claims, there needs to be objective medical proof to support the claim. It goes without saying that health insurance only covers conditions where medical attention is absolutely necessary. Long Covid symptoms usually develop after the original Covid infection has cleared, and they can be tricky to measure or assess, especially when it comes to the treatment duration and standards of care.
But beyond claim coverage, we are committed to extend our best support to our customers struggling with long-term Covid symptoms. It is important for us to provide our customers with the care they need, while ensuring our panel medical partners implement appropriate clinical guidelines and practices.
SI: Company insurance only covers you until the age of 60. Is there any insurance for those approaching retirement age and those with disease
FB: While company insurance typically covers up to 60, it is recommended to have a complementary individual comprehensive insurance plan that can keep you protected up to a higher age limit. For example, our comprehensive critical illness plan – CritiCover, do cover up to age 100 with protection against 194 critical illnesses and any future unknown illnesses. This plan will help to ease your financial burden while allowing you to focus on your recovery. Besides that, we also have various other products such as the SmartPA Enhanced and other Individual Health Plans such as SmartCare Optimum Plus that provides coverage up to age 100.
For individuals with health conditions, insurance companies may still offer insurance plans that have additional restrictions or exclusions for certain pre-existing conditions. The type of plans, coverage and premium offering may differs depending on the person’s health status.
SI: Any medical insurance for pregnant ladies and babies? Is it necessary to take such a policy?
FB: Complications such as cardiovascular disease, hypertension etc. may be contracted by pregnant or postpartum ladies, and such diseases may lead to unexpected medical expenses. Having an insurance plan is recommended to ensure you receive the necessary care and support on your recovery.
Though most individual insurance plan do not cover the cost of delivery or normal hospitalisation bill, there are several critical illness insurance plans that cover pregnancy complications.
Aside from the importance of a pregnant lady being insurance protected, having medical insurance for your child is equally important too. Children, especially infants, are susceptible to illnesses and accidents. Medical Insurance can provide peace of mind and security to the parent, knowing that their child will have access to the necessary medical attention when they need it most. For as young as 15 days old, your child can be covered under our comprehensive medical insurance plan – OneMedic Elite, which covers hospitalisation bills incurred should your child requires medical treatment.
SI: Education is getting more expensive. Is education insurance important?
FB: An education savings insurance plan is a type of insurance policy that provides a combination of insurance protection and savings elements, specially designed to help families to save aside for the future cost of education. Such plans allow you to save aside over a period of time, and such savings will be further invested to grow over time and, at the same time, provide regular bonuses to your insurance savings fund. You can access your savings fund to pay for your children’s education expenses. The amount required to set aside for such an insurance plan depends on your target education fund.
Such insurance plan also provide a lump sum payment to the beneficiaries in the event the insured person’s death, disability or diagnosed with critical illness, where such event may prevent your children from completing or paying for your children’s education. This will allow you to focus on their education goals without having to worry about the financial consequences of life’s unexpected events.
To help you to achieve your desired education for your child, our insurance savings plan – Wealth Saver, is designed to help you diversify your savings and achieve your financial goals. With just a short-term commitment of only 4 years, you can enjoy a guaranteed annual income of up to 18% of the sum insured. You will continue to be payable to you or your loved ones in the event of death or Total and Permanent Disability (TPD).
SI: What’s the reason people are not buying insurance? And what can be done to increase awareness of the importance of having insurance?
FB: Many think that insurance is expensive and an unnecessary expense. There are also some who merely see insurance as an investment rather than a form of protection. But insurance works on the principle of risk transfer and pooling – the whole intrinsic idea of insurance is to protect against uncertainties and unexpected risks.
Increasing awareness of this takes a collective effort from all insurers. While continuous educational campaigns are important, we are also looking at providing better insurance experiences as a whole by transforming our role beyond just selling products to providing more value-added, personalised services. Our guiding principle is to make the entire purchase, service, claims, assistance, and renewal effortless and care while ensuring that our customers receive personalised, phygital advice with a human touch for complex matters. We believe this will help bring a better experience and create more avenues for new protection.
Kita akan melihat kepada modus operandi yang digunakan oleh Lidt Cooperation Advertising Sdn Bhd atau Lidl Cooperation Advertising Sdn Bhd. Kedua nama ini merupakan nama palsu yang digunakan untuk memerangkap mangsa.
Di dalam siri pertama, penulis memperincikan tentang bagaimana sindiket penipuan ini menawarkan peluang pekerjaan untuk melanggan saluran di YouTube atau sebagai pembantu promosi produk Shopee manakala pada siri kedua, penulis memperincikan jenis penipuan yang berlaku di Telegram, dan boleh dikategorikan kepada beberapa jenis: pertama, dengan menggodam akaun dan mencuri identiti seseorang, kedua, skim Pelaburan NORDFX Trader yang menjanjikan hasil pulangan yang terlalu sempurna untuk dipercayai.
Dua siri ini ditulis berdasarkan pengalaman penulis sendiri yang menyamar sebagai individu yang ingin mencari peluang pekerjaan dan secara tidak sengaja, menjumpai sindiket penipuan ini dan mengambil keputusan untuk menyiasat dengan lebih lanjut.
Maka ini adalah kesinambungan daripada dua siri yang terdahulu. Apa yang menjadikan perkongsian ini sedikit berbeza kerana ianya merupakan pengalaman seorang mangsa yang mengalami sendiri peristiwa ini. Mangsa juga bersetuju untuk berkongsi pengalaman dengan syarat identiti beliau dirahsiakan.
Mangsa sendiri memberikan kebenaran dan persetujuan untuk menyiarkan pengalaman beliau sebagai satu langkah untuk memberi kesedaran kepada masyarakat di luar sana mengenai kewujudan sindiket-sindiket penipuan seperti ini.
Berikut merupakan perkongsian beliau:
1. Pihak majikan (Lidt Cooperation Advertising Sdn Bhd atau Lidl Cooperation Advertising Sdn Bhd) telah menghubungi saya melalui Whatsapp dengan mengatakan bahawa mereka mendapat maklumat peribadi saya di JobStreet (Gambar 1, kiri). Benar saya dalam usaha untuk mendapatkan peluang pekerjaan, kerana dengan pendapatan semasa sedia ada, saya tidak berkemampuan sama sekali untuk membuat sebarang simpanan
2. Menggunakan enjin carian Google, saya tidak menjumpai sebarang maklumat yang berkaitan dengan organisasi mereka, seperti profil dan nombor telefon syarikat. Carian di JobStreet, LinkedIN, dan Indeed turut menunjukkan hasil yang sama.
3. Mereka akan mengumpan mangsa untuk melakukan tugasan mudah dengan meminta mangsa memberikan “like” kepada beberapa buah video di Youtube, kebiasaanya mangsa akan diminta untuk memberikan “like” kepada tiga video yang berbeza dan akan mendapat RM15 sebagai bayaran atas kerja mereka. Mangsa akan menerima RM15 ini dalam selang beberapa jam (Gambar 2, kanan).
Gambar 1: Kiri (Nombor telefon yang digunakan untuk mengajak dan berhubung dengan mangsa), kanan (perbualan di WhatsApp dengan individu yang mengajak mangsa)
4. Tiada sebarang kontrak (hitam putih) bagi pekerjaan ini. Apatah lagi terma dan syarat yang dikenakan oleh majikan kepada pekerja (ini adalah satu tanda yang mungkin kita boleh perhatikan, ada sesuatu yang tidak kena disini).
5. Tiada proses temuduga berlangsung, sama ada melalui panggilan telefon atau secara atas talian (melalui Zoom, Google Meet, Microsoft Team dan lain-lain). Atas alasan pekerjaan ini adalah pekerjaan sepenuh masa atau separuh masa sahaja (juga adalah satu tanda yang mungkin kita boleh perhatikan, ada sesuatu yang tidak kena disini).
6. Mangsa akan diberikan link Telegram untuk menghubungi pegawai perkhidmatan pelanggan mereka yang bernama Steven (Gambar 3, kiri).
7. Mangsa akan dimasukkan ke dalam satu kumpulan di Telegram sebagai permulaan. Steven akan memberikan mangsa tugasan yang dikategorikan sebagai “PROJECT”. Setiap tugasan akan dapat bayaran. Mangsa akan diperdayakan, dibutakan dengan menerima duit bayaran ke dalam bank mereka hanya dengan membuat tugasan memberikan “like” kepada video sahaja.
8. Mangsa akan diberikan satu tugasan. Dan link untuk tugasan tersebut seperti yang berikut: (https://m.lidlcooperation.com/home). Tetapi, bagi tugasan ini, mangsa akan diminta untuk membayar sejumlah wang sebagai deposit. Dalam kes ini, pegawai perhubungan pelanggan, Steven akan menentukan jumlah deposit tersebut. Mangsa cuma mengikut apa yang diarahkan oleh Steven, tugasan ini mempunyai tiga transaksi. Mangsa tidak diberitahu berapa jumlah deposit yang perlu dikeluarkan sehingga mangsa mencapai RM600 sebagai deposit.
Gambar 3: Kiri (Mangsa diperkenalkan dengan pegawai perhubungan pelanggan – Steven), kanan (mangsa dijemput memasuki kumpulan di dalam Telegram)
9. Mangsa akan terikat membuat tugasan, kerana sistem ini telah direka untuk memerangkap mangsa dan mereka tidak dapat melepaskan diri. Tugasan ini bermula dari tugasan 1, mangsa diminta untuk memberi “like” kepada beberapa video di YouTube. Ini akan berterusan sehinggalah ke tugasan ke-18 yang bersambung dengan tugasan memberikan “like” kepada video.
Pada peringkat ini, setelah mangsa dimasukkan ke dalam kumpulan di Telegram, beberapa akaun palsu yang menyerupai individu-individu yang normal diwujudkan agar memberi tanggapan bahawa ada orang lain turut sama dalam menjalankan pekerjaan ini dan mereka tidak berseorangan. Penglibatan dari akaun-akaun palsu ini amat aktif, seolah-olah mewujudkan persaingan sihat dalam kalangan ahli yang menyertai. Sehingga pada satu ketika, mangsa akan merasa ketinggalan jika tidak turut serta dalam aktiviti mereka ini kerana kelihatan amat meyakinkan.
Walaubagaimanapun, akaun ini sebenarnya dikendalikan oleh bot yang menyerupai/meniru cara percakapan manusia biasa. Selepas itu, Pegawai perhubungan pelanggan mereka akan meminta lagi wang deposit sebanyak RM150. Seterusnya, meminta deposit kedua sebanyak RM2k (ini juga adalah satu tanda yang mungkin kita boleh perhatikan, kerana tidak mungkin ada sebarang peluang pekerjaan yang meminta kita memberikan deposit wang terlebih dahulu untuk mendapatkan bayaran bagi pekerjaan yang telah kita lakukan).
10. Saya tidak mempunyai sejumlah wang dengan nilai tersebut. Dan duit RM600 yang telah saya keluarkan terlebih dahulu untuk tujuan membayar deposit juga tidak dapat dibawa keluar. Sekiranya saya gagal untuk membayar deposit RM2k mereka tidak akan ambil kisah tentang deposit yang awak telah keluarkan sejak dari awal lagi. Akan dikira lesap begitu sahaja.
11. Apabila saya memberi pesanan/chat kepada semua individu di dalam group tersebut, balasan jawapan pesanan mereka adalah seperti keluar daripada “bot”. Menggunakan bahasa Melayu pun mereka tidak mampu, walaupun menggunakan gambar seolah-olah orang tempatan. Mereka akan memberikan jawapan “I don’t even know you“.
Perbualan yang ada di ruangan sembang/chat adalah daripada “bot-bot” sendiri untuk mewujudkan suasana yang biasa dalam kumpulan sembang/chat dan tiada apa-apa yang ganjil mengenainya. Sehingga pada satu ketika, saya telah diberikan amaran oleh pekerja mereka, jika tidak mahu komited membuat tugasan, saya mesti berhenti menganggu orang lain. Ini menandakan bahawa penipuan mereka telah terbongkar dah saya telah mengetahui bahawa mereka ini adalah scammer (Gambar 4, kanan).
12. Mereka telah menendang/mengeluarkan saya dari kumpulan Telegram tersebut. Selepas saya cuba untuk menghubungi semua individu di dalam kumpulan tersebut.
13. Saya cuba untuk menghubungi semula nombor WhatApp yang menawarkan saya pekerjaan sebelum ini. Tidak berjaya kerana mereka telah menyekat nombor telefon saya.
Kesimpulannya, harap mereka yang di luar sana sentiasa berjaga-jaga. Tidak dapat dinafikan, dengan kos taraf hidup yang kian meningkat, komitmen bulanan, dan lain-lain perkara yang di luar jangka menyebabkan pekerjaan hakiki tidak mencukupi untuk kita membuat sebarang tabungan untuk hari-hari kecemasan. Hal ini ditambah apabila kita bekerja di bandar besar seperti Kuala Lumpur, yang sudah pasti kos taraf hidup di sini lebih tinggi berbanding dengan bandar-bandar lain di seluruh Malaysia.
Namun, dalam mencari rezeki dan pendapatan sampingan, kita perlu sentiasa berjaga-jaga dan beringat dan ambillah ikhtibar atas pengalaman ini. Saya telah dibutakan dengan duit mudah, kerja yang cukup mudah menyebabkan saya hilang pertimbangan dan menjadi mangsa. Apabila berdepan dengan tawaran pekerjaan yang terlalu sempurna untuk berlaku di alam nyata ini, rujuklah kepada rakan-rakan yang terdekat, jangan mengambil keputusan secara melulu tanpa memikirkan akibat atas tindakan yang kita ambil ini.
Saya juga berasa kasihan kepada gambar-gambar individu yang digunakan sebagai alat penipuan, yang diletakkan sebagai profil gambar bot-bot. Sedikit nasihat daripada saya, jangan berkongsi gambar-gambar peribadi kita secara berlebihan, dua-tiga keping gambar mungkin mencukupi, kerana ada kemungkinan gambar-gambar peribadi akan digunakan oleh pihak-pihak yang tidak bertanggungjawab sebagai alat penipuan di luar pengetahuan kita sendiri.
Mengenai Penulis
Rashid Ating. Penyelidik di Jabatan Ekonomi, Fakulti Perniagaan dan Ekonomi, dan Institut Pengajian Termaju (IAS), Universiti Malaya (UM), Kuala Lumpur.
YesHello (DIGITAL AUTOMATE SDN BHD) is a SaaS platform that gives small businesses total customer visibility—from first contact, to sales, to support. Making customer engagements more precise, contextual, and purposeful. They are powering the communication engine at Volvo Malaysia, Jaguar, Land Rover, BYD, TeaLive, SIRIM Bhd, Beam Mobility Scooter, Sustainable Energy Development Authority (SEDA), Asia e-University and many more.
Smart Investor spoke to Carliff Rizal Carleel, Founder & CEO of YesHello to learn more about them.
Carliff Rizal Carleel, Founder & CEO of YesHello
Smart Investor: Can you provide an overview of YesHello.chat and its mission in the industry?
Carliff Rizal Carleel: We help modern Small Businesses that are overwhelmed communicating with customers online, install a systematic way to offer Predictably Great Customer Engagement. We help them create Visibility and Precision for Remote Teams by implementing a clear strategy that makes it simple for team members to respond to customers faster.
Technology can be frustrating and we remove that (As Regular group chats are slowing down small businesses). By working with us, teams GET SUPPORT & TOOLS to manage their internal and external communication in a TRANSPARENT & ORGANISED way.
SI: What specific problem does YesHello.chat aim to solve or address?
CRC: Three main problems. 1. Multiple Conversations, Multiple People, on Multiple Channels. 2. Teams Lacking Full Context when replying to customers. 3. Working alone. As more and more teams are going remote, team members feel more isolated and alone than ever before.
SI: How does your platform differentiate itself from other customer engagement solutions?
CRC: Most other platforms focus on either just email, or just social media, or just WhatsApp. We understand that modern customer engagement needs to address all channels. Most other platforms focus on the communication between the business and the customer.
But we understand that it’s the internal communication between team members in a transparent and collaborative way that will transform a team from ordinary to extraordinary.
SI: Can you share some success stories or case studies of companies that have benefited from using YesHello.chat?
CRC: We helped Peche Empire (a cosmetics company) double their revenues from 200k to 400k in 6 weeks. We helped Carnival Internet (Broadband provider from Bangladesh) increase the number of clients they can support from 400,000 users to 800,000 users without increasing the number of support team members.
We helped Volvo Bukit Bintang increase sales by 30% ever since they started including YesHello for their sales process.
SI: How does YesHello.chat utilise technology to enhance customer interactions and experiences?
CRC: YesHello is a cloud software platform for small business that captures all customer interactions across WhatsApp, and all social media (email, Facebook Messenger, Instagram DMs, WeChat, Telegram, Viber, Line, SMS, Twitter, website live chat, and phone)—contextualises all customer interactions to help teams close more sales.
Integrating all channels into one seamless dashboard is no small feat. We are able to create a single customer story containing every message, email, web chat and internal discussion creating a platform for messaging across the entire customer life cycle.
SI: What are the key features or functionalities that make YesHello.chat stand out in the market?
CRC: 1. Utilising Promotional Messaging, we are able to target specific interests with Broadcasts, enroll new contacts in drip campaigns and trigger event-based promotions via API.
2. Conversational Sales is the future. Upgrade from personal messengers to business accounts, increase sales visibility, auto-qualify leads & sync with your CRM.
3. Conversational Support. Use automated messaging to identify customer issues, then route to team members according to skill, function, language, shift & more.
4. Automate Transactional Notifications. Trigger abandoned cart messages, payment confirmations, order updates and more from platforms like Shopify and other marketplaces..
SI: How much funds are you seeking to raise through this fundraising exercise in collaboration with Beyond4 Fund 1?
CRC: We are seeking to raise RM1 million
SI: How do you plan to use the funds raised through fundraising for business expansion?
CRC: We will be utilising the funds mainly for our marketing push to get our brand known in the market and to acquire customers. Our goal is to get from our current Annual Recurring Revenue of RM350,000 to RM2,000,000 by first quarter 2024.
And to do this we only need to increase our customer base from 75 small businesses to 300 businesses. The funds raised will also allow us to hire key support staff and growth specialists to support our growth.
SI: What are your target markets and customer segments for YesHello.chat?
CRC: YesHello best serves SMEs that prioritise customer relationships (Edu, Wellness, Auto, Professional Services). For SMEs that need to focus on their business and not focus on handling tech. For SMEs that want a proven system in place and not have to experiment with something that might or might not work.
For SMEs that requires an affordable solution so they don’t need to pay for software they might not even use. With YesHello, SMEs can grow, and we grow with them.
SI: Can you provide insights into the growth and traction that YesHello.chat has achieved so far?
CRC: YesHello started during the lockdown in 2020. Ever since we started, our total revenues have reached over RM1 million.
SI: What strategies do you have in place to acquire and retain customers in a competitive landscape?
CRC: We use our own solution. And because we have the tools to take advantage of social channels, we mainly focus on digital ads that are directly connected to the YesHello platform for seamless transition from ads to engagement to conversion and customer success. Also because of this, our retention rate is at 98%. Most SMEs that come on board and use our solution are so positively impacted that they never consider to stop using us.
Our total belief in what we can do to help SMEs, coupled with our extreme focus on customer success is the reason why our clients love us. This is proven by their testimonials and the fact they would never go to another platform.
SI: How does YesHello.chat ensure data privacy and security for its users and their customers?
CRC: YesHello takes security and privacy seriously. That is why we have created the safest possible processes available to ensure that our service is stable and that there are no security gaps. The integrity of your data is ensured. YesHello meets industry standards to protect you and your data.
1. Cloud Security. YesHello is a cloud-based solution, Amazon Web Services (AWS). All stored and transferred data is encrypted. All data is safely stored and backed up on servers that follow the latest SSAE reporting standards. Systems are DDoS protected and hardened with firewalls.
2. SSL Encryption. YesHello’ data is encrypted both when it is sent to and from our servers, as well as when it is at rest. To protect your content in transit, YesHello uses 256-bit SSL/TLS encryption. At rest, YesHello content is protected using 256-bit AES encryption.
3. Network Security. YesHello regularly updates its network architecture and data flows between systems. Firewall rules and access restrictions are reviewed for suitability on a regular basis. We constantly provide system improvements to prevent vulnerabilities.
4. Backup & Recovery. Our infrastructure is designed to provide stability and to minimize service interruption due to hardware failure, natural disaster, or other catastrophes. To help ensure availability in the event of a disaster, we replicate data across multiple data centres. Our system automatically backups the database daily.
5. Access Control. Administrative sharing controls let you decide who in your organization has access to the platform. Add multiple users with different roles to allow access without having to share your private login details. Under no circumstances is sensitive data shared with anyone outside of YesHello and the client.
SI: Can you share any partnerships or integrations that have contributed to the success of YesHello.chat?
CRC: Yes, we have partnered with TM, Yellow Pages, Sunway iLabs, WOMENTUM.
SI: How do you envision the future of customer engagement and the role that YesHello.chat will play in it?
CRC: We believe that Selling By Chat is the Future. YesHello makes selling by chat easier for small businesses by capturing all customer chats across WhatsApp, and all social media into one place. Teams now have real-time visibility into all sales conversations to help each other close deals faster. We make Selling By Chat More Collaborative, Contextual, and Precise.
YesHello records and tracks customer-facing interactions across WhatsApp, all social media channels, website live chat, phone, and email to bring you transparent activity data. YesHello’s cloud platform ties conversations to outcomes logged in your CRM to capture what sets top performers apart. This total Visibility and Precision for SMEs is what will be the norm for all businesses doing business online.
SI: What challenges do you anticipate in scaling your business and expanding into new markets?
CRC: There are many big players in this space and I foresee other companies raising large sums and outspending other competitors as the main challenge in the future.
SI: How do you measure the effectiveness and impact of customer engagement using YesHello.chat?
CRC: We believe having full context, from lead source, full customer history, past purchases, all conversations, and previous issues—empowers teams to make decisions based on the full-story instead of guess-work. This is the key to building long term meaningful customer connections.
Drive change with confidence. Know from day one why your initiative is succeeding or failing, and course correct in real-time to meet revenue goals. Create a culture of coaching. Coaching only drives revenue if managers provide it consistently across their teams. Keep managers accountable to providing valuable feedback with whisper support.
Unparalleled pipeline visibility. Integrate your entire tech stack so data goes from siloed to streamlined, ensuring that all customer interactions are unified and up-to-date.
SI: What are the key metrics or KPIs that you track to assess the performance of your platform?
CRC: Speed to first reply is one big metric we most often measure. This is key as customers always prioritise speed.
SI: How does YesHello.chat incorporate customer feedback and suggestions into its product development?
CRC: Our team communicates with our customers on a regular basis via messaging channels, Zoom and phone calls. All their input and feedback is noted down and is considered when we are developing new features for our platform. All this is transparent on our product roadmap.
SI: What are your long-term goals and vision for the growth of YesHello.chat?
CRC: By 2027 YesHello will expand to the majority of SEA and Europe with a customer base of 30,000 SMEs using our platform generating over $200Mil in Annual Recurring Revenues.
SI: How do you approach customer support and ensure a seamless experience for your users?
CRC: We use our own solution. And because of this, our retention rate is at 98%. Most SMEs that come on board and use our solution are so positively impacted that they never consider to stop using us. Our total belief in what we can do to help SMEs, coupled with our extreme focus on customer success is the reason why our clients love us.
This is proven by their testimonials and the fact they would never go to another platform.
SI: Lastly, what message would you like to convey to potential investors who are considering supporting the expansion of YesHello.chat?
CRC: Nothing meaningful came from being timid. We all know Selling by Chat is the future! YesHello makes selling by chat (SBC) more Collaborative, Contextual, and Precise. YesHello is a sales engagement/enablement/management platform for small business teams (who mainly close + sales via chat). YesHello helps sales close more deals by shining the light on everyone’s conversations with customers. It records all conversations from first contact, to sales, to support, creating total visibility so leaders can drive sales effectiveness across the entire organisation.
Soon all SMEs will be utilising this. Now is the time to get onboard and support a local Malaysia startup, and you can say you were there when it all started! You can say that you saw it when no one else did. And that you were courageous enough to take the leap, when others were afraid.
The Securities Commission Malaysia (SC) is encouraging wider adoption of financial technology (fintech) in agriculture in order to help in achieving the country’s food security agenda.
SC Chairman Dato’ Seri Dr. Awang Adek Hussin said access to finance is critical to agriculture’s future.
This is especially important for smallholders and agritech-preneurs seeking to modernise agriculture and strengthen research and development, he said in his opening address at the SCxSC Grow Fintech Conference.
This marks the 10th iteration of the SCxSC conference that is held in-person after the Covid-19 pandemic.
SCxSC GROW, is a new collaborative programme, under the SC’s fintech flagship initiative “Synergistic Collaboration by the SC” (SCxSC). The SCxSC GROW embodies a collaborative effort with partners in the fintech ecosystem to harness the potential of alternative financing digital platforms to meet the needs of micro, small, and medium-sized enterprises (MSME) in strategic sectors.
Recognising the challenges faced MSMEs in the agriculture sector, Dato’ Seri Dr. Awang Adek said that leveraging fintech solutions will help improve access to financing and increase efficiency in the sector.
Dato’ Seri Dr. Awang Adek Hussin, SC Chairman
To achieve this goal, the SC has been working closely with ecosystem players to develop innovative solutions that cater to the unique financing needs of farmers and agribusinesses. This is in tandem with the national agenda to support the agriculture sector’s transition into a dynamic and progressive sector. Dato’ Seri Dr. Awang Adek said that the capital market can be an enabler and accelerator to help Malaysia achieve its food security agenda.
“Alternative financing avenues such as equity crowdfunding (ECF) and peer-to-peer (P2P) financing allow investors with the right risk appetite to mobilise capital directly for agri-preneurs,” he said.
This provides more options for younger and high-growth companies to access capital relevant to their business risk profiles,” he added.
Over 7,000 MSMEs have benefited from SC-registered ECF and P2P financing since their introduction in 2015, raising more than RM4.4 billion, with only 600 agri-related MSMEs across the entire value chain raising close to RM300 million. This presents a significant opportunity for agricultural growth and investment.
Dato’ Seri Dr. Awang Adek said, “Malaysia was also the first country in this region to adopt a co-investment model, MyCIF specifically for alternative finance platforms.”
MyCIF was instrumental in providing MSMEs with financing during the Covid-19 pandemic.
“MyCIF implemented a special allocation ratio of 1:2 for the agriculture sector in 2022, which is more appealing than the normal ratio of 1:4. We’ve seen increased interest as four times as many agri-businesses have raised funds through ECF and P2P platforms,” he added.
The SCxSC GROW Fintech Conference, themed “Fostering Innovative Finance in Agriculture”, aims to be a game-changer for the agriculture industry. With the world facing increasingly complex challenges, the conference brings together agriculture and fintech players to explore innovative solutions to food security, sustainability and supply chain resilience.
New cutting-edge solutions were showcased at the conference, highlighting the latest advancements in these fields. The conference also featured local fintech players in the agriculture sector.
These fintech solutions have the potential to revolutionise the way farmers access financing and manage their operations, enabling them to make better use of resources and increase yields.
About the Securities Commission Malaysia:
The Securities Commission Malaysia (SC), a statutory body reporting to the Minister of Finance, was established under the Securities Commission Act 1993. It is the sole regulatory agency for the regulation and development of capital markets. The SC has direct responsibility for supervising and monitoring the activities of market institutions, including the exchanges and clearing houses, and regulating all persons licensed under the Capital Markets and Services Act 2007. More information about the SC is available on its website at www.sc.com.my. Follow the SC on twitter at @SecComMy for more updates.
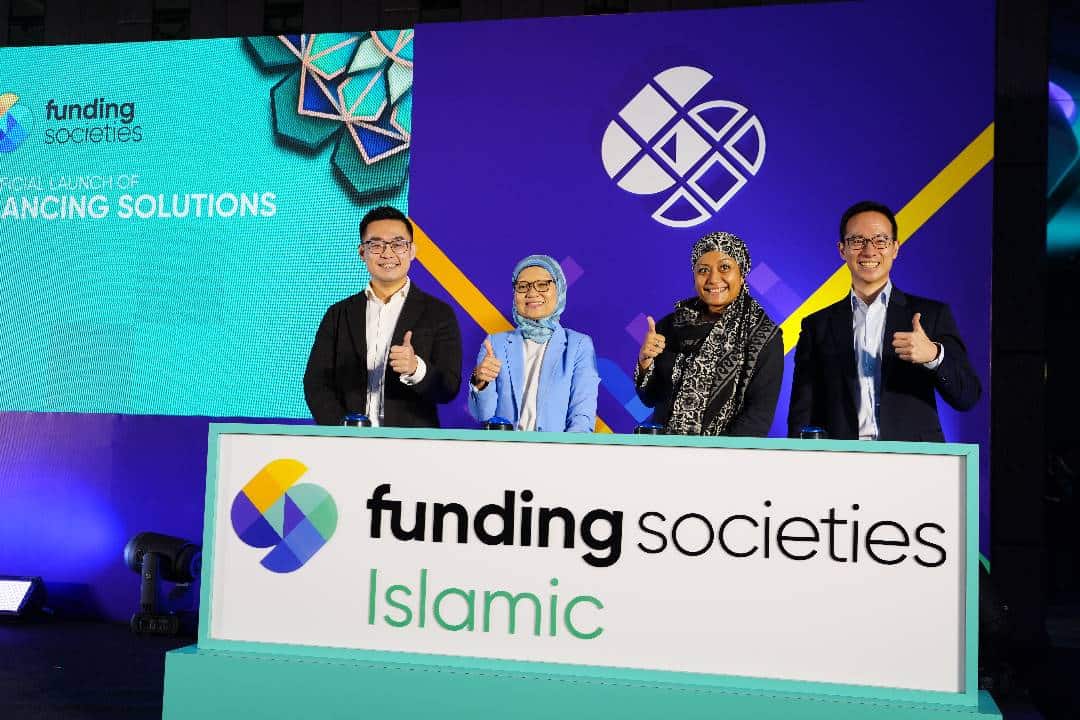
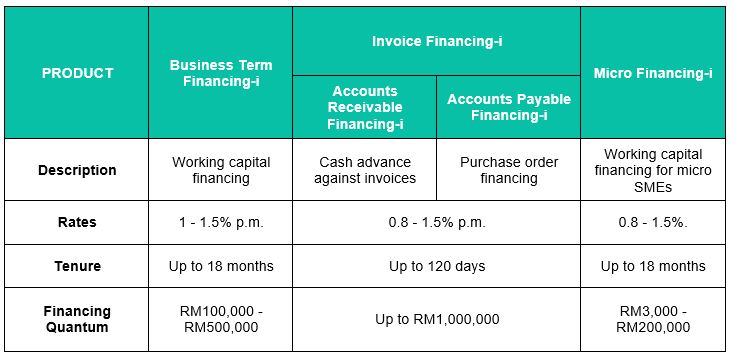
Funding Societies, the largest unified SME digital finance platform in Southeast Asia, has launched its comprehensive Islamic Financing product collection, a complete suite of Shariah-compliant financing solutions designed to meet the needs of creditworthy, underserved Malaysian micro, small and medium enterprises (MSMEs) seeking to grow their business. These Islamic financing solutions include Business Term Financing-i, Micro Financing-i, and Invoice Financing-i.
“Access to finance is mission critical for inclusive growth and MSME development. Case in point, there is a RM90 billion SME financing gap in Malaysia. To that end, SME digital finance platforms like Funding Societies play an important role in closing that gap. Given Malaysia’s leadership in Islamic finance, it is timely for us to scale our Shariah-compliant proposition to support creditworthy Malaysian SMEs of all sizes to thrive,” said Wong Kah Meng, Group Chief Operating Officer of Funding Societies | Modalku and Co-founder of Funding Societies Malaysia.
Chai Kien Poon, Country Head of Funding Societies Malaysia said, “Following market feedback, we observed demand for Islamic finance and Muslim entrepreneurs’ need for Shariah-compliant financing. Islamic finance is also appealing to non-Muslims given its emphasis on fairness and transparency in fees and charges. Besides that, the introduction of our Islamic Financing aligns with Malaysia’s aspirations to be the leader in Islamic finance as well as focus on the Islamic digital economy and FinTech.”
Interested SMEs can apply for these financing solutions online – seamlessly, anywhere and anytime. Through its simple and digital proposition, along with zero collateral requirements, Funding Societies can avail financing to MSMEs much quicker compared to traditional financial institutions.
“Besides launching our Islamic financing proposition, we have developed Shariah-compliant investment products for our investors. This allows investors to diversify their investments while joining us to support a critical segment of the Malaysian economy. We have seen very encouraging demand from investors (retail, high net worth individuals and institutions) and look forward to working with financial institutions to offer Shariah-compliant investments to their customers,” adds Chai.
Khairil Anuar Mohd Noor, Principal, Masryef Advisory, who was present at the launch event in Kuala Lumpur, remarked, “We are delighted to be part of this initiative by Funding Societies that would further elevate the landscape of Islamic Finance in Malaysia. We believe Funding Societies’ cutting edge, a leading digital finance platform, offers ground-breaking Shariah-compliant financing solutions to Malaysian MSMEs that would enable MSMEs to have access to alternative funding to fund their business. Similarly, it allows investors an alternative Shariah-compliant asset class to invest their excess liquidity. This collaboration allows us to leverage Funding Societies’ technological prowess and our expertise in Shariah advisory. Together, we will drive inclusive growth and unlock the potential of Islamic finance for sustainable economic development in Malaysia.”
Funding Societies has been operating in Malaysia since 2016 and has provided financing to thousands of SMEs in the country. The FinTech platform has disbursed more than RM2 billion in financing in Malaysia since its inception. Across the region, more than RM13.74 billion has been disbursed through more than 5 million transactions as of 2022. After its soft launch in May 2022, the Shariah-compliant financing propositions have seen encouraging take-up from SMEs. The Fintech platform targets to have at least 50% of its disbursement from its Shariah-compliant financing portfolio by 2025.
Funding Societies | Modalku is the largest unified SME digital finance platform in Southeast Asia. It is registered with the Securities Commission Malaysia (SC), as well as licensed in Singapore, Indonesia, and Thailand, and operates in Vietnam. It is backed by SoftBank Vision Fund 2, SoftBank Ventures Asia, Sequoia Capital India, Alpha JWC Ventures, SMBC Bank, Samsung Ventures, BRI Ventures, Endeavor, SGInnovate, Qualgro, and Golden Gate Ventures amongst others. The FinTech company provides business financing to small and medium-sized enterprises (SMEs), which are funded by individual and institutional investors. In 6 years, it has helped finance over 5.1 million business deals close to RM13.74 billion in funding. It was given the Digitalizing Services for Retail Participations award by the Securities Commission Malaysia during the INVESTSMART® FEST 2019, the Monetary Authority of Singapore (MAS) FinTech Award in 2016, the Global SME Excellence Award at the United Nations’ ITU Telecom World in 2017, KPMG Fintech100 in 2018, Brands for Good in 2019, and ASEAN Startup of the Year by Global Startup Awards in 2020. In 2021, it was honourably mentioned as Responsible Digital Innovator of the Year by the World Bank IFC SME Finance Forum and won the MAS ASEAN Fintech award for the second time.
Bintang Capital Partners Berhad (“Bintang” or the “Firm”) proudly announces its achievement of becoming a Certified B Corporation (“B Corp”), making it the first private equity firm in Southeast Asia to earn this prestigious recognition.
Administered by the renowned global non-profit B Lab, the B Corp Certification recognises businesses that meet high standards of verified performance, accountability and transparency on factors ranging from employee benefits and charitable giving, to supply chain practices and using responsible input materials.
By joining the community of 6,800 existing B Corps operating in 161 industries across 90 countries, Bintang is embracing a common objective of harnessing business as a force for good.
Johan Rozali-Wathooth, Founder and Chief Executive Officer of Bintang
Founder and Chief Executive Officer of Bintang, Johan Rozali-Wathooth, shares the reasons behind Bintang’s motivations in pursuing B Corp Certification, stating, “It has always been my dream to establish a private equity firm that integrates purpose with considerations for people, planet, and profit. During the early stages of the COVID pandemic, I had time to think about how companies all over the world achieved this goal. The narratives surrounding the B Corp movement inspired and convinced me that this is the way forward for Bintang.”
Bintang has integrated core values of the B Corp belief system into every facet of its business operations and investment processes. This certification represents a significant leap forward in the firm’s relatively short history, propelling Bintang towards becoming a leading impact investor in the Southeast Asian region, driven by the firm’s core “Triple I” philosophy of “Investing in Impact and Innovation.”
Johan further explains, “This achievement not only demonstrates our commitment to responsible business practices but also serves as an inspiration for our Partner Companies. We aspire to guide and support them on their quests to become Certified B Corps. Additionally, given the under-representation of Southeast Asian companies amongst the global B Corp community, we have a further dream to create at least 150 new B Corps in the ASEAN region within our portfolio of companies by 2050.”
Tan Ee Beng, Director at B Market Builder Southeast Asia (the Southeast Asian chapter of the global B Lab Network) shares that, “Bintang Capital Partners has long been a leader and evangelist of ‘Business as a force for Good’ as demonstrated in their organisation’s core values and purpose. This is aligned with our collective mission at B Lab Network globally to transform our current economic system to be more inclusive, equitable and regenerative. I applaud the Bintang team for their perseverance, commitment and leadership in making their dream of becoming a Certified B Corp a reality.”
To earn its certification, Bintang completed the comprehensive B Impact Assessment, evaluating the firm’s practices and performance across five impact areas: workers, communities, customers, governance, and the environment. This process involved rigorous assessments and verifications, engaging every member of the firm, and spanning approximately one year.
As part of the certification process, Bintang amended its Constitution to embrace stakeholder governance. This commitment ensures the firm’s accountability extends to all stakeholders, including workers, communities, customers, suppliers, and the environment – not only its shareholders. Bintang’s comprehensive Responsible and Sustainable Investment Policy further reinforces the incorporation of environmental, social, governance (ESG) as well as impact considerations into all aspects of its business operations, including the investment process.
Johan added, “Bintang Capital Partners’ B Corp Certification demonstrates its unwavering dedication to responsible business practices and its commitment to making a positive impact. The firm looks forward to continuing its journey as a leader in sustainable investing, inspiring others in the region and beyond”.
About Bintang
Founded in 2018, Bintang is a private equity firm headquartered in Kuala Lumpur, Malaysia. Bintang benefits from a parentage that includes leading independent Malaysian asset management group, AHAM Asset Management Berhad as well as leading global investment managers such as CVC Capital Partners and Nikko Asset Management.
Bintang focuses on deploying capital into fast-growing mid-sized ASEAN companies with proven track records: based on Bintang’s Triple-I Strategy (“Investing in Impact & Innovation”) the Firm backs visionary entrepreneurs who are aligned to Bintang’s twin core investment philosophies of Innovation and Impact.
Bintang is a signatory to the United Nations Principles for Responsible Investment (“UN PRI”). The Firm is also the first Malaysian signatory to the Operating Principles for Impact Management (“the Impact Principles”), an initiative whose development was led by the International Finance Corporation (“IFC”), a member of the World Bank Group.
On the 21st of May, 2023, Bintang became a B Corp, the first private equity firm in Southeast Asia to earn this prestigious recognition. Bintang has an aspiration to create 150 B Corp portfolio companies by 2050 (“150 by ‘50”).
The Firm’s maiden fund, BCP Asia Fund I (“BCPAF I”) is anchored by Dana Penjana Nasional, an investment fund under the Malaysian Government’s Ministry of Finance aimed at catalysing the country’s post Covid-19 economic recovery whilst supporting the local private capital industry.
BCPAF I invests in high performance and high innovation companies who are well-placed to meet the challenges, opportunities and disruption brought about by rapid advancements in technology. The fund focuses on investments in companies who are committed towards delivering impact from environmental, community, employee, customer and governance perspectives.
Recent investments by the firm include Involve Asia, a technology company that operates a performance-based marketing platform; My Care Concierge, a multi-award-winning provider of elderly care solutions; and iHandal, an industry leader in the energy efficiency solutions innovation space.
Further information about Bintang is available at www.bintangcapitalpartners.com.
About B Lab
B Lab is the non-profit network transforming the global economy to benefit all people, communities and the planet.
By harnessing the power of business, B Lab positively impacts companies around the world, helping them balance profit with purpose. Together, B Lab and the B Corp Community are shifting the global economy from a system that profits few to one that benefits all: advancing a new model that moves from concentrating wealth and power to ensuring equity, from extraction to generation, and from prioritizing individualism to embracing interdependence.
Further information about B Lab and the B Corp Certification is available at About B Lab (bcorporation.net).
Dunia pekerjaan semakin berubah. Krisis COVID-19 telah mempercepatkan aliran struktur sedia ada dan menyebabkan organisasi memikirkan semula pelbagai aspek pekerjaan. Bagaimana pekerjaan dilakukan, di mana dan oleh siapa menjadi lebih pelbagai dan berubah-ubah. Oleh kerana sifat kerja dan cara kita menjana wang terus berubah, ini secara tidak sengaja akan memberi kesan kepada aspek kewangan peribadi yang lain juga.
Sekiranya anda merupakan seorang anak muda Malaysia yang menabung untuk persaraan, masa depan anda mungkin kurang terjamin daripada apa yang anda fikirkan. Walaupun dekad yang akan datang bakal menyaksikan salah satu pemindahan kekayaan terbesar di antara generasi kepada golongan milenial dan Gen Z, tabiat dan tingkah laku kewangan semasa generasi muda ini, serta perubahan sifat kerja, mungkin akan menjejaskan simpanan masa depan mereka.
Sistem Pencen Sedia Ada Tidak Akan Mencukupi
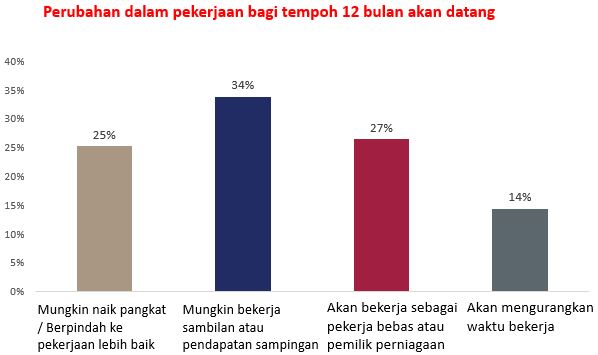
Kajian ICMR di seluruh negara berkenaan golongan milenial dan Gen Z mendapati bahawa 70% responden menjangkakan perubahan dalam kehidupan pekerjaan mereka dalam tempoh 12 bulan akan datang. Daripada jumlah ini, 61% melihat diri mereka menukar modaliti pekerjaan, sama ada mengambil kerja sampingan atau bekerja sambilan, atau bekerja sebagai pekerja bebas atau menjadi pemilik perniagaan.
Rajah 1: Perubahan pekerjaan yang dijangka berlaku bagi tempoh 12 bulan yang akan datang (Sumber Data: ICMR)
Dengan bilangan mereka yang beralih daripada tanggapan tradisional tentang mempunyai satu pekerjaan sepenuh masa semakin meningkat, isu perlindungan dan kecukupan dalam sistem pencen sedia ada akan menjadi lebih parah. Kebijaksanaan persaraan lampau yang bergantung kepada rancangan persaraan tradisional mungkin berkesan untuk ibu bapa dan datuk nenek mereka, tetapi ini tidak mencukupi bagi golongan milenial dan Gen Z untuk mengharungi tahun-tahun keemasan mereka.
Sistem pencen sedia ada di Malaysia sebahagian besarnya adalah berasaskan majikan, dengan sebahagian daripada gaji dipotong secara automatik daripada senarai gaji dan dimasukkan ke dalam simpanan persaraan. Tetapi seperti yang telah kami ketengahkan dalam laporan kami sebelum ini, pekerja gig, pekerja bebas dan pemilik perniagaan kecil tidak dilindungi oleh sistem sedia ada, dan ianya juga tidak mengambil kira pendapatan tambahan dengan tepat daripada pendapatan sampingan atau modaliti pekerjaan lain.
“Saya selesa dengan aturan kerja bebas, dan tidak fikir saya akan kembali bekerja sepenuh masa pada masa hadapan. Tetapi saya sedang berusaha untuk membeli rumah baru-baru ini dan menghadapi kesukaran untuk mendapatkan pinjaman kerana bank tidak mengiktiraf kerja bebas, walaupun saya dibayar secara konsisten setiap bulan.”
– Hussein, 30, perunding bebas
Mengatasi “Present Bias” Untuk Persaraan Yang Lebih Baik
Tanpa akses kepada pelan pencen berasaskan majikan, golongan muda Malaysia akan dibiarkan memikul tanggungjawab merancang untuk persaraan mereka sendiri. Bagaimanapun, tinjauan ICMR mendapati bahawa bilangan golongan milenial dan Gen Z yang tidak menganggap simpanan persaraan sebagai keutamaan adalah membimbangkan. Sebaliknya, mereka mengutamakan pembelian rumah, barangan mahal, dan mengaut keuntungan daripada pulangan pelaburan yang lebih tinggi.
Ini adalah selaras dengan pencerahan daripada temu bual kualitatif kami, di mana hanya seorang responden mempunyai matlamat kewangan persaraan spesifik. Bagi semua responden lain, persaraan adalah tanggapan yang samar-samar dan jauh, atau terdapat kepercayaan bahawa “ianya akan berlaku sendiri” untuk tujuan persaraan. Ramai juga merasakan bahawa mereka mempunyai terlalu banyak komitmen dan perbelanjaan semasa untuk memikirkan tentang persaraan.
“Present bias”membuatkan kita memihak kepada masa kini dan kurang bagi masa hadapan – lalu meningkatkan masalah seperti ketagihan, penangguhan, ketidaksabaran, kepuasan segera dan perancangan yang tidak baik (Sumber Imej: Don McMinn)
Contoh-contoh ini menunjukkan “present bias” apabila memikirkan tentang persaraan, atau kecenderungan untuk berpuas hati dengan ganjaran semasa yang lebih kecil berbanding menunggu ganjaran masa depan yang lebih besar. Malah, kajian terdahulu menunjukkan bahawa rakyat Malaysia hanya mula merancang untuk bersara selepas umur 40 tahun, justeru terlepas peringkat pengumpulan jangka panjang yang kritikal yang boleh mengakibatkan perbezaan ketara di dalam simpanan persaraan mereka.
“Saya kehilangan pekerjaan pada Mac 2020. Sekarang saya seorang pemandu Lalamove, dan saya membantu di bengkel rakan untuk mendapatkan pendapatan tambahan. Sukar untuk memikirkan matlamat kewangan atau membuat apa-apa rancangan jangka panjang apabila saya hanya menumpukan terhadap usaha untuk mendapatkannya dari sehari ke sehari. Saya tidak mempunyai masa atau tenaga untuk mengkaji perkara ini ataupun dana yang mencukupi.”
– Zaim, 34, pemandu Lalamove
Bermula Awal Untuk Mendapat Manfaat Daripada Perancangan Kitaran Hayat
Kekurangan persaraan yang mencukupi dalam kalangan anak muda Malaysia melibatkan kedua-dua peringkat individu, dan juga di peringkat dasar negara. Kesan gabungan penuaan penduduk dan kekurangan simpanan persaraan adalah pelbagai segi dan kompleks, dengan implikasi dasar untuk pasaran buruh, produktiviti, serta institusi sosial dan keluarga.
Golongan milenial dan Gen Z bernasib baik kerana mereka yang mempunyai jangka masa yang lebih lama. Ini membolehkan mereka untuk mendapat manfaat daripada perancangan kitaran hayat yang lebih baik berdasarkan tahap risiko mereka sendiri. Oleh itu, adalah penting bagi individu mengambil langkah pertama seawal mungkin dalam menilai keadaan kewangan keseluruhan mereka, dan membuat pelan kewangan dan pelaburan jangka panjang yang sesuai dengan keperluan dan gaya hidup mereka.
Apa yang boleh membantu ialah memikirkan tentang simpanan persaraan sebagai pengumpulan kekayaan. Membina tabung persaraan yang besar menjadi lebih sukar di kemudian hari apabila seseorang mempunyai lebih banyak perbelanjaan, seperti keluarga dan hutang rumah. Tetapi dengan bermula awal, menabung untuk persaraan boleh menjadi sesuatu yang jauh lebih menyenangkan – dan mengujakan. Jumlah sedikit yang disimpan untuk persaraan hari ini boleh membawa perubahan yang besar di masa hadapan.
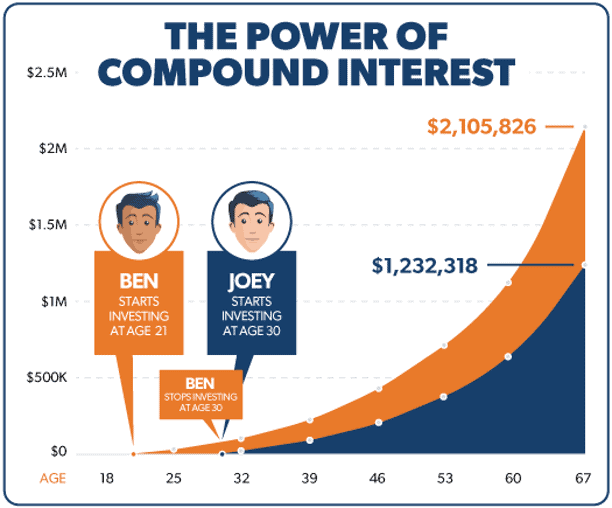
Dengan masa menyebelahi mereka, golongan milenial dan Gen Z boleh memanfaatkan kuasa faedah berganda dan meminimumkan kesan turun naik pasaran terhadap pelaburan mereka. Mereka juga boleh membuat keputusan yang lebih baik tentang pilihan kerjaya, pendidikan dan gaya hidup mereka, yang boleh memberi impak besar terhadap masa depan kewangan mereka.
Lebih banyak masa wang boleh berganda dan berkembang, lebih banyak peluang untuk pendapatan tersebut menjana wang tambahan. (Sumber Imej: Ramsey Solutions)
Mereka Semula Persaraan Untuk Masa Depan
Memandangkan sifat kerja yang terus berevolusi di Malaysia dan di seluruh dunia, adalah penting bagi individu untuk menyedari kesannya terhadap kewangan peribadi mereka, terutamanya yang berkaitan dengan perancangan persaraan. Sementara itu, penggubal dasar juga perlu memainkan peranan mereka dalam memastikan sistem pencen semasa adalah mencukupi dan inklusif untuk semua rakyat Malaysia.
Kesimpulannya, membina masa depan kewangan yang mampan dan terjamin untuk semua rakyat Malaysia memerlukan gabungan tindakan individu dan reformasi sistemik. Dengan mengutamakan perancangan awal dan komprehensif, serta menangani jurang dasar, kita dapat memastikan semua rakyat Malaysia berpeluang untuk bersara dengan selesa dan bermaruah.
Artikel ini adalah sebahagian daripada siri kandungan oleh Institute for Capital Market Research (ICMR). Ikuti laman Facebook ICMR untuk mendapatkan info terkini tentang petua tingkah laku dan pandangan, untuk tabiat pelaburan yang lebih baik. Untuk mengetahui lebih lanjut mengenai kajian ICMR ke atas milenial dan Gen Z, layari www.icmr.my atau muat turun laporan penuh di sini.