Category: Investments

  • Best Unit Trust In Malaysia

    Best Unit Trust In Malaysia

    With so many options when it comes to unit trust, it won’t be easy to come out with a list of the best unit trust in Malaysia. Nevertheless, here are some of the best unit trust in Malaysia.

    Source: FSMOne Recommended Unit Trusts Awards 2022/2023

    There were a total of 44 categories to emerge as the best unit trust in Malaysia. In total, there were 5 broad categories: Core Equity, Core Fixed Income, Balanced, Supplementary Portfolio and Private Retirement Scheme (PRS).

    The winner for Core Equity – Global category, goes to Manulife Global Thematic Fund by Manulife Investment Management (M) Berhad.

    The winner for Core Equity – Global (Islamic) is abrdn Islamic World Equity Fund by abrdn Islamic Malaysia Sdn Bhd.

    The winner for Core Equity – Global Emerging Markets is won by Eastspring Investments Global Emerging Markets Fund by Eastspring Investments Berhad.

    Two winners for Core Equity – Asia ex-Japan, one goes to Affin Hwang Select Asia Pacific (ex Japan) Dividend Fund by Affin Hwang Asset Management Berhad and the other goes to Principal Asia Pacific Dynamic Growth Fund by Principal Malaysia.

    We also have two winners for the Core Equity – Asia ex-Japan (Islamic) category, won by Affin Hwang Aiiman Asia (ex Japan) Growth Fund by Affin Hwang Asset Management Berhad and Principal Islamic Asia Pacific Dynamic Equity Fund by Principal Malaysia.

    For the Core Equity – Malaysia category, the two winners are Affin Hwang Equity Fund by Affin Hwang Asset Management Berhad and KAF Tactical Fund by KAF Investment Funds Berhad.

    Core Equity – Malaysia (Islamic) category have two winners as well: Affin Hwang Aiiman Growth Fund by Affin Hwang Asset Management Berhad and PMB Shariah Premier Fund by PMB Investment Berhad.

    Moving on to the Core Fixed Income, the Core Fixed Income – Malaysia category have two winners: KAF Bond Fund by KAF Investment Funds Berhad and Manulife Investment Bond Fund by Manulife Investment Management (M) Berhad.

    Core Fixed Income – Malaysia (Islamic) was won by AmanahRaya Syariah Trust Fund by AmanahRaya Investment Management Sdn Bhd.

    Next up we have the Balanced category, with Balanced – Global won by RHB Asset Management Sdn Bhd with its RHB Global Allocation Fund.

    Balanced – Asia ex-Japan winner is Principal Asia Pacific Dynamic Mixed Asset Fund by Principal Malaysia.

    Balanced – Malaysia category was won by Affin Hwang Select Balanced Fund by Affin Hwang Asset Management Berhad.

    Finally, Pheim Unit Trusts Berhad won the Balanced – Malaysia (Islamic) with its Dana Makmur Pheim.

    Under Supplementary Portfolio, the winner for Sub Regional Equity – ASEAN is Principal ASEAN Dynamic Fund by Principal Malaysia.

    Sub Regional Equity – ASEAN (Islamic) was won by ASEAN Equity Fund by Saturna Sdn Bhd.

    The Sub Regional Equity – Greater China was won by Principal Malaysia with its Principal Greater China Equity Fund.

    Sub Regional Equity – Greater China (Islamic) category winner is Eastspring Investments Dinasti Equity Fund by Eastspring Investments Berhad.

    Sub Regional Equity – Europe was won by Europe Equity Growth by AmFunds Management Berhad.

    Single Country Equity – US winner is Manulife Investment U.S. Equity Fund by Manulife Investment Management (M) Berhad.

    Single Country Equity – China category winner is RHB Asset Management Sdn Bhd with its RHB Big Cap China Enterprise Fund.

    Single Country Equity – Japan was won by Affin Hwang Asset Management Berhad with its Affin Hwang World Series – Japan Growth Fund.

    Single Country Equity – Singapore was won by Singapore Dividend Equity Fund by Nikko Asset Management Asia Limited.

    The Sector Equity – Asia ex-Japan Small to Medium Companies category winner is Affin Hwang Select Asia (ex Japan) Quantum Fund by Affin Hwang Asset Management Berhad.

    Sector Equity – Malaysia Small to Medium Companies winner is KAF Investment Funds Berhad with its KAF Vision Fund.

    Meanwhile Sector Equity – Malaysia Small to Medium Companies (Islamic) category was won by Kenanga Investors Berhad with its Kenanga Shariah Growth Opportunities Fund.

    Then we have Kenanga Investors Berhad winning the Sector Equity – Malaysia Focused with its Kenanga Growth Fund Series 2.

    The winner for Sector Equity – Global ESG (Water Theme) is Manulife Investment Management (M) Berhad with its Manulife Global Aqua Fund.

    Sector Equity – Global Healthcare category winner is Manulife Global Healthcare Fund by Manulife Investment Management (M) Berhad.

    TA Investment Management Berhad wins in the Sector Equity – Global Technology category with the TA Global Technology Fund.

    Maybank Asset Management Sdn Bhd wins in the Fixed Income – Global (Islamic) with its MAMG Global Income-I Fund.

    There were two winners in the Fixed Income – Asia ex-Japan category: Affin Hwang Asset Management Berhad with its Affin Hwang Select Bond Fund and AmFunds Management Berhad with its AmTactical Bond.

    Under the Fixed Income – Emerging Markets category, RHB Asset Management Sdn Bhd emerge victorious with the RHB Emerging Markets Bond Fund.

    Fixed Income – Malaysia (Short Duration) category saw that AmFunds Management Berhad wins with its AmIncome Plus.

    In the Fixed Income – Malaysia with Foreign Exposure category, AmFunds Management Berhad won it with the AmDynamic Bond.

    In the Private Retirement Scheme (PRS), there were a total of four categories. Affin Hwang Asset Management Berhad wins the Private Retirement Scheme – Moderate with its Affin Hwang PRS Moderate Fund.

    Next we have AIA Pension and Asset Management Sdn Bhd winning the Private Retirement Scheme – Growth category with AIA PAM – Growth Fund.

    The Private Retirement Scheme – Moderate (Islamic) category was Manulife Investment Management (M) Berhad picking it up with its Manulife Shariah PRS-Moderate Fund.

    Last but not least, Manulife Investment Management (M) Berhad wins the Private Retirement Scheme – Growth (Islamic) with its Manulife Shariah PRS-Growth Fund.

    How The Best Unit Trust Was Selected?

    The winners were chosen using a meticulous selection process that involves quantitative and qualitative criteria.

    Performance

    The most objective way to determine the quality of the fund manager is to assess the fund’s historical performance, a factor we weigh heavily in our fund selection exercise. For this, we consider both the magnitude of performance as well as the consistency of returns. In the case of new funds which feed into their overseas target funds with a longer track record, we may assess the target fund’s performance. We recommend funds which have at least a 3-year track record.

    Expense Ratio

    The expense ratio is what investors pay for the management of their fund on an annual basis. This charge is deducted from the value of the unit trust, and it takes into account all the operating expenses that a fund incurs, including its annual management fee, administration costs as well as trustee and custodian fees. Generally speaking, the lower the expense ratio, the better it is for you, because you are incurring less costs.

    Risk

    Instead of purely using standard deviation as the measure of risk, we believe that it is more appropriate to focus on how well a fund holds up during periods when the relevant markets saw substantial decline. As such, in our assessment of risk, we focus on the maximum decline of a fund over a given period, and also incorporate a measure of downside volatility, which tells us how volatile a fund is over periods when it is losing value.

    Bond Funds

    Equity funds usually track well-known stock market benchmarks, making it easier to compare funds invested in a similar region or country. Bond funds are less comparable, given their differentiated focus on credit, country selection, currency and duration. To reflect the emphasis on stability in fi xed income investments, we assign different weightings to the three quantitative parameters as shown below.

    Other Qualitative Criteria

    In addition to looking at the above-mentioned quantitative parameters, we also consider other qualitative factors in our analysis, including the fund manager’s consistency in their investment approach, the departure of key personnel as well as the stability of the management team. We also incorporate our outlook on the fi xed income market to assess the merits and disadvantages of a bond fund.

    As most of the funds which invest in other regions buy companies that predominantly have their assets and earning streams denominated in foreign currencies, there is currency risk involved. A gain in the MYR against another currency may reduce the returns of the funds exposed to other currencies, while a drop in the MYR against other currencies would increase the returns. Thus, qualitative analysis is a necessary step to distinguish
    funds with superior management ability from those which were beneficiaries of strong market or currency movements.

    As we take into account the qualitative factors, the highest scoring fund based on quantitative assessment in a particular category may not necessarily be the fund we recommend, although fund performance remains a significant factor.

    Weightage Of Quantitative Parameters

    Those are some of the best unit trust in Malaysia, but always do your own due diligence before buying any of it.

    Know your risk tolerance, time horizon and capital that you can invest in. A unit trust might be suitable for me, but might not necessarily be suitable for you or others.
  • Is Malaysia Property Still Worth To Invest In?

    Is Malaysia Property Still Worth To Invest In?

    Malaysia property might not be as hot as previous years, but the interest is still there. With the recent hike in interest rates and more hikes expected later this year, the instalment for properties will go up.

    This then begs the question as to whether Malaysia property is still a good investment?

    First of all, let’s look at some stats.

    Malaysian House Price Index

    Source: National Property Information Centre (NAPIC)

    House prices in Malaysia went up by almost 100% from 2010 to 2022 with the average price went up from RM220,154 to RM433,430.

    But there has been a steady decline in recent years caused by the pandemic where demand went down and supply going up. The concept of supply and demand has influenced Malaysia property price to a certain extent.

    Source: National Property Information Centre (NAPIC)

    The number of transactions were seen climbing up towards the end of last year before falling off a little bit.

    OPR (Overnight Policy Rate) Is On The Rise

    Source: Bank Negara Malaysia

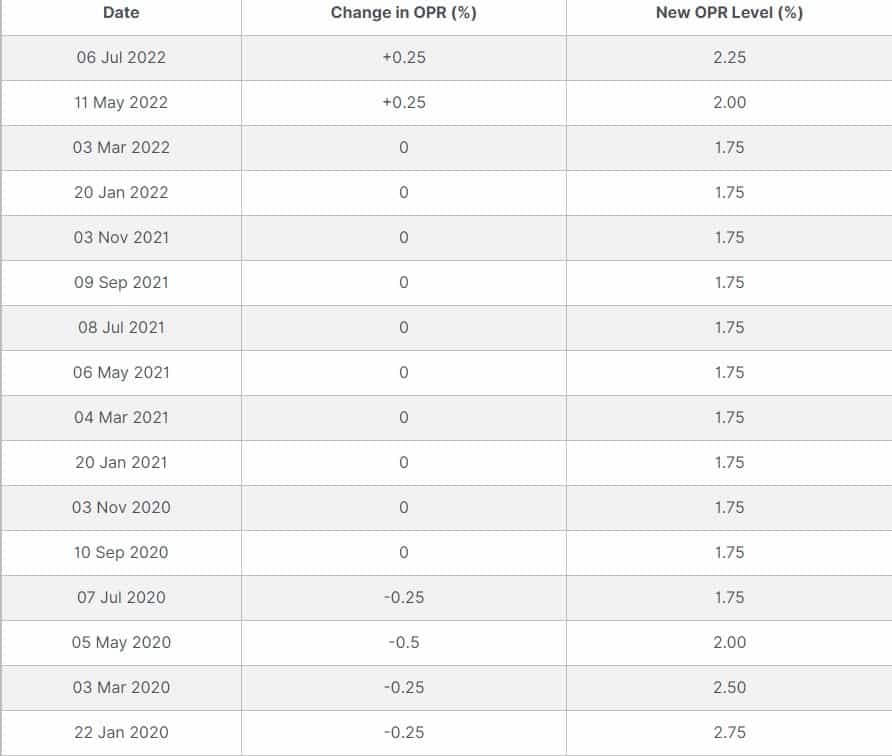
    Malaysia have been enjoying a very low interest rate since the pandemic begin. But with the recent OPR hike by Bank Negara Malaysia, this would have caused interest rate to rise, and subsequently the monthly instalment for houses to increase as well.

    Analysts are predicting a few more rounds of OPR increase to curb the rising inflation by end of this year, which could cause house purchases to cool off.

    The Rise Of Inflation

    Source: Department Of Statistics Malaysia

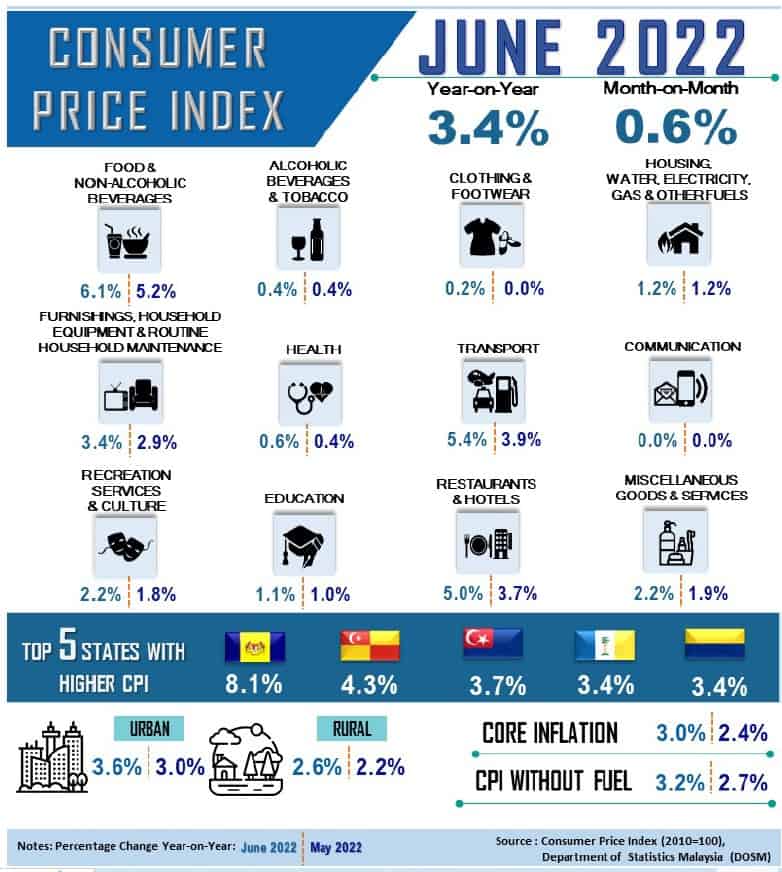
    Malaysia’s inflation increased 3.4%to 127.4 in June 2022 as against 123.2 in the same month of the preceding year. The Food index increased 6.1% and remained as the main contributor to the rise in the inflation during the month of June 2022. 

    When faced with high inflation, there will be lesser disposable income as everyone will be tightening their budget. Only those who have made the necessary preparation and is prioritizing in buying a house over other needs, will buy it.

    The others will then have to rent, so more renters are expected to be on the market.

    Ultimately only you can answer whether Malaysia property is worth investing in. Do you have the holding power? Are you able to find below market value and irresistible deals from the property market?

    As the saying goes, it is about ‘buying low and selling high’. Do your homework and remember the mantra, ‘location, location, location’.

    For more tips and tricks:

    Do you know how much is your Home Loan eligibility? Not sure how much you can borrow from the bank? 

    Get your TechRevo credit report + Home Loan Eligibility which includes:

    • Credit history up to the past 12 months [CCRIS] 
    • Bankruptcy, Legal Suits, Legal action from banks, SAA, and Trade Bureau (Section E)  
    • Max home loan eligibility calculation up to 12 mortgage favorable banks in Malaysia 
    • CCRIS + Credit report + Calculator 

    It only takes 5 minutes. Click here now to get 50% off -> https://www.smartinvestor.com.my/techrevo

  • What Causes Bursa Malaysia Prices To Go Up And Down?

    What Causes Bursa Malaysia Prices To Go Up And Down?

    We all know that investing in stocks are considered to be “high risk high return” investment. Which means that it can potentially make you profit a lot, and make you lose a lot as well. With that in mind, what causes the Bursa Malaysia prices to be volatile with the price going up and down almost all the time?

    It all boils down to the concept of supply and demand. When there are more buyers than sellers, naturally the price will go up. When there are more sellers than buyers, then naturally the price will go down.

    Bursa Malaysia Prices Always Go Up And Down

    To understand further, you need to do some Technical Analysis. Look at the charts and follow the trend.

    If a stock is in a solid uptrend, you stand to make good money for as long as the trend is still bullish. Well as long as there are new buyers and the volume is strong, then there’s still potential for it to go up.

    But in the end, what goes up must come down right?

    You can also look at stocks that are moving downtrend and wait for a strong reversal signal. As the seller weakens with no new sellers, then buyers will start to turn the tide. Once buyers are more than sellers, the price should stop from going down any further and the momentum will start to change upwards.

    Once it hits rock bottom, surely there’s no other way it can go other than up?

    More Millennials Coming Into The Stock Market

    Another reason why Bursa Malaysia prices are seeing a lot of volatility is due to many new investors come flooding the market – more specifically the youngsters. They typically trade stocks that are in the news, trending or based on thematic investment such as healthcare-related or oil-related stocks while also generally favoring small-cap and mid-cap stocks.

    With better access to information and technology, millennials are most prepared to participate in online share trading and investment. Investment gains and validation of good analysis attract young investors to develop money-managing skills and later, to begin their own investing journey. 

    Millennials are also deeply passionate about global issues that are important to them, and these include Environmental, Social and Governance (ESG), green technology and clean technology.

    Know The Risks Involved

    All investments carry with them some degree of risk, and these risks can range from inflation and interest rate changes to political uncertainties and economic trends. An investor must know his own risk tolerance, investment time horizon, and most importantly, his own financial goals. Holding investments for the long term, too, is advisable.

    Trading on stocks that have no fundamental earnings, poor cash flow and poor business model is a dangerous start. Penny stocks and cheaply priced warrants, too, can also turn into potential big losses as their price drops can be very sharp too.

    New investors should consider only value stocks and business models that are sustainable and should always make a practice of verifying if the information received is accurate. It is always good to diversify. Monitor the market and keep some cash ready for new opportunities that might arise.

    Make sure you read 4 Mistakes People Make In Stock Investing.

  • What Blockchain Taught Me About Parenting and Economic Wisdom

    What Blockchain Taught Me About Parenting and Economic Wisdom

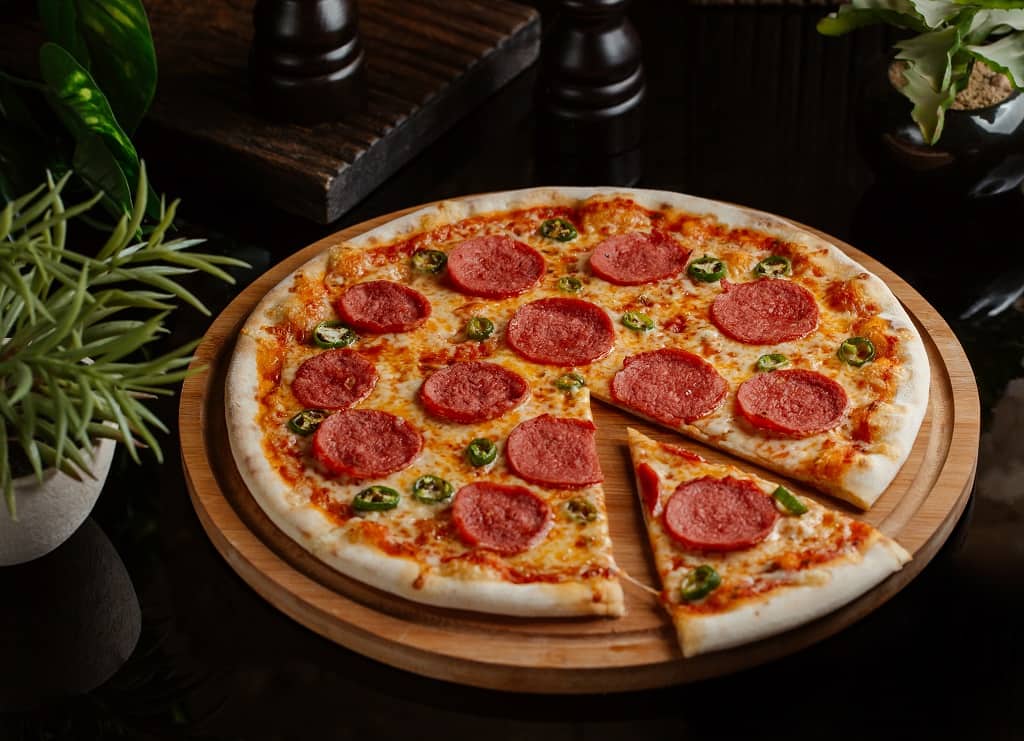
    Imagine the following situation: you bring your twins out for a family dinner in a pizza restaurant. When the pizza arrived, the restaurant didn’t split it. Now, you must split it between your children. The trillion-dollar question is how will you do it?

    For this exercise, I present two plausible options:

    1. You, as the parent, will split for the children.

    2. You let the children decide for themselves.

    For the first scenario, being their parent, you may rightfully believe that you are bestowed the right (by social convention for example) to decide for them. Here’s the catch though, what happens if you have good intentions but are inept with logic (e.g. You can’t tell that a large pizza with 8 slices and a large pizza with 12 slices is the same)?

    Or your method might not yield consistently good results due to some long held tradition (e.g. tiger parenting). When your children grow up, they might constantly defer to a “higher” authority while imposing their will rightly or wrongly on their children.

    For the second scenario, you are laissez-faire, trusting your children to behave well towards each other. Let’s say one of your twins is epigenetically different from the other. So one has a growth spurt much earlier than another. Making a twin stronger, but also hungrier. Then, it is easy for one to bully the other to get a larger slice. This creates an unhealthy dynamic between the twins. They might grow up hating each other, causing a rift in the family.

    The first method sounds tyrannical; while the second can turn into anarchy. Both scenarios presented above are not meant to predict what would happen definitively. It aims to jolt us into being more conscious of our methods, because they might lead to undesirable outcomes.

    Okay, what would be a better approach? How can we split the pizza between the children in such a way where a parent’s authority is not needed in the future; at the same time, the children will learn imaginative ways to treat each other as fair as possible?

    The Fairness Solution

    There is a little game to play when splitting the pizza, it is called the “split and choose”. To play the game, one of the twins is given the right to split the pizza into two slices, then the other gets to choose the first slice. For example, twin A splits the pizza into two, then twin B gets to choose which slice to take first. If twin A cheats by splitting the pizza unevenly, twin B will naturally choose the larger slice first.

    In such a game, only the cheater loses. You don’t have to use your parental authority, nor enforce any fairness values. The self-evident fairness of this game creates a naturally desirable result.

    Such games are at the centre of blockchain protocol development. This “split and choose” game is commonly referred to as proposer-builder separation in the blockchain development. The proposer (i.e. pizza splitter) will propose a block for the blockchain, while the builder (i.e,. pizza chooser) will build the block for the blockchain. The exact details of how this works is too lengthy and technical to cover in this article.

    Nonetheless, you can find out more in the Ethereum discussion forum here. The point of all these is to keep a balance of power by avoiding centralization, so that it is worthwhile to build meaningful use cases on it. Without which, the participant with the most power can corrupt the entire system.

    Not Everyone Thinks Fair

    For the astute reader, you might be able to detect a flaw in this game. This game only works if participants are willing to play the game. What if in the future, without parental supervision, the stronger twin decides not to play this game and resorts to brute strength for a larger share?

    This abuse of power happens a lot in the real world and in blockchain. However, let’s not forget that with continuous abuse, the weaker twin can also decide not to play the game and find other players willing to follow the fairer rule. One example in the real world is the migration of a minority group from one country to another.

    In blockchain speak however, we call it “forking”. Forking is a situation where a group of participants decide to create another version of a blockchain with a new set of rules. Participants fork a blockchain because of competing beliefs in a better system given the risks and rewards like utility, cost, convenience, scalability, security, transparency, decentralization etc.

    The trillion dollar question here is that given more time, which of these factors will society value most?

    Shade They will Never Sit

    Blockchain protocol developers are building blockchain infrastructure primitives (i.e. rules, standards, systems, protocols etc) that they believe will naturally and legitimately benefit society. Good blockchain protocols are developed through pragmatic first principles approaches using science, maths, cryptography, extensive human behavioural research etc.

    We are already reaping the rewards from these efforts. In 2014, disadvantaged groups torn by war and oppression found refuge and financial freedom through Bitcoin. In 2021, we see the rise of NFTs (through ERC-721 standard) which allows artists from all around the world to have another sustainable means of income.

    People living in countries with hyperinflation and foreign exchange controls use stablecoins (created through the ERC-20 standard) to keep the value of their hard earned incomes from eroding. And of course, some of us trade or invest in cryptocurrencies as a new class of asset.

    In the coming years, there will be a lot more innovation in this field (so don’t sleep on it). Only with hindsight, will we realise how these imaginative games played a pivotal role in solving difficult social, political and economic problems. With it, we may no longer require blind obedience to an authority, nor giving up to zero-sum anarchy.

    Future generations will reap the rewards of these old men who planted trees whose shade they shall never sit. Isn’t that what any good parent would want for their children?

    About the Author

    Chia Sheng Yeong is the partner of Celebrus Advisory, a bespoke and industry-acclaimed consulting firm for digital assets with focus on regulatory compliance, technical delivery, and project outcomes.

  • 2022 Bear Market: A Grizzly Affair

    2022 Bear Market: A Grizzly Affair

    Sometimes, we check our portfolio and we gasp in shock at the horrid performance. The percentages are all in the red, and there seems to be no light at the end of the tunnel.

    Young investors who invested into stocks and crypto are left holding the bag, seasoned investors are left shaking in their boots. What can we do to prepare for it?

    The Anatomy of the Bear

    Before we can figure out what our course of action is, it is prudent to analyze and understand the nature of the problem.

    Panda-monium

    One hundred dollars background.

    Early 2020 we were greeted with the pandemic. The world went into a halt for two years, where supply dwindled and demand skyrocketed. To alleviate the pain, the US Federal reserve printed trillions of dollars.

    Although the initial market reaction was of great fear, the money soon made it into the stock market, and we proceeded to have one of the greatest bull runs in the decade. The ride lasted for about a year, which brings us to the beginning of 2022.

    The Ursa Awakens

    March 2022 marks one of the darkest days of this year as equities dropped. War broke out in Ukraine following the invasion of the Russian army. The market was concerned with the effect the war will have on supply chain and the availability of commodities.

    When the supply of the commodities dwindles, and the demand remains the same, prices skyrockets. Classic economics.

    Inflation

    Inflation is the kryptonite of investing (or the economy in general). The CPI numbers is the highest since the 1980s, and it is no wonder it has got everyone running around like headless chickens.

    Companies will not be able to keep up with the input costs. Workers will not be able to get a livable wage since prices for basic necessities are soaring. Unchecked, this will create a cycle of hyper inflation that will instantly nuke an economy.

    The Feds have been printing money and pumping it into the markets for the past two years. Although the Feds have been parroting that inflation is only transitory, now they have finally changed their tune as the bone chilling inflation numbers become available to the public. Kicking the can down the road has become a non-viable option, and the markets will suffer the consequences.

    Although some of the inflation that is present today can be attributed to both the war and the Fed’s actions, one thing is for sure, everything is un-bear-ably expensive now.

    Hawkish Feds

    Since inflation is sky high currently, and the supply chain is impossible to fix, the Feds have only one option left. To destroy demand by increasing interest rates and reducing the money supply. That or risk runaway inflation.

    As interest rates rise and money supply is actively being reduced, cash becomes more expensive, and investors demand more return for their investment, which drives down the value of investments. Complex models are used to determine asset prices, but for us simple investors, understanding this relationship is more than sufficient. In simpler terms, interest rates go up, investment go down.

    Recession

    With the threat of two consecutive quarters of negative GDP growth in the US, it is no wonder the markets are growing restless. The GDPNow real GDP growth, as of writing, is standing at 0.3%, it is probable that it will dip into the negative region once more information is available, which will signal to us that a true recession is here.

    But can we time the recession and buy in at the bottom? Unlikely.

    Recession comes and goes at its own pace, and the markets might reflect that information a lot earlier than expected. Trying to time the market might have the opposite effect of lowering long term returns, since missing just 10 best days of returns in a year will already cripple your portfolio.

    Surviving the Rampage

    Knowing all of the above, what can we do about it? Navigating the bear market requires understanding of the risk return profile of our portfolio and our specific goals.

    Investing in a portfolio of investments that is fully diversified across all economies and geographical regions and taking on the market risk is still the simplest way one can invest without losing too much sleep, as recommended by John C. Bogle, the founder of Vanguard.

    Beating the markets is nice, but trying to time derivative hedging strategies and complex long-short plays in a highly volatile market might not be suitable for the less sophisticated investor, and is a recipe for financial ruin. Beating the market is a tough racket, and almost all professionals will not be able to beat it consistently for a long period of time.

    The markets have not failed (yet!), and if one believes in the markets, a monthly dollar cost averaging strategy into a diversified index fund is still the most prudent strategy for investors that can tolerate the volatility. Investors nearing retirement age might want to consult a licensed financial advisor to properly plan for retirement, as the market volatility might not be suitable for a retirement fund.

    Crypto

    Some experts have touted that crypto moves with the broader market, and offers no diversification benefit, which is hard to dispute, given the current state of crypto. Both institutional and retail investors have lost boatloads of money from being over leveraged and over invested in crypto as the overall crypto market tanked.

    Wave after wave of projects that fail to prepare for the market downturn has left investors holding bags. Terra, Celsius and Voyager, are the 3 biggest names that have imploded into oblivion. Many projects, although not dead yet, have lost 90% or more of their peak values. Even Bitcoin and Ethereum have lost more than 60% of their peak values.

    What can crypto investors do to survive the impending winter?

    First, this is a lesson for young investors that they should only invest in crypto what they are willing to lose. It may sound harsh, but it needs to be said.

    For some, it might be 5% of their portfolio, or maybe even less. One might not get rich quick, but at least they won’t be thrown into a roller coaster ride every time the market sneezes.

    Second, investors should stay away from any projects promising unrealistic returns. Celsius, Terra, Voyager and many other projects promising extreme returns have gone belly up. If you’re a fish dead in the water, the bear will not hesitate to feast on you.

    Stick to the “blue chips” and call it a day.

    Summary

    There is no sense in panicking in the face of the bear. The myth is that the best investors are dead! (Or forgot they have money invested).

    Maybe that is the trick, to play dead, stay invested and wait for the bear to move on.

    About the Author

    Kevin Wong is the partner of Celebrus Advisory, a bespoke and industry-acclaimed consulting firm for digital assets with focus on regulatory compliance, technical delivery, and project outcomes.

  • What Does it Take to Retire Comfortably?

    What Does it Take to Retire Comfortably?

    The issue of retirement is haunting everyone, especially now with the rise of inflation and interest rates. It is happening not only in Malaysia, but the rest of the world. This makes retirement planning harder and it makes us wonder, what does it take to retire comfortably?

    According to Husaini Hussin, chief executive officer of Private Pension Administrator Malaysia (PPA), the reason why most Malaysians are not able to save is because they are poor with financial planning. 

    “We don’t normally live within our means and do not have a plan for the long term, such as building up our retirement funds,” said Husaini.

    To overcome this, we must set aside one third of our monthly salary to have two thirds of our last drawn salary as income replacement in order to have adequate funds upon retirement. This fund will then need to last us throughout our golden years. With Malaysians living on average up to 77 years of age, it is definitely a challenge to have sufficient funds to retire comfortably. Therefore, it is always good to start planning for retirement as soon as possible.

    Husaini Hussin

    For those who contributed to the Employee Provident Funds (EPF), at least there is something for your retirement. But according to statistics, 6.1 million EPF members have less than RM10,000 in their savings. This amount is not enough to sustain even for a year.

    Husaini suggested that all of us start saving for our retirement as early as possible. 

    “Start with a small amount, then gradually increase the saving once our salary increases. By building a regular saving habit and with the help of compounding growth, it helps to build up our retirement funds,” Husaini remarked.

    What About Those with No EPF?

    The younger generation these days prefer to have freedom and flexibility, which has given rise to a new generation of freelancers, small-time business owners or e-hailing drivers, with all of them not contributing to EPF, hence there is no retirement fund for them.

    So how can they start planning for their retirement?

    “It has to start with the right awareness, that they need to begin planning for their retirement as soon as possible,” mentioned Husaini. 

    It is important to start a saving habit and set aside some money each month and make contributions to a bona-fide scheme such as PRS which is a voluntary long-term saving and investment scheme to help people save for their retirement.

    On the issue of scams, Husaini mentions that this is due to greed, negligence, carelessness and naivety. Even though there are a lot of legitimate investments out there, people still fall for scammers, which is now to the tune of billions of Ringgits. Based on Bank Negara Malaysia’s Financial Capability and Inclusion Demand Side Survey 2018 (FCI Survey 2018), most Malaysians are lacking in financial literacy with one out of three Malaysians rate themselves to be low in financial knowledge.

    We can avoid scams by educating ourselves and getting credible information by visiting the official websites, such as the Securities Commission Malaysia (SC), Federation of Investment Managers Malaysia (FIMM), Financial Planning Association Malaysia (FPAM) and the likes, before making any investment. Also, we can seek investment advice from a licensed financial planner instead of online gurus with no evidence of qualification. 

    Malaysians from all walks of life are invited to visit PRS LIVE website, which is a one-stop learning centre on retirement and PRS. There are insights, articles, news and videos available for visitors to read and have a better understanding on retirement planning. 

    “At PPA, we advocate Private Retirement Schemes (PRS). It was launched by the government in 2012 as a voluntary long-term saving and investment scheme to help Malaysians save more for their retirement. With the regulatory framework developed by the SC, PRS forms the third pillar of Malaysia’s multi pillar pension framework,” added Husaini.

    How Do We Cope with the Rising Inflation and Interest Rates?

    retirement

    We can do this by reassessing our spending habits and to clearly define our “needs” and “wants”. If inflation is making it difficult to stay within budget, take a moment to reassess your cash flow.

    With the rise in interest rates, this will cause our spending to reduce and hopefully it can help us to save. But there is so much that we can do to reduce our expenditure, perhaps it is time that we earn additional income by getting a second job.

    Other than saving regularly towards our retirement funds, we should also set aside some sum towards an emergency fund. We can then dip into when we need access to cash during a crunch period. Studies have shown that people having access to an emergency fund would not touch their retirement savings. 

    In order to achieve a happy retirement, we need to have the mindset of ‘saving before spending’. Allocate a certain amount of savings before deducting your expenses for the month. 

    “This ensures we will always set aside a sum for our retirement savings, rather than to wait until the end of the month to see if we have anything left to save after all expenses,” Husaini mentioned.

    Because chances are, we might not have anything left to save if we did not allocate ahead. Another consideration is to save now and indulge later. 

    Start saving for the life you want with as low as RM100 to enrol in PRS via PPA’s PRS Online service today and stand to enjoy more PRS treats during the #ISaveinPRS Treats Contest period until 20 December 2022. For more information, visit https://www.ppa.my/isaveinprstreatscontest/ 

  • Beware of Investment Scams and Financial Gurus

    Beware of Investment Scams and Financial Gurus

    Australians lost AU$158mil to investment scams in the first quarter of 2022. Malaysians have suffered the same fate with more than RM2bil lost through scams since 2017. The figure is potentially higher since there were many cases that have not been reported.

    V. Thanga Velu @ VP Thanga, Executive Director and a Financial Planner at Blueprint Planning Sdn Bhd shares that most of the scam’s victims wanted to achieve their shortfall with the highest return. Besides, scammers are now getting smarter and more creative blending in with the people.

    We seldom conduct our own research on whether the investment is legitimate. The other thing that Thanga emphasizes is that the government should impose severe punishments on the scammers. For example, longer jail terms and the seizure of their assets. 

    Normal people without a finance or investment background may not know how to classify or identify whether an investment is a scam. 

    “Legitimate investments tend to have lower returns and more paperwork such as Know Your Client (KYC) or fact findings to participate in the investment, which may not be attractive and troublesome to some people. If an investment is convenient, provides high returns and no questionnaires are needed, think hard, think long before making that decision as it might just be another scam,” Desmond Foo Wai Kheong, Practice Director of UOB Kay Hian Wealth Advisors Sdn Bhd explains. 

    As a rule of thumb, if it is too good to be true, you should consider getting a second opinion before investing your hard earned money. 

    With the rise of social media, a lot of financial gurus and influencers are now giving out tips. Some of them are legit, while some may take advantage of their followers. There were a few social media investment scam cases that were reported. 

    But how do the public filter all of the information given by the gurus or shared by the influencers so that they won’t fall in the trap?

    Nick Lim, a Licensed Financial Planner at I-MAX Financial Sdn Bhd shares that we need to assess the person dispensing the financial advice whether they are qualified. Check this person’s track record and ensure that verifiable facts support everything being shared. 

    Senior Vulnerability

    investment

    In a survey led by the International Organization for Securities Commissions (IOSCO) which represents more than 150 countries’ securities regulators including Malaysia, it found that the senior investors in particular face greater risk of becoming victims of fraud, being misled or taken advantage of.

    The 2018 survey which focussed on seniors, defined as those in or nearing retirement, highlighted the rising financial fraud on the elderly across the globe.

    As investors age, they may face new challenges such as cognitive impairment due to health and age reasons as well as mental health issues arising from greater social isolation. For some senior investors, these challenges are compounded by a background of limited education and financial literacy – all of which can affect their judgement and decision-making capacity when it comes to investments. 

    According to the Securities Commission, this is already apparent in Malaysia – senior citizens are often targets of various syndicates, ranging from phone scams and sweepstakes to more complex scams which involve impersonation of figures of authority. Most scams or fraud activities target the life savings of these senior citizens, regardless of net worth, and take advantage of their vulnerabilities.

    The growth in digitisation has also exposed vulnerabilities among investors who lack the knowledge to protect themselves in the digital age.

    Beware if It’s Too Good To Be True

    The reason that most of us fall prey to scams is due to us being gullible to get rich quick and forget that investment is a long term game.

    Some of the more popular scams are the ones that promote non-existent investment schemes that promise high returns with little or no risk within a short span of time. Have you seen an ad that says, “Invest RM1,000 and get RM10,000 within 24 hours”?

    Ask yourself, is it too good to be true? If it is, then you should be very careful and avoid it at all costs.

    Scammers have also been known to use fake certificates, invoices and payment receipts from authorities such as the Securities Commission Malaysia (SC), Companies Commission of Malaysia (CCM), Bank Negara Malaysia (BNM), and Inland Revenue Board of Malaysia (LHDN). We tend to feel safe if it is endorsed by the authorities, and wouldn’t question them on the legitimacy of the documents.

    There is also a rise in clone firm scams, where clone firms pose as legitimate entities by using names, logos, credentials, website and other details of legitimate entities to promote bogus investment schemes. At a glance, it looks very similar between the two. If we are not careful, we will think that it’s the real deal.

    Always take some time to research any financial tips, to evaluate if that tool applies to oneself. Keep this in mind, we are the decision-maker and there will be nobody else to blame but ourselves if things don’t turn out well. Ultimately it is always advisable to deal with a licensed personnel.

  • Top Unit Trust In Malaysia

    Top Unit Trust In Malaysia

    There are thousands of unit trust funds in Malaysia, making it very hard for an individual to choose to invest in which unit trust. There are many categories to choose from, ranging from equities (high risk) to bonds (low risk).

    Let’s check out some of the top unit trust in Malaysia as per below:

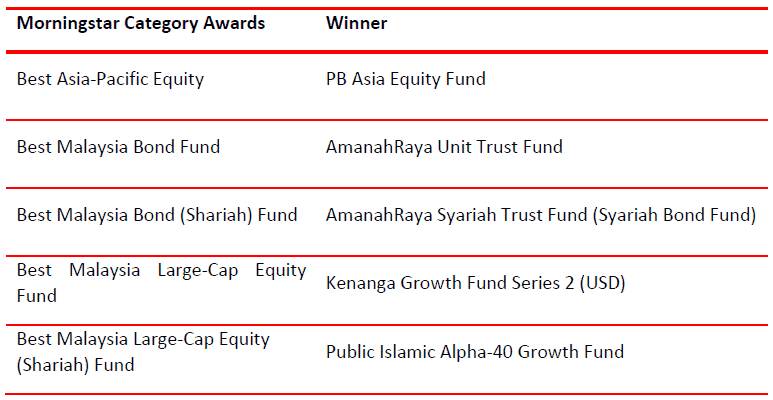
    2022 Morningstar Fund Awards Malaysia

    The above are the 2022 Morningstar Fund Awards winners in Malaysia.

    For the category Best Asia-Pacific Equity, the winner is PB Asia Equity Fund by Public Mutual Berhad.

    Best Malaysia Bond Fund category goes to AmanahRaya Unit Trust Fund by Amanahraya Investment Management Sdn Bhd.

    Amanahraya Investment Management Sdn Bhd wins again in the Best Malaysia Bond (Shariah) Fund category with its Amanahraya Syariah Trust Fund (Syariah Bond Fund).

    Kenanga Investors Berhad won the Best Malaysia Large-Cap Equity Fund with its Kenanga Growth Fund Series 2 (USD).

    Finally, Public Mutual Berhad won again for the category Best Malaysia Large-Cap Equity (Shariah) Fund with its Public Islamic Alpha-40 Growth Fund.

    How The Winners Are Selected?

    The Morningstar fund category awards are based on Morningstar fund data as of 31 December 2021. The awards methodology emphasises the one-year period, but funds must also have delivered strong three- and five-year returns after adjusting for risk within the awards peer groups in order to obtain an award. In selecting winners, fund returns are adjusted for risk using the Morningstar Risk, a measure which imposes a higher penalty for downside variation in a fund’s return than it does for upside volatility. The full methodology for the awards is available here.

    So there you go, those are some of the top unit trust in Malaysia. But before investing in any unit trust or any investment vehicle for that matter, do your own due diligence first. The unit trust might be suitable for me, but it might not be suitable for you or for everyone.

  • How a Trust Can Help You in Times of Need During Retirement

    How a Trust Can Help You in Times of Need During Retirement

    Malaysia’s mandatory retirement age is now at 60 years old. It can either be a good thing or worrying, depending on whether a proper planning has been done prior to retirement.

    For most of us, the main savings for retirement would be our contributions to the Employee’s Provident Fund (EPF) or other equivalent retirement fund. But as statistics have shown, it is inadequate to maintain the quality of life we were used to before retirement.

    Many would take a step further and seek advice from a Financial Planner to see how they can enhance their planning by growing their wealth through investments. With so many options available in the market, many have been blind-sided about one particular issue.

    Retirement planning is more than just saving enough money to generate a passive income that covers your post-retirement living expenses and healthcare.

    Regardless of how you save or how much you save; you need to think about a situation where you or your family members may not be able to access your savings. What if you are comatose or is suffering from dementia, and are not able to take care of yourself during old age? Or perhaps another pandemic like COVID-19 happens?

    You may have a family to take care of, but they will need access to your savings. They would not be able to do so if they are not authorised to operate your account.

    retirement

    Planning for retirement is not just about making sure you have enough to live, but also about providing for contingencies that can happen.

    A well-planned retirement covers planning in many aspects, from financial to healthcare arrangements to estate planning and even bereavement care. Proper planning could save your family from a lot of heartaches and financial pitfalls. Rather than just merely saving for retirement, you can further enhance your retirement planning by using a Trust.

    A trust is like a water tank that you have installed in your house. Your house’s water supply come from the main pipe. Although the supply is supposed to be continuous, it is only a matter of time before a shortage can happen. This is where your water tank comes into use by continuing your water needs in such an emergency.

    This is how an investment or insurance trust from Rockwills can help in your retirement planning.

    This type of trust provides liquidity in times of need during your retirement. In the trust structure provided, you need not transfer the asset yet until the events that were predetermined by you happens. Such events could be Total Permanent Disability (TPD) such as being comatose for a period of time, critical illness, and mental disability.

    Rockwills as your appointed Trustee will then utilise the trust funds to take care of your financial needs, such as medical expenses and even your living expenses while you are under nursing care. This is very useful especially for those whose children have migrated overseas and are no longer around to help.

    retirement

    In summary, you need to build a safe where you can keep piling up your life treasures; and when the need arises, your dependants are able to access it. You will then need someone who can act as your trustee with a backup key to access your funds and carry out the distribution instructions. By setting up a trust, you will be protected in case of unforeseen events and that will only mean a safer future for you and your family.

    Rockwills can help you plan to ensure that your retirement planning objectives can be achieved. Established in 1995, Rockwills is the specialist in providing comprehensive Will Writing, Will Custody & Trust services. We are one of the largest estate planning groups in the region, having written more than 280,000 Wills, 12,000 Trusts and holding over RM25 billion assets under Trust.

  • Retirement Planning with the Right Tools in Hand

    Retirement Planning with the Right Tools in Hand

    When it comes to retirement planning, investment is one of the tools that can help us to achieve our goals. The famous quote by Benjamin Franklin rings true;

    If you fail to plan, you are planning to fail!

    Recently Smart Investor spoke to Isnaliyah Sarwadi, director, business development of PMB Analytics Sdn Bhd (PMBA) which is a subsidiary of Pelaburan Mara Berhad, to get her views on the topic at hand.

    According to her, there are many investment vehicles to support our retirement planning, but the two  vehicles that she believes could warrant the achievement of the goal are through unit trust and property investment.

    Unit Trust and Property

    retirement

    Unit trust investment is one of the most common investment vehicles in Malaysia. It is easily accessible by everyone and it also has a very low entry barrier. You can start investing in unit trust from as low as RM100, which makes it affordable for everyone. It can also be used as a tool to invest regularly each month.

    One must emphasize asset allocation and diversification strategies to benefit the most from unit trust investment. With just a small amount of money, you can already be exposed to global markets such as the United States, ASEAN, China and the rest of the world. Just ensure that it matches your investment objectives, investment horizon and risk tolerance level.

    Secondly, there is property investment. With the right selection of property especially the right location, it can save you time and money to access to your work place. On top of that, price of a good property will always grow over a long period of time. When it appreciates in value, instead of selling it to buy bigger property (an upgrade of lifestyle), one may lower or maintain the lifestyle by buying two properties to accommodate two purposes (accommodation and investment).

    Hopefully, when you combine these two investment vehicles, you will enjoy strong financial standing when you retire. These investments can also be liquidated and used for other purposes such as for your children’s education or to start off a new business.

    Another tip by her is the new age comes with the latest technology. You must equip yourself with new skills as well. If you start saving early, over time, you will have money to start great things in life as the savings will enable you to start small businesses (become an entrepreneur). Immediately, the money will provide you with working capital or a deposit to buy machinery or vehicles for transportation to start the business. In addition, it will provide you money for upskilling since you will need to attend courses of your preference, for example, culinary, bakery, saloon, sewing, massage technique, writing technique, etc.

    Why Aren’t We Able to Retire Well?

    The reason that some of us are not able to retire well is caused by the low awareness of personal financial planning. We tend to spend more than what we earn, which then causes us to borrow in order to carry on with our lives.

    The credit card debt trap which can be a very vicious cycle. Once you are trapped as you are only able to pay the minimum amount each month, it will be very difficult to get out of it. It can snowball to a huge amount over a period of time.

    It all boils down into a mismatch of lifestyle against income. Ever heard of the quote, “We buy things we don’t need with money we don’t have to impress people we don’t like.”

    We also tend to fall prey to “ponzi” schemes and scammers out there. We are easily blinded by the promise of getting rich instantly and receiving extraordinary monthly returns.

    Tackling the Rising Inflation and Interest Rates

    retirement

    Finally, we have to deal with the issue of rising inflation and interest rates. Here are some tips that Isnaliyah is kind enough to share with us. To help us weather the storm, we should do the following:

    • Prudent management of cash flows and personal budgeting requires you to choose wisely between needs and wants
    • Structure your retirement portfolio well. The investment horizon is for the long term and should the market tumble, don’t panic and don’t abruptly restructure your existing portfolio.
    • Invest in upskilling so that you can look for additional income streams if the need arises.

    Retirement planning is something that we should not take for granted. As the years pass so quickly, especially these days, we will be staring at the day we retire very soon.

    If we do not take action, we may have to work until our golden age. So do not delay; start to plan for your retirement now.