Category: Investments

  • Interview with Affin Hwang Asset Management Bhd, Winner Of The FSMOne Recommended Unit Trusts Awards 2022/2023

    Interview with Affin Hwang Asset Management Bhd, Winner Of The FSMOne Recommended Unit Trusts Awards 2022/2023

    Affin Hwang Asset Management Bhd is an independently-managed, bank-backed asset management firm which started in 2001. The company won nine awards, making it the biggest winner in FSMOne Recommended Unit Trusts Awards 2022/2023!

    Chan Ai Mei, chief marketing and distribution officer, shared their investment philosophy and strategies with us.

    Smart Investor: Congratulations on bagging nine awards at the recent FSMOne Recommended Unit Trusts Awards 2022/2023! Tell us about your fund house’s investment philosophy and strategy which contributed to your win.

    Chan Ai Mei: Our investment philosophy is underpinned by an absolute return mindset by focusing on quality growth at reasonable prices. This is then overlaid with a macro awareness to determine our risk tolerance. This approach has served us well over the years by knowing when to take some money off the table when the risk- reward considerations justify doing so, as well as deploying more when the risk-reward outcome is in our favour.

    We are benchmark-aware investors, but are not constrained by it in our investment process. This has allowed us to raise cash during periods of volatility and focus on capital preservation when the macro environment becomes challenging. Importantly, we also subscribe to the simple belief of managing our client’s money as if it were our own.

    We don’t take unnecessary risk with investors’ capital as we are very much invested together with them. The total staff investments within our funds stood in excess of over RM150 million YTD which sums up the belief that we have in our own products.

    SI: Affin Hwang AM was a big winner in the Core Equity Category this year. Tell us a little bit about the Select Asia Pacific (ex-Japan) Dividend Fund which won the best Core Equity – Asia ex-Japan fund award. Also, why should investors consider a dividend-focused strategy for their portfolio?

    CAM: Select Asia Pacific (ex-Japan) Dividend Fund is an actively-managed equity fund that seeks to provide regular income and capital growth through investments in dividend yielding equities and ‘future dividend leaders’ in Asia.

    Through a disciplined investment approach, the Fund adopts a barbell strategy in its stock selection process. The first basket comprises very stable and high dividend-yielding equities that will ensure the consistency of dividend payouts. On the other end, the Fund will invest in companies with strong earnings growth and rising cash flows that have the potential to be future dividend leaders.

    One of the important benefits of having a dividend strategy is the measure of stability it adds to one’s portfolio by creating a regular income stream. Through a dividend strategy, investors essentially get ‘paid-to-wait’ as dividends provide a predictable income stream, whilst investors wait for long-term capital appreciation or volatility to subside.

    This would help induce investors to stay invested in their portfolios and avoid any drastic shifts in their asset allocation which can be detrimental to their long-term goals.

    SI: 2022 has been a volatile year for markets. What advice would you give investors in navigating through this cycle?

    CAM: It’s time for investors to go back-to-basics. Markets are going to stay volatile and the past year has shown that timing market conditions isn’t going to work all the time. Instead, practice dollar-cost averaging by continuously investing in fixed sums through regular intervals. This helps lower the purchase price of your investments over time by taking advantage of market dips as well as reducing the risk of bad timing or investing according to one’s emotions.

    Investors should also strive to achieve diversification in their portfolios across different asset-classes, strategies, sectors and geographical exposure. Over the long-term, it’s been shown that diversification still remains an investor’s best defence in lowering volatility and achieving better risk-adjusted returns overall.

    Against a constant 24-hour news cycle, it pays to also tune-out and avoid monitoring your portfolio constantly. It is counter-productive and usually leads to emotional knee-jerk reactions that puts you in a worse position than before. Instead, set half-year portfolio reviews with your wealth manager or when there is a significant change in your risk capacity, time horizon or objectives. This may warrant a change in your asset allocation because you may be taking too much risk.

    A great yardstick is to ask yourself if you can sleep at night comfortably without thinking about your portfolio. If you can’t, then chances are you taking more risk than you can stomach financially. So it’s important to make periodic reviews at least biannually and ensure that your portfolio is geared towards its stated purpose with an asset allocation that matches your risk tolerance.

    Chan Ai Mei, chief marketing & distribution officer, Affin Hwang Asset Management.
  • Interview with abrdn Islamic Malaysia Sdn Bhd, Winner Of The  FSMOne Recommended Unit Trusts Awards 2022/2023

    Interview with abrdn Islamic Malaysia Sdn Bhd, Winner Of The FSMOne Recommended Unit Trusts Awards 2022/2023

    On the importance of diversification and being cautious in the face of uncertainty

    The global market faced a lot of uncertainties over the past few years. Just when we thought the worst was over after COVID-19 cases have subsided, then comes the Russia-Ukraine conflict, which has caused energy and other commodity prices to skyrocket. These are just some of the risks associated with the global market, shares Gerald Ambrose, Chief Executive Officer, of abrdn Islamic Malaysia Sdn Bhd.

    The fund house changed its name from Aberdeen Standard Islamic Investments (M) Sdn Bhd to abrdn Islamic Malaysia Sdn Bhd in July last year. According to its group website, the new brand symbolises the “transition underway to bring a clarity of focus, renewed sense of purpose and drive for sustainable growth for shareholders, clients and colleagues.”

    Read more below on the insights and challenges faced and the market outlook for the near future.

    Smart Investor: Congratulations! Can you tell us more about your winning fund in the FSMOne Recommended Unit Trusts Awards 2022/2023?

    Gerald Ambrose: Firstly, thank you for selecting abrdn Islamic World Equity Fund (AIWEF) as one of FSMOne’s Recommended Unit Trusts for 2022/2023. This is a testament to all the hard work that the team behind the Fund had put in to deliver an investment solution which has been very
    well-received by investors in Malaysia. AIWEF is a global equity fund which was incepted on 6 February 2013. It invests in an international portfolio of Shariah-compliant equities and equity-related securities which offer good growth prospects.

    The Fund is benchmarked against the MSCI ACWI Islamic (Shariah) Index and seeks to offer investors capital appreciation over the long term. It is well- diversified from a country and sector perspective, providing investors an “all-weather” core portfolio comprising a balance of growth and resilience.

    The Fund uses a bottom-up stock selection approach backed by extensive research and analysis from our global equities team and Sustainability Institute to select high-quality companies with qualities such as strong cash flows, healthy balance sheets, sustainable business models and sound corporate governance principles. With a track record of almost 10 years, the Fund’s investors have enjoyed an annualised return of10.3%* p.a. since inception.

    * Annualised return is gross of fees. Past performance is not a guide to future results.

    SI: What are the challenges that you have faced in the past 12 months?

    GA: While the Fund delivered a very strong return of 26.8%* in 2021, market conditions in 2022 have proven significantly more bearish. The global economy continues to face multiple headwinds to asset performance. The challenge has been sentiment and macro factors driving market movements rather than company fundamentals. The rotation of the market towards value stocks has meant stocks with high-quality fundamental characteristics have not been recognised or factored into share prices despite many companies reporting solid operational results.

    Instead, concerns over conservative guidance and lower expectations have overshadowed them. Amidst times of market volatility, our focus is on the process of identifying quality businesses that have enduring business models.

    This current market has been challenging for short-term performance, however, we have been using this as an opportunity to build positions in high conviction names at lower relative prices. We remain disciplined and committed to the equity process.

    *2021 calendar year return is gross of fees. Past performance is not a guide to future results.

    SI: What are the market trends that an investor should look out for in the near future?

    GA: We would remind investors of the importance of diversification and urge caution in the face of uncertainty. Fund managers are worried about
    several key tail risks – soaring inflation and monetary policy, a global recession and geopolitical worries. We see parts of the world still navigating lockdown disruptions – for instance, China and its zero-COVID policy. Geopolitical issues, especially Russia-Ukraine and its knock-on inflationary
    effects on oil and commodity prices have continued to cause supply chain shortages.

    Global inflation is running significantly higher than pre-pandemic levels, requiring tighter monetary policy from central banks to tame it, raising concerns over a potential global recession. Our strategy for AIWEF remains consistent with our global equity process of investing for the long-term in quality businesses with reasonable valuations and robust business fundamentals.

    The Fund boasts a high conviction portfolio of diversified businesses and a balance of defensive and cyclical elements. We believe that the Fund is well-positioned to take advantage of future growth and it benefits from solid underlying structural drivers.

    Gerald Ambrose, Chief Executive Officer, abrdn Islamic Malaysia Sdn Bhd (formerly known as Aberdeen Standard Islamic Investments (M) Sdn Bhd)
  • Interview with AIA Pension And Asset Management, Winner Of The FSMOne Recommended Unit Trusts Awards 2022/2023

    Interview with AIA Pension And Asset Management, Winner Of The FSMOne Recommended Unit Trusts Awards 2022/2023

    Be on the lookout for geopolitical uncertainty, rising rates, slowing growth and election uncertainty

    Smart Investor: Congratulations! Can you tell us more about your winning fund in the FSMOne Recommended Unit Trusts Awards 2022/2023?

    Nor Daliya Mohd Daud: We are honoured to receive this recognition for our AIA PAM Growth Fund. This Fund, which was launched on 16 May 2013, invests in equities with a bias towards equities with potential for growth. The Fund will invest in local and foreign markets as it seeks to provide long-term risk-adjusted returns to its members by integrating rigorous fundamental research with disciplined risk management.

    We incorporate Environmental, Social and Governance (ESG) considerations into the investment decision-making process as we believe ESG principles underpin proactive risk management.

    Since its inception, the AIA PAM-Growth Fund has recorded a cumulative return of 57.2% as at end March 2022.

    SI: What are the challenges you have faced in the past 12 months?

    ND: In addition to COVID-related lockdowns within Malaysia and in other major markets which restricted movements and impacted market sentiments over the past year or so, other more recent challenges include Russia’s invasion of Ukraine, soaring commodity prices and supply chain disruptions.

    Underperformance in Chinese stocks had also caused equities to decline and bond yields to rise while accelerated monetary policy and quantitative tightening by the US Federal Reserve and Bank Negara Malaysia (BNM) is now a major concern. Notwithstanding the evolving market conditions, we
    will remain vigilant and adjust our investment strategies accordingly when the need arises.

    Asset allocation decision remains the key driver when determining the range of portfolio outcomes amid volatile markets. We may adopt a temporary defensive strategy during adverse market conditions by increasing exposure to lower risk assets.

    SI: What are the market trends that an investor should look out for in the near future?

    ND: Geopolitical uncertainty. Market volatility is likely to persist in the near term given no signs of the war ending in the Russia – Ukraine conflict. The longer the war drags on, the longer sanctions will be in place with negative implications on commodity supplies and further increased inflation risks.

    Rising rates. Bond yields are rising as the market has been repricing due to the number of rate hikes by the US Federal Reserve that should occur in the foreseeable future. The US Federal Reserve and other central banks are moving to normalize monetary policy to tackle inflation. Domestically, Bank Negara Malaysia’s policy measures should remain accommodative in the near term and the supply of sovereign bonds should be well-absorbed by the market. Overall, the domestic financial system liquidity remains ample, which shall remain supportive of the bond market.

    Slowing growth. After a strong economic rebound in 2021, a slowdown in the global economy is expected this year amid less favourable market conditions with rising inflation, China COVID-19 lockdowns and geopolitical concerns.

    Election uncertainty. There are news that the 15th Malaysian General Election will be held this year. The uncertainty in the general election outcome could trigger volatility in the market. Investors would want to see decisive policy decisions to combat inflation and a slowing economy.

    Nor Daliya Mohd Daud, Director, AIA Pension and Asset Management Sdn Bhd
  • FSMOne Malaysia Is Positive That Investment Opportunities Are Abound In The Current Market

    FSMOne Malaysia Is Positive That Investment Opportunities Are Abound In The Current Market

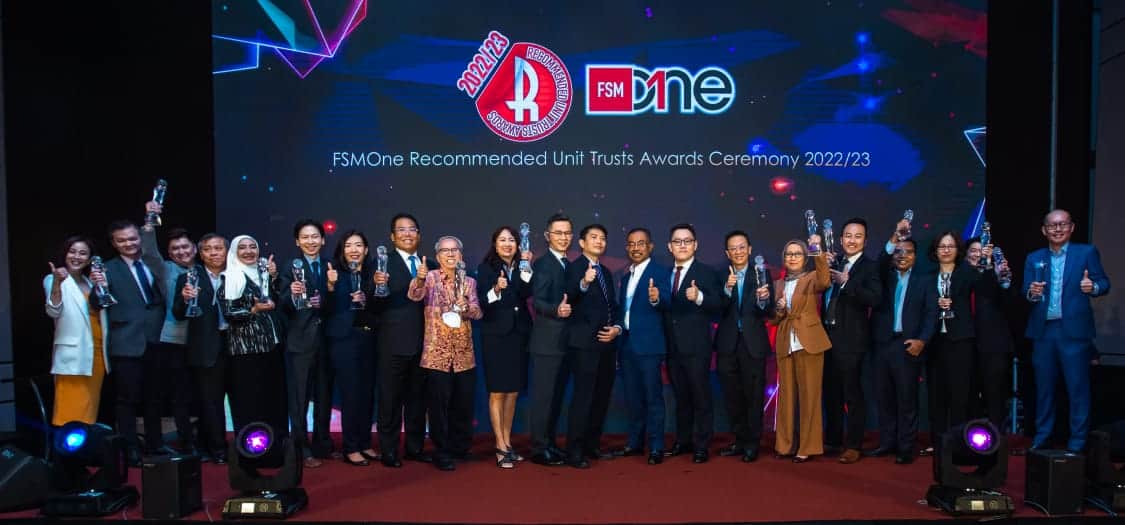
    FSMOne Malaysia, a multi-asset investment platform today assured Malaysian investors that unit trusts are still relevant and viable option that can help them achieve medium to long term financial goals. This assurance was reiterated at the FSMOne’s Recommended Unit Trusts Awards 2022/2023 at Pavilion Hotel, Kuala Lumpur earlier today.

    The Awards, which are distinguished acknowledgements of outstanding fund managers that have produced best-in-category fund performances, saw 44 Recommended Unit Trusts from 17 fund houses, including Affin Hwang Asset Management Berhad, Manulife Investment Management (M) Berhad, Principal Asset Management Berhad, RHB Asset Management Sdn Bhd, Kenanga Investors Berhad, Eastspring Investments Berhad, and AmFunds Management Berhad, to name a few, make it to the list (see appendix for the full list).

    Mr Koh Soo Cheng, General Manager of FSMOne Malaysia during his presentation emphasised that unit trusts continue to be an essential investment vehicle for all investors as they allow investors to build highly personalised and appropriately diversified portfolios to achieve their financial goals.

    “From our analysis, we observed that throughout various market cycles over the years, the performances of our Recommended Unit Trusts have consistently been up to the mark against peers within the same category,” said Mr Koh Soo Cheng.

    “The huge following of our Recommended Unit Trusts is a testament to the trust that our investors have on our selection methodology,” added Mr Koh Soo Cheng.

    The Recommended Unit Trusts were assessed on both quantitative and qualitative parameters. The quantitative parameters included Returns, Risk, and Expense Ratio while the qualitative parameters considered were the consistency of fund managers in their investment approach, stability of the management team, and the departure of key personnel, among others.

    “With an increase in our client base for the past 2 years, I believe that financial literacy among our investors is now more evident than ever. Besides FSMOne Recommended Unit Trusts lists which serves as a good point of departure for new investors, they can also get investment ideas from iFAST TV. It is an investment-focused channel committed to creating relevant, informative and engaging video content which was launched last year.”

    “We are committed to provide the best of wealth management all under one platform.  To that end, FSMOne Malaysia has launched stocks and ETFs trading capabilities supporting Malaysia, US, Hong Kong and Singapore exchanges last year, and will be supporting the China A-Shares exchange on 8 July 2022,” added Mr Koh Soo Cheng.

    On the global economic outlook, Mr Jason Wong, Research Manager of FSMOne Malaysia highlighted that he expects global growth to slow in the second half of 2022 amid persistently elevated inflation and monetary policy tightening by major central banks around the world.

    In terms of the market outlook, he expects volatility to persist as lingering risks such as slowing growth, recession fears, high inflation, aggressive rate hikes and geopolitical tensions to possibly drag on towards the end of 2022.

    “That being said, the market retracement this year has dragged down global equities to much more palatable levels, which could present opportunities for long term investors to take advantage of. With a lot of the negativity priced into markets, we would not rule out a gradual rebound amidst the volatility should things turn out better than expected. Some of the potential catalysts for a swift turnaround include inflation abating, China’s reopening and the end of the Russia-Ukraine war,” Jason Wong added.

    Yet, on the other hand, despite the obvious risks, he thinks that the deep sell-off in Chinese stocks could finally be on the cusp of a turnaround. He expects China to roll out more policy measures to help support the economy. In fact, the government has already been rolling out economic support measures and fighting back against plummeting confidence in recent months. Adding to his optimism is the fact that China is emerging from its worst Covid-19 outbreak in more than two years, with daily Covid-19 cases trending down nationwide in recent weeks.

    “Amidst the changes in the macroeconomic environment, fund managers have adjusted their portfolios accordingly towards investments that can better weather rising inflation and interest rates. Hence, we advise everyone not to overlook this opportunity for returns that would contribute to better long term wealth accumulation,” Jason Wong elaborated further.

    This is the 14th year FSMOne Malaysia hosted its FSMOne Recommended Unit Trusts Awards. FSMOne Malaysia has been established in Malaysia since 2008.

    For more information about FSMOne Malaysia and their recommended unit trusts, please visit www.fsmone.com.my.

    About FSMOne Malaysia and iFAST Capital Sdn. Bhd.

    FSMOne Malaysia (previously known as Fundsupermart.com Malaysia) is a Multi-Asset Investment Platform under iFAST Capital Sdn. Bhd. (“iFAST Capital”), established in Malaysia since 2008.

    iFAST Capital is a holder of a Capital Markets Services Licence (CMSL) and is licensed by the Securities Commission to deal in securities (includes Stocks & ETFs, unit trusts and OTC bonds), dealing in private retirement scheme, offer investment advisory services, financial planning services and fund management services in relation to portfolio management.

    iFAST Capital is a Federation of Investment Managers Malaysia (FiMM) registered Institutional Unit Trust Adviser (IUTA) and Institutional Private Retirement Scheme Adviser (IPRA). It is also an approved Financial Adviser licensed by the Central Bank of Malaysia to conduct financial advisory business and also a Participating Organisation of Bursa Malaysia Securities Berhad.

    iFAST Capital is a subsidiary of iFAST Malaysia Sdn. Bhd. which is wholly owned by iFAST Corporation Ltd. (“iFAST Corporation”). iFAST Corporation is headquartered in Singapore and the iFAST group of companies are also present in Hong Kong, Malaysia and China. The company was incorporated in Singapore on 10 January 2000.

    iFAST Corporation was listed on the Singapore Exchange Mainboard in December 2014.

  • Are High-Risk Investments Suitable For Me?

    Are High-Risk Investments Suitable For Me?

    Many investors are familiar with the concept of risk vs reward. There is risk in any investment, whether large or small. For bearing that risk, you expect a return that compensates potential losses.

    In theory, the higher the risk, the more you should receive for holding the investment, and the lower the risk, the less you should receive.

    High-risk investments can come in many different forms; some examples of high-risk investments include cryptocurrencies, options, forex, starting a business and venture capital. Although the potential return of these high-risk investment assets are higher, one must always be aware that they carry a higher possibility of losing money as well.

    investment

    As an investor, one must always look at the big picture and decide what is your investment objective and your investment duration. Examples of common investing objectives for investment can include:

    • Building a passive income stream
    • Retirement planning
    • Children’s tertiary education
    • Purchasing a property

    Before investing, remember to ask yourself three things:

    1. What are you investing for?
    2. Can I afford to lose this money? 
    3. Is it for short term (1-3 years), medium term (5-10 years) or long term, (>10 years)? 

    Different investment objectives would determine if high-risk investments are suitable for you. For example, a retiree would generally be more concerned about preserving his accumulated wealth rather than risking his capital.

    Read : 5 Drawbacks Of Unit Trusts Investment That You Should Know Before Investing

    He would be more focused on ensuring his accumulated wealth will be sufficient to maintain his desired lifestyle for the rest of his life rather than risk it to get higher potential returns. Thus, high-risk investments might not be suitable here.

    Another example would be children’s tertiary education. When investing for children’s tertiary education, one would not want to take too much risk as any reduction in the value of the investment due to market fluctuations might mean that the child has to delay their education, or in the worst scenario, there might not be enough for them to continue their tertiary education.

    Millennials As A Case Study For High-Risk Investments

    investment

    As of 2021, millennials and Gen Z now make up the largest demographic in the workforce. As their disposable income increases, they would have more surplus income to invest. One observation I have made is that younger investors are more inclined towards higher risk investments.

    This is probably not due to higher risk tolerance, but because they want to achieve their goals faster. For a generation used to instant gratification, waiting for one year to get 1.8% return on a fixed deposit is much too slow!

    Fear of missing out (FOMO)

    Millennials and Gen Z have grown up in the age of social media and one impact of that is the desire to keep up with their peers. Seeing the luxurious lifestyles of their peers may make some millennials want to take on higher risk as a method to grow their wealth. Do remember that what we see on Instagram and Facebook may not reflect reality, and taking excessive financial risk just to keep up is unwise.

    Read : Why The Best Investment On Earth Is Earth Itself?

    Availability of information

    Millennials are digital natives and have grown up in the information age. We can now find any information we want with a quick Google search and that includes information about investing. This abundance of information can give millennials and Gen Z the confidence in having the knowledge on investing.

    However, it is important to be able to filter out what is accurate and up to date information when making an investment decision as there are many websites and blogs which are keen to promote their products and investment ideas. One must differentiate knowledge from wisdom and applied wisdom will keep one grounded and clear headed when making an investment, especially when it comes to high-risk investments. 

    Always remember to ask yourself, is this in line with my investment objectives and can I afford to take this risk?

    Be aware of greed and fear

    Greed and fear relate to an old Wall Street saying: “financial markets are driven by two powerful emotions – greed and fear.”. This applies to cryptocurrencies as well. The fundamentals of investing are to buy low and sell high, but greed and fear has caused many investors to behave in the exact opposite manner.

    For example, Bitcoin has delivered returns of 224% in 2020 alone. There are also many other cryptocurrencies in the market which have given even higher returns than bitcoin last year. These sky-high returns have encouraged many investors to invest in the crypto market in hopes of getting ever more returns.

    As an investor, we must always remember that returns are never guaranteed and one must always remember to not let greed blind us to that fact.

    When an investment has given you the returns which you have set for yourself, it is important to have the discipline to sell or lock in your profits. In this way, you can minimise your risk and will be able to enjoy the profits.

    Are High-Risk Investments Suitable For Me?

    High-risk investments can be part of one’s investment portfolio as they can help grow one’s wealth. However, it is crucial to have an understanding of the existing risks involved in high-risk investments and decide if it is aligned with your investment objectives. Finally, remember not to put all your eggs into one basket to ensure you minimise risk to your capital.

    Do take note that your risk profile, commitments and requirements may also change through the years and you may want to adjust your investment portfolio and exposure to high-risk investments accordingly.

    There are strategies you can employ to help manage your portfolio’s exposure to risks, minimising your risks whilst still offering exposure to the potential of sizeable gains. If this is something you find difficult to undertake alone, you can speak to a financial planner or advisor to learn more.

    A financial planner offers a variety of services associated with wealth management, covering a large spectrum of services, from wealth generation, wealth protection, to wealth distribution and can serve as a professional in guiding one in investing their money.

    About the Author

    Nicholas Wong insurance

    Nicholas Wong is a licensed financial planner of IPP Financial Planning Group that specialises in advising professionals and millennials to achieve their financial goals. He can be contacted at nicholas.wong@ipp.com.my

  • How Does Hanlon’s Razor Apply To Crypto Investment Risks?

    How Does Hanlon’s Razor Apply To Crypto Investment Risks?

    In the wake of the massive crash of the Luna stablecoin that brought the crypto industry to its knees, people everywhere are demanding justice. There are memes comparing it to the notorious Bernie Madoff, right next to McDonald’s job ads for those who lost their life savings.

    Blame It On Stupid!

    The creator of Luna which lost almost 100% of its US$40 billion value at one point, told the Wall Street Journal that it’s not a scam: “I made confident bets and made confident statements on behalf of UST because I believed in its resilience and its value proposition. I’ve since lost these bets, but my actions 100% match my words.”

    He emphasized: “There is a difference between failing and running a fraud” (italics added).

    There is an age-old wisdom called the Hanlon’s Razor which states: ‘Never attribute to malice that which can be adequately explained by stupidity’. What this means, reductively, is that not everything is a fraud. People can and do make dumb mistakes.

    So don’t automatically assume that everyone is evil. The world is not out to scam you. Sometimes sh*t happens! You just have to accept that as a part of life.

    If the Hanlon’s Razor is applied to the context of Luna, it suggests that stupidity is to blame: Not everyone is smart enough to manage a multi-billion-dollar crypto fund. Sorry to the investors who lost everything. Do you buy that?

    Law enforcement investigations are now underway. Unfortunately for Luna, stupidity is not a great legal defence. There might not be an intent to defraud investors, but failure could mean negligence which is punishable by law. Were proper measures taken to safeguard investor monies? Was there a duty of care to do the right thing? Did they fail to do so, chose not to react in time, or were wilfully ignorant of the fallout?

    Stupidity Is A Big Risk

    What is not obvious to most investors, and which Hanlon’s Razor elucidates, is that that the risk of stupidity is as serious as the risk of scams! But investors tend to mix up the two even though incompetent or dumb management is a much more outspread problem than perceived. While scams are intentional, stupidity is not and generally can’t be helped (‘if you are dumb, you are dumb, so help you God’).

    One reason is because so much of the crypto DeFi space is unregulated. DeFi or “decentralised finance” with their anonymous operations and offshoring structures are still beyond the reach of national laws. Furthermore, in a traditional financial firm, the management has to be ‘fit and proper’ with deep requisite experience and board oversight.

    But with most DeFi projects, you are stuck with the founding team. Even if they can’t perform, you can’t fire or remove them. And while they claim to be decentralised, their decision-making flows often indicate otherwise.

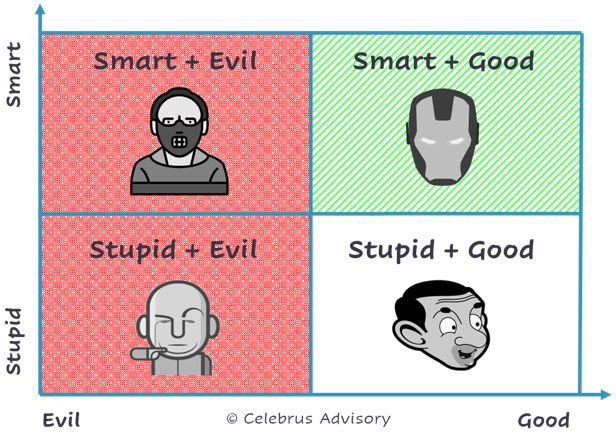
    We created a quadrant to illustrate this. In a very simplistic world where investment projects are ranked on two factors – only 1 in 4 (or 25% chance) have the rare combination of competency and virtue (green area). There is a possibility that 2 out of 4 projects (50% chance) are led by those who are incompetent, or by those with malice (red area). In other words, there is an equal chance of project failure due to either stupidity or scams.

    Each quadrant can be profiled by these fictional ‘straw men’:

    a. Smart + Evil: For instance, pure villains such as Gordon Gekko (the fabled Wolf of Wall Street) or Hannibal Lecter.

    b. Stupid + Evil: This could be like the Dr. Evil and Mini Me characters, or the bumbling burglars in Home Alone movies.

    c. Stupid + Good: A classic case is Forrest Gump, or when Mr. Bean tries to save the world.

    d. Smart + Good: The most relatable is Ironman, a genius and philanthropist, in the Marvel Universe; or Dr. Manhattan in the DC Universe. 

    For the Smart Investor, there are two things to take away from this. First, while there is moral hazard or malice everywhere, it particularly thrives in an unregulated environment. Second, never underestimate the power of stupidity. Dumb management can do a lot of damage. If you want to invest your life savings with a bunch of college dropouts and young punks who genuinely want to make the world a better place, please don’t cry fraud when you lose.

    Disclaimer: Contents above are for educational purpose only.

    About the Author

    Edmund Yong is the managing partner of Celebrus Advisory and appointed by MDEC as part of its Talent Expert Network (formerly known as Digital Expert Panel) for blockchain technology. He is also the resident consultant for GLT Law, a multi-award-winning legal practice with specialisation in digital assets.

  • A Real Life Investment Question Answered 

    A Real Life Investment Question Answered 

    Dear Mr Neoh, I was hoping that you can give me some advice on my situation, below is a bit about me:

    I am Malaysian, now 62 years old. I am currently single, and I am still working for a living. My take home income is about RM3,000. I do have two children who are now already working and in their late 20s/early 30s. I am feeling a bit insecure because currently, I only have about RM40K in savings with me, and this represents the only money (savings) that I have. What should I invest in order to get extra when I am no longer able to work for a living? Recently, I was approached by a Unit Trust person from a reputable unit trust company who invited me to take up a scheme with her in order to grow my wealth. Since I have never had any investment experiences in life, I honestly think that I lack knowledge about investments. I don’t feel confident about this investment. In fact, I feel a little confused. Can you please give me some advice? 

    Mr Ng

    Answer:

    Hi Mr Ng,

    Thank you for your email, I hope after reading this response, you will feel less confused but empowered to make a decision regarding the above.

    I understand that you are still working, and I am assuming that the take home pay of RM3,000 mentioned here is a net income, consistent month-to-month.

    While I agree that you should actively look for options to invest your money, it is very important for you to ensure that you make a good, quality decision.

    This is because, if you invested into something that is too risky for you, or into something that is not what it seems to be, your chances of losing your money will be higher. This will be very dangerous for you, considering that you are now in your sixties.

    Based on the illustration above, let us assume that you invest all RM40,000 but you suffer a loss of 50% in the first year. You will end up with just RM20,000. If this misfortune happens, you will then need a long time to get back to the original amount of RM40,000, assuming you are able to rebalance the remaining RM20,000 to an investment or portfolio that can grow at 10% pa.

    The above projection shows that if invest RM20,000 into something that can generate 10% a year for the next few years, you will need seven years and four months before you can get back to the original amount of RM40,000; and by that time, you will be 69 or 70 years old.

    Of course, if you can only feel comfortable investing into a “safer” investment generating 5% a year, you will need 14 years to get back to the original amount of RM 40,000 as can be seen in Illustration 3. By then, you would be 76 years.  

    The above example is why it is very important for us to ensure we don’t lose our money by investing into things that we do not understand, or are too risky to match our risk profile.

    At the age of 62, and with RM40,000 being your total savings at this point, you may want to be conservative with your money. Having said this, it does not mean that you should just keep all the money in a savings account or all of it in Fixed Deposit. Because this is also dangerous since our purchasing power will decrease every year due to inflation (where you need to pay more to buy the same or even lesser amount of the item you need).

    Therefore, you should consider investing not more than 20% of your money into equity (stocks or shares). But investing in shares requires knowledge, time, effort, and you will also need a bigger capital to have a reasonable holding of stocks that are properly diversified.

    I suggest you invest into stocks or shares through a Unit Trust fund. You can invest into a Unit Trust fund that invests in “Blue Chip” stocks as it is more stable and less volatile compared to other stock funds.  An alternative to a blue-chip stock fund, will be a Balanced or Moderate fund.  This type of fund typically invests 50% of the money into stock and 50% into fixed income instrument, so it will be quite safe, since we limit your exposure to not more than 20% of your wealth.

    I do not know the kind of fund or scheme the unit trust agent recommended that you invest into, therefore, I cannot comment on the suitability of the fund for you.  

    It is however very important for us to note that no matter what you will eventually invest in, the investment has to be one that suits your current needs, your capacity for risk-taking, and if things go south, will not put you into a position that will likely lose most if not all of your savings.

    About the author

    kevin neohKevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my
  • SC Releases New Sukuk Framework to Facilitate Companies’ Transition to Net Zero

    SC Releases New Sukuk Framework to Facilitate Companies’ Transition to Net Zero

    The Securities Commission Malaysia (SC) today launched the Sustainable and Responsible Investment linked (SRI-linked) Sukuk Framework (Framework) to facilitate fundraising by companies in addressing sustainability concerns such as climate change or social agenda, with features that relate to the issuer’s sustainability performance commitments.

    With the accelerated shift towards developing a climate-resilient future, high-emitting industries are at a high risk of being phased out. The SRI-linked sukuk will enable companies in these as well as other industries to transition into a low-carbon or net zero economy. As at December 31, 2021, the global sustainable bonds outstanding exceeded USD1 trillion with sustainability-linked bonds making up USD118.8 billion [1].

    The Framework is an extension of the initiatives under the SRI Roadmap that was introduced in 2019 to broaden SRI products offerings. More significantly, this initiative reflects the SC’s commitment to expand the reach of the Islamic Capital Market (ICM) to the broader stakeholders of the economy and build an enabling ICM ecosystem for the sustainability agenda.

    The SC recognises that there are significant opportunities for the market to attract a more diverse issuer and investor base and undertake a wide range of sustainable projects.

    The SC Chairman Dato’ Seri Dr. Awang Adek Hussin said, “The SRI-linked Sukuk Framework will encourage greater mobilisation of private sector and issuers’ financing towards sustainable development and meet the increasing global demand for sustainable financing. This is in line with the initiatives outlined in the Capital Market Masterplan 3 to reinforce Malaysia’s value proposition as the regional centre for Shariah-compliant SRI.”

    Under the Framework, the proceeds raised can be utilised for general purpose, subject to the issuer committing to future improvements for sustainability outcomes within a predefined timeline, which will be monitored using key performance indicators (KPIs).

    The financial characteristic or structure of the SRI-linked sukuk may be varied based on the success or performance of the issuer in meeting its KPIs and sustainability goals.

    The Framework also provides greater transparency for investors by requiring issuers to appoint an external reviewer before issuance and an independent verifier postissuance to assess compliance with the framework and issuer’s sustainability performance which can be tracked by investors.

    Further details of the requirements for the SRI-linked sukuk are set out in the Guidelines on Unlisted Capital Market Products under the Lodge and Launch Framework and the Guidelines on Issuance of Corporate Bonds and Sukuk to Retail Investors, which can be downloaded here.

    [1] Source: Sustainable Debt Global State of the Market 2021, Climate Bond Initiative

    About the Securities Commission Malaysia

    The Securities Commission Malaysia (SC), a statutory body reporting to the Minister of Finance, was
    established under the Securities Commission Act 1993. It is the sole regulatory agency for the regulation
    and development of capital markets. The SC has direct responsibility for supervising and monitoring
    the activities of market institutions, including the exchanges and clearing houses, and regulating all
    persons licensed under the Capital Markets and Services Act 2007. More information about the SC is
    available on its website at www.sc.com.my. Follow the SC on twitter at @SecComMy for more updates.

  • Financial Scams : Fear, Greed & Ignorance

    Financial Scams : Fear, Greed & Ignorance

    I still remember a business owner who asked my team to create his portfolio to make sure he would have enough money for his retirement. We advised that he could earn solid returns from a diversified global portfolio based on his financial profile.

    He was assured that part of the strategy drawn up for him would spin out a good amount of cash on a regular basis. I convinced him to “buy” some sleeping pills and take a slightly higher level of volatility to achieve better capital growth.

    A week after the meeting, he came back and said he was no longer interested in my portfolio because he had found a much better opportunity elsewhere. He said that a financial salesperson had explained to him that he could make more profit with lesser risk if he took another investment product.

    All That Glitters Is Not Gold

    scams financial

    A few years later, the same business owner revealed to me that the investment he had bought into performed terribly. It turned out to be more volatile than he had thought. It is no consolation to realize that he, along with others who had also bought into that product without taking a balanced look at all the facts, will suffer.

    Remember all those expensive, slickly produced advertisements boasting market beating ratings and top quartiles? Contrary to what nearly everyone believes, you do not make money buying an investment just because it “looks good” on the surface.

    Yeah, everyone is going to get rich washing Mercedes, and BMWs. How about slogans like “You can become a millionaire in three years”, “You can turn your financial dreams into reality”, “Amazing, fabulous, unbelievable strategies for building massive wealth”, “You can invest with the world’s blue chip funds with as little as…,” and so on?

    Life is not all sunshine and lollipops. There will always be financial salespeople with sketchy reputation or those who will put their own interests before their clients. They are usually well spoken and persistent and like to target the most naive and least informed investors.

    I have no desire to offend anyone. Speaking from my experiences, it is commonly believed that those working in the sales department of bigger institutions are compensated well because they make money for investors. Yet, some of their clients are getting worn down. Some are still losing money or making very little money after so many years.

    Taking Advantage

    scams financial

    I have seen investors saddled with unnecessary charges and lengthy lock-up periods. It is good for the seller but not the poor investor buying it. Some of these investors have absolutely no idea how badly they are being ripped off. Anyone with eyes and a brain knows what I mean.

    So, you have been told not to worry just because your investment is being managed by the captain who has been dealing with multi millions or billions for a long time. Well, so what? Someone used to share with me that some fund managers should not be allowed to run a grocery store, let alone operate a billion-dollar investment vehicle.

    Sorry to throw up at your party. There are some fund managers with poorer track records and far less skill but are managing far more money. Yet, some other great managers slip under the public’s radar because of the lack of publicity.

    In my work, I love to find managers who have some limited capacity, so the big boys cannot compete against them. It is about sustainably higher returns for investors, not scale. Big is not beautiful here.

    Many of you out there have been scammed, in one way or another, at some stage. Beware of financial schemes or money games guaranteeing anything from a few percent to double-digit returns within a few weeks or months. Financial scams are so popular because they take advantage of people’s fear, greed and ignorance.

    The whole idea behind a scheme is that they do not want you to understand anything. Anyone can make any story out of thin air which is absolute nonsense. The fraudster allays your fears and provokes your greed, they entrap you by befriending you, and they say the investment is riskless then they talk about returns.

    Betraying Your Trust

    scams financial

    Some of the victims are professional business people because they are intelligent, they think they should understand what they are being told, so they go along with it. The people who sell them are often someone whom they know for a long time.

    Fraudsters and operators of financial scams sometimes target business groups in order to find their victims. In some cases, members have innocently encouraged each other to put money into such schemes. Run like hell if someone is pressuring you to make a decision at any financial events.

    Most of the modern schemes are versions of old frauds, first committed more than 100 years ago. They are known as Ponzi Schemes after a 19th century fraudster named Charles Ponzi who was offering a 50% return on investment in just 45 days.

    Fraudster draws victims in by honouring the agreed interest for the first few installments, then drawing more and more money from them as they start to believe they are on to a sure thing. It is like “robbing Peter to pay Paul” as the fraudster pays the initial interest payments with the investments from other victims who have fallen for the scheme.

    Always open your eyes. If you leave your head in the sand and ignore it, you are only going to be victimised.

    About the Author

    YH Wong has over two decades of experience in the financial services industry. His clients include high net worth investors and boutique institutions such as family offices and investment partnerships in the region. He is currently a senior partner with Satori Consultancy Ltd, a financial services company regulated by the Mauritian Financial Services Commission. He can be reached at yhwong@satoriconsultancy.com.

  • How Does Gresham’s Law Apply To Private Money Like Crypto?

    How Does Gresham’s Law Apply To Private Money Like Crypto?

    Back in 2018, the Managing Director of the Monetary Authority of Singapore (MAS) Ravi Menon, gave a speech about the future of crypto and cited an old concept in economics known as Gresham’s Law, which is loosely interpreted as ‘bad money drives out good money’.

    He opined: “Like Money, crypto tokens can be a force for good or bad… It is the enchantment with these tokens as a way to make a quick buck and their abuse for illicit activities that are at the root of our concerns.”

    Therefore: “We must work together – regulators and the crypto industry – to make sure that bad money does not take hold. And that a new generation of crypto tokens emerges, that harnesses the potential of blockchain technology for social good while mitigating the risks today’s tokens pose.”

    Good Money vs. Bad Money

    crypto

    The original concept in Gresham’s Law is that in an economy where there are two currencies with the same face value, people will use up first the currency that is constantly devaluing (bad money), and hoard the currency that retains or increases in value (good money). 

    For example, let’s say you are given equivalent amounts in both MYR and USD. As MYR keeps depreciating against USD, you will spend MYR first and hold USD in reserve. The so-called ‘bad money’ would be used for daily transactions and dominate circulation, while ‘good money’ would eventually disappear from circulation as it is kept for savings and long-term investment.

    Imagine now that you are given BTC (bitcoin) instead of USD. If you expect that BTC will rise in value, you will not pay your daily expenses with BTC as you may lose out on its future valuation. This is one of the reasons why BTC has grown faster as a store of value than as a means of payment.

    Going back to the MAS speech: Interestingly, it applies the concept to market conduct. It refers to the illicit use of crypto by bad actors in the market, along with the profusion and poor quality of crypto products as a form of currency. If these bad actors continue to flourish, they will crowd out and drive away the good actors. The crypto industry and its innovation benefits will suffer as a result. 

    But if crypto can be used responsibly as a force for good, it will be ennobled and gain wide acceptance by the public. This would turn into the opposite of Gresham’s Law (known as Thiers’ Law) which states that ‘good money will drive out bad money’.

    Is Private Money Good or Bad?

    crypto

    The characterisation of crypto as either good-or-bad is not always helpful. Private money like crypto, which are not issued by central banks, is very diverse and hard to generalise. Tech is morally neutral. They are self-serving financial constructs and are not mandated to be a public good. The vast majority of them are work-in-progress prototypes that will fail.

    On one hand, you would read of industry reports claiming that illicit or criminal activity constituted only 0.10% (according to CipherTrace) to 0.15% (Chainalysis) of total crypto transaction volume in 2021, the lowest level ever. This makes crypto sound like a model private citizen!

    But on the other hand, the crypto scandals keep getting bigger and bolder, with contagion impact on venture capital and lending companies as seen recently. The industry has spawned an entirely new genre of lawlessness (which Elliptic calls) “DeCrime” which could rewrite the penal code. Black hat hacks are commonplace, highly sophisticated, and even state-sponsored.

    Ironically, as crypto improves and creates better version of themselves, they become too good to ignore. Savings and capital may leave financial systems, for good. Domestic banks may become undercapitalised. In response, governments are mulling to create crypto-versions of central bank digital currencies (CBDC), so that their national currencies will not be substituted by crypto. And they have the natural advantages to do so. As the Bank of International Settlements remarked, “anything that crypto can do, CBDCs can do better”!

    Investors are at a unique point in economic history. They are spoilt for choice between private money (crypto) and public money (fiat), something that was unthinkable a generation ago. They have free capital movement, in the truest sense of the word, across borders, assets and entities. Whether this is ‘good’ or ‘bad’ is anyone’s guess.

    Disclaimer: All opinions expressed above are the author’s own.

    About the Author

    Edmund Yong is the managing partner of Celebrus Advisory and appointed by MDEC as part of its Talent Expert Network (formerly known as Digital Expert Panel) for blockchain technology. He is also the resident consultant for GLT Law, a multi-award-winning legal practice with specialisation in digital assets.