Category: Investments

  • 5 Best Thing To Do When Your Retirement Funds Are Insufficient

    5 Best Thing To Do When Your Retirement Funds Are Insufficient

    Most working-age Malaysians have certain ideas of how they want to live their retirement years, but more often than not, the stark reality of retirement paints a picture that is far from rosy.

    Challenges such as the lack of adequate savings and rising medical costs are knocking well-made retirement plans off kilter, and thus reducing the value of one’s nest egg. Throw the Covid-19 pandemic into the fray and Malaysians are suddenly discovering that their retirement funds are insufficient.

    For context, according to Employees’ Provident Fund (EPF), current EPF savings for most Malaysians are barely enough for a decent life after retirement. In fact, statistics indicate that 70% of Malaysians outlive their retirement savings – those who withdrew their funds at age 55 use up their savings less than a decade after retiring.

    epf retirement

    Equally troubling is the fact that more than two-thirds (68%) of EPF members aged 54 had less than RM50,000 in EPF savings, and with the household poverty line income at RM930 monthly, the RM50,000 in savings will only last approximately 4½ years. The bottom fifth of EPF members, meanwhile, have average savings of only RM6,909.

    Read : Retirement Planning, Why It Is Important From An Islamic Point Of View

    This begs the question: is having insufficient retirement funds beyond one’s control given the worsening global crisis, or could this be due to poor financial management?

    Managing Priorities And Habits

    Retirement planning can be daunting, but the beauty of the process is that it allows you to think about your retirement goals, how long you have to meet them, and most importantly, it allows you to work out how much you would need to comfortably enjoy your golden years.

    “Retirement planning can be planned, but at the end of the day, it all comes down to one’s priorities and habits,” opines Harveston Wealth Management financial advisor Annie Hor.

    “If you are in your 50s and have nothing prepared for retirement, you are in a lot of trouble. You may not be able to stop working immediately and would need to start relooking at your expenses and trim as much as possible while saving most of your nett income,” she says.

    Hor goes on to share that she once advised a client in his late 50s to immediately cut back on his lifestyle and spend no more than half of his income.

    “The client is single, has a house that has been paid up, and other loans. However, he has no one to depend on and has less than RM150,000 in his savings and EPF account. While he has a medical insurance, he also has a medical condition that requires regular treatment which is not covered by his medical insurance.

    “At the moment, he can still claim employee benefits, but because of his age and low resources, he is unable to maximise his investments and would need to be mindful about his money management,” Hor recalls.

    Hor cautions that despite not being in a similar situation, one should not make the mistake of thinking that time is on his side and that he still has many more years ahead of him to plan for his retirement.

    “We don’t have much time to plan for retirement as there will always be distractions and setbacks in life, chief among them being getting married and starting a family, worrying about your children’s school fees, having to take care of your ageing parents, and even the Covid-19 pandemic,” she reveals, adding the earlier one sets his retirement plan in motion, the better.

    Ensuring you have medical insurance is the basic foundation of financial planning. If you do not have one, falling ill can potentially affect your wealth, she adds.

    “Medical insurance can secure your coverage for today and for the future. This is because when you are much older and possibly less healthy, it would be difficult to get adequate insurance coverage even if you are willing to pay for it.”

    Bridging The Growing Gap In One’s Retirement fund

    While EPF does its best to support one’s post-retirement life, simply relying on it alone is not enough, as indicated in the revision of the minimum savings target in 2017, which saw the EPF raising the minimum savings target by age 55 from RM196,800 to RM228,000.

    Suffice to say, active contribution to one’s EPF account alone may be insufficient for achieving one’s retirement goals, and Malaysians would need to explore other avenues to give their nest eggs a boost. And a useful tool that one can consider is private retirement schemes (PRS).

    retirement plan

    “PRS was introduced especially for Malaysians to save for their retirement in a structured and regulated scheme. It complements the mandatory contribution scheme to bridge the retirement savings gap.

    “If you are self-employed and do not contribute into a mandatory scheme, PRS is a great avenue to start building your savings as it provides diversification into various asset classes in multiple regions to grow your retirement nest,” Private Pension Administrator (PPA) Malaysia CEO Husaini Hussin tells Smart Investor.

    According to PPA’s survey last year, 67% of the respondents want to save more for their retirement.

    “However, as we go about our lives balancing various commitments, perhaps at one point it became inconvenient to find the time to set up an account. Or maybe we procrastinated a little in another instance and forgot to follow up later on. One way or another, this intention of wanting to save did not translate into action.”

    As such, with the PRS Online service developed by PPA, the user experience of opening a PRS account is now made easy, convenient and secure. A seamless process, Husaini stresses, will be one less barrier for Malaysians to enrol and continually top up their PRS accounts.

    “It is never too late to start. In fact, the government encourages you to save with a PRS Tax Relief of up to RM3,000 each year. This means that when you start saving in PRS, not only are you saving for your future, you also get to enjoy immediate benefits through the tax incentive. 

    “For example, if your tax bracket is 24%, then just by setting aside RM250 per month into your PRS account each month for one year will earn you a tax savings of RM720. Reinvesting the tax savings on a yearly basis will further compound the growth of your retirement fund,” he explains.

    Husaini urges those who just entered the workforce should start saving too. “It’s a myth when people tell you that it’s too early to plan for retirement. Young Malaysians aged 30 and below get to enjoy 0% sales charge when they enrol for a PRS account with PPA’s PRS Online service.

    “Get into the habit of setting aside a fixed sum into a retirement fund each month as saving regularly is more important than how much you actually put away, because even small amounts add up over time,” he advises.

    Weathering Unexpected Setbacks

    Unexpected setbacks like the Covid-19 pandemic are oftentimes inevitable and can put a glitch in one’s retirement plans, and temporary as they are, they can negatively affect your existing retirement plans.

    retirement funds

    “You may need to tap into your savings meant for retirement in such situations, but if you have done proper planning, your retirement planning is in fact not even your savings. You should have emergency funds at hand to weather these unexpected setbacks, and this will ensure that your retirement planning will still be untouched and intact,” Harveston Wealth Management’s Hor explains.

    While the pandemic is unavoidable, she believes the situation can be rectified with proper planning. “Make sure that you have sufficient emergency funds to last you about three to six months should something like this happen again.

    “On top of that, review your household expenses and try to use less than what you are currently earning. If you keep your lifestyle just within your average means and do not maximise your borrowings, you would have less to be worried about,” Hor suggests.

    Worth a read : Saving Up For Our Retirement, Is It Possible To Do It Post-Pandemic?

    On what Malaysians can do if their retirement funds are insufficient, here’s her advice: “First, find out what kind of retirement you would like to have. Then, look at your current resources and identify which basket of assets is meant for your retirement. Your next step is to identify the shortfalls and gaps, and ways that you can fulfil these realistically.”

    “Start trimming down unnecessary wants and expenses and start investing for the future. You don’t only work to spend today. You work to spend today and save – or invest – for tomorrow.”

    Doing The Math For Your Golden Years

    If you are a young adult today (say, in your late 20s or early 30s) and taking into account the fluctuating global markets, how much would you need to retire comfortably?

    How much one needs for retirement will depend on their current lifestyle. Studies have indicated that we will need 2/3 of our last drawn salary as replacement income to maintain our current lifestyle in retirement.

    This is because work-related expenses such as commuting would no longer be incurred and long-term loans such as mortgages would most likely have been settled. In order to achieve this, we should aim to save 1/3 of our salary today.

    The good news is, if you are currently employed, you are probably already contributing 11% of your salary into a mandatory scheme each month. Your employer also contributes at least a further 12%, which brings the total contribution to 23%.

    Therefore, you just need to top up an additional 10% to achieve the 1/3 minimum. I say ‘minimum’ because one should first aim for 10%, and then plan to save more as our earnings increase.

    As the amount each person needs for retirement differs, we have created a retirement calculator on PPA’s website for those interested to simulate different projections and scenarios. You can use it as a guide to design an accumulation plan to reach your retirement savings goal.      

    Handy Tips For Retirement Planning

    retirement plan

    When it comes to ensuring sufficient retirement funds, good financial planning is paramount. Here are some important tips on saving and investing for one’s retirement.

    1. Never underestimate the importance of having your own personal medical insurance. That way, in the event of a medical emergency, you can rest assured knowing that you can file a claim with the insurance company rather than tapping into your retirement funds;
    2. It is not too early to plan for your retirement. You can always start early, and even if you do not have children, you can always start investing early for your children’s education. The sooner that you start, the better;
    3. Take a bit of risk when it comes to retirement planning. You need to look at investing to grow your monies to beat inflation and not depend only on your savings to retire. Have a licensed financial adviser review your investments and help make sure that your investments grow according to your desired returns;
    4. If your resources are limited, do not try to look at settling your mortgage and car loans and forgo investing. You might be asset rich but cash poor when you retire.
    5. Always make sure that your children’s education plan and your retirement planning are done separately. If you do not plan for your children’s education, you might end up using your EPF to fund your children’s education. If you cannot afford to do both education and retirement planning, remember that you can borrow money for education but not for retirement so make a wise decision.
  • From Almost Being Murdered To Setting Up A Digital Marketing Agency, To Branding And NFT

    From Almost Being Murdered To Setting Up A Digital Marketing Agency, To Branding And NFT

    The story that we are about to share with you is truly an interesting one. It is about an individual who bounces back after a tragic event to reach greater heights.

    Let’s meet Mr. Sanz Teoh, Chief Executive Officer and Founder of Jumix and his inspiring story below.

    Smart Investor: Thanks for taking the time to talk to Smart Investor. Can you tell us a little bit about yourself, about Jumix, and what makes you started the company?

    Sanz Teoh: Hi, I’m founder and CEO of Jumix. In 2014, I was almost murdered by a local gangster group. That inexperienced me was trying to work a side hustle while having a full-time digital marketing job.

    It was at that moment, I decided that I have to fully commit my time, effort, and energy to my own business. I promised myself that no one else in this world should go through the same experience as I did, and I set out to make this my business mission.

    Combining my educational knowledge in marketing and my personal passion in creating digital products, I founded Jumix. It started off as a web design & digital marketing agency, now we also do Branding and NFTs for businesses.

    nft

    Smart Investor: We heard about your recent foray into the NFT scene with BeU, care to elaborate on that?

    Sanz Teoh: Yes, and I’m very excited about this. There’s a story behind why we are doing NFT. Previously during the MCO, we have a long discussion with a creative agency to come out with a ‘Virtual Influencer’ that is set for a launch in late 2020.

    My entire team put a lot of effort and commitment into that project. But due to some contractual dispute, the plan didn’t work out. It is then we decide to take things into our own hands, and is determined that we are going to create something new all by our own instead of working with another agency.

    This is why we decided to dive into the NFT scene. Being a seasonal cryptocurrency investor and familiar with blockchain technology myself, I proposed to my team that we can use utilize our creativity to create characters, which will then be a set of collectibles on the blockchain.

    Starting from scratch, my team brainstorm, sketch, draw, produce and code the entire BeU NFT project. Throughout the entire journey, we learnt a lot more about NFTs and how NFTs can really help brands and creators to bring a lot more to the table.

    People who are interested in an NFT project can ‘own’ it and enjoy the benefits or utilities that the NFT project gives.

    For example, people who own BeU NFT will get another NFT for free, which is the ‘egg’ of the original character, which will ‘hatch’ and revealed later on. It would remain a mystery for now.

    All owners will also get to involve in the roadmap of BeU project, which include deciding on which charity foundation that we will donate our money to, getting access to exclusive BeU merchandise, stand a chance to win life-size BeU figurine, and ultimately, be the first to access the virtual world that BeU created – BeUtopia.

    Smart Investor: How big is the NFT industry in Malaysia and are Malaysians ready to get on board the NFT phenomena?

    Sanz Teoh: I would say that the NFT industry in Malaysia is still pretty new. But so far I’ve already seen quite a number of artists, creators and brands that have dived into NFTs.

    Things are just going to get more interesting for Malaysians, but just like any other market, there’s always a stigma when it comes to adopting or investing into something new.

    I believe with more brands and creators embracing NFT with more following suit, this is why Jumix is going to bring more both brands and creators into this industry, and drive the growth of Malaysia’s market together.

    Smart Investor: With the recent crash of the crypto market, does it have an effect on the NFT market?

    Sanz Teoh: Crypto market has its ups and downs over the years. While I’m not talking about cryptocurrencies trading, the price crash of crypto does affect the NFT market as well.

    When prices of crypto drops, it actually makes NFTs more appealing, as you can now purchase NFTs at a much lower price. This makes collecting or investing in NFTs much more approachable to the public.

    Smart Investor: Can you share with us your plans for the future?

    Sanz Teoh: BeU is only the first NFT project that Jumix pushes out, we’ll have more NFT projects in collaboration with other brands, which would include more utilities, features and more creative concepts.

    For the next 6-12 months, other than growing the BeU community, I’m also looking to work with brands who are interested in NFT to build new projects with them.

    Smart Investor: What is your advice to Malaysians out there who wants to get involved with NFT?

    Sanz Teoh: There will be two groups of people here. The first ones are the brands and creators.

    For brands and creators, my advice is to get involved as soon as possible, as the trend is rising rapidly and the attention in this space is high. But please do not take this opportunity as a money grab, NFT is still very community-driven and it should be created for the community, not for your own profit’s sake.

    The second group of people are the owners and investors. For investors, don’t take this as a get-rich-quick investment, but something more like a long-term investment. But before putting in your hard-earned money, make sure that you believe in a particular NFT project and do your own due diligence.

    For smaller NFT owners, go ahead and support your favourite creators and brands while enjoying the benefits that the NFTs provides, experience how blockchain and cryptocurrency work, and have fun at the same time.

    nft

    Smart Investor: Can we really make money from NFT, is NFT a good investment to venture into?

    Sanz Teoh: I’m not one to tell people that we can ‘earn money’ from NFT. I would tell them to first, truly understand as to what, why and how cryptocurrency, blockchain and NFT exists.

    Once you fully understand the benefits of blockchain and NFT, then, like any venture or business, you have to be creative, committed, and create something that people want, or of interest, to be able to ‘make money’ from it.

    For the general public, some NFTs project are really good, and has good utilities, visionary founders, responsible project team and for a good cause. These are NFT projects that you can invest into.

    For brand and business owners, investing in creating NFTs is a good way to differentiate your brand and business, raise funds, or to offer additional utilities and benefits to your fans or loyal customers.

    The potential of NFT is vast. With proper strategy and ethical purpose, NFT is definitely the way to go.

  • 5 Reasons Why You Should Invest In REITs

    5 Reasons Why You Should Invest In REITs

    Real Estate Investment Trusts (REITs) can be simply put as shares of commercial properties that are listed in Bursa Malaysia stock exchange.

    REITs are being managed by property developers or professionals. There are many categories for REITs that will convert into a great profitable investment such as malls, residentials, factories, offices and many more.

    You may want to read this : Best Reits In Malaysia. Which One Is Better? Is It Time To Invest Now?

    Simply put, we can say that an amount of monies being pooled together from many other investors to invest in properties. This may be a good alternative rather than you have to buy physical properties which can cost you a fortune.

    Investors who buy REITs’s shares entitled for dividend payments which will be distributed quarterly or semi annually. This is mostly contributed by the rental performance of the properties.

    5 Advantages of REITs Investment

    1. Invest in REITs With As Low As RM100

    Whattt?? You don’t want to risk a lot of your money to your property investment?

    No worries! By REITs investment, you don’t need a huge capital to start. With RM100, everyone give it a go in property investment via REITs.

    Property investment using REITs in stock market
    Source : Bursa Malaysia

    As from the list above, you can see the price per one unit of REITs shares which most of them are below RM1.00. You will need to buy at least one lot which equals to 100 units as fixed by Bursa Malaysia.

    Still, it’s way much cheaper than buying a physical property for investment.

    2. Tax Exemption

    REITs tax exemption

    You don’t have to worry about tax. REITs investment in Malaysia are exempted from tax. If you own a physical property, you will have to pay for taxes, stamp duties and many more during your purchases or disposal.

    You don’t have to pay for Real Properties Gains Tax (RPGT) which will affect your investment returns.

    These taxes exemption are a huge savings where you can save a significant amount of money.

    3. REITs Investment Is Easy

    Don’t get yourself into property investment messes. REITs provides you peace of mind while investing.

    REITs are traded on the Bursa Malaysia stock exchange. You’re not tied to a huge amount of mortgage. REITs are very liquid as they can be bought and sold easily.

    You can have your CDS account, the transaction can be done via your platform. Easy, right?

    4. REITs Being Managed By Professionals

    reits managed by professionals

    Newbies in stock market? Worry no more with REITs investment. Why? Did you know that your REITs investment are managed by professionals?

    Yeah. You heard it right! Managed by professionals unlike investing in physical or conventional property. You don’t have to deal with tenants, local authorities or many other things out there.

    Sit back, relax and enjoy your dividend! (Still, you need to study stocks potentials before deciding to invest)

    5. Higher Dividend Payouts

    Did you know that REITs will distribute at least 90% of their earnings to investors in order for them to qualify for tax reliefs?

    The investors may enjoy 5% to 7% of dividends every 3 months or twice a year depending on the company.

    Well, we can say that the dividends rate is higher that most of the rental properties return.

    In a recent survey of Malaysians carried out by Palindrome Communications, 14 percent of respondents said they thought that REITs were good investments and 29 percent thought they weren’t. The majority of respondents (57 percent) were unsure and opted to ‘sit on the fence’. This could signify a lack of education regarding REITs in Malaysia and mean that members of the public are more familiar with other investment options. Respondents included professionals in technical fields such as engineering, and solar.

  • How Do We Safeguard Digital Assets?

    How Do We Safeguard Digital Assets?

    Digital technology is now an integral part of our lives and, with the advent of fintech, more people are investing in digital currencies and cryptocurrencies.

    Currently, digital assets and planning legacy for such assets tend to be overlooked by many Malaysians in their estate plans. The result is a potential loss of valuable assets and data, some of which are of immense emotional meaning to family members, with money and time spent to track them down.

    While data protection and digital security are important when we are alive, how do we make sure that our digital assets can be accessed by our loved ones when we pass on? The answer is to include them in our inheritance plan. As digitalisation and its adoption continues, planning will become more important.

    What are Digital Assets?

    digital assets


    Digital assets are a collection of binary data online rather than actual physical objects where it is created, stored, recorded in digital devices and/or online services, for example, websites, social media sites, emails, cloud services, mobile phones, laptops, hard drives and computers.

    The most well-known digital asset is digital currency. Other popular digital assets of monetary value are e-wallets, e-commerce accounts, internet domain names, online business platforms and even online storage such as google drive and dropbox as it may contain valuable data.

    These days for creative professionals, their photography and works of art are often found in various online platforms such as shutterstock.com and istock.com. Such platforms allow their work to be sold or used for a limited period. Their work product stored in such platforms are digital assets which generates income and the royalty payments to the account holder.

    In order to gain access to any digital asset stored online, it requires the username and password. If there are multiple accounts for different types of digital assets, the account owner should have an inventory of usernames and passwords for each account. Unfortunately, many people do not bother have such an inventory to organise their digital assets meticulously.

    If an estate plan did not account for digital assets properly and without an inventory list, the executor would not be able to access them. They may not even be aware of the existence of such digital assets. These assets will be lost forever and the heirs might not receive all the money and/or the precious memories that the deceased have wanted to leave for them.

    Digital Assets Inventory

    How then do we safeguard our digital assets?

    First and foremost, prepare a list of your digital assets using a digital assets memorandum (DAM), including cryptocurrency accounts, social media accounts, e-wallets, online securities trading accounts and e-commerce account such as Lazada and Shopee.

    As you would only want a trusted person to have access to your digital assets’ user and password details, you would need to appoint a Digital Facilitator in your Will.

    In your Will, you should state the type of digital assets you own and the beneficiaries who will be entitled to them. You may include the user details, but the passwords must not be included in the Will.

    Your passwords should be stored separately from the DAM and your Will. It may be kept in an encrypted thumb drive in your home safe or safe deposit box or in some secure manner. However, it must be made known to your Digital Facilitator where it is kept and how to gain access to it.

    As you may change passwords from time to time, it is important to update the list of passwords. Otherwise, your Digital Facilitator will not be able to gain access to your digital assets.

    Accessing Digital Assets

    digital assets

    Gaining access to digital assets is difficult. Each online service has its privacy or end-of-life policy and a court order will not count.

    Even if the local court where the owner of the Will resides grants the families access to the digital assets, the laws where the company resides could prevent the families from getting access to them.

    The laws that govern digital assets vary from country to country, and online sites have widely different terms and conditions that sometimes lock out executors. There may even be difficulty to determine which jurisdiction to apply for the court order to let the company allow your heirs to gain access.

    Therefore, it is best to make sure that your estate plans are prepared and executed by lawyers or professional trust companies because it is a specialised area.

    Malaysians aged 18 and above who reside in Peninsular Malaysia and Sarawak are eligible to set up a Will, while people in Sabah are required to be 21 and above.

    This article is contributed by Azhar Iskandar Hew, Group CEO, Rockwills International Bhd.

  • Will Initial Exchange Offerings (IEOs) Change the Crowdfunding Game?

    Will Initial Exchange Offerings (IEOs) Change the Crowdfunding Game?

    In this final part of our article series, we explore the viability of the new IEO model. Two IEO operators have been announced so far.[1]

    From the aspect of the platform, how will these operators perform as a capital formation channel i.e., how will they raise serious money? This has traditionally been the domain of licensed investment banks, so all eyes are on these operators. The business community is eager to hear its first success stories.

    And from the aspect of the market, how will these IEO assets be structured to appeal to investors? These are exotic financial products that befit a narrow risk profile. They have often been compared as alternatives to IPO. Suitable investors who are seeking digital asset exposure in their portfolios might consider this.

    Given that IEO is a major innovation, there are bound to be problems when we look under the hood. They are not operational yet, generally high risk, and involve novel points in law. Many things could change, including regulatory positions over time. Hence our opinions too are tentative.

    Is There Enough Local Investor Base for This?

    The IEO operators’ role is to draw investors into the platform. But they do not underwrite raises. In other words, they do not guarantee results.

    When you do the math, you will understand that this is not retail play. Here is a simple back-of-envelope calculation: Retail investors can only invest up to a limit of RM2000 per project. If a project has a RM100 million target, it will need to raise from at least 50,000 retail investors – assuming every single one of them maxes at RM2000, passes background checks, and nobody backs out during the cooling off period.

    Imagine the sheer marketing cost and investor relations effort needed to convert such a large group. Imagine the due diligence work to onboard 50,000+ names.

    And there is a further rub: According to the Securities Commission (SC), the total number of investors that have collectively used ECF and P2P financing platforms since 2017 is only about 31,000 investors![2] So IEO operators – if they focus only on the retail segment – will need to be able to recruit new adequate investor bases to cover the demand, presumably within Malaysia itself.

    This is the reason why institutional participation and sophisticated investors will be crucial to the success of IEO. They are the main target.

    But it remains to be seen whether the IEO operators will take an active role in building the order books i.e., sourcing investor demand; or whether they will merely facilitate the offering like an ECF model.

    Rather than setting a blanket investment limit on all retail investors, the regulators should consider marketing restrictions and ensure IEO operators perform suitability assessment on all investors. This could ease the fundraising burden of IEO operators. Even with the investment limit, vulnerable investor groups like the elderly and financially illiterate can still be indiscriminately targeted by IEO marketing.

    What Would IEOs Look Like Without Crypto?

    At first thought, the local digital asset exchanges (DAX) may seem to provide some low hanging fruits and serve as the addressable market for IEOs. The number of DAX accounts has been growing phenomenally and may well cross 1 million this year.

    But investors who are used to trading highly liquid digital currencies like Bitcoin and Ether might not have the same appetite for tokenised private securities like IEOs.

    The biggest impact will come from the restriction on the use of crypto (or digital currencies) to pay for IEO investment. This effectively turns off the crypto segment and the entire trillion-dollar global crypto capital pool. While it is possible to cross-sell IEOs to third party DAXs in Malaysia, DAX customers cannot use their crypto holdings to invest in IEOs.

    Foreign-based crypto investors including hedge funds and venture capitalists will have to convert into Malaysian Ringgit, wire through the correspondent banking system, and be subject to exchange control rules.

    Why is crypto restricted? Perhaps from a compliance viewpoint, this mitigates the money laundering and terrorist financing (MLTF) risks associated with crypto. Unlike DAXs, the IEO operators are not equipped to screen and surveil illicit cross-border flows in crypto.

    There are other substantive implications. In a standard ICO or IEO, the crypto received is used to activate the ‘smart contract’ for the automatic distribution of digital tokens to investors. Without the crypto element, this step is removed.

    In the Malaysian modified version, it is basically just an ‘asset tokenisation’ process. What this means is that digital assets are programmed and recorded on a blockchain ledger and issued as tokens.

    Also, there will be no need for digital asset custodians (DAC) as there are no crypto funds received and handled. The digital tokens, minted by the IEO operator on behalf of the issuer, don’t require custody as they are proprietary, remain in a closed loop, and all settled in fiat currency.

    The reality is, IEOs without crypto is a rather hollow proposition. IEOs may end up like another vanilla ECF platform – but with more investor risks!

    If Something Goes Wrong, Where Do I Seek Help?

    If digital tokens are not well-defined legally, it will be tough for both aggrieved investors to litigate and for regulators to prosecute. In our opinion, the current taxonomy does not provide sufficient clarity on the status of stablecoins, DeFi lending, and non-fungible tokens (NFT) – what more private tokenised securities that can be designed in so many ways?

    It will be good to have legal certainty and a path of recourse if things go awry. Having to go to court to enforce an ambiguous investment contract is the last thing any investor wants. In the absence of such, you can expect IEO operators to prop up the legal paperwork.

    Despite the use of ‘smart contracts’ for IEOs, it is very likely that investors will be required to physically sign subscription agreements, including the acknowledgment and acceptance of all instrument risks, and even limitation of liability!

    Conflicts of interest need to be properly disclosed if any, where the IEO operator approves the project, develops the token, promotes to the public, and gets paid in tokens. Whose interests is the operator beholden to – the issuer, investor, or its own? If the tokens purport to be asset-backed, the collateralisation agreements and prudential policies should rightfully be shown.

    For the smart investor, this is the Achilles heel of IEOs: Wouldn’t he or she be better off putting their money in normal shares or loans (via ECF or P2P), where there are more legal safeguards, investor protection, and formal dispute resolution?

    For the impatient investor, please be reminded that there is currently no linkage between the primary (IEO) and secondary markets (DAX) locally. The digital tokens are unlisted products for time being. Angels and early investors cannot take money off the table. Investors cannot transfer their tokens between one another.

    Note: Remarkably, the IEO guidelines do not state any prohibition of foreign DAX listings, which could be something to watch out for.

    Will IEOs Be Around a Few Years from Now?

    The race for global crypto capital has become heated. The major economies in ASEAN have rolled out crypto licensing regimes which are capital-friendly, competitive, and compliant. Regulators expect market operators to keep the pace of innovation, sustain the interest of investors, and remain relevant.

    The face of global crypto capital is also evolving rapidly. IEOs can already be offered on normal centralised exchanges like DAXs (in Singapore), through licensed intermediaries (like ICO portals in Thailand), or without going through DAXs at all e.g., through an Initial DEX Offering (or IDO) on open decentralised platforms. There are even DAICOs where decentralised autonomous organisations are created as the token issuer.

    Investors and issuers will be spoilt for choice as this space matures. IEOs will morph into the next in-thing. There will be more regulatory uniformity and cooperation across jurisdictions. New bespoke laws will be created instead of relying on extant securities laws. This article series surely won’t outlive its purpose.

    About the Author

    Edmund Yong is the managing partner of Celebrus Advisory and appointed by MDEC as part of its Talent Expert Network (formerly known as Digital Expert Panel) for blockchain technology. He is also the resident consultant for GLT Law, a multi-award-winning legal practice with specialisation in digital assets. All opinions expressed are the author’s own.

    [1] https://www.sc.com.my/resources/media/media-release/sc-registers-two-initial-exchange-offering-ieo-operators#

    [2] Securities Commission of Malaysia, Capital Market Masterplan 3: 2021-2025 (2021).

  • Picking the Best Time to Invest

    Picking the Best Time to Invest

    Since the start of the market rout in mid-March 2020, when benchmark gauges worldwide plunged due to pandemic fears over COVID-19, investors are probably wondering if it’s a good time to invest.   A sea of red across equity markets certainly has attracted the attention of bargain hunters looking to scoop up stocks that are trading at a discount to their premium.

    However, the vagaries of market timing can make it challenging for investors trying to pick this elusive bottom.

    Of course, the biggest question is whether these gains are sustainable or just a dead cat bounce. The reality is that there are too many market variables to know for sure, and what’s more, we are in uncharted territory. The world has never seen an economic shutdown on such a scale before due to a pandemic.

    It is likely that the economy is already in a recession as a result of this clampdown on business activity and consumption. The depth and length of this economic slowdown still unclear given the many variables at hand.

    But what is absolutely certain is that volatility is poised to persist. 

    So What Should Investors Do?

    Keeping perspective for one. It may seem like uncertain times, but this isn’t the first time that stock markets have gone through a recession before. History shows that every bull market cycle ends at a higher point than the previous one by subsequently recovering and notching higher gains.

    For instance since the MSCI World Index plummeted by -13.5% in March 2020, the index has retraced losses by climbing +10.8% in the month of April.  Similarly the MSCI Asia ex-Japan index recouped back gains of +8.9% buoyed by stimulus hopes as central banks eased monetary policy.

    Gains during expansionary periods have also far outpaced losses suffered during a downturn. As such, it is important that investors remain disciplined and stay on track towards achieving their investment goals. Adopting a long-term approach and staying diversified is important in this regard to weather the turbulence ahead.
    More defensive asset classes such as fixed income tend to hold up better compared to equities during periods of market stress.  But that does not mean investors should overlook equities completely.

    The stock market will eventually recover and it is important that investors stay invested to be in a position to capture that rebound. Similar to sell-offs, market gains often occur in short bursts at high velocity. Timing precisely for such moments require more than a stroke of luck and is highly unlikely.

    As can be seen in Graph 1 below, missing out on the best days in stock markets can significantly undermine an investor’s long-term financial success.

    Graph 1: The Cost of Market Timing The Risk of Missing the Best Days in Market, 2000 – 2019  
    Source: Morningstar, 2020

    According to research by Morningstar, investors who stayed in the market for all 5,035 trading days achieved a compound annual return of 6.1%. However, that same investment would have returned 2.4% had it missed only the 10 best days of stock returns.

    Further, missing the 50 best days would have produced a loss of 5.5%. Although the market has exhibited tremendous volatility on a daily basis, over the long term, stock investors who stayed the course were rewarded accordingly.

    This underscores the peril of market timing that could lead to significant opportunity loss. 

    The appeal of market-timing is obvious by avoiding periods of poor performance to improve portfolio returns. But the truth is timing the market consistently is extremely difficult that even the savviest investor can get wrong.

    As aptly put, history does not repeat itself, but it often rhymes. The COVID-19 pandemic may be unprecedented with little clarity yet on outlook, but some of the strongest rebound often occur when the market is at its most bearish.

    The ideal approach to invest in such a period then is by staying disciplined and investing consistently by sticking to a regular investment plan to ease one’s way into the market.

    Over the long-term, this would reduce the impact of volatility by spreading out your investments over periodic time intervals by dollar cost averaging. This ensures that one do not buy at inflated prices as well as seize the opportunity to acquire more units at lower prices.

    Best Time For You, Not The Market

    stock chart candlestick

    Instead of looking outward and trying to time the market, investors should turn inward to decide when the best time for them to invest is. 

    An easy way for investors to do so is by asking themselves basic financial questions such as:-

    • Do I have enough in my emergency savings to cover necessities?
    • What about future commitments and liquidity needs?  
    • Can I take a long-term view on my investments?

    The global economy is undoubtedly in a fragile state as businesses grapple with closures due to nationwide lockdowns to stem the spread of the coronavirus. With companies embarking on cost-cutting measures, the likelihood of pay-cuts, redundancies and job losses may be inevitable.

    That is why the importance of having enough in emergency savings cannot be emphasised enough. A rule-of-thumb is that one should have at least 3-6 months’ worth of living expenses in a rainy day fund for precisely in times like these.

    Similarly, investors should also look at their time horizon and liquidity needs. Do you require cash to pay any outstanding debt or expenses in the near future? Also, can you afford to hold your investments without withdrawing for at least 3 years?

    These are important points because no investment can churn out returns overnight.  Patience is needed for investment success and history has proven to be kind to investors who do sit through market cycles and stay invested.

    Waiting for the perfect time to invest should not be an external exercise and what happens in the market.   Rather, it should be an introspective one by taking into consideration your own financial standing, investment horizon and risk appetite.

    About The Author

    Lee Sheung Un is the Communications Officer of Affin Hwang Asset Management. A former business journalist, he is an ardent investor who is passionate about markets and is working towards building his dream portfolio.

  • Gold Investment From An Islamic Point Of View

    Gold Investment From An Islamic Point Of View

    Gold is one of the most popular precious metal investment and can provide a source of income for investors.

    Gold has historically been used as a hedge against currency depreciation and inflation. When there is a rise in inflation, gold usually gains in value.

    As a result, in this post, I will discuss gold investing from an Islamic perspective.

    Gold Is One Of The Ribawi Item

    Initially, it was ruled that buying something with cash or in instalments was permitted in Islam. However, if a transaction involves ribawi items (items included under the ruling of riba), then each party involved will have to give attention so that he or she would not be involved in riba.

    أَخْبَرَنَا مُحَمَّدُ بْنُ عَبْدِ اللَّهِ بْنِ بَزِيعٍ، قَالَ حَدَّثَنَا يَزِيدُ، قَالَ حَدَّثَنَا سَلَمَةُ، – وَهُوَ ابْنُ عَلْقَمَةَ – عَنْ مُحَمَّدِ بْنِ سِيرِينَ، عَنْ مُسْلِمِ بْنِ يَسَارٍ، وَعَبْدِ اللَّهِ بْنِ عَتِيكٍ، قَالاَ جَمَعَ الْمَنْزِلُ بَيْنَ عُبَادَةَ بْنِ الصَّامِتِ وَمُعَاوِيَةَ حَدَّثَهُمْ عُبَادَةُ، قَالَ نَهَانَا رَسُولُ اللَّهِ صلى الله عليه وسلم عَنْ بَيْعِ الذَّهَبِ بِالذَّهَبِ وَالْوَرِقِ بِالْوَرِقِ وَالْبُرِّ بِالْبُرِّ وَالشَّعِيرِ بِالشَّعِيرِ وَالتَّمْرِ بِالتَّمْرِ – قَالَ أَحَدُهُمَا وَالْمِلْحِ بِالْمِلْحِ وَلَمْ يَقُلْهُ الآخَرُ – إِلاَّ مِثْلاً بِمِثْلٍ يَدًا بِيَدٍ وَأَمَرَنَا أَنْ نَبِيعَ الذَّهَبَ بِالْوَرِقِ وَالْوَرِقَ بِالذَّهَبِ وَالْبُرَّ بِالشِّعِيرِ وَالشَّعِيرَ بِالْبُرِّ يَدًا بِيَدٍ كَيْفَ شِئْنَا قَالَ أَحَدُهُمَا فَمَنْ زَادَ أَوِ ازْدَادَ فَقَدْ أَرْبَى ‏.‏

    It was narrated that Muslim bin Yasar and ‘Abdullah bin ‘Atik said:

    “Ubadah bin As-Samit and Muawiyah met at a stopping place on the road. ‘Ubadah told them: ‘The Messenger of Allah forbade selling gold for gold, silver for silver, wheat for wheat, barley for barley, dates for dates”‘- one of them said: ‘salt for salt,”‘ but the other did not say it-“unless it was like for like, hand to hand. And he commanded us to sell gold for silver and silver for gold, and wheat for barley and barley for wheat, and to hand, however we wanted.”‘ And one of them said: “Whoever gives more or ask for more has engaged in Riba.”

    According to the preceding hadith, sales and purchases of ribawi products like as gold jewellery must be made immediately and without delay.

    If there is a condition of delaying payment or delivery of the item, it falls into the category of riba al-nasiah, which is riba that occurs as a result of the item’s delayed payment or delivery. In fact, it is of greater prohibition when the delay is included with some additional charges.

    As an alternative, the buyer may take a financing from a third party before buying the gold in cash. However, using a leverage technique in gold investment is riskier because it will magnify the profit (when gold price appreciates) and loss (when gold price depreciates).

    6 Ways To Invest In Gold

    There are 6 common ways to invest in gold for an everyday investor:

    1. Physical Gold via Bullion or Coin Websites

    Bullion refers to high-purity physical gold and silver held in the form of bars, ingots, or coins. Purchasing gold bullion bars is the most conventional method of gold investment.

    However, don’t limit yourself to buying actual gold, such as coins or bullion, when considering gold investments.

    2. Physical Gold via Jewellery

    Gold jewellery is one of the most popular ways for women to invest. This strategy is a popular option for women to invest in gold because it makes them happy by allowing them to use the gold while also making them look attractive when worn around their neck and on their wrist.

    However, there are a number of drawbacks to gold investment in the form of jewellery:

    • You’ll probably pay more than the gold price for the piece’s craftsmanship.
    • You’ll most likely be purchasing a piece of 24 carat gold that isn’t totally pure. Because 24 carat gold is delicate and easily scratched, it is rarely used in jewellery. As a result, make sure that you’re not buying 24 carat gold.
    • It is a nightmare to keep the gold safe. Burglars know that Malaysians like to keep gold in their homes, thus they target a lot of Malaysian houses.
    • Because each piece of jewellery is unique, you won’t get a uniform price when you sell it; instead, you’ll have to shop about and bargain, and you won’t likely get as good a price as a pure gold coin or similar item. This is because the buyer will be responsible for the cost of melting down the gold to rebuild it. As a result, they’ll pass that cost on to you.

    3. Exchange-Traded Funds (ETFs) That Buys Gold

    Besides physical gold, ETFs can be purchased like shares on a stock exchange. ETFs allow investors to gain access to gold without the expenses and hassles of markups, storage charges, and security risks associated with real gold.

    The expense ratio of a fund causes an investor to lose a percentage of his or her investment each year. An expense ratio is a recurrent annual fee that funds levy to pay their management and administrative expenditures.

    In Malaysia, TradePlus Shariah Gold Tracker by Affin Hwang Asset Management provide investors a Shariah-compliant Avenue to invest in physical gold without the hassle of storing or insuring gold bullion. The Fund closely tracks the returns of gold through an Exchange-traded Fund structure; where units are tradeable on Bursa Malaysia Securities.

    4. Buy Gold Through Futures Or Options

    Bullion futures or forwards contracts are also available to investors. A futures or forwards contract is an agreement to buy or sell an asset or commodity at a current price and have the contract settle at a future date.

    The seller of gold and silver futures contracts agrees to deliver the metal to the buyer on the contract’s expiration date. The buyer will only be an owner of a paper gold contract until the gold is delivered. If the buyer does not wish to own gold bars or coins, the contract can be sold before it expires or rolled over into a new contract.

    This form of investment is not permitted in Islam since, as stated in the hadith above, all item ribawi transactions must be made on the same measurement and on the spot. It indicates that the buyer must take possession of the gold immediately rather than waiting for it to be delivered later.

    5. Contract For Differences (CFD) On Gold

    Gold trading has progressed to the point that traders no longer require physical possession of the commodity. A contract for differences (CFD) is a financial contract that pays the difference between the open and closing trade settlement prices.

    The objective behind gold trading with CFDs is to speculate on the price of gold. The profit or loss is calculated by the change in Gold’s price throughout the course of the contract. You can buy in rising and falling markets while trading Gold as a CFD, just like other assets. You can trade when the price of gold is rising or decreasing, in other words.

    In a falling market you can actually SELL Gold and then later BUY it at a greater value. Likewise, you can BUY low and SELL when gold rises in value

    Contract for differences (CFD) investing is categorically prohibited. This is due to the fact that there is no genuine gold transaction going on, and the economic effect is equivalent to gambling.

    6. Exchange-Traded Funds (ETFs That Trade In Gold Futures Or Forwards)

    When the underlying contract is gold futures or forwards, it is also Haram to invest in gold futures or forwards through exchange-traded funds (ETFs).

    About the Author

    Hanif Yahaya is a Licensed Financial Planner. He is the best student of Shariah Registered Financial Planner (Shariah RFP) in 2018 and completed Registered Financial Planner (RFP) in 2020. He is Certified HRDF Trainer and currently he is Youth Committee Member of Malaysian Financial Planning Council (MFPC) and Member of Malaysian Association of Muslim Finance Professionals.

  • 5 Things That You Should Know About This Local NFT Artist Who Is Making Waves Worldwide

    5 Things That You Should Know About This Local NFT Artist Who Is Making Waves Worldwide

    Non-Fungible Token (NFT) is the buzzword these days, and you can see many brands embracing it. We have McDonald’s, Coca-Cola, Nike, Ray-Ban, Louis Vuitton and BMW among the well-known brands that have started their own NFT initiative.

    Over here in Malaysia, we have KFC, AEON and MyeongDong Topokki offering NFT with benefits to its holders; whereas MY EG Services Bhd (MYEG) have launched their own NFT marketplace called Pangolin.

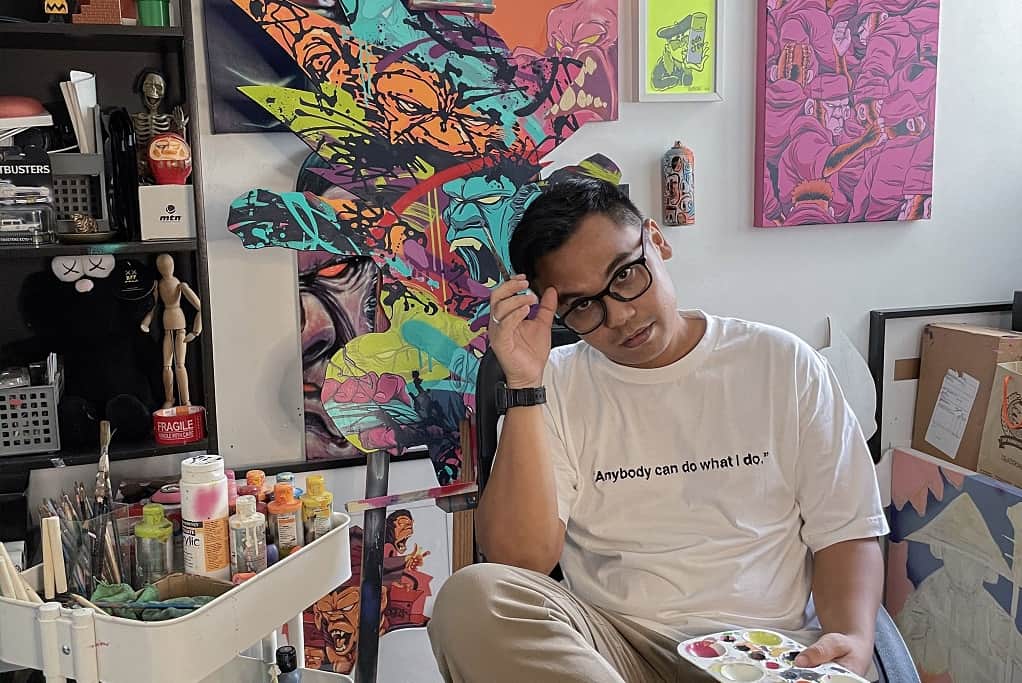
    Having said that, there’s a local NFT artist that have been making waves worldwide and raking in millions of dollars from his NFT collection. Let’s meet Katun and get to know him a little bit better.

    Here are 5 things that you should know about this local NFT artist.

    1. How It All Started

    Katun is a Graffiti Artist and Illustrator based in Kuala Lumpur, Malaysia. He first embarked on his NFT journey with his manager/partner David Ku. Although the NFT sector locally is still in its infancy, they both shared a common vision and their ideas clicked.

    With Katun’s experience in the art community, David believed that they could take it to the next level by stepping into the NFT space. Several months of back and forth conversations with industry leader Elliot Wainman, co-founder of U.S based Superfarm platform, resulted in their partnership that set the groundwork for 4 Stages, which then sets the Apes R Us project into motion.

    2. Have Been Creative Since Young

    Katun have always been a creative person and he has been drawing since a very young age. When Katun was in kindergarten, he used to imitate all of his favorite 80’s cartoon character styles, and even told his teacher that he wanted to be a cartoonist when he grow up.

    What do you know, dreams do come true!

    3. His NFT Have Been Sold For Millions

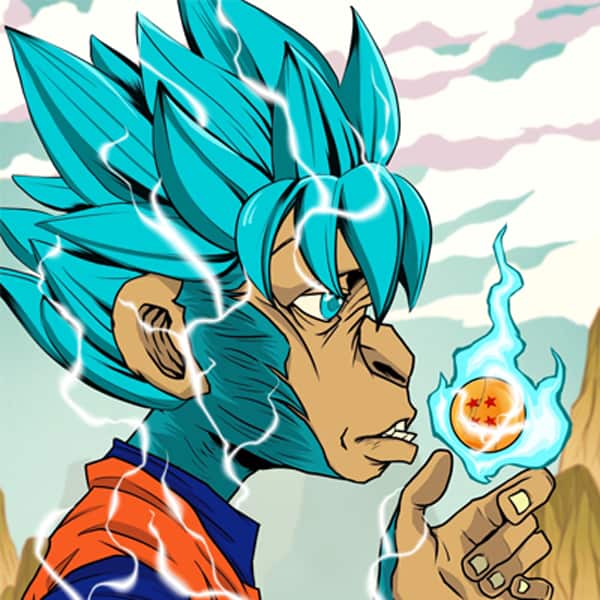
    His recent collection entitled Apes R Us, consisting of 8,444 NFTs was sold out within 28 hours. The collection, which valued at USD7 million, surpassed his previous NFT releases – ‘Apes Stands Strong’ and ‘Mystical Fruits’ – which reached an approximate total sale of USD401 thousand.

    He have also worked with renowned international artists such as Chris Brown, Dua Lipa, & Post Malone, and brands such as DC Shoes, JBL, Vans, Sony and New Era.

    4. His Advice To Fellow Malaysians

    For fellow Malaysians who wants to get involved with NFT, it is important to know the value of your art and your audience. Take your time to create good artwork and most importantly, don’t rush. Don’t stress yourself out on how much you can earn, just enjoy creating instead of thinking about it.

    Focus, concentrate, and trust the process.

    5. His Plans For The Future

    There is plenty in the works regarding the Apes R Us project. He aims to expand and explore other mechanisms and mediums.

    A few brand collaborations are in store as well, and anyone that wants to know more about his projects, feel free to join their Discord community and follow their Instagram profile for the latest updates.

    Of course we didn’t stop there, we also asked Katun on NFT as an investment tool. Let’s check out his answers.

    With The Recent Crash Of Crypto, Will The NFT Market Crash Too?

    Personally, he don’t foresee the NFT market crashing. As a creator, he have always been self-motivated, and don’t quit easily.

    “Ups and downs are part of the game, you either keep going or you’ll get chewed out. For as long as there are creators in this world, it will always be survival of the fittest”, said Katun.

    And we can see that NFT is still in a very early stage. We haven’t even get started talking about Metaverse, which is said to be booming in the next few years – which prompted Facebook to change its name to Meta.

    Is NFT A Good Investment To Venture Into?

    “If you have a solid plan of action, a valid strategy, I believe money can be made, but my core focus is on building and growing the project, along with the community, and putting emphasis on executing development work”, said Katun.

    For investors, yes NFT would be a good investment. But maintaining a diversified portfolio to mitigate the risks involved is equally important.

  • 8 Categories of Real Estate Investment Trusts (REITs) in Malaysia

    8 Categories of Real Estate Investment Trusts (REITs) in Malaysia

    Real estate or property is one of the ‘cliche profitable’ investment portfolios. Many people said that you can never go wrong with property or real estate investment. They never ‘betray’ you. It performs very well for the last few years.

    Before REITs were introduced, an investor need to buy physical property to get exposure in real estate/property investment. But now, with REITs being introduced, an investor can just buy a fraction of the property prices.

    Want to get investing started? You can try the easiest one : 5 Easiest Investments You Can Start With In Malaysia

    Simply put, REITs offer you a high-value commercial property at just a low price and without the need for you to buy the properties physically. It’s very interesting and tempting! Isn’t it?

    We can also say that it’s an investment that gather funds and access better investment opportunities which in this case, property.

    So, what are the categories of REITs in Malaysia? This categories came from PropertyGuru.

    8 Categories of REITs

    1. Hotels

    hotel REITs

    This includes any property with hotel business and also accommodation

    2. Office

    This includes office buildings or office spaces.

    3. Retails

    Malls REITs

    This includes malls, shops or commercial shops.

    4. Industrial

    This includes factories, industrial buildings, and industrial lands.

    5. Healthcare

    Hospitals property reits

    This includes clinics, hospitals, pharmacies or any healthcare buildings.

    6. Warehouse

    This includes storage and logistic facilities.

    7. Carparks

    car park reits

    This includes car parks or parking infrastructure.

    8. Residential

    This includes residential properties, multi-unit properties or rental properties.

    You can buy this REITs via your CDS account in Bursa Malaysia. These are 18 REITs that you can purchase from Bursa Malaysia as of 1st June 2022.

    Source : Bursa Malaysia

    Remember! There are syariah and non-syariah compliant REITs (this will be discussed in our next article).

    The best REITs in Malaysia? Best Reit In Malaysia. Which One Is Better? Is It Time To Invest Now?

    As you can see from the image above, you can invest in property (REITs) with less than RM100. It’s kind of great opportunities for those out there that want to save their money, take lower risk without having to buy hundreds of thousands or million of physical property.

    What do you think?

  • Avoiding Behavioural Biases Of Investing

    Avoiding Behavioural Biases Of Investing

    C: Behavioural biases can lead investors to make decisions that can jeopardize their investments

    The traditional economic theory assumes that all individual investors would behave and act rationally by considering all information available to them. This would be reflected in the prices of assets and ultimately, what makes markets efficient.

    But we know textbook theories don’t apply in real life and investors do not behave rationally all the time. This is particularly true when markets reach euphoric highs or plunge to scary lows.

    Following these mental cues or tendencies can be harmful, especially when logic gets thrown out the window. Decisions that may appear rational are in fact detrimental. Here are four common behavioral biases that can lead investors astray and how one can overcome them.

    1. Recency Bias

    Symptom: If you find yourself reacting immediately to every breaking headline and being trigger happy with your investments, you may be succumbing to recency bias which is the tendency to overemphasize new information.

    In the current 24-hours news cycle with the prevalence of social media, the investment realm has become a global echo chamber constantly reverberating with news alerts.

    The coronavirus outbreak and ensuing market correction is a more recent example. But if there is something more contagious than any viral outbreak is the spread of fear. Add a web of disinformation and fake news; you have a toxic concoction oozing with fear and market angst.

    If you look at past outbreaks like that of Severe Acute Respiratory Syndrome (SARS) in 2003, the incident didn’t create any long-term impact on asset classes and equity markets promptly recovered after the outbreak was contained.

    Having a recency bias will also almost certainly lead you to buy when markets are peaking and selling at the bottom.

    Remedy: There is nothing wrong with staying informed with new information, but the problem lies in how we react. According to Lim Chia Wei, a portfolio manager of Affin Hwang Asset Management, it is essential to first recognize the media’s thrives by sensationalizing new news.

    “I think it is helpful to clearly write down every investment’s long-term thesis. As new information presents itself, we should ask ourselves how the new information will affect our long-term thesis. It is crucial to think in terms of probability. Anything is possible to break or support one’s thesis. But not everything is probable,” he says.

    The prevalence of market noise as well as the legitimisation of social media as a reliable news source has injected more volatility in markets. Think US President Donald Trump and his Twitter diplomacy during the US-China trade talks last year. If you reacted to every one of his tweet, you may find yourself burnt in the end by Trump’s randomness.

    2. Herding Bias       

    Herding Bias

    Symptom: There is safety in numbers, correct?  Well not really if you look through history. From Tulipmania in the 17th century, the dotcom bubble in the early 2000s, and the 2008 subprime mortgage crisis, history has shown that investors are willing to suspend disbelief when the going gets good. But, we all know how the story ends when there is irrational exuberance bubbling amongst asset classes.

    Investors are social creatures, and we are comforted that someone else is buying into a particular investment too. But the wisdom of the crowd can be wrong and the repercussions severe. More recent examples like the bitcoin mania underscore the dangers of herding behavior. 

    The truth is much of today’s market volatility is also fuelled by machines or algo-traders that profit from short-term fluctuation in prices and ignore any fundamental analysis. Behind each market plunge is a digital herd of trading bots programmed to buy and sell based on pre-determined formulas and models.

    This ignited a ‘flash crash’ like that seen in 2010 when the Dow Jones Index lost close to 1,000 points in mere minutes. The S&P 500, Dow Jones Industrial Average and Nasdaq collectively lost US$1 trillion. But in 36 minutes, the rout was over and markets rapidly recouped its losses.

    Remedy: Stop focusing on what the crowd is doing. Instead, work on developing a plan that is right for you. Understanding the self is the first step in modeling a portfolio that is meant to serve your life goals and financial aspirations.

    Next, concentrate efforts on building a diversified portfolio that fits your own financial goals and risk-appetite. Intraday fluctuations in markets are unlikely to bother you if you are well diversified across asset classes. 

    A diversified multi-asset portfolio with low correlations helps smoothen the investment journey when faced with adverse market conditions. In turn, this would induce investors to stay invested and reap the benefits when markets bounce back.

    3. Loss aversion bias 

    Loss aversion investment bias

    Symptom: We all hate to lose money. But if you find that fear of loss crippling and clouding your decision-making, you may be suffering from loss aversion bias. Investors often feel more acutely the pain of loss than the pleasure they reap from gains.

    Why are we so afraid of loss? It’s an emotive response that is typically hard-wired into someone’s psyche. In markets, this is manifested through behaviors of extreme risk-avoidance, such as investing in only low-risk, low-return investments and selling immediately at the first sign of a headwind.

    This behaviour is counterproductive to investors’ financial goals by not fully utilising their capacity for risk and financial resources.

    Remedy: Investors’ memories are by nature short-term and most of the time we only remember the bad parts. If you are feeling jittery about markets, consider rebalancing your portfolio to its target asset allocation or locking-in gains to raise some cash.

    Importantly, work on developing a financial plan that suits your goals and risk-appetite. If you cannot stomach the volatility, chances are that you may be taking too much risk and there is a portfolio mismatch.

    Chia Wei believes it is important to have the right perspective of performance to overcome one’s loss aversion bias. “History has shown that taking a long-term investment approach and sitting through short-term declines has been very rewarding. Investors should push themselves to focus on the long-term prospects and de-emphasise short-term events.”

    4. Confirmation bias 

    Symptom: One of the more common behavioral biases amongst investors stems mainly from overconfidence, particularly in bullish market conditions. When investors are misled to think they are invisible in the marketplace when they are raking it in, this can lead to tunnel vision when they only seek out information that supports or confirm their view.

    For example, say you just added a new stock into your portfolio. When you continue your research on the stock, you only click on positive headlines which support your decision but avoid negative ones. Restricting yourself to such information only confirms your own assumptions that may lead you to miss important red flags or warning signs.

    Remedy:  Be open to new sources of information that may not sit well with you. Ask yourself if the issues raised have their merits and if they would impact the fundamentals of a particular investment you just made. It’s not easy to challenge your own assumptions. Still, it is important to do so, especially when there is a lot of hype built-in and technical indicators are pointing to overbought territory.

    Investing With Clarity

    The first step in overcoming behavioural biases is to understand why we have such tendencies in the first place. But proper planning with clear financial goals can help anchor investors and guide them in their financial journey no matter how markets behave.

    Stick to a disciplined approach by investing consistently and be conscious about the decisions you make to navigate markets confidently. 

    About the Author

    Lee Sheung Un is a communications officer at Affin Hwang Asset Management. A millennial, he is still finding that balance between wealth, freedom and purpose. Views expressed are his own.