Category: Investments

  • What Is Halal Investing And Why Is It Important?

    What Is Halal Investing And Why Is It Important?

    Halal investing, in simple terms, means investing in permissible businesses according to the Islamic ethico-legal system or Shariah. There are two main screening levels for halal or Shariah-compliant investments.

    Firstly, a business screening is undertaken to review a company’s business practices, products sold, and revenue sources. A company is prohibited from generating returns from the selling or producing of alcohol, pork, products, weaponry, gambling, adult entertainment, or riba (interest). Other considerations include the prohibition of hazard or uncertainty (gharar) such as speculation and the prohibition of investment in forbidden assets (haram).

    Secondly, a financial screening is done to ensure that companies have better control on their business and excessive risk taking is avoided. The screening lays out three broad pre-defined ratios, as formulated by AAOIFI (Accounting and Auditing Organization for Islamic Financial Institutions) standards:

    1. Conventional debt / Total market capitalization < 30%
    2. (Cash + Interest-bearing deposits) / Total market capitalization < 30%
    3. (Total interest + income from Shariah non-compliant activities) / Revenue < 5%

    Investments are considered halal if a company passes both the business and financial screenings set out by AAOIFI or by the local Shariah body of scholars. In Malaysia, the Shariah Advisory Council of the Securities Commission Malaysia is the central authority responsible for determining the application of Shariah principles in the local Islamic capital markets.

    Why Halal Investing Matter?

    Asian Muslim families celebrate Eid together while enjoying a meal

    For Muslim investors, the option to invest in a halal manner enables them to generate wealth in line with their faith. The interpretation of Shariah law as applied to business activities is nuanced. Since different standards exists, Muslim investors rely on guidance from Islamic scholars to help in the determination if an investment is halal. This allows the Islamic finance industry to thrive as halal solutions are becoming increasingly available in the capital markets.

    For non-Muslim investors, investing according to Islamic principles still offer many benefits. Halal investing brings a sense of responsibility on how investments generate returns by preserving a concern for ethics and values. It encourages a disciplined investment process that promotes in-depth research and monitoring to better understand the business.

    The financial screening standards also facilitate a conservative approach that appeals to risk-averse investors without compromising on returns.

    How To Invest In A Halal Manner?

    In this age of digitalization, halal investing has been democratized by the emergence of many options such as digital brokers, online providers of unit trust funds and robo-advisory platforms. This means investors with little financial knowledge may still be able to participate in the Islamic capital markets and learn the ropes on investing from a younger age as the barrier to entry becomes lower each day.

    The financial inclusion of the younger and underserved demographics is vital in ensuring that the overall economy continues to grow and remains sustainable.

    What Is A Robo-Advisor And Why Should You Care?

    Artificial intelligence AI research of robot and cyborg development for future of people living. Digital data mining and machine learning technology design for computer brain communication.

    Robo-advisors are automated financial advisors. They are an online tool that assists investors in picking an optimal investment portfolio according to their risk tolerance profile. Typically, robo-advisors start by asking investors questions to understand their risk appetite and allocate investments based on certain algorithms.

    Once investors agree to the investment allocation, they can start funding their account and the robo-advisors will purchase the underlying securities and manage their portfolio by rebalancing it periodically. Robo-advisors have emerged as favorites to younger demographics due to their low account minimums, low fees, digital-only service and overall, a more efficient and timesaving offering.

    About Wahed Invest

    Wahed Invest (“Wahed”) is one of Malaysia’s robo-advisors (or digital investment management company) that focuses on halal investing. Wahed was licensed by the Securities Commission Malaysia in August 2019 and launched in October 2019. Since then, Wahed has been offering Malaysians diversified Shariah-compliant investment portfolios that provide exposure to foreign and local equities (via exchange-traded funds or ETF), local Islamic fixed income (via sukuk funds) and gold (via ETF). Further information regarding Wahed’s services can be found at wahedinvest.com, and the Wahed Invest robo-advisory application can be downloaded from the iOS App Store or Google Play Store.
  • Top 20 Malaysia Small Cap Companies: These Are The Jewels For 2022

    Top 20 Malaysia Small Cap Companies: These Are The Jewels For 2022

    RHB Research recently published the 18th edition of Top Malaysia 20 Jewels 2022. RHB Research continues to persevere and maintain unwavering commitment towards producing yet another signature compendium of 20 top small-cap investment ideas despite the extremely challenging macroeconomic environment.

    The selection has been complicated by capital market volatility – buffeted by rising interest rates, high inflation, the Russia-Ukraine conflict, and draconian lockdowns in China – we see a strong rebound in economic activities, with manufacturing and retail spending recovering swiftly. Valuation for small-cap stocks have also retraced, leading to a sizeable valuation gap to the big caps, making the investment thesis more compelling.

    Top Malaysia 20 Jewels 2022

    Here’s the list of Top 20 Malaysia Small Cap Companies for the year 2022 by RHB Research.

    1. Aemulus Holdings

    2. Bonia Corporation

    3. CJ Century Logistics Holdings

    4. Coastal Contracts

    5. Dayang Enterprise Holdings

    6. Dufu Technology Corp

    7. Homeritz Corporation

    8. Kawan Food

    9. Kumpulan Fima

    10. KKB Engineering

    11. Nova Wellness Group

    12. Optimax Holdings

    13. Samchem Holdings

    14. Sedania Innovator

    15. Supercomnet Technologies

    16. Texchem Resources

    17. Tune Protect Group

    18. Unimech Group

    19. VSTECS

    20. YBS International

    The 20 companies featured are not within RHB Research’s existing coverage. Companies from 10 different sectors with an average market cap of MYR509m have been curated into this 2022 edition. Consumer and industrial products & services sectors feature prominently, making up 45% of the picks. All but five – which are Ace Market listed – of the 20 names reside on the Main Market.

    Source: RHB Research Team

    *All investors are advised to conduct their own independent research into individual stocks before making any decision to buy or sell. Investors are also advised that past stock performance is no guarantee of its future price.

  • Follow These 5 Steps For An Effective Asset Allocation In Your Investment

    Follow These 5 Steps For An Effective Asset Allocation In Your Investment

    It has been a volatile few years for the global markets. Pummeled by the COVID-19 pandemic, risk assets endured a fierce selloff in the 1Q2020 as economic activities came to a grinding halt with a complete shuttering of businesses. Global equities succumbed to one of the steepest and quickest correction ever witnessed in March 2020. 

    However as sharp and quick as the rout began, the recovery has also been swift and ebullient. Due to unprecedented stimulus measures injected by governments and central banks, benchmark gauges have rebounded strongly driven by ample liquidity. The US stock market has even surpassed its pre-COVID-19 peak despite infections continuing to rise in the country. 

    To any casual market observer, the new normal investment realm can be confusing terrain to navigate as the gap between the real economy and the stock market continues to widen. This is especially as traditional macroeconomic theories no longer apply in a world of negative interest rates and unlimited quantitative easing (QE). 

    Whilst the markets will ebb and flow, it is far more important for investors to stay the course and practice diversification in their portfolios. Here is a 5-step guide that investors can follow to an effective asset allocation.

    Step 1: Defining Your Investment Objectives

    It’s the first step in the asset allocation process that often gets overlooked. But really, it is the most important part that you should invest the most time with before modelling a portfolio.

    Asking yourself basic questions like “who am I?” and “what are my aspirations and expectations?” can help you define your objectives. Are you a millennial looking to build and accumulate wealth, or are you someone in your mid-50s looking to prepare for retirement and have a steady income stream?

    Once you’ve established these answers, it’s crucial then to be as specific as possible and to be able to quantify your financial objectives. How much wealth do you want to build exactly? How much does your current lifestyle cost and how much do you need to sustain it?

    For example, someone in their mid-50s will need to determine how much wealth they would like to accumulate by the time they reach retirement, as well as the rate of return % they need to achieve as a hedge against inflation.

    All these considerations are important because it lays down the parameters of your investment objectives so that your portfolio is geared towards achieving its stated purpose. 

    Step 2: Gauging Your Risk-Tolerance

    Determining your risk-tolerance is the next step. Understanding your risk-tolerance can also be gauged by asking yourself basic questions like your age, monthly income and expenditure and other types of commitments you have. Different psychological profiles and imprints often determine what type of person you are and if you are a risk-taker or risk-averse.

    But it is critical here to separate what your risk-tolerance and risk-acceptance are, as the two gauges measure different things. For example, an investor in their mid-20s may be more inclined to take on more risk because of his youthful exuberance and more daring nature. Therefore, he has a high risk-acceptance.

    But if you consider the fact that if he is already married with a child along the way, as well as parents and in-laws to take care of, his capacity to take on risk is actually limited. As such, the investor actually has a low risk-tolerance and would not be able to stomach an aggressive portfolio that is highly tilted towards riskier asset classes.

    Step 3: Time Horizon and Liquidity Needs

    Businessman holding an hour glass, signifies the importance of being on time

    Next, an investor would need to determine their investment time horizon and liquidity constraints. Think of these two factors as the levers shifting the gears of your portfolio that will ultimately determine your capacity to invest and by how much.

    For instance, an investor in their mid-20s who does not need the principal sum and returns back from the investment for the next 8 – 10 years would have a long investment horizon and hence a higher capacity to invest.

    This would allow the investor to take on more risk and be more exposed towards longer-dated instruments or riskier asset classes that only show returns at a later stage. Such asset classes typically include small-caps or growth stocks that are high-risk and typically exhibit strong earnings and growth only at a later cycle. Thus, investors with a shorter investment horizon should avoid such asset classes.

    Similarly, as an investor you should also assess your liquidity needs and determine how much you are willing to set aside from your wealth as investments. It’s crucial that you understand that this is a separate pool of wealth that is different from your own savings account that you use for your own daily sustenance and allowance.

    Thus, as much as possible, you should avoid dipping into either pools of wealth and using your savings for investments and vice-versa.

    You need to give time for your portfolio to work and to compound returns. Opting to cash-out from your portfolio can be disruptive to your investments especially at a crucial stage of the market cycle when it is starting to rebound. Thus, investors should remain disciplined and focused.

    Step 4: Understanding Different Asset Classes

    These are the ‘building blocks’ of your portfolio. There are 3 broad asset classes for an investor to work with, i.e. equities, fixed income and cash.

    Equities are the riskiest asset class but has the potential to provide the highest returns. Common instruments include ordinary shares or equity funds that an investor can easily buy into.

    Fixed income, also known as debt, is a less risky asset class that provides more stable but often lower returns. Investors may not be able to gain exposure to this asset class by investing in bonds directly or through bond funds.

    Cash or cash-equivalents are the most liquid asset class and typically provide little to no returns especially in inflationary periods. But they serve its importance by being extremely liquid to quickly move in and out of a market correction as well as a buffer during an emergency.

    There are also other types of asset classes including REITs, commodities, precious metals, real estate or even alternative asset classes such as private equity or debt. But more importantly, you need to really understand what it is that you are investing into and the underlying asset class of the product before deciding to include it in your portfolio.

    Step 5: Constructing Your Portfolio

    Finally, you are ready to construct your portfolio. There is no single method or approach in building the ‘perfect’ portfolio, as each portfolio would need to be customised according to the needs and risk-profile of the investor. But there are some model blueprints that an investor can follow as a start.

    For more risk-inclined investors, they can invest in a more aggressive portfolio composed of 70% – 80% in equities and the rest in fixed-income. On the flip-side a more risk-averse investor should have a higher tilt towards fixed-income of between 70% – 80% in bonds, with minimal holdings in equity and some in cash. A risk-moderate investor could have equal exposure to both asset classes.

    Underpinning all these considerations in the asset allocation process is the simple principle of diversification of not putting all your eggs in a single basket. Diversification strives to minimise risk in a portfolio by investing in a mix of different types of asset class that are not or less correlated, so that gains from one asset class can offset losses from another.

    It is a risk mitigation technique that has been proven to outperform over the long-run by protecting against losses, whilst maintaining sufficient exposure to capture market growth.

    Knowing is Half the Battle

    Starting your investment journey can be especially daunting during such volatile market conditions. But as the saying goes, “Never let a good crisis go to waste.”  Anyone can invest as long as you have a plan and a robust asset allocation to ride through the market peaks and troughs. 

    About the Author

    Lee Sheung Un is a communications officer at Affin Hwang Asset Management. A millennial, he is still finding that balance between wealth, freedom and purpose. Views expressed are his own.

  • Making Sense of Alternative Assets in Your Investment Portfolio

    Making Sense of Alternative Assets in Your Investment Portfolio

    “Given the nature of these alternative investments at this juncture – where price discovery remains a challenge, volatility is high, and long-term values remain uncertain – it would be more appropriate to classify them as part of your high-risk investment bucket.”

    It is almost impossible to miss the headlines these days about the next new investment idea. Chances are those new ideas are likely related to digital assets (e.g. cryptocurrencies) or online funding intermediation (e.g. peer-to-peer lending or equity crowd funding) and the like.

    These options seem to be the most attention-grabbing ones, attracting both seasoned and novice investors alike. This begs the all-important question – are these investments suitable for you?

    To help us get a grip on this question, let us briefly take a look at what each of these alternative investments are, how it works and how can you benefit from it.

    1. Digital Currencies (a.k.a. Crypto Currencies)

    Digital currencies as the name suggests are an alternative means of a financial exchange in a non-physical format. This is unlike fiat currencies that are government issued and regulated such as the US dollar, British pounds or our own local currency – the Malaysian ringgit. Among digital currencies, bitcoin remains the most well-known and sought after.

    The rise (and fall) in value of digital currencies has been nothing short of phenomenal. However, apart from scarcity, it would seem that speculation (partly fueled by celebrity tweets) and regulatory risks seem to be main drivers of price movements for now. This could change as digital currencies start to gain a foothold as a medium of exchange, potentially replacing fiat money in the future.

    For now, an investor will monetise any returns by selling the investment, hopefully at a profit.  

    2. Peer-to-Peer (P2P) Lending

    As the term suggests, this involved the lending of funds between individuals, supported by a platform as an intermediary to facilitate the process. It is effectively a way of cutting off the middleman’s role which has long been played by financial institutions.

    In P2P lending, also known as “social lending”, investors are offered a socially attractive value proposition by borrowers who might otherwise find it challenging to fund their enterprise via traditional channels. Investors receive returns in the form of interest payments at the end of the loan period.

    Given that these often represent higher risk lending, the interest payment will likely be higher than bank fixed deposit rates.   

    3. Equity Crowdfunding (ECF)

    ECF works similarly to P2P lending in that it provides an alternative source of funding for budding companies. However, the main difference is that ECF investors will receive a stake in the business instead of an interest payment. This might be an attractive proposition for those looking to discover the next unicorn investment.

    However, investors should also be aware of their exit strategy before committing their hard-earned money.

    What’s Your Risk Profile?

    Now that we have some high-level idea about these alternative investments – are they right for you? Instead of limiting your analysis to the investment idea itself, I would suggest that the question is better answered by firstly determining your investment risk profile, followed by your ideal strategic asset allocation. Only then should one take the plunge to invest.

    Investopedia defines risk profile as “an evaluation of an individual’s willingness and ability to take risks”. Are you a risk taker by nature, fully aware of how investment values fluctuate depending on market condition and are ready to ride out any storm that come your way?

    Or are you the more conservative type – preferring to err on the side of caution by placing your hard-earned money in risk-free assets?

    Secondly, how long can you remain invested? If you need to use the fund in the next one to two years, then investments should not be on your mind. However, if your investment duration is between three to five years, perhaps you can consider moderate risk rated investments.

    If your funds can remain invested for over five years, then you are in a better position to weather the ups and downs associated with higher risk assets.

    Answering these two questions will give you an idea of your risk profile – conservative, balanced or aggressive. Next, you should determine your ideal asset allocation. The strategic asset allocation is a breakdown of your investment allocation into three simple investment asset classes – low risk, moderate risk and high risk.

    Low risk assets would comprise of risk-free assets that hold their values and likely have a pre-determined rate of return. Examples would include deposits place in financial institutions and government issued bonds like Malaysian government securities (MGS).

    Other fixed value assets with variable expected returns or those with minimal price fluctuations that fit this category include our Employees Provident Fund (EPF) savings, certain fixed priced Amanah Saham funds and low risk fixed income securities like money market funds or capital protected products.

    Moderate risk assets on the other hand have the potential of generating a higher variable return (e.g. between 4-6% p.a. above the risk free rate) and could comprise of assets such as blue chip dividend stocks or a balanced diversified portfolio consisting of shares and bonds. Property assets and REITs that offer both regular income and potential long-term capital appreciation can be categorised here as well.

    Lastly, we have growth or high-risk assets that are made up of stocks in a diversified portfolio of expansion-focused companies, small to mid-sized businesses in developing countries, commodities and perhaps alternative assets such as private equity investments or collectibles like wine, luxury watches and paintings.

    These may fluctuate a lot more in value but offer potentially better long-term returns.  

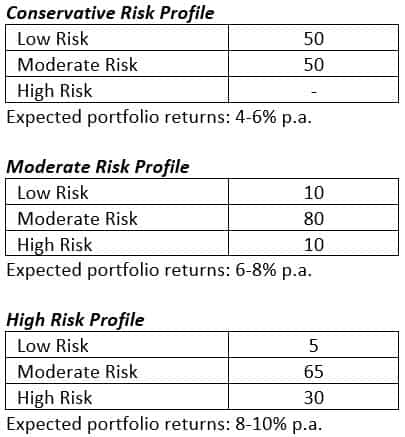
    Let us look at a simple approach to asset allocation for one’s investable assets:

    A moderate risk investor would probably place the bulk of his investable assets in moderate risk assets and only around 10% in the high-risk space. From this allocation, he should expect a blended overall return of around 6-8% p.a. As such, the strategic asset allocation gives you an idea on how you can select a combination of different assets classes and the corresponding expected returns on your overall portfolio.  

    Given the nature of these alternative investments at this juncture – where price discovery remains a challenge, volatility is high, and long-term values remain uncertain – it would be more appropriate to classify them as part of your high-risk investment bucket.

    Back to the question of whether investing in those alternative assets in the examples given are suitable for you, firstly consider where it fits in based on the suggested strategic asset allocation.

    Perhaps a 10% allocation in each of these strategies would be sufficient for most. In simple terms, this means roughly 1-3% allocation of one’s investable assets would be about right for the balanced to aggressive profile investor.

    In conclusion, the next time you encounter an innovative investment option that comes across as the best invention since sliced bread, the first thing you need to do is to increase your knowledge and understanding of that product instead of signing the dotted line simply based on a herd mentality or the fear of missing out.

    Should you decide to proceed thereafter, then invest based on your ideal strategic asset allocation in line with your risk profile. This golden rule should keep you in good stead for a long time to come.

    About the Author:

    Felix Neoh CFP CERT TM is the Director of Financial Planning at Finwealth Management Sdn Bhd and is a certified member of FPAM. He can be contacted at enquiry@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth

  • 5 Investing Lessons from Warren Buffett’s Letters

    5 Investing Lessons from Warren Buffett’s Letters

    The letters of Warren Buffett… What are they?

    Well, if this is the first time that you heard of these letters, you are likely new to investing or Warren Buffett. Let’s start by giving you the background of this super investor, his letters and its significance to the investment community around the world today.

    Who is Warren Buffett?

    Warren Buffett is the chairman and CEO of Berkshire Hathaway Inc, a US-listed holding company that owns substantial interests in some of the world’s most profitable and valuable companies. They include Apple, Coca-Cola, American Express, Wells Fargo, US Bancorp, and so on.

    The 91-year-old Buffett has accumulated a total of US$125 billion in net worth, hence, placing him as the fifth richest man and a living investment legend on planet earth today.

    A native of Omaha, Nebraska, Buffett is also known as the Oracle of Omaha because the investment community closely follows his investment picks and comments on the market.

    His Letters

    Buffett writes to his fellow shareholders of Berkshire Hathaway Inc to report on the latest happenings and future direction undertakings of the company, and more importantly to the rest of the world, imparting his gems of wisdom and as well as decades of experiences in the field of investing.

    Tens of million investors around the world have read and studied his letters in search of insights to what or how they can do better when it comes to managing their investments.

    My Advice to New Investors

    Empty cinema white screen with audience. Ready for adding your picture. Screen has crisp borders. This shot was made using tripod with long exposure.

    Read it. Study it. It is worth it. You will emerge as a better stock investor from it. Here, in this article, we’ll share five lessons from reading the letters written by Warren Buffett. 

    1. Investments Into Productive Assets

    Warren Buffett invests for steady and rising cash flows for the long-term. In his letter in 2011, he views a stock or a business as a ‘commercial cow’ which could produce ‘milk’, referring to recurring profits and cash flows for years or decades to come in the future.

    Also, in his letter in 2013, Buffett wrote that if your focus is on ‘prospective price change’ when buying stocks, you are speculating and he is sceptical of anyone who claimed to have sustainable success in doing so in the stock market.

    So, put it into perspective:

    An investor is one who will be looking at a stock’s long-term income-generating ability before investing for he wants to receive recurring profit or to have its shareholdings revalued higher as a result of sustainable growth in earnings in the future.

    A speculator tries his luck buying into stocks in the hope that its prices might somehow jump in the future, which is not wise based on the writings of Buffett. After 78 long years of investing, he has not seen anyone able to speculate his way to sustainable profits in the stock market. Thus, the question is: ‘Why would you?’

    2. Be Prepared For The Thousand-Year Flood

    Jokingly, Warren Buffett remarked in his letter in 2014 that he would be the guy who sells life jackets if the thousand-year flood occurs in the future. What does it mean to get ready for the thousand-year flood?

    The answer lies in the ‘financial staying power’ of an investor. This is evident for Buffett for he has maintained a sizeable cash balance of US$ 75+ bil within Berkshire Hathaway Inc in Q3 2019. While he stated that cash itself is a poor investment, he is holding onto them for emergency funds or to stand by for significantly discounted investments in the future. In other words, Buffett believes not in being cash-strapped and is one who builds a sizeable buffer at all times.

    3. The Use Of Debt Or Borrowings

    In his letter in 2010, Buffett likens debt as being a double-edged sword. It can either make people rich or poor. He is known to favour an investment into stocks where their businesses earn a good return on equity (ROE) without or with little use of debt.

    But, having said that, Berkshire had made investments into companies which were funded by long-term debt such as Burlington Northern Santa Fe and MidAmerican. Nevertheless, Buffett is comfortable with them as the obligation from both corporations is serviced by cash flows from operations which are stable and recurring.

    4. Reduce Investment Fees At All Cost

    In his letter in 2017, Warren Buffett wrote a profound statement: ‘Performance comes, Performance Goes. Fees never falter.’ This comes after Buffett emerged as the winner of a 10-Year Bet against Protege, a US-based investment advisory firm where Buffett has publicly challenged any investment firm to create a fund or funds to beat a ‘virtually’ cost-free unmanaged S&P 500 index fund.

    Protege, the firm who took up Buffett’s challenge, had failed to create funds to overcome the returns of S&P 500 index fund despite having assembled a team of investment experts to manage these funds professionally over the last 10 years.

    The conclusion of this bet is pretty simple. It is to educate the public, and especially those who had invested in mutual funds or hedge funds, to rethink about their investments. First, he wishes to point out about the recurring ‘fees’ involved in these investments, for they are not cheap. Second, he wants us to consider the worth of fees paid to fund managers.

    This is because fund managers are compensated regardless of the fund’s investment performance over the long-term. Hence, the message is clear, and it is to avoid investing in funds that charge high fees for they would erode your investment returns in the future.

    5. Continuous Learning Is Important To Investors

    Warren Buffett is an avid reader, an active learner and one who appreciates the power of mentorship. It is evident, as Warren Buffett revealed that he had read two books that had effectively shaped his investment life.

    The first is titled ‘The Intelligent Investor’ by his mentor, Benjamin Graham, while the second is titled ‘Common Stocks and Uncommon Profits’ written by Philip A. Fisher. To date, he remains committed to applying what he’d learnt from these books into investing in the stock market and now, Buffett believes that he should pass along this same investment wisdom to the next generation, which is us.

    What Should I Invest In 2022 And Beyond?

    The answer is: ‘Investment Education’. Instead of finding out what stocks to buy or speculate in 2022, why not take time to learn to become a better investor? It would be the most profitable thing to do if you are new to investing, be it stocks or properties.

    By the way, you can download Buffett’s letters from Berkshire’s website, for free. Begin your progression towards becoming a better investor.

    About the Author

    This article is co-written by KC Lau and Ian Tai.

    Ian Tai is a Dividend Investor. Financial Content Machine. Producer of 200+ Articles, Weekly Host and Presenter at KCLau.com. Co-Founded DividendVault.com, an online educational membership site that empowers retail investors to build a stock portfolio that pays rising dividends in Malaysia and Singapore. 
    KCLau is a financial educator, having published seven books including the current bestseller Money Smart, and co-created a dozen online financial courses. He gives away his popular Money Tips e-book volumes free at his website: https://KCLau.com

  • Investing In Property With A Holistic Perspective Using This 3-Step Process

    Investing In Property With A Holistic Perspective Using This 3-Step Process


    “17 years ago, I missed the opportunity to invest in Desa Park City. 5 years ago, I missed Sunway Velocity. I regret it. I don’t want to miss the boat this time”.

    “Too many new projects available now and developer offers good incentives and rewards, I don’t know which to choose.”

    “I heard many unpleasant experiences from friends and family, I worry the property I invested would be abandoned or the quality is bad when I gain vacant possession.”

    These are typical comments you might hear when Malaysians share their perspective on property investing. Like other developing countries, economic growth and continuous urbanisation in major cities have made real estate investing one of the more attractive investment vehicles for Malaysians to grow their wealth.

    There are loads of property investing books and “property gurus” on hand to offer pointers to those looking to embark on the property investment journey, imparting their strategies and experiences in this field. Some share their seemingly unbelievable profit-making experiences through property flipping (buy-to-sell) or property management (buy-to-rent).

    The outbreak of Covid-19 in 2020 put a dampener on an already sluggish real estate market, resulting in property players having to transform their business model to weather the storm. Industry players responded with various digital innovations to allow most of the transaction process to be conducted without physical interaction.

    Supported by a low interest rate environment, these efforts seem to be paying off, as property demand at certain areas remained fairly stable despite the depressing health and economic backdrop.

    Just like any other investment asset class, the real estate investment journey has its ups and downs. Some of us may make money from it, others should learn from the mistakes made so as not to repeat them to our own detriment.

    An opportunity often arises from a threat, so it is important to be able to separate the wheat from the chaff. In order to have a higher probability of success, we will need to apply a structured approach to address these potential opportunities.

    Plan-Check-Monitor

    A structured opportunity management approach for investing involves a simple three-step process: Plan-Check-Monitor.

    Plan refers to having a clear purpose and objective for the investment – do you know what you want to achieve and when you want to achieve that? The answer will determine your direction in investing and know what information is required to build a solid investment portfolio.

    Check involves activities to survey and collect information about the respective investment to ensure it is compatible with your plan.

    Monitor is about keeping track of any changes on investment and being sensitive to the important indicators that your investment returns can potentially sustain and improve, or otherwise. This also requires one to be nimble and responsive according to changing market conditions. Adopting the PCM approach will enable investors to differentiate whether it is a real opportunity, and to know how to ensure the compatibility of the opportunity to one’s current situation.

    As property investing is possibly the single largest financial commitment in one’s lifetime, it can have a different impact on various aspects of our personal and family life. As such, merely asking what property to buy or where to buy is not enough.

    So how we can apply the PCM model in a property purchase scenario?

    You should start with questioning. What is your primary purpose for this property investment? What is your goal for this investment? The answer is crucial to determine the appropriate strategy to follow.

    Say you are looking for an own stay property. You will need to identify a property that caters to your current and future family needs. Start by consolidating information about the targeted property (for example, understand the potential of the upcoming neighbourhood, the demographics, nearby amenities, etc.).

    Then identify and assess the saleable area of the property, number of rooms, potential renovation costs due to expansion or layout restructuring and suitability for future expansion to determine its compatibility to your needs. For newlyweds, do not forget to consider the extra rooms for your future children.

    If you are looking for investing or a rental property, you need a clear approach with cost-effective solutions and a well-planned property rental management strategy to optimise your rental yield. If you want to save the cost of engaging agents or a property management company, you need to determine if you have the capability to do it on your own.

    Again, start with gathering information about the property types that are popular for rent, the targeted potential tenants, their preferred rental price range, etc. Then continue to identify and assess the property based on the needs of your targeted tenants. 

    In addition to this, you should continuously monitor the progress around the targeted property area. Are there any growth plans and projects to spur the development of that area, such as  upcoming MRT lines, connection to highways and other developments that might affect your investment return direct and indirectly?

    You should also be prepared for vacant tenancy periods without rental income as this will represent an opportunity cost to you. Hence, your sensitivity towards the growth around the property area will assist you to seize the opportunity in pricing the rental accordingly.     

    Potential capital appreciation and positive rental income is a property investor’s ultimate goal. Nevertheless, few can accurately predict their actual investment return as this will depend on the overall development and progress of property location – actual versus expected.

    Given this uncertainty, it is important for you to have a practical plan to secure the rental yield and a well-planned exit strategy prior to investing in any property. As such, one can apply the PCM model prior to the investment instead of blindly following what is recommended by people around you.

    Impact On Your Financial Health

    Malaysia currency of Malaysian ringgit banknotes background. Paper money of one, five, ten, twenty, fifty and hundred ringgit notes. Financial concept.

    The above examples should give you a fair idea on how you should approach a property purchase in the future. But is this sufficient for you to make the right property-related financial decisions? Will the purchase have a positive or negative impact on your overall financial well-being? To answer this, we will need to overlay the decision-making process with a holistic financial planning perspective.
    Broadly speaking, holistic financial planning provides you a 360-degree view of your financial situation, taking your current and future financial expectations into consideration to empower you to make more informed investment decisions. A holistic financial planning empowers you to constantly be on guard against possible investment risks and potential financial costs as you expand your property portfolio holdings.
    Working on strategic asset allocation helps you manage your investment risk while stabilising your overall investment returns. For example, strategic asset allocation will remind you to invest less than 40-50% of your funds in properties.

    Understanding key financial ratios provide valuable information to help you monitor your debt ratio to avoid over-gearing and keep track of your emergency funds in the event of a scenario without rental income. Cash flow management will help you ensure that you have sufficient cash for down payment without using up your emergency funds, and give you clarity on how you can continue to save and invest for other goals once the property loan repayment starts.

    In conclusion, there is no doubt that property investing has a big role to play in growing one’s net worth. However, there are pitfalls in investing in this asset class so the practice of opportunity management approach utilising the PCM model, coupled with holistic financial planning, will help to minimise.

    About the Author

    Jess Hon is a Licensed Financial Planner with Finwealth Management Sdn Bhd and would like to assist millennials to take control of their own finances and achieve financial happiness. She can be contacted at jesshon@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth

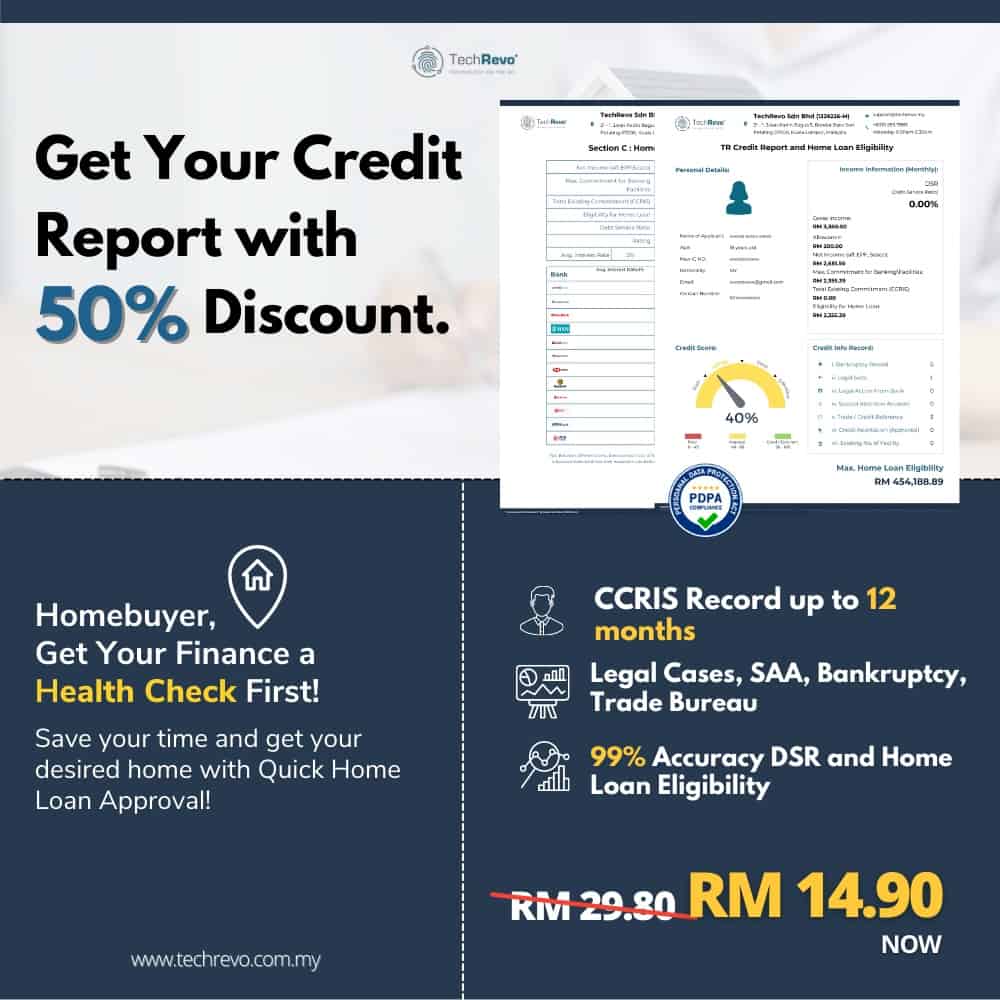
    Do you know how much is your Home Loan eligibility? Not sure how much you can borrow from the bank? 

    Get your TechRevo credit report + Home Loan Eligibility which includes:
    • Credit history up to the past 12 months [CCRIS] 
    • Bankruptcy, Legal Suits, Legal action from banks, SAA, and Trade Bureau (Section E)  
    • Max home loan eligibility calculation up to 12 mortgage favorable banks in Malaysia 
    • CCRIS + Credit report + Calculator 

    It only takes 5 minutes. Click here now to get 50% off -> https://www.smartinvestor.com.my/techrevo


  • 4 Tips To Invest For Long Term

    4 Tips To Invest For Long Term

    Countless investment articles have continually espoused the benefits of having a long-term view. Forget about the short-term setbacks and keep your eyes on the prize. It is just a bump in the road. Stay invested and you will reap the rewards in the end.

    But in reality, adopting a long-term view might be more difficult to practice. It can be a long journey riddled with sudden surges of volatility capable of wiping out massive gains in a portfolio.

    Telling someone to be patient and ride through the volatility is the common refrain used in the industry to tell investors to stay invested and not part with their funds. But how convincing is it sometimes?

    Here are a few tips on how you can practice long-term effectively in your investments:

    1. Accept That It Is Going To Be Bumpy

    Having a long investment horizon does not mean you will be spared from the volatility that is bound to happen in any market.  An investor with a 20-year investment horizon who started investing in the year 2000 would have to endure the dotcom bubble, September 11 terrorist attacks, the 2008-GFC, taper tantrum in 2013, and now the Covid-19 pandemic.

    In fact, the longer your investment horizon, the more economic recessions, bear markets, geopolitical flares and market memes you have to endure. Saying that you have a long-term view does not automatically give you a free pass and allow you to bypass these short-term swings. Your portfolio will react in tandem and you might have to put up with losses for periods of time. This sounds painfully obvious, but few investors appreciate this fact.

    Many still react immediately and make drastic shifts in their allocation because the sight of red just makes them nauseous. That is when you start making those impulsive decisions and kicking yourself later.

    Learning to live with volatility requires a mental adjustment and some getting used to. But accepting it is the first step.  

    2. Diversification Is No Fun, But It Works

    The future is inherently unpredictable and no one has perfect foresight of everything including how an industry or a company will evolve in the future. So how do fund managers do it then and invest with conviction?

    The answer probably lies somewhere in between. There are no absolute yes’ or no’s in the investment realm where the tide can turn at any time. Decisions are made by fund managers by determining what is probable and what is not based on information available.

    That is also the reason why the holdings of a fund are diversified across different companies or sectors to avoid any overreliance on a single stock to drive returns.

    In an age of instant gratification, where expectations for returns have only gotten higher and quicker, diversification almost seems passé today. Making concentrated bets in eye-watering meme stocks or cryptocurrencies with promises of double-digit returns is now considered à la mode.

    But to succeed in investing is not about making no mistakes at all. Not even Warren Buffet can lay claim to that. Rather, it is about making sure you get more rights than wrongs in your investment journey.

    The fact that we do make mistakes in investing is why it is critical for our portfolio to be diversified. That way, losses can be offset by gains in your portfolio to ensure that you still have skin in the game.

    Setting aside some ‘play money’ to chase the next stock or crypto darling is unlikely to do much harm. But the real danger is when investors gamble their entire savings away and lose all their capital with no chance of ever returning.

    3. Holding Power Is Crucial

    The ability to think long-term can only happen when we feel secure about our present state. An investor with low savings and piling debts cannot be expected to stay ‘optimistic’ about the future and ignore the losses in his portfolio when his survival is on the line. Who bothers about the future, when they are worried about the now?

    There were many lessons that Covid-19 taught us about managing money, but the most valuable one is undoubtedly the importance of keeping an emergency fund.

    The future is becoming inherently more unpredictable. The only way to tide things over is to keep an ample margin of safety through cash reserves and liquid instruments such as money market funds.

    To be fair, it is hard to know how each of us will react when a market meltdown happens. It is usually preceded by really scary events like a terrorist attack or this current pandemic. But if you are experiencing real anxiety, perhaps it is an indication that you might be taking too much risk or you actually do not have the financial endurance that you thought you had before.

    This brings us to the final tip…

    4. Revisit, Review And Rebalance

    Change is constant throughout history and market cycles. But many of us underestimate the capacity for change in ourselves too. Major life events such as a new addition to the family, marriage or a career switch can affect our capacity for risk and investment objectives.

    For example, an investor who is now nearing retirement might have to tweak the portfolio’s allocation towards more conservative asset classes like fixed income or balanced funds. On the other hand, an investor who has just become a parent may want to be positioned more heavily in equities for long-term capital growth opportunities.

    While investors should commit and stick to their long-term plan, it is important that they also periodically review their portfolio to see whether it is still geared effectively to accommodate any new changes in their life. An investment plan should not necessarily be seen as being carved in stone; it is meant to be organic and fluid just as life is.

    Lastly, throughout the year, an investor should also consider whether the asset allocation (for example, in equities and fixed income) has drifted away from the initial parameters because of market movements. In hot markets, the equity portion in a portfolio might climb higher than other asset classes.

    Rebalancing is then necessary to ensure that the portfolio is reset back to its target allocation to ensure that it is compatible with the investor’s risk appetite. Otherwise, the investor might be taking more risk than originally intended which might be detrimental to his long-term goals.

    Hold On And Sit Tight

    Long-term investing is not so difficult when you focus on yourself and ignore the goings-on of markets. Some patience is needed, but what is also essential is the ability to endure and be willing to put in the time to compound returns.

    As legendary American stock trader Jesse Livermore said, “It never was my thinking that made the big money for me, it always was sitting.”

    About the Author

    Lee Sheung Un is a Communications Officer at Affin Hwang Asset Management. A millennial, he is still finding that balance between wealth, freedom and purpose. Views expressed are his own.

  • 5 Drawbacks Of Unit Trusts Investment That You Should Know Before Investing

    5 Drawbacks Of Unit Trusts Investment That You Should Know Before Investing

    We’ve gone through unit trusts investment in few articles before. You may get the ideas of having unit trusts investment will help clear your mind on investing but there are some drawbacks that need to be considered.

    Well, if you never heard of unit trusts investment, maybe you should read Unit Trusts, The ‘Safest’ Investments For Beginners In Malaysia?

    If you want peace of mind, you may consider unit trust as one of your investments. You just sit back, relax and let professionals do their job. You just have to wait for the results of your investment. How’s that?

    Like there’s no light without the darkness, there is also its downside. It’s up to us how to manage our investment settings. Unit trusts investment may not suit us, but it may suit somebody else well.

    5 Drawbacks of Unit Trust Investment

    1. The Fees

    unit trusts investment

    Investing hassle free will cost you some fee. As we all know, your funds will be managed by professionals who are the fund manager. As the fund manager trying their best to get the most profit from your investment fund, you will need to pay for their expertise.

    Your returns may be lower than the market due to this fee. Besides, other fees may also be applicable, such as administration fees etc.

    2. Less Control of Your Investment

    Yeah, that’s your money, but you don’t have control. The fund managers will manage it for you. You won’t be able to select the exact assets or specific stocks to buy. But no worries, as an investor, you can still choose trusts that align with your risk appetite or your investment goals.

    Other than that, your fund manager will help you manage the fund based on your goals and preferences. You must trust their expertise in managing your fund!

    3. Brain Dead Portfolio

    There are also unit trusts known as brain dead portfolios. Fund managers will buy various types of investment instruments as an investment method, but there is no portfolio reconstruction process implemented by them (not all).

    Your investment will be passive and wait for time to pass until the value of the stock increases in the future. This will be detrimental to investors as it will cause the profit taking period to be longer. A good fund manager will review their portfolio, sell unprofitable stocks, and replace them with more potential holdings.

    Read : Best Mutual Fund In Malaysia During The Pandemic

    4. Lower Returns Than ASB & Tabung Haji

    Not everyone has the privileged to subscribe to ASB and Tabung Haji. They opt for other investments like unit trusts. Believe it or not, there are times when ASB and Tabung Haji returns were better than unit trusts.

    Typically, these low return of unit trusts was due to too many funds being put into low-risk products such as government bonds that only will give you around 3% – 5% per year. If it’s too low, the investors have to wait for at least 2-3 years to get the original working capital (don’t forget about the other charges incurred).

    5. Not Suitable For Short-Term Investment

    unit trusts investment

    Most of the unit trusts are not suitable for short term investment. That is what often touted by agents or principals. The acquisition of profits takes time. It’s not a one-night rodeo and you can just enjoy your profits. It takes time!

    Want to know what unit trust investment can offer you? Please read The Benefits Of Unit Trusts Investment In Malaysia.

    Unit trusts are a very good investment but it will not suit every investors. Make sure that you understand your investment preferences and needs before investing.

  • Is Takaful Not Attractive For Most Malaysians?

    Is Takaful Not Attractive For Most Malaysians?

    “Wisdom is not measured by appearance.”

    As a husband, father, son, and even brother, I am the breadwinner and main contributor to the family finances. I work hard to give my best to my loved ones. The pressure is on to make sure I can leave my loved ones in the same or even better state when I am gone

    As a Chief Agency Officer, I am aware of the need for takaful protection in life. It can alleviate unexpected situations Takaful benefits provide for its participants in times when emergency funds are required because of a disaster resulting in death, accident, critical illness, or hospitalisation.

    The adage preparing for a rainy day holds true with a comprehensive takaful plan that can maintain our, or our beneficiaries’ lifestyles in times of disaster.

    I am often asked what is takaful and how is it different from conventional insurance.

    Takaful vs Conventional Insurance?


    Conventional insurance and takaful share the objective of protecting against financial loss. However, closer inspection reveals some clear differences.

    Takaful is based on Islamic principles of mutual cooperation (taawun). Participants (customers) fulfil their obligations by contributing a certain amount of donation (tabarru’) into a fund to protect one another against losses or damages covering life, general (assets) and medical. A takaful operator manages this fund.

    The takaful operator disburses the funds according to its participants in the event of loss or damage suffered. Surplus monies will be distributed between customers and operator at the end of the financial term based on an agreed ratio. This will only be done after all obligations of assisting customers has been fulfilled.

    Despite being based on Islamic principles, anyone can obtain takaful protection.

    Factors Affecting Takaful Contribution Amount

    Like conventional insurance, lifestyle factors affect the contribution amount each participant is required to make. These include occupation, age, family history, and underlying health factors.

    As takaful is based on the basis of donation, if the tabarru’ fund is insufficient, there may be a revision in the contribution amount. For example, the tabarru’ fund can be short due to volume of claims or medical inflation.

    A responsible takaful operator must monitor and revise the fund if necessary, to ensure it s contributors are always adequately protected. It is important in sustaining the tabarru’ fund for the long term. If a revision to contribution amount is necessary, the operator will notify customers beforehand so contributors are never caught unaware.

    What Can I Do If I Cannot Afford To Fulfil My Contribution?

    If personal circumstances change, let your takaful agent know so that a customised plan can be worked out based on your affordability. There are two main options provided to customers.

    Firstly, there is the option of reducing some of the benefits while maintaining the same amount of contribution. Another option is to remove certain riders (add-ons) and replace them with other benefits that may be more relevant to the customer’s needs in life.

    This is where a knowledgeable agent is invaluable. A good agent can advise you on the available options, and what may be best for your situation. Everybody’s protection needs differs from person to person. This is why Bank Negara Malaysia requires agents to conduct thorough fact finding to assess customers’ needs and provide recommendations.

    Do I Still Need Takaful When My Employer Already Provides Protection?

    Many overlook the importance of having their own personal protection plan. They think t heir employers will provide coverage for them until they retire. But work situations can change. Some may receive better offers or choose to work for themselves. When this happens, the protection afforded to them by their employer ceases. The level of protection can also cease or change upon retirement.

    Participation in takaful is for future needs. It is not only for one time use. Nobody can guarantee our health throughout life.
    Separating your takaful plans to cover different scenarios and needs is advisable.

    The rule of thumb is to differentiate existing plans for specific purposes, such as medical, savings, and retirement.

    Nowadays, there are plenty of plans with competitive and flexible riders. This allows users to choose add-ons based on their lifestyle needs. It minimises the need for multiple plans as one plan can cover different things. It is recommended to seek professional advice from a knowledge agent to get a better understanding.

    How Can I Tell If The Agent Is Right For Me?

    Agents are dutybound to ensure they do not bring disrepute to the takaful company, which seeks to help individuals, businesses, and community from financial loss. All agents must be licensed. You can and should ask to see the agent’s credentials before signing o n the dotted line. To obtain the license, the agent is required to pass a high integrity and closely supervised Pre Contract Examination organized by Malaysian Insurance Institute (MII).

    Takaful agents are subject to an additional Takaful Basic Exam (TBE) by the Islamic Banking and Finance Institute Malaysia (IBFIM). Many agents now opt to sit for TBE so they have wider breadth of knowledge to better serve customers.

    Beyond this, good agents must have solid fundamentals on different plans available. Investing time in the Customer Fact Finding (CFF) form will enable agents to understand the lifestyle and needs of the customer. Only then can agents propose a suitable plan within the customers’ budget, with adequate protection and savings.

    What Makes A Great Agent Stand Out From The Rest?

    Simply put it is their effort to upskill and improve themselves. Agents must complete the Continuous Professional Development (CPD) training yearly. The minimum is 30 hours. Dedicated agents typically undertake up to 60-70 hours of learning per year to upgrade and upskill themselves with knowledge in providing professional service and advice to help their customers better.

    Great agents prioritise customers. They consider customers’ future needs and explain how the recommended plan ca n help address customers’ concerns and provide peace of mind. The agent must also be honest in what the plan can or cannot do for the customer.

    Customers may have other concerns as well such as the processing of claims, plan maturity or even lapsation of policies. A well trained agent must be able to answer and address these concerns.

    Can Agents Help Me Get Claims Approved?

    A common complaint about the industry is the difficulty in getting claims when required. It does not help matters if the agent is absent or not helpful at all. Claims may be denied due to plans not covering certain aspects, or in other cases it may be due to anti-selections. This is where a person does not declare their health conditions when subscribing to a plan. Upon filing a claim, their case is studied and if found to have not declared, their claim could be denied.

    Good agents will advise customers to be honest and the onus is also on customers to do so. Customers must make timely contributions to ensure their takaful certificates do not lapse. To this end, agents will also advise customers to go through available online portals to avoid delays which could leave the customer unprotected.

    In the case where genuine takaful claims are denied, the customer can write to the takaful provider to appeal or dispute the denial. All takaful providers will act in a fair manner and review the case thoroughly before rejection. The providers are careful to ensure all legitimate claims are honoured.

    Investing into protection is a critical life decision. It is wise to engage a certified and knowledgeable person on different plans and coverage. Seeking advice from multiple agents to make more informed decisions is also good.

    About the Author

    Nazrul Namizan is Chief Agency Officer of Zurich Takaful Malaysia Berhad.

  • Aggressive Investment vs Conservative Investment, Which One Is Suitable For Me?

    Aggressive Investment vs Conservative Investment, Which One Is Suitable For Me?

    “Should I invest in aggressive investment or conservative investment?”

    This is one of the most common questions often asked by the public. We all know that aggressive investment implies potential higher return, but it always comes with higher risk. While conservative investment implies potential, or sometimes guaranteed lower return but it always comes with a lower risk.

    There are usually two types of answer from the investors and non-investors. Investors will always argue that aggressive investment is the best choice because conservative investment can’t even beat the inflation rate. Non-investor will always defend that conservative investment is the best choice as it possesses lower risk of losing capital.

    However, all the above said reasons should not be the primary factors when we decide on which investment tools to invest in. Instead, we should be more concerned on whether the investment tool can help us to achieve our goals.

    Below are two scenarios to illustrate the above argument.

    Mr. A
    Current age: 40 years old
    Desire retirement age: 60 years old
    Life expectancy: 99 years old
    Annual retirement income needed at current value: RM60,000
    Inflation rate: 5%
    Target annual return after retiring: 5%
    Current investable asset: RM1 million

    After some calculation, Mr. A find out that he needs to have a total of RM6.28 million of retirement fund at the age of 60 to sustain his life until 99 years old. With the investable asset of RM1 million that Mr. A has, he needs to expect 10% annual return for 20 years to grow his RM1 million to RM6.28 million.

    For Mr. A to gain 10% annual return, he would have to choose moderate to aggressive investment tools. He can have a combination of few investment tools in his portfolios such as stocks, derivatives, equities unit trust fund and P2P financing to generate potential 10% annual return.

    However, it is definitely a wrong decision for Mr. A to invest his money into conservative investment tools such as fixed deposit, money market fund or savings account. This is because these financial tools are not able to deliver a potential of 10% annual return for Mr. A.

    Choosing any investment tool that is unable to help Mr. A to achieve his retirement goal, which is to have a total of RM6.28million at the age of 60, is considered a wrong investment decision.

    Despite some of the aggressive investment might be risky and volatile, investor can still mitigate the risk by doing proper research regarding the investment tools before making decision, diversifying the investment portfolio, knowing the investment horizon, and only investing through the legal platform.

    As what Warren Buffet said: “Risk comes from not knowing what you’re doing.”

    But, does this means that if an investor choose to invest in conservative investments is wrong?

    The answer is NO.

    Mr B
    Current age: 60 years old
    Desire retirement age: 60 years old
    Life expectancy: 99 years old
    Annual retirement income needed at current value: RM60,000
    Inflation rate: 5%
    Target annual return during retirement: 0%
    Current investable asset: RM6.85 million

    Mr. B goes through the same calculation, he finds out that he needs RM6.85 million to sustain his life until 99 years old and he already has RM6.85 million in hand.

    In this case, Mr. B does not need to invest his money at all as his retirement goal is already met. So, it is alright for Mr. B to keep all his retirement fund in conservative investment tools such as fixed deposit, money market fund or even savings account.

    Whereas it might be a wrong investment decision to Mr. B if he choose to invest the retirement fund in an aggressive investment tool because he might risk losing the capital which will then affects his retirement plan.

    Hope that these two scenarios can clear the doubt when making an investment decision.

    About the Author

    Angel Chan is a Licensed Financial Planner attached to UOB Kay Hian Wealth Advisors Sdn Bhd. Besides providing comprehensive financial advisory to her clients, she is also committed to educate the public about the correct financial management mindset and methodology through article, YouTube video and Financial Management Workshop conducted by her and the team.

    FB page: https://www.facebook.com/angelchan.financialplanner
    YouTube channel: https://www.youtube.com/channel/UCf5f7O3vuOhnwy_wflDuuKA
    Smart Finance: https://smartfinance.my/planners/chan-aun-kei-rfp
    To book a free 1-hour consultation with Angel Chan: https://forms.gle/8Ur46Dox9T6g3yKS8