Category: lifestyle

  • Growth of the Malaysian Gig Economy Among Gen-Zers

    Growth of the Malaysian Gig Economy Among Gen-Zers

    Social media has been the main source in forming a new culture among the younger generation, creating a new norm that challenges Gen Z to come out of their comfort zone. With technology constantly progressing and simplifying the way we execute our tasks, the gig economy is now high in demand, especially during a time like COVID-19.

    While many among us are afraid of salary cuts and retrenchments, Malaysians are leveraging the resourcefulness and popularity of freelancing to make ends meet.
    Glenn Tay

    According to Glenn Tay, CEO and Founder of Gigworks, the freelancing landscape will not be diminishing anytime soon but will in fact continue to grow at a rapid pace as majority of the workforce are currently conquered by millennials and their priorities are more focused on work-life balance.

    “Malaysian youths, similar to those around the world, are always craving for that opportunity to do the things that they are passionate about, be it traveling, exploring, experiencing etc. and while doing so, they want to have the flexibility to earn sufficient income from wherever they are residing at that time.

    “We cannot deny that this is a new way of working now where jobs are no longer restricted by geographical boundaries. The idea of being fully employed by one firm is not desirable for those looking to have ‘freedom’ in their work management,” said Tay.

    With jobs experiencing drastic change and with the labour force shrinking, competition for talent is getting increasingly intense. Organisations need to think out-of-the-box to attract the talent market such as redesigning the job scopes in a way that can both draw in and connect with the Gen Z and, at the same time guarantee that these jobs continue to create a path for future talents.

    The Gen Z in Comparison to X and Y

    A study by the Zurich Insurance Group (Zurich) and the Smith School of Enterprise and the Environment at the University of Oxford on agile workforce has found that 38% of the respondents in Malaysia who are currently in full-time employment, are looking to enter the gig economy in the next 12 months. This percentage is significantly higher than the global average of 20% recorded in the study.

    While individuals involved in the gig economy come from a diverse range of backgrounds, identifying the main target is essential for the gig economy to develop in years to come. An ever-increasing number of individuals from Generation Z appear to shun ordinary 9-to-5 jobs. Instead, they would prefer working for themselves by freelancing their way in order to obtain their dream jobs.

    The impact of their entry into the working environment will be quick and significant. However, Gen Z has an entirely different point of view compared to the rest when it comes to careers and how to define success.

    Gen Z More Inclined towards Autonomy 

    One of the factors contributing to more people opting for freelance work over permanent 9-to-5 professions is self-directed motivation. It is much simpler to be driven when you are in control of the flow of your work.

    It gives Gen Z a sense of autonomy which they desire for themselves – generating a sense of individuality, determination and providing the ability to achieve what they have been dreaming of. Having control over how they work and the type of job to work on is something that appeals to this young crowd.

    The appeal in this type of working lifestyle is that it also allows for work to be centred around creative passions based on portfolios and skills, as opposed to a full-time job that provides steady income but is more monotonous and rigid in structure.

    For example, university students juggling between college and work-life can find it challenging, therefore they are looking for easier alternatives to fund their tuition fees. Joining the gig economy as a freelancer allows them to have this much-desired flexibility. Although they may not always be able to earn as much as a full-timer, the option of being able to pay off their debts bit by bit while still having the capacity to manage their work-life-balance is satisfactory enough for these undergrads.

    Desire for Flexibility

    According to Workforce Institute, 55% of Gen Z-ers are attracted to the ability to work on their terms in gig employments as the flexibility allows you to go at your own pace and avoid breakdowns. Approximately 26% of Gen Z-ers would work harder and remain longer at an organisation that supports flexible working hours.

    Millennials and Gen Z currently account for slightly over a third of the global workforce. In the next decade, that figure is set to shoot up to 58%, making the youthful generations the most dominant drivers of the workforce.

    To meet the demands of this up-and-coming generation, we, as a society, have to respond to these differences in a mutually beneficial way that would increase trust and generate positive societal impact.

    Thus, it is important that a proper transition and greater overall acceptance of freelance careers is in place to welcome this new way of work.

    Digital Natives 

    Being moulded by technology, Gen Z was exposed to the Internet at a young age, making them the youngest influencers to appear on the scene. They are generally more tech-savvy than the older generations as they have never known a world without smartphones and the Internet.

    Non-traditional ways of working appeal to this group as they are more familiar and accustomed to a technology-driven society.

    We see a rising consensus that digital readiness is no longer optional, but mandatory. When MCO was enforced, the few months of this nation-wide exercise have shown that Malaysians have become more comfortable with utilising technology to collaborate and deliver work on time, replacing the need for physical travel.

    However, this period also brought to light certain difficulties and challenges encountered when working from home such as network issues, communication barriers, and lack of technology readiness.

    Nonetheless, Malaysia is well equipped and ready to adapt to this new normal, with Tun Dr. Mahathir Mohamad looking to implement the gig economy as part of the upcoming 12th Malaysia Plan, and most organisations already alerted and prepared following the MCO period.

    It is only a matter of time before we start to enjoy improved network connectivity and speed, better IT infrastructure, and clear work procedure and discipline to be implemented for the majority of Malaysian freelancers.

    Is Gig Work Appealing Enough?

    Numerous permanent jobs today do not provide a similar degree of job security compared to the past as employers often look at optimising cost efficiencies. Organisations often choose to reduce operation size as a way to find more resources to invest in other parts of the business.

    Instead of simply keeping full-time employees, a coordinated workforce permits organisations to better manage expenses and investments to coordinate business and market demands. Gen Z wants both stability and flexibility at the same time to stay in business.

    Due to this sentiment and in realising the limited options for individuals to find valid yet justifiable freelance work, Gigworks, a mobile application providing online professional service engagement is opening doors for all groups including the younger generation to ensure their talents are being recognised by businesses while catering to the needs of Gen Z.

    “We want to introduce a culture that builds the interest of Gen Z to have a work-balance and offer stability to foster them financially especially during a time like this. Encouraging them to pursue their passion will only make them more confident, allowing them to venture into new projects,” said Tay.

    In a nutshell, now that technology finally exists and caters to these demands, this will be something everyone can benefit from in the gig industry.

    This article is contributed by Gigworks, a mobile application inspired by the impact and advancement of technology in people’s lives. For more information on the company and its services, visit www.gigworks.co/sg.
  • Encouraging Property Trends Among M’sians Despite COVID-19

    Encouraging Property Trends Among M’sians Despite COVID-19

    iProperty.com.my has revealed encouraging property-seeking trends among Malaysians despite pandemic.

    iProperty.com.my has recently announced the results of its latest consumer survey. The survey aims to understand Malaysians in their property seeking journey during the Movement Control Order (MCO) period and how it has affected them.

    The survey also analyses the purchasing desire of homebuyers before, during and after MCO. The survey was conducted between 11 May – 1 June 2020.

    44% of survey respondents were looking to purchase a property before the announcement of MCO

    The property portal reveals that 44% of the survey respondents are looking to purchase a property before the announcement of the Movement Control Order (MCO).

    Out of these property seekers, 28% stopped actively looking after the MCO was announced on 16 March 2020. However, more than one third of the property seekers who stopped actively searching (38%) stated that they are either waiting for prices to drop or are still open to good property deals.

    The top two factors which influence a property seeker when evaluating an online listing is validation of a property’s valuation (pricing trends for similar properties) and listing content which gives a very clear understanding of the property’s space and layout.

    Property seeking interest unaffected by MCO

    According to the survey results, in spite of the unprecedented situation caused by COVID-19, property seeking trends among Malaysians remained encouraging.
    Interestingly, the survey results reveal that 24% of the respondents who were not looking to buy a property before the MCO are now looking to purchase after the MCO announcement.
    A majority of these new entrants are either looking at current market conditions as an opportunity to purchase their first homes, to upgrade their existing homes or to invest in property, while the minority mentioned that they are downsizing or moving to more convenient locations.

    With these new entrants the percentage of respondents who are actively looking for a property increased to 45% post MCO announcement. On top of this, another 10% of respondents, who are not actively looking for a property post MCO, are open to the right property deals.

    Taking into account this group, the percentage of respondents who are interested to purchase a property after the MCO announcement tops 55%.

    Nevertheless, 92% of the people who are actively seeking for a property state that they have a lower readiness to transact (49% are waiting for prices to drop while 43% are still looking but more cautious about making any financial commitments).

    90% of property seeking respondents named easy entry options as the top factor

    The survey further reveals that 90% respondents answered that the factors which will help ease their transaction decisions are easy entry options such as zero down payment, developer discounts and subsidised legal costs.

    In addition to easy entry points, the survey also reveals that 81% of respondents are looking for trustworthy and reliable developers/ agents.

    Also, 89% of property seekers are receptive to the idea of virtual viewings. 75% state that it will help them decide whether or not to view a property in person while the remaining 14% says it is enough for them to decide whether to buy/rent a property.

    On the same note, 83% of all respondents want to get updates on good property deals (new properties on promotion, or sub sale properties at good prices), while 54% of respondents are interested in market insights and data, to help them better understand the current state of the property market.

    This positive consumer survey highlights the timeliness of the re-introduction of the Home Ownership Campaign (HOC) under the government’s recent Economic Recovery Plan (PENJANA) package.

    The HOC initiative which features significant stamp duty holidays would help alleviate the financial burden of aspiring home buyers.

    Commenting on the consumer survey, iProperty.com.my General Manager of Marketing and Communications Wong Siew Lai said, “The findings from this consumer survey revealed something very encouraging on Malaysian property seekers purchasing desires despite the unprecedented situation caused by the COVID-19 pandemic.

    “Overall, volume of demand did not change significantly and people are still looking for properties. Property seekers are spending more time researching and evaluating their property options online.

    “The market may be much more receptive to property deals and solutions that help them discover those deals, as well as online content that helps them better understand the current market conditions.

    “If they discover the right deal, many opportunistic property seekers are willing to invest even beyond their original budgets.”

  • Investing Quandary for Gig Economy Millennials

    Investing Quandary for Gig Economy Millennials

    In Malaysia, the rising number of gig workers face various challenges to investing for their future.

    The rapid advancement of technology over the past decade have more than changed the way people live, work and spend their money. The employment landscape, too, has undergone an evolution, with hyper-connectivity and social media paving the way for the rise of the ‘gig economy’.

    The gig economy is a labour market characterised by the prevalence of short-term contracts or freelance work done by individuals. Driven by the digital environment and popularity of apps that instantly communicate information and opportunities for work, the gig economy sees companies engaging contract workers for a temporary period rather than hiring them for permanent positions.

    Simply put, the gig economy is a free market system in which companies – from small businesses to larger organisations – collaborate with independent contractors, project-based workers, part-time employees and freelancers.

    This segment of the economy is gaining popularity among the younger generation, especially millennials and Gen Z, simply for the fact that it provides them with dynamic flexibility towards their time management and encourages specialisation to provide specific services in accordance to their interests or talents.

    The gig economy has experienced a growth trend in recent years whereby about 25.3% of the Malaysian workforce in 2018 comprised freelancers, according to World Bank data.

    “This number is growing, thanks to the rapidly available platforms which act as intermediaries between independent workers and consumers,” Wealth Vantage Advisory certified Islamic financial planner Nuraishah Hanani Abdul Ghani.

    Nuraishah Hanani

    Not just about flexibility and freedom

    While being a gig employee offers great flexibility and freedom in terms of working hours and the people that you work with, the downside is that gig employment does not promise a fixed salary, says Blueprint Planning licensed financial adviser Gunaseelan Kannan.

    The other important implication is that the high instability of income will have a direct impact on their investment engagements, he adds.

    “Gig employees should understand the investment risks, investment time horizon, and the terms and conditions on the withdrawal of investments. In general, high liquid investments should be adaptive to an individual who is active in the gig economy,” he explains.

    According to Gunaseelan, the fact that gig employment does not provide Employees Provident Fund (EPF) contributions will also have severe implications on one’s retirement funds.

    Gunaseelan Kannan

    “Taking the initiative to make personal contributions to EPF is a good idea for gig workers as EPF currently allows investments of up to RM60,000 annually for this group of individuals.”

    Moreover, gig workers are also at the mercy of market risks and fluctuating economic conditions, licensed financial adviser Gor Sheau Shuenn chimes in.

    Gor further points out that the irregularity of income presents gig workers with a limited opportunity for investments as they are more likely to put their income aside for when they are in between projects.

    “In addition to EPF, the lack of Socso contributions and possibly, retirement savings and medical insurance as well may leave gig employees in a tight spot during rainy days or when they retire,” he adds.

    A right mindset is needed

    As to how gig workers can overcome these problems, Gor reveals that having a personal cashflow budget is important. “You should be clear how much money you need to put aside for investment, how much money you can spend, and what you spend your money on each month.

    “Next is an investment objective: will you be investing your money for retirement, for a property down payment, or for a college fund for your children?

    “Knowing how much money is needed in the long term and breaking it down to monthly, quarterly or yearly saving targets is a good practice. Once your priorities are clear, you can then work towards that goal,” he advises.

    Gor Sheau Shuenn

    Wealth Vantage Advisory’s Nuraishah concurs. “Because gig workers do not receive a regular salary, millennials who are engaging in the gig economy might face problems with their instalments which can affect their credit rating if the matter goes unattended in the long run,” she adds.

    Therefore, a detailed approach with the right mindset must be adopted to prevent the issue from ballooning up, which may eventually disrupt one’s financial stability.

    “The very first step to achieve this is by determining and strategically splitting your finances into different categories, namely basic needs, expenses, forced savings and investment allocations.

    “That way, you will always have extra money to carry forward into the next month in the event of low gig demands,” explains Nuraishah.

    Diversify your income

    With the immense freedom and flexibility of the gig economy comes the great responsibility of taking charge of your own financial future. And no doubt investment is probably a stressful topic for anyone involved in this segment of the economy.

    Nuraishah says a good first step is to start building an emergency saving fund immediately.

    “As a gig worker, millennials are more susceptible to financial hardship as compared to those who have to miss work due to an emergency.

    “In contrast to salaried workers, they do not have health coverage or other forms of protection at work, and it is critical they have enough money saved up in case of an emergency, in addition to having excellent coverage of term life and health insurance,” she explains.

    While it might seem like an obvious suggestion, Nuraishah suggests one of the keys to achieving financial success in the gig economy is for millennials to think like a business person and plan accordingly – and this means getting into the habit of keeping themselves accountable for their expenses.

    “Diversifying their income, meanwhile, may come naturally as they delve further into the gig economy, and for freelancers, this move becomes essential to achieving financial success.

    “As the nature of work in the gig economy is temporary, diversifying your income as much as possible is important to keep their financial and business plan on track.”

    Despite the lack of a fixed salary, Nuraishah believes it is not impossible for gig workers to have the upper hand in terms of investment.

    “In comparison to the regular working concept, millennials who have opted to join the gig economy are not restricted to the 9-6 routine which is rigid and repetitive with little to no opportunity of generating additional cashflow beyond what had already been agreed upon.

    “Thanks to the dynamic concept practised in the gig economy, gig workers are their own managers, and they alone can decide where their money ought to go to. For this matter, it is very crucial that they have a clear financial goal, which needs to be practical and yet, feasible to achieve.

  • Analysis: A Bright Spot for ASEAN Economies

    Analysis: A Bright Spot for ASEAN Economies

    Global trade volumes topped out in 2018 amid slowing global growth and ongoing trade tensions between the US and China. In 2020, the global pandemic has been another headwind for global trade. What about ASEAN economies?

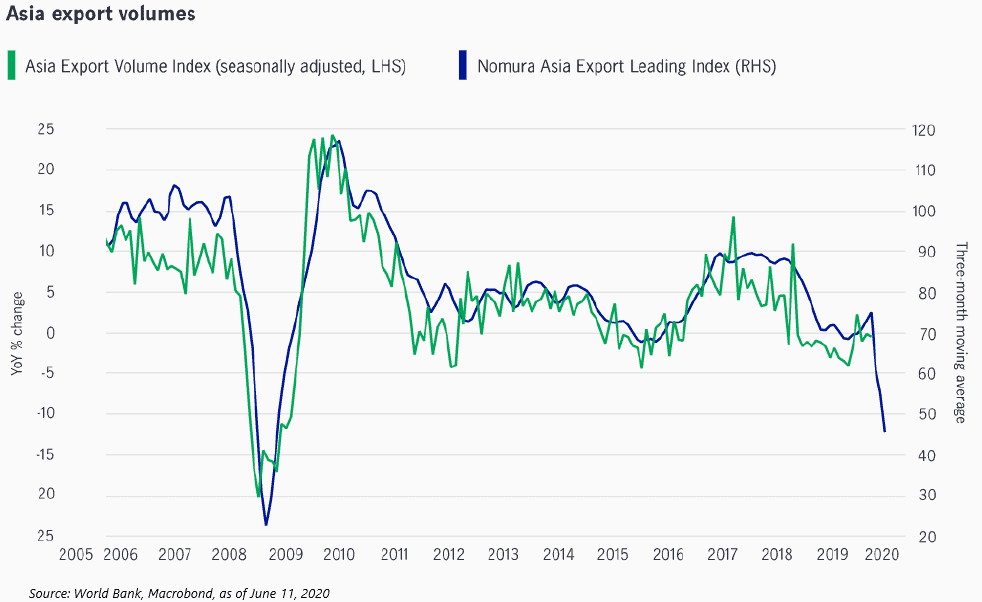
    Nomura’s leading index of Asian exports, which aggregates the region’s exports (excluding Japan) of eight forward-looking components, and typically has a three-month lead, is signalling that aggregate export growth in the region could shrink between 10% to 20% (relative to last year) in the coming months.

    Further downside risk to global trade comes from the worsening relationship between the US and China and the potential for a reescalation in trade tensions. Understandably, this backdrop makes for a difficult environment for Southeast Asian economies – specifically, members of the Association of Southeast Asian Nations (ASEAN), a group of highly trade-dependent economies.

    That said, how the region weathered challenges in the past two years has given us some confidence in its ability to navigate the current environment.

    The News isn’t All Bad

    The Asean region has been a big beneficiary of ongoing trade tensions, the global pandemic, and China’s relatively early emergence from the Covid-19 outbreak.

    The region’s share of global trade has gone from strength to strength since 2000, with trade in electronics and integrated circuits being a major driver.

    When the US-China trade war started to escalate in early 2018, there were fears that slower global trade growth would negatively impact the trade-dependent region.

    But as events unfolded, it became clear that China looked increasingly to Asean to offset the impact of the trade war – and later, the Covid-19 outbreak – to counter the rise of increasingly stringent US trade policies.

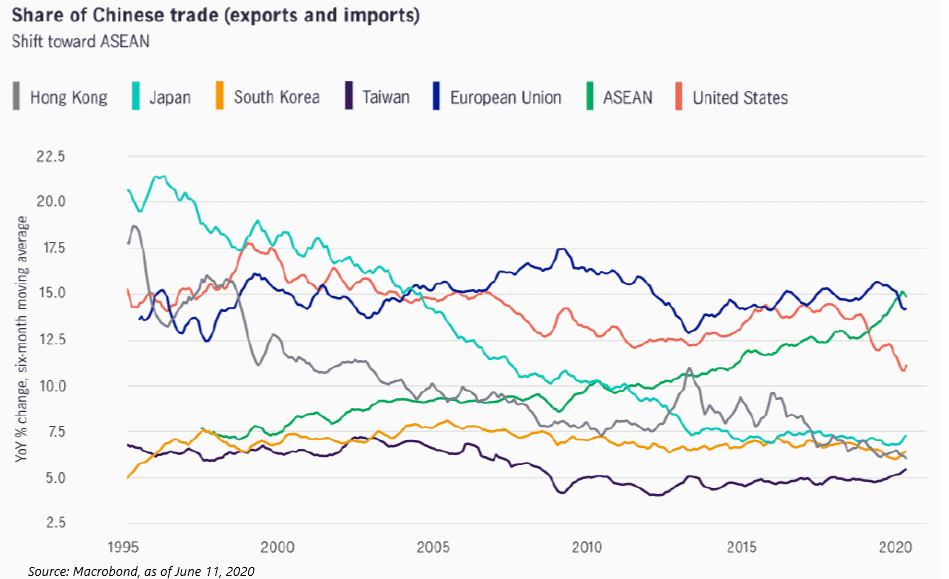
    Asean’s share of Chinese trade (exports plus imports) overtook that of the US’ in early 2019. But it didn’t stop there – in early 2020, Asean overtook the European Union as China’s largest trading partner and its share of trade with China remains near a record high of around 15%.

    The ASEAN region has attracted many global companies that are looking to diversify their production in the wake of the US-China trade war, and the Covid-19 outbreak has accelerated that trend.

    The development is understandable – Asean sports many competitive advantages, among them, its member countries’ relatively high rankings in the World Bank’s Ease of Doing Business Index.

    The Asean-6 (namely, Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam) all sit within the top half of global rankings across 10 areas of doing business – starting a business, dealing with construction permits, getting electricity, registering property, getting credit, protecting minority investors, paying taxes, trading across borders, enforcing contracts, and resolving insolvency.

    Other advantages that the region has over its competitors are: relatively lower-wage structures, better productivity, and geographic proximity to China. The fact that the region has a complementary industrial structure to China is also important.

    As China emerges from Covid-19, the gradual recovery in consumer demand in the country is being met by ASEAN. Vietnam, Malaysia, and Thailand have enjoyed particularly strong growth in demand for their goods from China.

    In our view, sectors that are likely to benefit as the Chinese economy kicks into gear include mining (benefiting major producers from Indonesia and Malaysia), semiconductor and electronics (benefiting Thailand, Malaysia, and Vietnam), and textiles and garment industries (benefiting Vietnam and Thailand).

    Important Mitigants in a Challenging Environment

    An acceleration in Asean integration in the coming years is likely to make the region even more competitive and resilient to global shocks.

    This could be achieved by reducing tariffs, improving market access, and increasing the region’s absorptive capacity further.

    The Regional Comprehensive Economic Partnership, a proposed regional free trade agreement that’s currently being negotiated, could go a long way to expand regional connectivity in trade and investment. Proponents of the agreement hope that negotiations can be concluded by the end of the year.

    On balance, even though the leading indicator for Asian export growth is warning of a major slump ahead and geopolitical risks remain elevated, there remain many positive dynamics at play that can serve as mitigants in a challenging environment.

    By Sue Trinh

    Sue Trinh is a senior macro strategist at Manulife Investment Management, a leading global asset manager, with investment expertise extending across a broad range of public and private asset classes, as well as asset allocation solutions.

  • Analysis: The World after the Flood of Fiscal Stimulus

    Analysis: The World after the Flood of Fiscal Stimulus

    The global fiscal stimulus tap has been unleashed to fight the impact of the COVID-19 outbreak. We think the impact of this stimulus is binary and, if sustained, it could break the decade-long disinflationary cycle.

    In contrast, if austerity measures are subsequently imposed, the era of low rates and low inflation will likely continue for the foreseeable future.

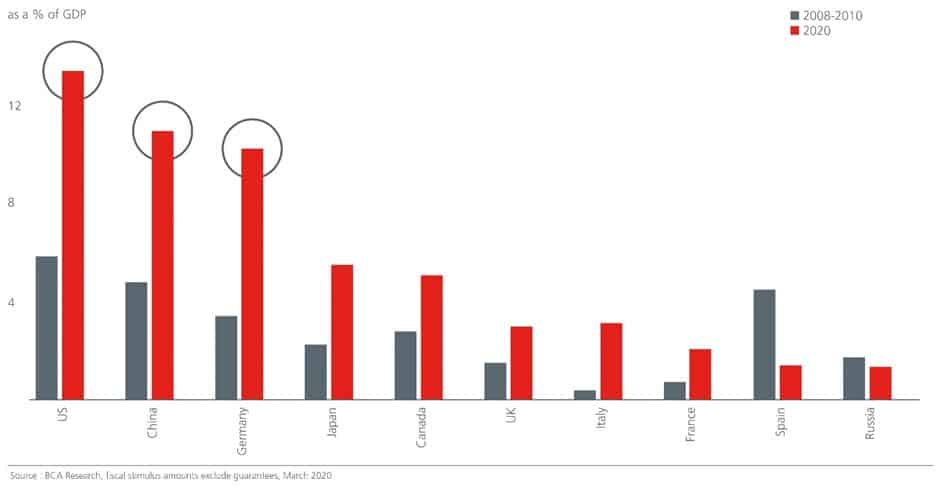
    The combined scale of fiscal and monetary response has been massive – estimated to be around US$17 trillion at the time of writing. The quantum of stimulus provided this year is also significantly higher than the 2008 Global Financial Crisis (GFC).

    This is not surprising since monetary policy has far less wiggle room now. Moreover, the pandemic is not due to bad economic decisions; there will be little backlash on governments supporting affected sectors (e.g. airlines, banks, small retailers etc.).

    Although we saw countercyclical fiscal stimulus after the GFC, it was followed by significant austerity measures as governments were worried about the inflation implications of quantitative easing (QE). But inflation never returned.

    The past decade has demonstrated the effect of loose monetary policies: negative interest rates, flatter yield curves, low inflation, accumulation of corporate debt, and narrowing credit spreads, among others. But we have little experience of knowing the combined effects of expansionary fiscal and monetary policies on economies and markets.

    Fig 1: Global fiscal stimulus exceeds 2008

    A Powerful Twin Policy-mix

    A key difference between monetary and fiscal policy is that while monetary stimulus creates a large positive liquidity shock, it requires households and companies to be willing to take on debt and spend. On the other hand, fiscal spending adds directly to aggregate demand with no private sector debt build-up.

    Large unemployment benefits and “helicopter” money are windfall gains to consumers and leave no debt behind. If the stimulus is directed towards public capital expenditure which ultimately increases economic growth and creates jobs, it would eventually crowd-in private spending and the multiplier effects would fuel higher growth.

    Recent fiscal packages have focused on mitigating the initial impact of COVID-19. When the second-round of impact hits i.e. higher unemployment, corporate defaults and bankruptcies, more fiscal support will likely be announced.

    Of course, if these stimulus packages prove to be one-off and governments hit the pause button on the deficits or actively seek to reduce it, the medium-term implications will likely mirror the conditions post GFC.

    However, if countries see renewed waves of COVID-19 outbreaks, unemployment rates may stay elevated for a number of years. Against this backdrop, and with demographics not in favour for many developed and some emerging markets, countries that have limited binding constraints will probably continue to run large deficits.

    The Fiscal Divergence

    There will likely be divergences in the impact of fiscal stimulus on developed markets (DM) and emerging markets (EM). DM economies that have the benefit of low rates, low external debt, and low inflation can afford to keep monetary and fiscal policy easy, facilitating the cycle of higher demand, higher inflation and steeper curves.

    But not all DM economies are in the sweet spot, particularly within Europe where monetary and fiscal policy do not work in tandem; certain countries may only be able to announce stimulus with constraints.

    However, within EM economies, there are potentially two groups – one which does little fiscal stimulus to start with given their prudent approach, and one that continues with fiscal stimulus despite weak external balance sheets and therefore potentially face vulnerabilities in their foreign exchange and bond markets.

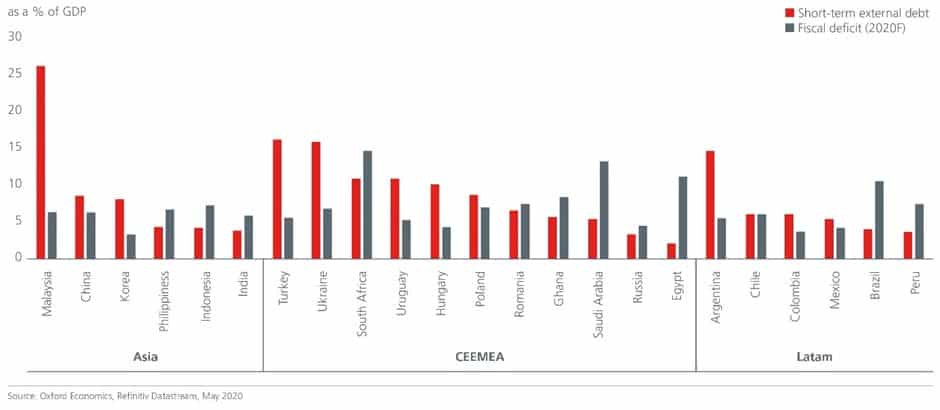
    Looking at the EMBI universe, CEEMEA (Central & Eastern Europe, Middle East and Africa) countries stand out as being the most vulnerable as they have higher short-term external debts and are expected to run large fiscal deficits this year.

    These economies indulging in fiscal extravagance may face sovereign rating downgrades, spike in bond yields, and steeper yield curves, and eventually be forced to undertake austerity measures. EM Asian economies appear as relatively stronger, with most having short-term external debts lower than 10% of GDP, with the exception of Malaysia.

    While rising fiscal deficits are bringing debt sustainability questions to the fore, it is important to highlight that debt issuances are a problem mainly when interest rates are higher than nominal GDP growth. If interest rates remain low (as they are now) and fiscal spending leads to higher growth, then debt/GDP ratios might fall or at least remain steady.

    Fig 2: EM Asia appears to be better placed

    Inflation or Disinflation?

    Sustained fiscal deficit, combined with synchronised monetary stimulus may eventually break the decade-long disinflationary trend. Adding to this tailwind to inflation is the potential negative supply side shock driven by the end of globalisation and the reversal of supply chain efficiencies.

    This scenario can be thought of as being akin to the post World War II period; after the negative demand shock and low inflation, the US economy saw a sharp rise in inflation led by stimulus, eventually forcing monetary policy to tighten substantially.

    The process may be more gradual this time; it will take a while for the current economic slack to narrow. Besides, structural changes such as more remote working and less demand for business travel and commercial real estate will likely dampen inflationary pressures.

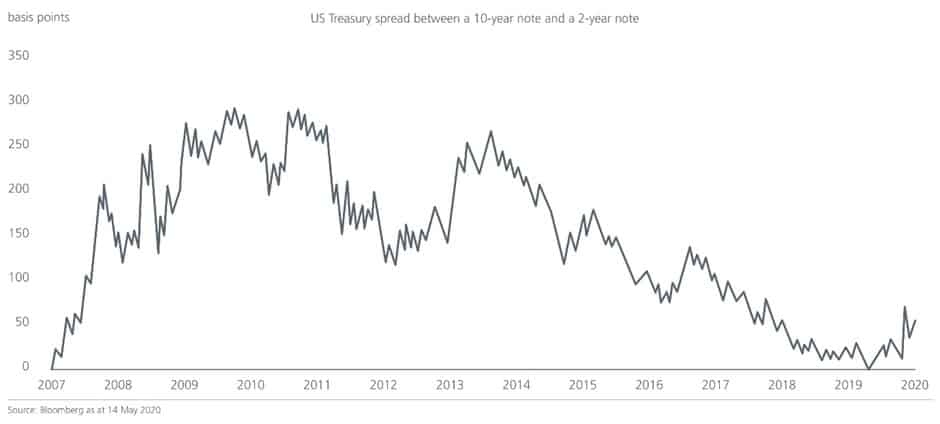
    There are several market trends that have relied on subdued inflation expectations. First would be the impact on the yield curve. Post GFC, the yield curve steepened significantly as fiscal policy eased, but reversed as soon as austerity measures kicked in. Yields have fallen substantially since and yield curves flattened as inflation expectations have plummeted and monetary policy has remained easy.

    Fig 3: Yields have declined substantially since GFC

    However, this trend may reverse – a spike in US treasury yields and a steeper yield curve is possible if the fiscal stimulus sustains. This in turn would have positive repercussions on rate-sensitive equities, particularly financials and other ‘value’ sectors.

    Binary Outcomes

    The risk of higher interest rates also implies that policymakers need to strike the right balance. Too swift a rise in yields could increase the debt burden and complicate refinancing issues for governments. Equally, rising inflation with no change in nominal rates could impede central bank credibility.

    Central bankers over the past few decades have allowed market participants to price in appropriate risks and maintained stability in bond markets, in particular.

    However, if central bank actions begin to differ from their stated objectives due to other interests, market participants will find it difficult to accurately price in various scenarios, leading to lower market confidence, higher market volatility and hinder price transparency.

    But in today’s situation, central banks may be forced to maintain accommodative policies for longer periods to maintain the solvency and liquidity of the government, keeping front-end rates well anchored.

    If this were the case despite rising inflation, real rates would decline even further, and wealth transfer would take place from savers to borrowers. From an asset allocation perspective, this would imply greater weight on equity over bonds in portfolios in order to meet stated investment objectives.

    In our view, the unprecedented fiscal stimulus we have seen post-COVID-19 can lead to binary outcomes. If the deficits sustain, the world will evolve more akin to post-World War II with higher demand, higher inflation expectations, and steeper yield curves.

    Alternatively, if governments are forced to impose austerity measures once demand returns to normal, as with post-GFC, then the era of low rates and low inflation will continue for the foreseeable future.

    By Nupur Gupta

    Nupur Gupta is multi-asset portfolio manager Eastspring Investments, Singapore. Part of Prudential plc, Easpspring Investments is a global asset manager with Asia at its core, offering innovative investment solutions to meet the financial needs of clients.

  • Building a Thriving Online Business

    Building a Thriving Online Business

    Malaysia’s e-commerce industry is expected to continue its upward trajectory and rapid growth in 2020 and for many years to come.

    As an aspiring entrepreneur, the opportunity to ride on the sector’s coat tail is an intriguing and exciting one. Whether you have already launched an online business on one of the e-commerce platforms or are looking to get involved in your very first venture, now is the time to get your foot in the door.

    Indeed, data from German online statistics portal Statista reveals that Malaysia’s e-commerce market for 2019 generated a whopping revenue of US$3.68 bil (RM15.2 bil), with a prediction for annual market growth to reach 11.8% by 2023.

    DataReportal, meanwhile, revealed there were 26.69 million internet users in Malaysia as at January 2020. The number of internet users in the country increased by 919,000 (+3.6%) between 2019 and 2020, while internet penetration in Malaysia stood at 83% as at January this year.

    Source: Datareportal 

    Mapping E-commerce Growth

    For perspective, Shopee led the industry with the highest consumer downloads of its mobile application, according to iPrice Group Sdn Bhd’s Map of E-commerce report for the third quarter of 2019 (3Q19). The e-commerce platform also tops the list of the most visits to its websites at 25,789,300 monthly web visits.

    As for Lazada, the e-commerce platform had the highest number of monthly active users of mobile application in 3Q19, while breaking into the top five list of most visited websites is PG Mall, a homegrown online shopping mall.

    With technological advances and not to mention the growth of the internet economy, the e-commerce industry is set for an exciting ride in the next few years.

    E-commerce Malaysia chairman Ganesh Kumar concurs, saying the local e-commerce industry is expected to grow up to 30% in 2020, supported by advancement in technology and wider access to virtual buying platforms.

    “Currently, we are seeing more people buying online and trusting e-commerce sites. More merchants are also starting to sell their products online,” he said recently.

    Fast-changing E-commerce Landscape

    In the era of Industry 4.0, technological advances have had a massive impact on the e-commerce industry, transforming the way consumers connect with brands and empowering them to shop more cost-effectively.

    Driven by the convenience of making purchases without the need to visit a physical store, e-commerce has now become an integral part of everyday life. But while the shift in consumer behaviour is a given, businesses, too, are adopting a changing mindset when it comes to e-commerce.

    “Rather than seeing e-commerce as a competition, businesses have now come to see it as another stream of revenue which will complement their brick-and-mortar business,” Shopee regional managing director Ian Ho (pic) tells Smart Investor.

    These businesses, to cater to the increasing demands of today’s e-commerce landscape, have set up dedicated e-commerce teams to manage various facets of their operations.

    This includes manning the online store, pricing, handling orders, fulfilment, and customer service, as well as investing in warehouses that come equipped with advanced systems to organise warehouse operations.

    Evolving mindset aside, many businesses however find it difficult to grow their sales effectively after opening a store.

    “This is because of operational and marketing challenges. These businesses lack the know-how to nurture the business and run marketing efforts to increase exposure for their online stores and product offerings,” Ho reveals.

    Helping Hand from Shopee

    In Shopee’s case, the e-commerce platform has empowered many brands and sellers to succeed online because they understand the challenges that businesses face, and offer various forms of support to help them succeed.

    For example, Shopee University, a free seller’s workshop to provide sellers with the knowledge and skills to grow their businesses on the Shopee platform, was launched in 2016.

    From the workshop, participants will learn multiple ways to boost sales; tips and marketing techniques to promote their store on Shopee; the right way to list products; and how to fully utilise all of Shopee’s features to help promote sales.

    “What has made these workshops even more resourceful is that they are also available through web seminars, which means that participants anywhere with an internet connection can join in,” shares Ho.

    To date, around 10,000 sellers have benefited from the Shopee University modules.

    In addition to Shopee University, the e-commerce platform further launched Shopee Live in 2019 in an effort to bring users closer to their favourite sellers and brands.

    This allows brands/sellers to engage their users throughout the shopping journey via a wide array of live content such as product reviews, guides and demonstrations hosted by popular local influencers.

    And the results are pretty impressive, to say the least. Tyra Kamaruzzaman’s Beautyra lipsticks, for instance, sold out in minutes on Shopee Live, recording over 2,000 orders, while Photobook’s store traffic and visibility increased by 18x after running a 45-minute live stream on Shopee Live.

    “In addition to driving orders, Shopee Live is also effective in driving traffic and followers to the retailers’ stores, as indicated by Shopee seller wanjojo of JJ70 Store who gained more than 800 store followers after a single live stream.

    “Another seller also shared that by doing daily live streams, he was able to rapidly gain followers and double his sales in less than three months, with 2019 being the first time he had managed to break the RM1 mil mark in annual sales,” Ho shares, adding the results are testament to Shopee Live’s success.

    Success: an effort of both parties

    Over the years, many businesses have achieved success on e-commerce platforms, but many others have also not done well. So how does a business guarantee its success online?

    PG Mall managing director Datuk Wira Louis Ng believes that success on e-commerce platforms stems from the effort of both parties, namely the platform operator and the merchant.

    “Successful merchants on the PG Mall platform put in a lot of effort from their end to build store awareness and visibility by participating in all PG Mall-related activities and campaigns.

    “In addition to providing attractive prices, these merchants are very committed, have zero cancellations rate, are very responsive to shoppers’ enquiries, and are efficient in processing orders to ensure a positive shopping experience.”

    On the flipside, there are merchants who – after setting up their online store – solely rely on the platform to drive sales without going all out and taking the initiative to do more, he adds.

    Merchants on the PG Mall platform are supported with regular creative campaigns that partner with different e-wallets and banks to drive both sales and traffic to the stores.

    PG Mall is also the only platform to partner with all major e-wallets in the country. The vast check-out options available will in turn gives merchants a boost in capturing more shoppers.

    On how merchants can conduct a successful business on PG Mall, Ng points out that PG Mall’s mission is to be the number one choice when it comes to online shopping, and therefore, it is always best for merchants to feature all products on hand to be available on the PG Mall platform.

    “Providing a fair price for shoppers is essential, as is the effort put into managing the store by putting up clear and attractive images as well as the right product descriptions.

    “While Success on e-commerce platforms stems from the effort of both parties, namely the platform operator and the merchant. these may sound trivial, these are factors that will influence a shopper’s final decision.”

    The homegrown e-commerce platform, which cites gold jewelleries, groceries and pets, as well as home appliances as its current best-performing categories, are in the midst of bringing in more brands to join the PG Mall family.

    Trusted Delivery Service

    Delivery service is a crucial aspect of online businesses, as it allows for the efficient and timely transportation of goods to customers.

    In today’s world, customers expect fast and reliable delivery, and the ability to track their orders in real-time. This is especially true for e-commerce businesses.

    Use Delyva as your main delivery platform that allows you to choose the best delivery service in Malaysia by price, speed, area coverage and reliability.

    By Bernie Yeo

    Find out more about Delyva here: https://delyva.com/my/delivery-service-in-malaysia/

  • Under the Influence of Social Media Influencers

    Under the Influence of Social Media Influencers

    Do you know of a life without social media? Better still, do you remember a life when there was no Facebook, Instagram, Twitter, WhatsApp, Snapchat and TikTok? Or influencers?

    Social media has grown to become one of the most dynamic developments in digital media over the past two decades. With billions of users worldwide, social media is now a huge aspect of modern society and has a tremendous impact on our culture, on business, and the world at large.

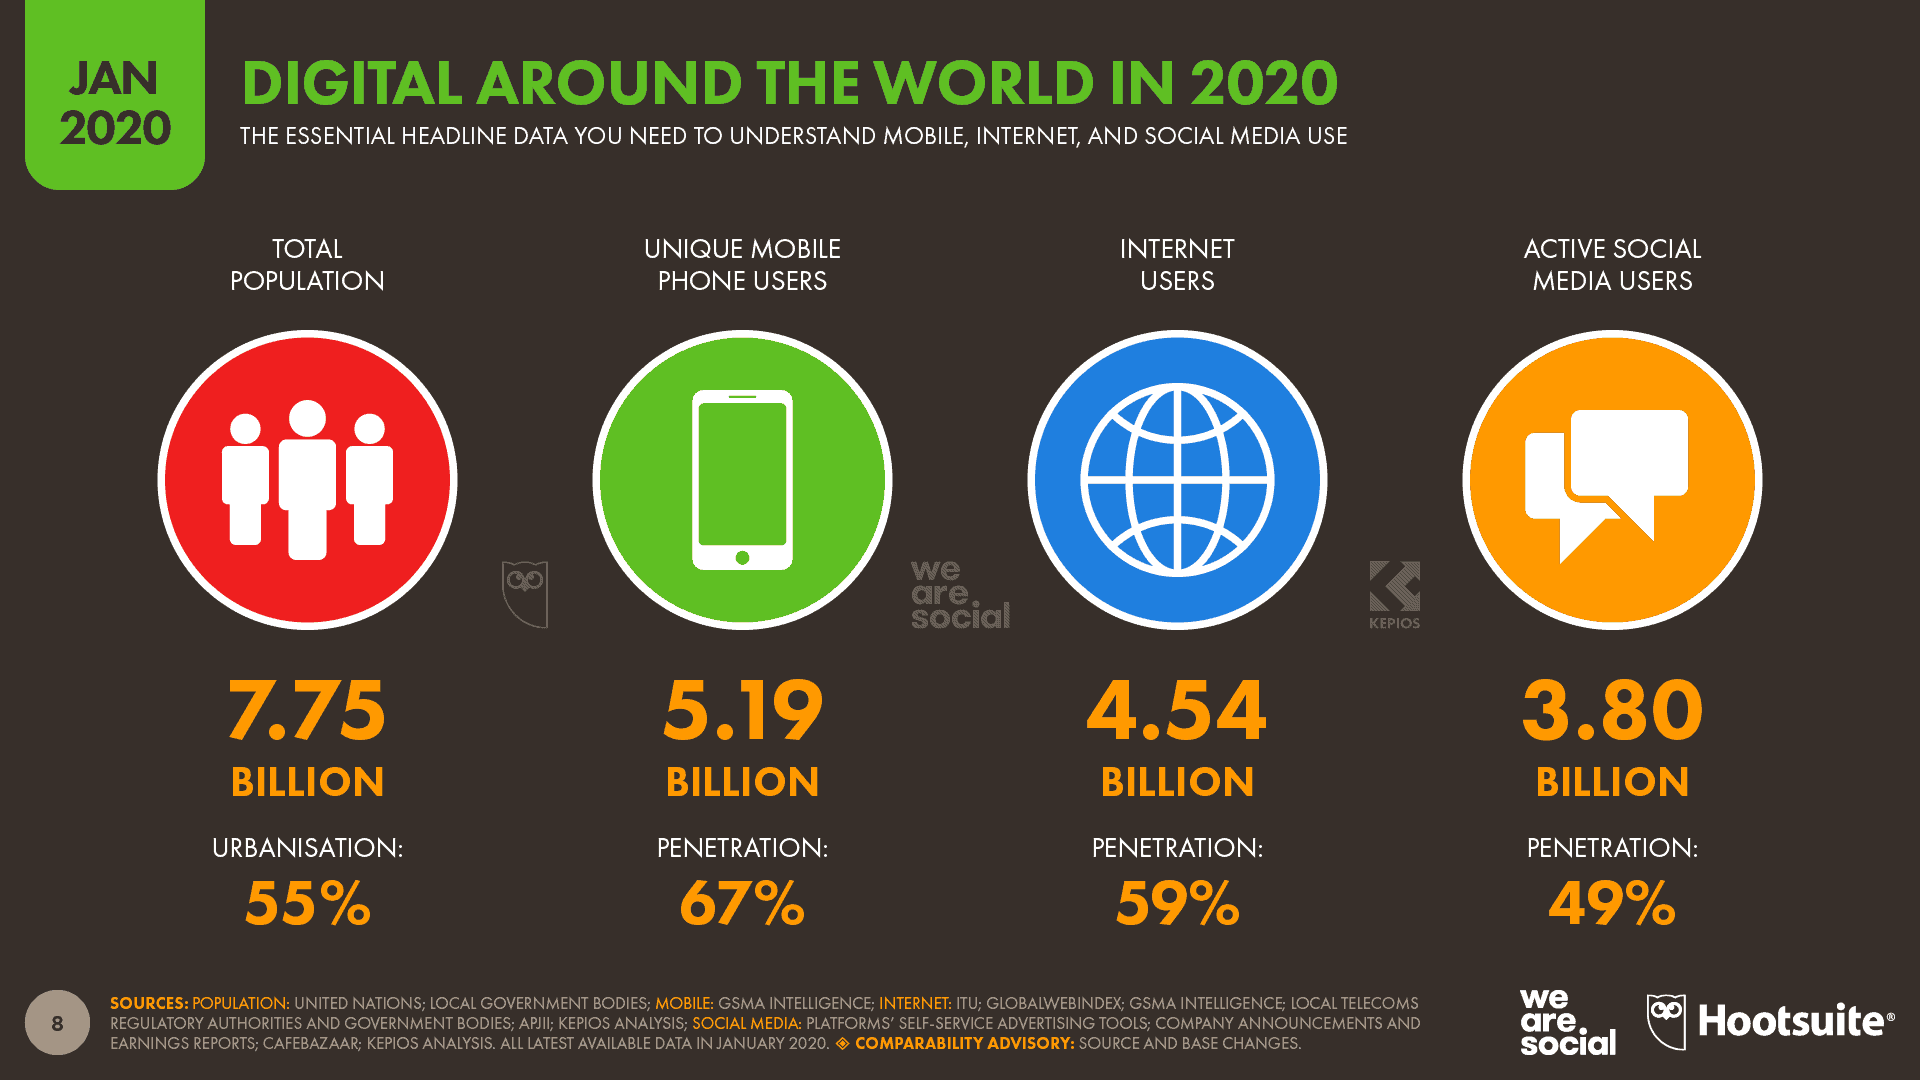
    Digital 2020, a collection of reports on digital trends and social media uses, reveals that as at January 2020, there are 3.80 billion active social media users in the world against a total population of 7.75 billion.

    Source: We Are Social Inc.

    Understanding the modern consumer

    There was a time when it was not possible to share your opinions about a specific product with others because there simply was no available outlet, and there was no way of reviewing a product or service except with a few family members, close friends and coworkers.

    Consumers today enjoy a very different situation, all thanks to social media. Through platforms like Facebook, Instagram and Twitter, consumers have been able to easily convey their opinions about various brands.

    In other words, there is now an opportunity for consumers and brands to build a working relationship in which opinions can be voiced and views exchanged.

    “The modern consumers want to interact and engage more with brands. Consumers want to speak with brands, and not be spoken to,” opines Karen Ong, Luxasia Group regional managing director (Singapore, Malaysia, Thailand and Vietnam) & country manager (Singapore).

    So for brands to be successful, it has to be a two-way communication between them and their consumers as this is how the latter prefers to communicate – they go directly to the brands to express their preference.

    Luxasia is the leading omnichannel partner for more than 140 luxury beauty and lifestyle brands including Bvlgari, Hermès and Prada.

    The growth of influencer marketing

    The use of influencer marketing has grown rapidly as consumers are already using social media platforms to follow influencers who create content according to a certain category or theme.

    What is interesting to note is that global ad spend on influencers, according to Business Insider Intelligence, is predicted to reach between US$5 bil and US$10 bil by 2022. But why is this so?

    The reason is simple, say Ong and Luxasia Group country manager (Malaysia) Cindy Poh. “Brands leverage on the trust and relationship these influencers have built with their follower base, who are very likely to be captive audiences and are interested in reading and hearing what these ‘key opinion leaders’ (KOLs) have to say about a brand.”

    They note that influencers create content that adds personalised touches in a way that mass media is unable to replicate. And it is through these personalised contents that the influencer is deemed a credible and authentic source as the content that he/she creates for the brand is aligned to the influencer’s personal brand.

    “A PwC Study in 2018 found that today’s consumers are more responsive to credible, authentic content and opinions from someone they know or trust on social networks, suggesting that opinions and suggestions on social media – posted by friends and strangers alike – have more influence on specific purchase decisions than factors that retailers can control, such as advertising, promotions, and pricing,” they explain.

    One good example of influencer marketing is YouTube celebrity PewDiePie’s collaboration with the makers of a horror movie set in the French catacombs under Paris in conjunction with the upcoming movie As Above, So Below in 2014.

    Renowned for his histrionic reactions to horror movie games, the Swedish YouTube celebrity agreed to undertake the ‘Catacomb Challenges’ where he would give his reactions to a recreated version of the movie’s setting.

    The resulting two-part video series was the perfect content for PewDiePie’s millions of subscribers, and received almost double the views of the movie’s trailer. It was, suffice to say, a win-win situation for everybody.

    An influencer’s perspective

    An influencer can be anybody from a popular fashion icon on Instagram to an indie wedding singer who blogs to a well-respected political figure who tweets. What makes them influential is their large followings on the web and social media.

    The shift to influencer marketing started about six to eight years ago first on banner ads on a digital medium to blogs (seen as a form of online media) before reaching social media platforms like Facebook, Instagram and Twitter, says local blogger, speaker, columnist and TV host Dr Choo Mei Sze.

    Choo, who holds a PhD in Development Psychology from the University of Hawaii at Manoa, is the Youth Ambassador for the National Cancer Society of Malaysia (NCSM).

    She advocates cancer awareness especially among youths through talks and youth support groups in collaboration with NCSM and has hosted a show called ‘An Awakening’ in collaboration with insurance company Axa Affin Life Bhd which showcases amazing stories of cancer patients, survivors and caretakers. Today, she blogs about her journey with the Big-C, in addition to topics on fashion, beauty and travel.

    “When I first came back from the States about eight years ago, I was surprised that many brands asked to advertise on my blog. At that point of time I was blogging as a way to connect with my friends and family and I didn’t imagine it being a form of advertising,” Choo tells Smart Investor.

    “These days, influencers are the new ‘word of mouth’ and brands prefer this form of advertisement as it allows them to see exact figures rather than made-up ones like on billboards.”

    Getting into the business

    But how does a person get into the business of becoming an influencer?

    “With the market being so saturated these days, anyone can be an influencer. Nowadays, an influencer is all about being able to influence enough people through the posts you put up on social media be it in the form of pictures or captions.

    However, I believe that a true influencer is someone who is able to encourage their target audience to purchase a product or share a posting though a shout-out,” Choo opines.

    As for who to collaborate with and the products she recommends on her social media platform, Choo admits she is rather picky.

    “My followers are urban and quite a few of them know their stuff and so, I refrain from endorsing brands that do not suit me and my personality.

    “As the Youth Ambassador of NCSM, a lot of people ‘follow’ me for health and cancer advice as well as for inspiration, and therefore, I will not promote things like cigarettes or alcohol.

    “I am careful when I choose the brands I collaborate with, and I collaborate with companies promoting organic skincare or healthy eats as these are the things that I actually use and practise on a daily basis.”

    This brings us to the next question: how much are influencers paid to post photos of a specific brand’s clothes, watches, jewellery and make-up on their platforms?

    According to SLPR Worldwide Group chief operating officer (Southeast Asia) Leon Tang (pic), remuneration usually comes in the form of an in-kind or a monetary token as a form of appreciation towards the influencer’s efforts.

    “Influencer marketing does not necessarily always involve monetary contributions or sponsored contents. It depends on the brand affinity the influencer has for the brand and whether the promoted products/services bring values to the audience of the particular influencer,” he says.

    As such, he adds, there are numerous cases whereby the influencer finds the brand to be of great value to their audience and are therefore more than happy to share the brand’s products/services at no cost whatsoever.

    In instances like these, the influencer will be offered a product sponsorship as a token of appreciation.

    “The exact value is not fixed and differs from influencer to influencer, although this is usually decided by both the brand and the influencer.

    “There are, however, some influencers who are employed under a specific talent agency and as such, already have a company-set rate card in place. The rates are usually determined based on the number of followers or the engagement rates per post,” explains Tang.

    No one-size-fits-all

    ‘Matching’ a brand to an influencer – and vice versa – is also an important element to be considered when it comes to getting influencers involved in a brand’s campaign.

    Among the factors to be considered include the number of authentic followers, the number of legitimate engagements in a post, demographics of followers, the track record of the influencer, his/her connections to other influencers, budget and the fit between the influencer and the brand in terms of the look, the styling, the ‘feel’ and even the use of linguistics.

    In Luxasia’s case, the process involves getting the right influencer whose profile fits the brand it carries. As simple as this may sound, however, the details involved in the selection of influencers is a complex one.

    “The challenge of a regional beauty business is in local marketing knowledge, effectiveness, and execution. Different markets have different platforms of choice, and hence different ways of doing influencer marketing.

    “This is also the very reason why Luxasia has so many local offices – we need to know the market locally and intimately to be effective,” explain Ong and Poh.

    “Before we address influencer selection, we need to be clear about social media platform selection. Instagram is the go-to social media platform for all things that are beauty-related.”

    Weighing in on the onboarding process, SLPR’s Tang adds: “A detailed background check on the influencer will be conducted before initiating a conversation with the influencer. The screening and selection process usually take around seven to 14 working days.”

    This will be followed by a meetup and if they are interested to be part of the campaign, remuneration and collaboration tokens will be discussed, he points out.

    In some Southeast Asian markets like Vietnam, Facebook still reigns, while in Thailand, apps such as LINE can be an effective channel for social-commerce as well.

    Luxasia’s local office in China engages influencers on platforms such as WeChat, Weibo, Douyin, and the beautycentric social shopping platform Little Red Book (Xiaohongshu).

    “As such, there is really no one-size-fits-all. We need to identify the effective platform for the local market, followed by the influencers to engage. Furthermore, we need to determine the nature of the campaign – image-centric or video posts of ‘live’ KOLstreaming.

    “For some brands, it may also be more relevant to engage 30 micro-influencers as opposed to five macro influencers,” say Ong and Poh.

    By Bernie Yeo

  • Analysis: Digital Banking in Malaysia

    Analysis: Digital Banking in Malaysia

    According to KPMG’s latest report entitled , in a post-COVID-19 world, the financial services sector will be a key driver of economic recovery and growth. In particular, the stage is set for digital banking to thrive.

    KPMG Malaysia Head of Financial Services Adrian Lee observed how the changing socio-economic landscape has altered customers’ money management and spending patterns as well as the way businesses are run. For both individuals and businesses, mode of payments and channels of financial management will also change.

    “Recent customer behaviours in both retail and commercial sectors during the pandemic have evolved in support of digital banking services. As customers and businesses seek alternatives to safely run operations, the potential is great for digital banking to be the next success story for the financial services sector in Malaysia,” he said.

    “Digital banking presents a value proposition poised to help companies and individuals get back into the economic saddle, and financial services providers that design its products around customer needs will stand out the most,” added Lee.

    Bank Negara Malaysia (BNM) is due to announce its application guidance for the five digital banking licences following a public consultation of the updated exposure draft on the licensing framework for digital banks, which is due to conclude on 30 June 2020.

    Interests have already been stirring among the bank and non-bank institutions, ranging from credit businesses, telecommunications, e-commerce platforms, advanced technology companies and local conglomerates.

    Lee continued, “It is widely anticipated that BNM will see a large number of applicants for the five digital bank licenses in Malaysia due to the lower entry requirements in minimum capital and significant market opportunities locally and in the region.

    “Given the emphasis BNM has placed on financial inclusion, the successful applicants will be the ones that demonstrate how their products and services will help the underserved and unserved segments rebuild themselves financially.”

    According to KPMG’s Financial Services Advisory Partner and Head of Financial Risk Management Yeoh Xin Yi, a successful digital bank should incorporate three areas into its strategic blueprint:

    Understand customer behaviours and expectations

    KPMG in Malaysia conducted an online survey to understand customer appetite and concerns when it comes to digital banking.

    The study revealed that 77% of the 1,220 respondents in Malaysia believe digital banking is the next evolution in financial services, and 82% are already using internet banking functions of their banking service providers. It is interesting to note that 82% indicated they would consider opening a bank account through online platforms only if they were regulated by BNM.

    The survey also highlighted that 79% expressed interest in better accessibility to financing products, where 52% of respondents prefer to perform online application for these financing services.

    With the conditioning of using mobile or internet services during the MCO period, it is expected that familiarity with online registrations and onboarding will increase. KPMG’s survey also indicates that consumers are most concerned about cyber security and convenience of information uploading, hence this is one area that digital banks need to pay attention to when designing a good customer experience for users.

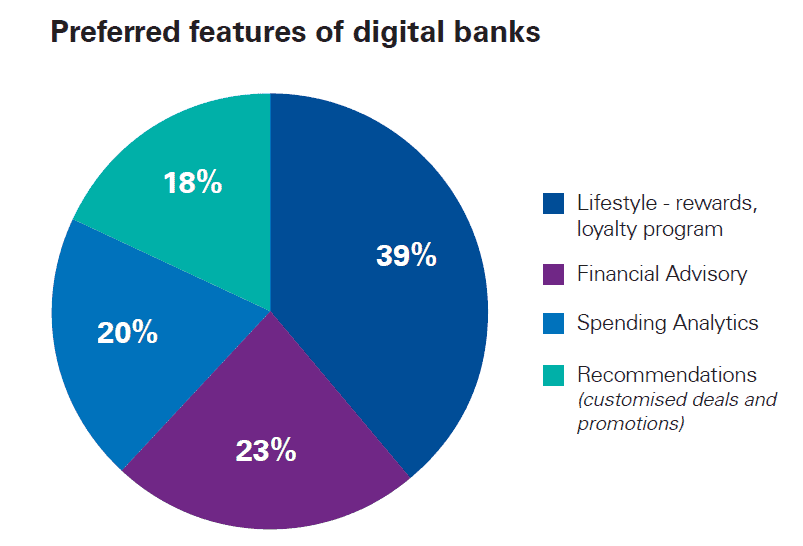
    On preferred features of digital banks, respondents appear to look forward to products and services that add value to their lifestyle (see chart below).

    Source: Survey on digital/virtual banking in Malaysia by KPMG Management & Risk Consulting, conducted from September 2019 to February 2020, involving 1,220 respondents in Malaysia.

    “Malaysian consumers are clearly ready and willing to embrace digital banking. It is up to the players to make the crucial step in establishing a customer-first model for digital banking,” said Yeoh.

    Banks, she continued, need to incorporate advanced analytics into understanding customer preferences and behaviour, from a historical as well as a forward-looking point of view. Information and data are key to providing customers with better products and services, thereby translating to economic value for the digital bank.

    Improve financial literacy and inclusion
    Despite there being more than 1,823 bank branches in Malaysia as of December 2019  and more than 37 banking institutions covering commercial banks, Islamic banks, and development financial institutions, there is still a lack of coverage for the unserved and underserved segments of the B40 and M40 groups.

    Yeoh commented, “Customers that fall into the unserved or underserved segments are more likely than others to have a profile that fall short of the conventional bank’s credit criteria when financing is sought.

    “Digital banks can view this as an opportunity to expand its reach into untapped markets while also delivering on BNM’s aspirations for financial literacy and inclusion. Ideally, we would seek to have customers achieve higher financial literacy through the provider’s ability to advise, recommend and encourage positive financial behavior.”

    For the unserved or underserved in retail and non-retail segments, micro-savings or deposits, micro-financing and micro-insurance are some of the basic products that is needed.

    These “bite-sized” products enable consumers to access affordable financial enabling services in manageable quantum, and introduces those who are financially unaware to products that can gradually improve their financial literacy and economic livelihood.

    The unserved and underserved of the B40 groups in Malaysia should be onboarded to financial service platforms that can help in cashflow management, enabling micro-savings or deposits, micro-insurance that safeguards their basic needs, and basic financing products to tide them over their financial trouble if the need arises.

    The underserved M40 and T20 segment can also benefit from the convenience and value add that digital banks can offer from a lifestyle and advisory perspective, with a different set of customized targets to help achieve their financial needs.

    Be an active platform
    Digital banks should be an active platform in the economic lifecycle of the segments it serves. It can do so by forming an eco-system or be part of an eco-system that is relevant to their users, where the user will be immediately plugged into a host of services within the digital bank platform.

    Yeoh explained, “For a micro-enterprise, for example, the platform would enable receiving payments digitally, purchasing materials via a marketplace, micro-savings and micro deposit auto functions, analytics for its business and personal finance, and basic micro-financing that commensurate with their financial behaviour and capacity as a micro-enterprise.”

    In conclusion, by leveraging on advanced technology, digital banks can fill the void that is within our economic environment and address the pain points of the unserved and underserved in both retail and non-retail segments.

  • Analysis: Property Market Expected to Bounce Back

    Analysis: Property Market Expected to Bounce Back

    As the nation endures its third week under the extended Movement Control Order (MCO), Malaysians from every walk of life face increasing uncertainty in the face of unprecedented sociopolitical and economic change.

    The impact of the MCO amid the ongoing Covid-19 outbreak on the Malaysian economy has yet to be fully realised. Conservative estimates forecast Gross Domestic Product (GDP) growth of 2.0% to 2.5% for 2020, while other analysts foresee domestic and global recession.

    However, PropertyGuru Malaysia, in line with its commitment to being the nation’s property advisor, anticipates corresponding effects on home seeker sentiment to be short-lived,with prospects for recovery in the near term.

    Bread-and-butter Issues Take Centre Stage 

    “Income and employment have been adversely affected by the closure of non-essential businesses during the MCO, and many Malaysians are prioritising bread-and-butter issues,” says Sheldon Fernandez, Country Manager, PropertyGuru Malaysia.

    Sheldon Fernandez

    “This dampened sentiment is likely to persist through to H2 2020, though measures such as the government’s Economic Stimulus Package (ESP) announcements and Bank Negara Malaysia’s (BNM’S) six-month moratorium on financing payments are laying the foundation for the market to bounce back.”

    Sentiment among home seekers was already in decline at the start of the year, with the PropertyGuru Malaysia Consumer Sentiment Study H1 2020 reporting a drop in the Property Sentiment Index to 42 points, down from 44 points in the corresponding period last year.

    This will likely see a fall in home loan applications, despite catalysts such as BNM’s recent revision of its Overnight Policy Rate (OPR) to 2.50%. Other markets experiencing Covid-19 outbreaks have seen mortgage applications drop by as much as 30%.

    Beyond these short-term impacts, research by property data analytics and solutions provider MyProperty Data Sdn Bhd underscores the property market’s resilience in the face of prior economic downturns and viral outbreaks, notably the severe acute respiratory syndrome (SARS) epidemic of 2002.

    The Resilience of Property

    While recent events have brought industries such as tourism and hospitality to a standstill, property transaction volumes and values have remained strong throughout periods of uncertainty (see Chart A).


    Chart A: Property Transaction Volume vs Value Growth (Source: MyProperty Data, NAPIC data)

    “The 1998 recession, in conjunction with the outbreak of the Nipah virus, saw volumes and values declining by 32.3% and 47.6% respectively, the largest downturn in recent decades,” says Fernandez.

    “However, the industry still moved forward, with 186,000 transactions worth RM27.9 bil. In addition, house prices as a whole have only continued to grow over the past few decades, highlighting the merits of property as an asset class.”

    According to the National Property Information Centre (NAPIC), the national house price index has not exhibited an overall decline since 1999, though its growth moderated to a low of 1.1% in 2001.

    In terms of property types, high rises exhibited the most volatility in prices from 1999-2009, from a high of 15.1% growth in 2003 to a low of –5.9% the previous year (see Chart B).

    Chart B: Malaysian House Price Index Growth (2000-2009) (Source: PropertyGuru Analytics, NAPIC data)

    From 2009 to 2018, this volatility spread to other property classes such as detached and semi-detached homes. Since 1999, terrace homes have shown the most stability and consistent price growth among property types, with prices in the segment growing by 6.5% in 2018 (see Chart C).

    Chart C: Malaysian House Price Index Growth (2010-2018) (Source: PropertyGuru Analytics, NAPIC data)

    As such, terrace homes will likely be a key focus for property seekers moving forward. This is supported by the PropertyGuru Malaysia Consumer Sentiment Study H1 2020 report, which found that terrace homes are the residence of choice (39%) among Malaysians.

    Locational Variations in Demand

    The aforementioned price trends were seen in the market as a whole, with variations in demand by area. For instance, MyProperty Data research shows that terrace homes emerged as the clear favourite in Greater Klang Valley from 1999 to 2004, in terms of transaction volumes.

    However, Kuala Lumpur saw high demand in luxury condominiums and service apartments throughout these crisis years. High-rise properties were also popular in Penang, particularly lower-end apartments and flats.

    “For Selangor, it was the city fringe, with terrace houses in Subang Jaya, USJ and Putra Heights as the hottest market. Median prices went from about RM220,000 in 1999 to up to RM400,000 by 2004. Around which time, demand similarly progressed to Setia Alam, Klang and other outlying areas towards 2012,” says Joe Hock Thor, CEO, MyProperty Data.

    Joe Hock Thor

    “Developers such as Sime Darby, SP Setia, Gamuda Land and IOI caught the wave perfectly, building larger homes within master planned townships at prices found closer to the city. High-rise popularity in Kuala Lumpur over this period picked up post-2003; this may have been due to cashed-up investors taking the opportunity to pick up glossy headline properties at discount prices.”

    This resulted in substantial price appreciation, with median high-rise prices rising from RM350,000 in 4Q 2003 to RM765,000 in 4Q 2009.

    Inflection Point and Recovery

    Whether in terms of price, transaction volume or value, the property market has repeatedly showcased a tendency to bounce back immediately following a downturn.

    This is seen in surging transaction volumes and values in the years following 1998 (the Asian financial crisis and Nipah virus outbreak), 2002 (the SARS outbreak) and 2008 (the global financial crisis and H1N1 outbreak).

    Similar recoveries are seen in national house price growth in the years following 2001, 2006 and 2009. “Price growth, as well as transaction volumes and values, have slowed down in recent years, with measures in place to address the residential overhang. This may cushion potential impacts on the market as it rolls with the blow,” says Fernandez.

    “Moving forward, investors tend to restructure their portfolios in uncertain times to manage risk, with property as a potentially lucrative venture. This, along with natural corrective forces as the market regains equilibrium, may account for the sharp recoveries seen in domestic property following crisis years.”

    These patterns are set to repeat themselves following the MCO and Covid-19 outbreak, with various initiatives contributing towards significant domestic liquidity moving forward.

    These include BNM’s reduction of the Statutory Reserve Requirement Ratio to 3.00%, moratorium on financing payments, OPR revision as well as revised voluntary EPF contribution guidelines in the government’s earlier ESP announcement.

    “For those struggling to make ends meet, these measures help address costs of living while presenting an opportunity to rebuild savings. For those with leverage, it may be a good time to invest,” says Fernandez.

    “There have already been calls from some quarters for revised loan-to-value ratio caps for third home purchases. This would accommodate demand from property seekers with leverage, driven by developer initiatives to add value for purchasers amid the changing property landscape.”

    GuruCares Reaches Out to Property Agents

    The Covid-19 outbreak and MCO have highlighted existing structural weaknesses in domestic businesses when it comes to technology-driven remote operations. However, while property players are tapping further into online platforms to drive sales, the underlying business model is likely to remain.

    “Developers have already invested in virtual show units and the online paradigm, and these can be useful for informational purposes. Due to the large emotional and financial investment required for property purchases, though, there will always be a need for the human touch, as well as physical showrooms and site visits,” says Fernandez.

    However, PropertyGuru acknowledges the potential impact of the MCO and other recent events on industry stakeholders, particularly property agents, who are often overlooked amid the larger national housing agenda.

    In its role as Asia’s largest property technology company, PropertyGuru has announced the launch of a (), aimed at easing the burden on agent partners. These include:

    • 100 free advertising credits, valid for a 12-month period to support listing activities
    • Complimentary account upgrades for renewing agents
    • 40% price reductions for any agent package, for first-time applicants, and
    • Four months’ unlimited access to Property Transaction Reports.
  • The Smart Investor’s Guide to Islamic Social Finance

    The Smart Investor’s Guide to Islamic Social Finance

    What are the main tenets of Islamic social finance?

    Sustainable Development Goals 2030

    Sustainable Development Goals 2030

    In 2015, countries around the world adopted a set of goals to end poverty, protect the planet, and ensure prosperity for all as part of a new sustainable development agenda. Formulated on the principle that no one gets left behind, the Sustainable Development Goals (SDGs) have defined the world’s priorities and aspirations for 2030.

    In 2016, a high-level panel commissioned by then-UN Secretary-General Ban Ki-Moon estimated a humanitarian financing deficit of $15 billion – and the gap is widening each year.

    Last year, only 58.5% of requested humanitarian funding needs were met.

    There’s an overwhelming need for capital to help fragile nations battle everything from widespread food and water insecurity to the fallout from natural disasters.

    Uplifting Poverty Levels

    To mobilise these efforts, we need to effectively uplift groups living below the line of poverty.

    Although poverty levels have fallen dramatically since 2000, there are still 783 million people living below the international poverty line of $1.90 a day. Obviously, it calls for more creative and effective solutions to end poverty.

    With technology playing a key role in implementation, this makes it more targeted and effective – an important move that we must take to lift people at the bottom of society from poverty and end world hunger to ensure that no one gets left behind.

    An Important Role in Achieving SDGs

    Islamic social finance was developed in adherence to the Sharia principles of socioeconomic justice, equality and collective prosperity.

    Islamic social finance tools have been instrumental in the alleviation of poverty and socio-economic development for over 1,400 years. Among the instruments available in Islamic social finance to achieve this are zakat, waqf and sadaqah (charity) which have been adopted and applied even outside the Islamic world.

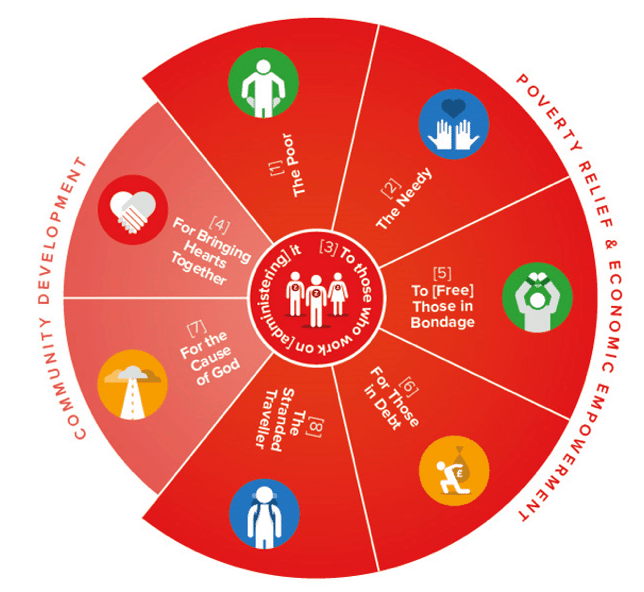
    Zakat – wealth tax and a means of wealth distribution – is thought of as harmonising the relationship between the individual and public interest (maslaha). Each year, Muslims are required to donate 2.5% of one year’s total cumulative wealth to the poor in the form of zakat.

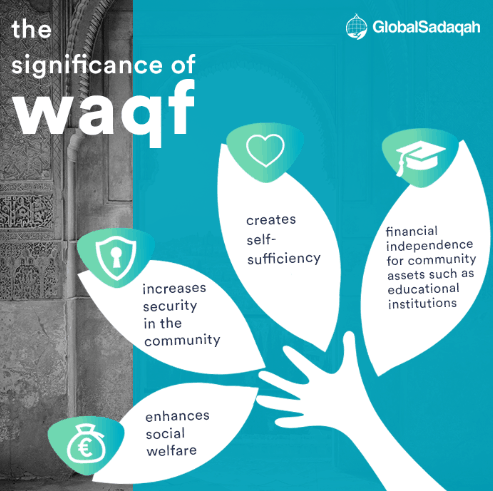
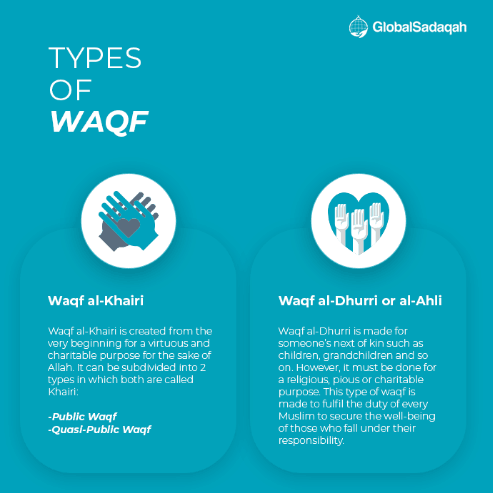
    Waqf is an endowment to a religious, educational or charitable cause, most frequently used to build schools, hospitals or religious institutions. Given its communitarian nature, waqf is often used to fund social projects and services.

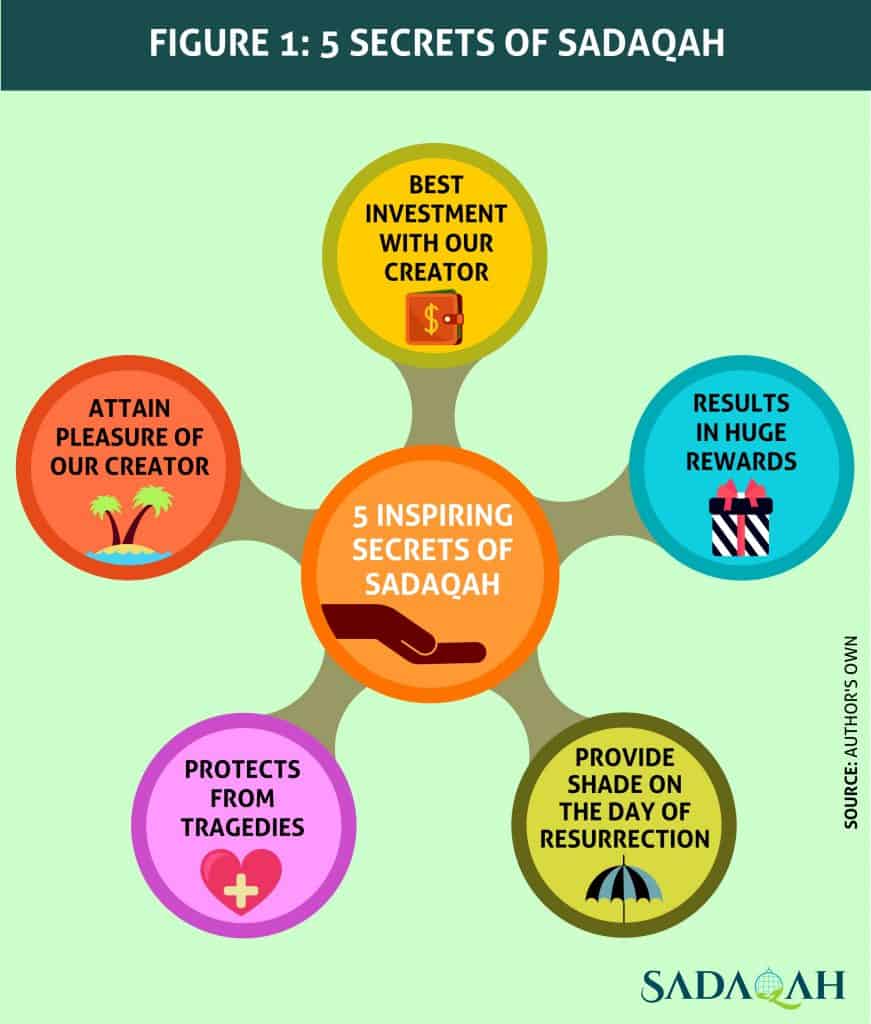
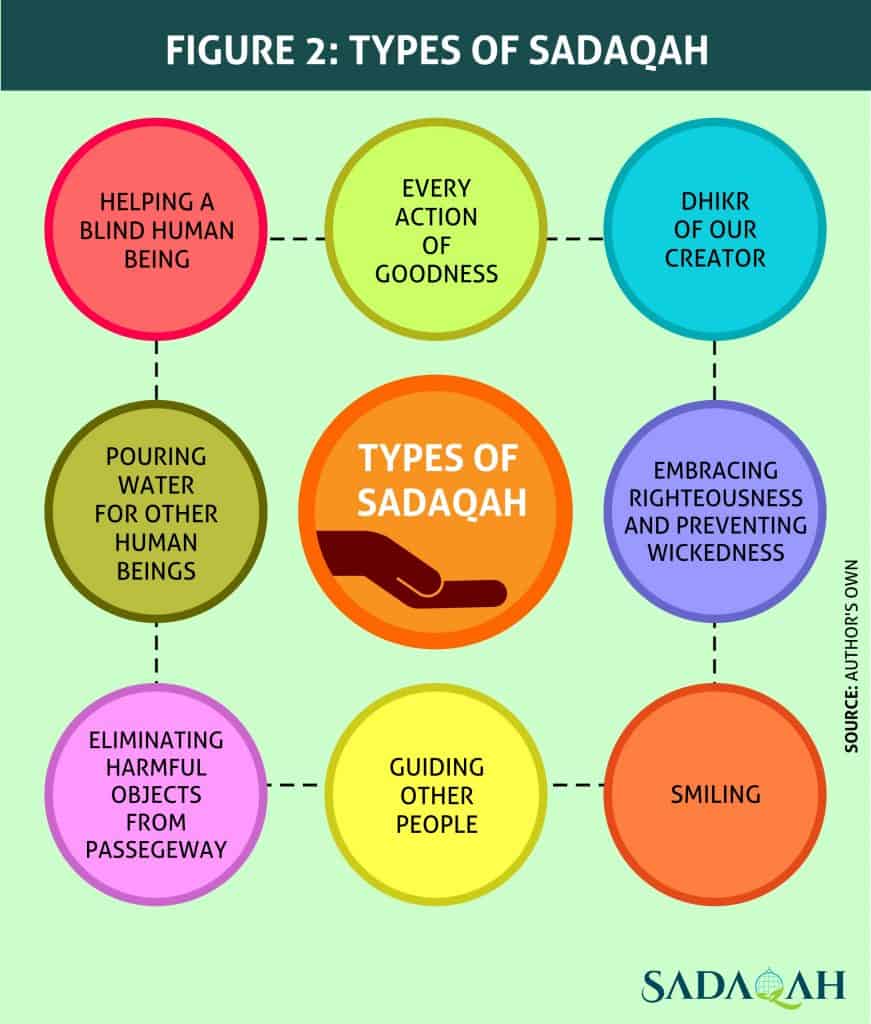
    Sadaqah is a voluntary charity given on an ad-hoc basis; a concept similar to putting coins into a charity donation box.

    These instruments are used to provide education and healthcare, to develop infrastructure and maintain social welfare provisions for the poor and destitute.

    waqf-sadaqah-zakat-social-islamic-financewaqf-sadaqah-zakat-social-islamic-financewaqf-sadaqah-zakat-social-islamic-finance

    Charity through Islamic Crowdfunding

    With the huge gap in humanitarian funding, coupled with the immense need, innovative financing models are starting to play a critical role as it becomes clear that no single factor can plug the deficit.

    In the humanitarian sector, international aid organizations are looking to new sources of capital and utilizing Islamic social finance for humanitarian projects. Innovation in the financial industry happened at a very fast pace, and Islamic Social Finance is one of the industries undergoing rapid disruption by digital platforms.

    GlobalSadaqah was a recipient of the Best Social Impact Islamic Fintech Firm Award at the World Islamic Fintech Awards 2018, during the Global Islamic Fintech Huddle in Bahrain. The Islamic crowdfunding platform helps channel donated funds to some of the neediest individuals in society. It connects individual donors to a diverse range of social causes that require financing around the globe.

    For donors, digital technology makes it easier to identify, evaluate, and fund causes. For organizations collecting social finance, technology provides greater access to donors, lowers costs, and allows for greater reporting and communication. For institutions implementing projects, technology enhances project management, workflows, and monitoring. Perhaps most importantly, digital technology can help recipients of social finance and their communities by making resources more accessible and distribution more efficient.

    waqf-sadaqah-zakat-social-islamic-financewaqf-sadaqah-zakat-social-islamic-financewaqf-sadaqah-zakat-social-islamic-finance