Category: lifestyle

  • Explaining Financial Planning through Football

    When we talk about the concept of financial planning, many people may think that it’s very complex and comprehensive, and may require a lot of information such as total income, overall expenses, liabilities, value of personal assets, investment assets and so on. While this is undeniable, to help you achieve your financial goal, this data can’t be ignored. However, it can also be as simple as ABC – let’s use football as an analogy to relate it to your asset allocation.

    What is asset allocation? 

    In layman’s terms, asset allocation is an investment strategy that diversifies money into different kinds of asset classes. It aims to balance the risks and optimise the returns. In order to have good asset allocation, a financial planner will distribute the capital into various asset classes with different levels of risk and return, so each will behave differently over time. Since each person has different kinds of goals, risk tolerance, and investment horizons, a financial planner will analyse his/her financial characteristics and apportion a portfolio’s assets that’s suitable for him/her.

    How to allocate assets? 

    As mentioned earlier, we’ll use football as an analogy to break down the best way to allocate assets. There are 11 players that make up a team that plays the game, which consists of a goalkeeper, defenders, midfielders and strikers. All of them are unique and have their own role to play. The same analogy also can be applied to our financial planning. Each financial tool represents a football player with an important role to play in personal financial planning. As we always say, don’t put all your eggs into one basket, hence you must diversify the risk and purpose by using different financial tools.

    Goalkeeper: Emergency funds

    The goalkeeper is the one standing at the last line of defence to make sure that the team won’t lose. His main job is to block shots from the opposing team to avoid giving up a goal. In the context of financial planning, who are our goalkeepers? Insurance and emergency funds probably fit the criteria.

    Insurance protects you from financial risks by transferring the risk to insurance companies, while emergency funds are used to overcome unpredictable events like unemployment or sudden loss of income. However, many people don’t pay serious attention to this and even procrastinate on insurance and emergency funds. This results in them being financially vulnerable to unpredictable crises ahead. 

    Defenders: Capital guarantees

    Apart from goalkeepers, the next line of defence are the defenders. Their main purpose is to offer protection to the goalkeeper and goal, and also preventing the opposition team from creating goal-scoring opportunities. 

    In the context of financial planning, these financial instruments are designed to provide stability for your funds, with capital guarantee often the priority. Examples of these financial instruments include fixed deposits, money market funds, your Employment Provident Fund (EPF), and bonds, which provides you with a stable income and principal guarantees for your investment.

    Midfielders: Collective investment vehicles

    Midfielders are positioned between attack and defence. These players act as the road maps, determining the direction of the play. They have the flexibility to be either attackingly aggressive or more defensive when needed, depending on the situation. Collective investment vehicles make great midfielders because these financial tools possess a diverse set of characteristics thanks to interventions from professional fund managers. 

    Strikers: Profit-making machines

    Lionel Messi, Cristiano Ronaldo, Harry Kane, Robert Lewandowski – these are examples of world-famous strikers. Their fame is thanks to the goals that they score, often resulting in their team going on to secure victory. In investments, the striker’s main goal is to score for profits! 

    Take your private businesses for example, which will generate income for you. You’re likely to spend a lot of time, capital, and energy on your business due to the potential it has to give you the best returns. However, if you fail to have a backup plan and blindly chase profits, when unpredictable events occur, it may be hard for you to rise again. Examples of investments or financial tools which play the role of a striker include equities, derivatives, and leveraged real properties.

    In a football game, there are 11 players on each team, but aside from the players, there’s still another important role that can’t be ignored. Without a coach giving instructions, there is no game plan for the team.

    Coach – Financial planners

    This is the 12th man in the game. Although he’s on the sidelines, he also plays an important role. Without the coach, can you imagine how the players can win the game? In the same situation, without players, do you think that the coach can win the game? In financial planning, the role of coach is often played by a financial planner.

    He/she will advise you based on your financial goals, risk tolerance, and investment horizon. This information is important as your financial planner will analyse and determine the best course of action based on your unique situation. This results in a very specific financial plan which is tailored just for you.

    The way of allocating assets can make a huge difference when it comes to seeking financial freedom. In the long road of a financial journey, you are likely to undergo many challenges in life such as economic cycles of market expansions, peaks, contractions, and troughs from time to time. Going through the four stages of an economic cycle requires great emotional management and smart financial strategies. So, it’s highly recommended for you to engage a licensed financial planner and approved financial adviser to ensure your financial well-being ahead.

    About the author

    Teoh Shoon Yee (FAR CMSRL RFP BIBM) is a FA Manager, Licensed Financial Planner and Bank Negara Approved Financial Adviser Representative with approximately nine years of experience in financial services. She is well versed in holistic, independent and unbiased approach with a pleasant and friendly personality. She can be contacted at ShoonYee.Teoh@yesfinancial.co
  • How to Start Personal Investment Planning

    “Tell me about the best investment plan!”

    “I heard my friend talking about XYZ investment, do you think it’s good?”

    These are just two examples of commonly asked questions on investment.

    Yes, I get it. You don’t want to lose out on the “best” investment deals in town.

    However, before you start investing, do ensure that you have built a solid financial foundation for yourself.

    So how do you know which one is the best investment for you?

    All financial solutions are designed for a target audience. The best investment is simply the one that suits you in the following three areas combined:

    1. Investment goal
    2. Investment time horizon and risk profile
    3. Investment vehicle

    As everyone is unique, there’s no doubt that an investment plan should be 100% tailored to your situation.

    Blindly taking recommendations from friends (who don’t understand your financial situation) could be detrimental to your finances.

    It’s just like self-medicating without a proper diagnosis from a health professional, but in this case, you’re putting your financial health at risk!

    Investment goals

    “Begin with the end in mind.” – Stephen Covey (Author of 7 Habits of Highly Effective People)

    It’s important to know what you’re trying to achieve, because without a clear goal, how do you plan for it?

    Take a moment to think.

    What is your goal in investing?

    – To build up emergency funds
    – To buy a dream house
    – To provide for children’s education
    – To further studies
    – To migrate overseas
    – To support family
    – To prepare retirement funds
    – To start a business
    – Others

    Why is this goal important for you? (Your why)

    – To prepare for unexpected expenses
    – To set up a family
    – To have peace of mind
    – To have freedom / choices
    – To have a comfortable retirement life
    – Others

    Finding out your why in investment is crucial, because it drives and guides you towards the future/ bigger picture that you are seeking to create.

    Investment time horizon and risk profile

    Once you have defined your investment goal, the next thing to work on is your investment time horizon and risk profile with regards to investing.

    Your investment horizon:

    When do you need this money?

    – Short-term (1-2 years)
    – Mid-term (3-5 years)
    – Long-term (more than 5 years)

    To define your risk profile, you may ask yourself some questions:

    1. How do you feel about a 20% loss in your investment?
    2. What is a decent investment return for you?
    3. What will you do during a market crash (sell off investment, buy more or do nothing)?

    Investment vehicle

    Lastly, what kind of investment vehicle suits you? Undoubtedly, suitable investment tools should fulfil your defined investment goals, risk profile and time horizon.

    Investment tools come with three fundamentals: capital preservation, liquidity, and returns.

    There’s always a trade off in any investment tool in terms of capital preservation, liquidity and return. Just like life, we can’t have everything we want. We have to give up something in order to get something else.

    If you want capital preservation and high liquidity in your investment, you will have to accept that returns will be low.

    If you want good returns and liquidity in your investment, you will have to accept that there will be absence of capital preservation.

    If you want capital preservation and a good return on your investment, you will need to give up liquidity.

    As you can see from above, there is no single investment that can give you capital preservation, high liquidity and high return at the same time. If you encounter one, there’s a good chance that it’s a scam – please do check with Bank Negara Malaysia on said investment!

    Let’s use an example on finding the right investment for you. Assume that you have defined the following:

    If your goal is to save up for an emergency fund, your investment vehicle should come with capital preservation (keeping your saved money free from volatile or fluctuating markets) and high liquidity (you need access to your money as soon as possible for unexpected events). 

    So, suitable investments for building your emergency fund can include:

    1. Bank – high-interest saving account
    2. Bank – fixed deposit
    3. Fixed unit price unit trust fund

    Please note that bank high interest saving account/ saving account and fixed deposit are protected by PIDM but unit trust funds are not protected by PIDM.

    You may repeat the steps discussed above to design your best investment plan that’s tailored specifically to your needs.

    All in all, there is no single best investment plan, because the best one is the one suits you the most! You have to define what you want, what you like and have a plan that you are comfortable with.

    It’s incredibly dangerous to just follow the crowd and invest blindly, because that means you’re jeopardising your financial future.

    If you feel lost when planning your financial future, you may consider investing in a financial professional.

    A financial professional would not only develop a roadmap for you, but will also provide advice as unexpected financial issues arise in your life and bring you nearer to your financial goals.   

    About the author

    Kuah Soo Yee is a Licensed Financial Planner (CFP) who is passionate about helping people make sound financial decisions and achieve their financial goals, and recently launched her own app. She can be contacted at soo.yee@ipp.com.my

  • Understanding Your Money Blocks

    Reflecting on my childhood, I remember we were given a book to write down our money spending during school – Buku Wang Saku. We also had to listen to a talk about how to manage our money. I remember only writing in it for a week and there was no follow-up after that. 

    That was almost 20 years ago, yet we’re still here talking about the same issue of money management, poverty and struggling to manage finances. We all subconsciously learn about money as children, with concepts that are good or bad depending on what we hear from our family, society, and even things we pick up from watching television or the news. Therefore, as we grow older, we form these money stories in our heads and couple them with our subconscious beliefs around money that influences our behaviour as adults.  

    It baffles me that even after 20 years, I’m still struggling with the same subject. I started reflecting on managing my money and how I sometimes unintentionally sabotage myself. Now I know that this was due to deep, unresolved money blocks. 

    What are money blocks? 

    Money blocks are negative subconscious beliefs about money that limit you from achieving your conscious desires. The main reason why it’s so hard to implement behavioural change is the part of the brain that is used. When watching a motivational video or reading a self-help book, we’re calm and composed to act better. But when we’re about to go shopping or have lunch, we kind of lose our mind, even though you promised yourself to manage your finances better after reading that self-help book you picked up before.  

    We keep going through this same pattern because of our brain’s subconscious and conscious compartments. For the first five years of our life, our brain is in the theta wave stage, whereby it’s in a sponge mode to absorb everything and anything. We take everything literally and learn how to be a person. These first, vital five years are when we learn all the emotions and feelings that surround us, which results in the formation of habits. 

    We learn all this from the adults that surround us. We observe their behaviours and mimic them as we grow older. We are very habitual human beings, and with that, we tend to keep close to feelings that we are familiar with, that is, the similar, regular cycle we’re programmed to react to. We tend to react the same way as we’re taught in the first few years of our lives, with all of this formed early on when we have no conscious control. These habits are then carried towards adulthood. 

    The conscious part of the brain only starts to develop later in life. So as a child, we unconsciously absorb all things wholeheartedly with no filter, including the good and the bad that cannot be told apart. We form most of our beliefs before the age of 5. Therefore, most days we operate solely out of habit and are on autopilot when we come across familiar situations.  

    When we try to learn a new habit, this is when the conscious part of the brain works. When we’re aware of patterns and want to change bad habits, but are faced with a specific situation that needs an immediate response, previous habits that are hardwired begin to react. This results in the nervous system reverting to existing patterns in the subconscious based on programming, long before our conscious brain can grasp and take control of the situation. Suddenly, you may see yourself falling back to the same lousy money habits even though you know this isn’t a good thing. 

    To have control over this is to make yourself conscious of situations that trigger you relapse into bad money habits. Take a breather and question yourself, before making a conscious decision. The recurring pattern from your past robs you of strength to make better financial decisions. If you can make a conscious decision to create new habits around your triggers and to change that narrative, you’ll be able to change past thought patterns!

    “Money is 80% behaviour, 20% knowledge.”- Dave Ramsey. 

    Although I have a degree in Islamic Financial Planning, I still struggle with my money blocks. Most of the time, financial planning focuses on numbers and figures but not the human thought process; I wish I was taught this back in university. Even with an abundance of education around managing our finances as a nation, there are still people falling back to their old habits and sabotaging their finances. I believe what’s stopping them is the deeply ingrained habits they grew up has made it hard to break the pattern. 

    Some common negative beliefs I learned:

    1. I don’t have the skill to make more money 
    2. Money is evil and rich people are mean and greedy 
    3. I can’t keep a lot of money or else I’ll lose it
    4. Witnessing parents fighting about money 
    5. I have to work hard to make money
    6. You’ll get sick easier if you work for money 
    7. When I am rich, there will be poor people suffering 
    8. There is not enough money for everybody, including me 
    9. A lot of things need to be sacrificed to gain wealth
    10. I have to know someone to be able to gain more wealth

    We tend to fall into this pattern of these messages, thus creating a wrong impression about money. These money beliefs tend to stay in our way and form our habits until we decide to identify them and heal consciously. 

    How to know if you have money blocks? 

    Everyone has them regardless of their financial upbringing. One way to tell is that you’re aware of money, but you’re not getting any results and constantly battle the same issues. Another indicator is that you know how to manage your finances, but you keep sabotaging your success. 

    This is what I’m currently experiencing. I have the knowledge to manage my finances well and I know how every decision I make influences my finances, yet I keep making the same bad decisions that trip me up. 

    Create an action plan 

    The only way to reset your money blocks is to identify your beliefs around money. Write in a journal and answer these questions: 

    1. What are my money beliefs, how did my family view money, and how was I culturally brought up around the subject of money? 
    2. What are your biggest fears around money? 
    3. If you are blessed with an abundance of wealth, how will you use it to help others? 

    “Self-sabotage is like a game of mental tug-of-war. It’s the conscious mind versus the subconscious mind where the subconscious mind always eventually wins.” – Bo Bennett

    Break that pattern 

    When we were growing up, the fears that adults subconsciously placed upon children helped them cope with their money concerns. However, when they didn’t heal from their subconscious fear, it tended to be passed down to their kids.

    In reality, we control how we can benefit and help others when we have an abundance of money. We’re all born with potential, and it’s our birthright to reach for the stars. We form our blueprint with the words used, and the mind tends to interpret it into reality. Our mind is meant to protect us from harm so it starts creating a scenario to defend ourselves. Re-write a better script around your many beliefs. It’s a process, one that never really ends. 

    I’ve been working on my money blocks and it is still a work in progress. I hope you enjoy diving into your thought patterns and enjoy the journey!

    About the author

    Nurul Yahi has a background in Business Administration majoring in Islamic Financial Planning. She’s a financial enthusiast and you can find her at dearduit.com. You can also find Nurul on TwitterInstagram and Facebook.

  • Turning A New Page For SMEs

    Turning A New Page For SMEs

    Low technology literacy has created a digital divide amongst businesses in Malaysia, with the common assumption that SMEs are less likely to access and use the internet when it is massively beneficial for them to do so. According to a report by World Bank Group in 2018, only one in three SMEs in Malaysia have implemented digital transformation strategies, while less than a quarter have a dedicated digital strategy team. Despite being the backbone of the country’s economy, SMEs in Malaysia performed rather poorly in adopting digital changes.

    SMEs are also susceptible to the practice of only adopting fundamental technologies for their operation—missing out on the more extensive digital solutions that could ensure their operation to remain robust in the long run. As one of the leaders spearheading digital transformation in various industries, the experts at JurisTech notice that there is an uninformed fear of the change brought on by digitalisation. This is not only specific to SMEs, but also applicable to almost every industry; with most citing ill-suited employees, lack of funding and technology experts for guidance as the reasons they lack the initiatives to start the transformation.

    Accelerating The Digital Transformation of SMEs

    Prior to the global pandemic in 2020, there has been a lag in digital adoption in Malaysia behind the global average. The struggle is not only felt by SMEs, but also technology providers, as there is a gap of knowledge differences between both parties. SMEs are afraid to reach out for help due to the perception that the cost will eventually be too taxing for them to run their operation and digital transformation simultaneously, while technology providers find it difficult to penetrate the market with low technology literacy amongst SMEs decision-makers.

    However, with the current economic climate and new regulation implemented by the government, SMEs in Malaysia are slowly acknowledging the importance of upgrading their current hardware and software infrastructure—where previously wondering how much would the transformation cost them, it is now a question of “how soon can we digitalise our existing processes?” SMEs now recognise digital adoption would enable them to continuously push through the periods of respective lockdown and semi lockdown, allowing them to remain operational and to create further stability in 2021.

    The demand is also spurred on by the need to be paperless and cashless. Besides that, 2020 taught many of us the importance of interpersonal interaction. While the face-to-face interaction was greatly reduced to lessen the effect of the pandemic, it has also speared the movement to innovate existing customer service technologies. An interactive, personalised chatbot is no longer sufficient; SMEs now have to find a way to not only attract and retain customers, but also to create a seamless customer onboarding process. This will help SMEs avoid drop-offs, increase customer acquisitions, and adhere to the lockdown regulations that are in place.

    The new digital transformation program rolled out by MDEC along with encouragement from our government drives the awareness for digitalisation and creates a bridge for many tech companies to offer their expertise to these businesses. SMEs now have a clearer idea of which areas of their operations are direly in need of digitalisation and can create a rising demand for it. This in turn allows technology providers to further enhance the existing features of their products to adapt to SMEs needs, just like JurisTech’s CollectXpress, an invoice-based collection recovery system and Juris Access, a digital customer onboarding platform developed with SMEs in mind.

    Acknowledging The Need For Digital Transformation

    Although the lockdown restrictions have been gradually lifted to encourage the recovery of the nation’s economy, many SMEs continue to operate remotely, cutting back on physical operation cost and manual processes implementation, allowing them to redirect their resources into upskilling their talents. This signifies a good start in many industries as it accelerates the digital adoption that has not seen satisfying progress in the last few years, as previously Malaysia was behind many of its neighbours in terms of technology utilisation.

    Most importantly, this indicates an increase in technology literacy amongst SMEs in Malaysia; as this shows a willingness to explore more extensive digital platforms to be included in their operation to remain relevant in whichever industry they are in. In the upcoming future, we can expect more SMEs will continue to grow alongside the ever-changing technology of today and forming active collaborations with technology providers that allow the development of more digital platforms aligned to their needs without the fear of disrupting ongoing business.

    About the author

    Nuralia Mazlan is part of the marketing and communications team at JurisTech, a leading Malaysian-based Fintech company, specialising in enterprise-class software solutions for banks, financial institutions, and telecommunications companies in Malaysia, Southeast Asia, and beyond. You can reach out to them at contact@juristech.net  

  • How to Calculate The Internal Rate of Return for Property Investments

    How to Calculate The Internal Rate of Return for Property Investments

    Let’s use the following example of a 1,500 sq ft fully furnished, two-bedroom, three-bathroom apartment in Mont Kiara valued at RM1 million, with rental at RM4,000 per month and a RM500 monthly management fee. We also assume that for 5 years, the property is perpetually rented. The rental yield is [(4000-500) x 12]/1,000,000 or 4.2%.

    While this is simple enough math, it doesn’t take into account appreciating (or depreciating!) property. Nor does it take into account the upfront costs you probably paid to renovate the home for it to be competitively rented out. And what about those annual taxes? Or that one-month agent fee you paid?

    Going over the variables for this exercise, we get:

    (A) Initial outlay – including legal fees, down payment and booking fees = -RM150,000

    (B) Monthly loan payments = -RM3,800

    (C) Upfront renovation works = -RM50,000

    (D) Monthly management fee =  -RM500

    (E) Monthly rental income = RM4000

    (F) Taxes and property insurance = -RM1000

    (G) Hypothetical net selling price of the property in year 5, minus RPGT and marketing/selling costs (eg. agency and lawyer fees) = RM1,100,000

    (H) Hypothetical remainder of loan outstanding on the property in year 5 = RM790,000

    Step 1: Calculate net inflow or outflow for each year

    Let’s put the values below in Column B, next to the corresponding years in Column A.

    Year 1 = A + (B x 12) + C + (D x 12) + (E x 11) + F (don’t forget the one month agency fee!)

    Year 2 = (B x 12) + (D x 12) + (E x 12) + F

    Year 3 = (B x 12) + (D x 12) + (E x 12) + F

    Year 4 = (B x 12) + (D x 12) + (E x 12) + F

    Year 5 = (B x 12) + (D x 12) + (E x 12) + F + G – H

    Step 2: Input the formula for IRR in Excel

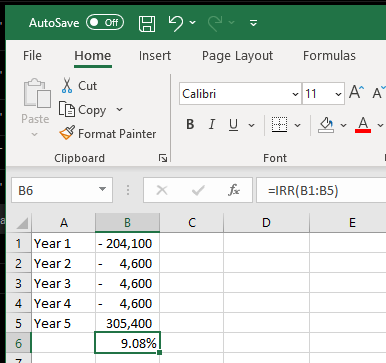
    In cell B6, input =IRR(B1:B5) to select the values of the cash movements in Step 1 above.

    input rate formula table for internal rate of return irr property investment

    This should result in an IRR of 9.08%.

    Summary

    In short, the internal rate of return is an annualised investment return which is directly comparable to other asset class returns. For example, if a share at the end of one year gives you 14%, inclusive of capital gains of the stock as well as dividends, then this number becomes immediately comparable to the IRR of the property.

    The trick here is to be realistic and be honest with yourself. After all, there’s no point cheating in comforting yourself that these property investments are “paying for themselves”. Using ratios and numbers such as IRR enables astute property investors to make logical decisions on what represents a good or not-so-good investment decision.

    Click here to read the full article about how to spot property investment opportunities in Malaysia.

    About the author

    Rozanna Rashid is a Licensed Financial Planner (CFP, IFP) and holds an MSc in Real Estate Economics & Finance from the London School of Economics & Political Science. Her background is in corporate banking and Islamic finance and she can be contacted at rozanna@alpine-advisory.com.

  • The Most Common Financial Planning Myths

    The Most Common Financial Planning Myths

    Financial planning has been defined as a process of developing strategies to help people manage their financial affairs to meet life goals. However, many people tend to have misconceptions that can be described as financial planning myths.

    “The best time to invest was yesterday. The next best time is now.”

    Yesterday has passed, so now’s the time for you to plan for your future, which involves learning about money and financial planning. If you master your finances well, then you’ll likely live a great life in the future because delayed gratification helps you to reach your life goals faster.

    What this means for you is to overcome the most common financial planning myths that I’ll be sharing with you in this article.

    1. Financial Planning is Only for the Wealthy 

    It doesn’t matter whether you earn RM2,000 a month or RM20,000 a month. As long as your income is used to pay for expenses, you need to have a financial plan regardless of whether it’s a simple or comprehensive plan. You need to calculate your net worth statement, cash flow statement and well as other relevant financial ratios.

    Whether you are driving a luxury car or economical car, you’ll still need to send your car for regular servicing – the only difference is the cost of servicing. Similarly, regardless of income levels, all of us still need to manage our own daily expenses, loan expenses and other allocation into savings or investments.

    2. I’m Too Young for Financial Planning

    Financial planning is meant for everyone regardless of age. If you are a child or teenager, it would be great if your parents teach you the importance of savings and growing your money that you received from red or green packets during festive seasons and other celebrations. Parents with good financial beliefs should plan for their children by starting a high interest savings or investment account for them in order to reap the benefits of the long-term returns.

    If you’re a working adult, you probably should have a financial plan in place to set aside and build an emergency fund, start insurance planning, retirement planning, travelling fund and or savings for your first house or car, and / or a wedding.

    If you’re a new parent, you need to plan for your children’s education, on top of your retirement and insurance planning. Some may probably need to save and invest so that he or she can accumulate enough capital to start a dream business. It’s at this stage that you may want to consider estate planning.

    If you’re a retiree, you may review and plan the expenses required for your desired lifestyle, which could include travelling goals, or simply your medical expenses.

    3. I Will Start Financial Planning when I Earn More

    Another common answer is, “I don’t have much income to plan financially and I will only start when I earn more”. Let me illustrate why this is a bad idea through this chart blow:

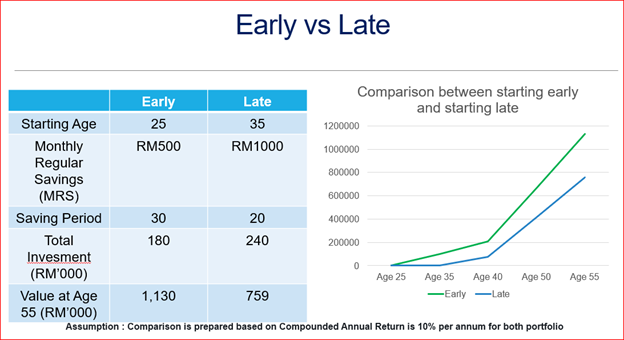
    financial planning early vs late

    These are two individuals, Mr. Early and Mr. Late. Assuming, both portfolios are growing with an annual compounded rate of 10% over the period of their investment horizon. Mr. Early who has learned the power of compounding from his dad and through reading investment books started saving regularly at age 25 with RM500 per month till age 55.

    However,  Mr. Late who believed that he should spend first and save later when he started working only realized the power of compounding and saving regularly after attended a wealth seminar recently. He started saving regularly at age 35 (10 years later than Mr. Early) with RM1,000 per month until age 55.

    When both reach age 55, Mr.Early would have accumulated RM1.13 million and Mr. Late with RM759,000 (even double the amount of Mr. Early monthly savings). The difference is around RM371,000 just by delaying it for another 10 years. Hence, do spend some time to learn and establish what your beliefs about money and financial planning are. Otherwise, it could have serious consequences on your financial goals or life goals. 

    “It’s not your salary that makes you rich, it’s your spending habit” – Charles A. Jaffe.

    What are you waiting for in your financial planning journey?

    About the Author

    Goh Chee Yong is a Licensed Financial Planner, and can be contacted at cygoh@imaxfinancial.com.my.

  • How to Set Financial Goals for Your Future

    How to Set Financial Goals for Your Future

    Much has been said and written about the sorry state general of financial literacy among people, both local and globally. According to financial literacy platform Multiply, almost 70% of Malaysians are in need of financial literacy support.

    “Financial planning” seems to be a popular catchphrase in recent years. The 7th of October is even recognised as “World Financial Planning Day”, which began four years ago. The purpose? To raise awareness about the importance of financial planning.

    If I used the term financial planning with my grandparents, they would say “Don’t worry so much, just work hard and be honest in your trade”. This shows how the concept of Financial Planning is fairly modern, with such an ideology being so foreign back in those days. Chances are, if you asked someone who is in their 60s or 70s today what financial planning means, there’s a high chance they’ll say it’s having insurance!

    However, financial planning is the process of developing strategies to help people manage their financial affairs to meet life goals. What constitutes a good financial plan? First and foremost, it involves taking stock of your assets, liabilities, investments, income, expenses and cash flow. The next part is important because it involves knowing the right strategies in order to achieve future goals. It also helps to break down goals according to priority and affordability. It then requires constant monitoring because we know circumstances in life will change – for both good or bad.

    Financial planning is clearly not as simple as signing up for a product. It’s a commitment to yourself and your family to ensure that your financial goals are achieved. In my observation and dealings with clients, I have found that the challenges in developing and sticking to a financial plan are summed up below (the list is not exhaustive):

    • Lack of priority – due to busyness at work and family commitments. The fear of the unknown future can be very daunting and it is easy to sweep this aside
    • Rising consumerism – shopping and spending is extremely easy. You can purchase literally anything in the world online and get it delivered to your doorstep. If left unchecked, would there be funds in the event of an emergency, let alone savings for the future?
    • Escalating prices of real estate – one of the social issues that the government is trying to tackle is the issue of affordable housing
    • Low interest rates – At the point of writing, the Overnight Policy Rate (OPR) rate is 1.75% which translates to Bank fixed deposits of 1.6% to 1.9% per annum
    • Salary vs inflation – not on par with rising cost of living

    All these seem to indicate that the younger generation is already at a disadvantage in achieving the same levels of success compared to their parents. For example, if your parents could afford to send you overseas when you were in university, can you confidently say you will be able to do the same for your children today?

    Having a financial plan is akin to being prepared for battle. You will know your limitations, ability to optimise your resources and your odds of winning.

    In the case of an investment portfolio, the more you spend time monitoring, the more invested you will be. For example, if you exercise daily, you’ll be much more conscious of your lifestyle, choice of food and calorie intake. The same can be said for a financial plan when you monitor it on a regular basis, which will lead to you becoming wired to make more informed financial decisions.

    Too much focus on any one area such as savings, investments, or insurance, may adversely affect the balance of your financial plan. The topic of investments alone is so vast, with plenty of choices available today, and is often confusing for consumers. Each platform has its pros and cons and it’s easy to get distracted by the whole process and only see things from that one perspective. Having a macro view is important and most consumers are not trained to do that.

    Let me give you an example. It’s highly possible to have false confidence knowing you invested in a portfolio that is performing at 15% per annum. However, if the amount invested was RM10,000, and even IF this portfolio could consistently perform for the next 10 years at 15%, the future value is only RM45,000. In the larger scheme of things, is that total of RM45,000 a meaningful solution in terms of the end goal to fund a child’s tertiary education and/or your retirement? Investment should be a means to an end, not the end in itself. Successful investment requires time, strategy and consistent positive returns to be favourable.

    There’s also the danger of neglecting risk management. An employee or an entrepreneur’s greatest asset is their ability to earn and also their potential future earnings. This asset can be severely affected due to a major health crisis. Have you considered income replacement in your financial plan? Most companies would have decent employment benefits that would cover you in the event of death and hospitalisation. However what happens if an employee is unable to contribute 100% to his/her job due to a health condition? Will your employer be happy to retain such an individual?

    In summary:

    • Work hard and smart in your trade
    • Manage potential risks that could happen in your working years
    • Look for opportunities to invest (in products/services registered with the Securities Commission Malaysia)
    • Monitor your financial plan and goals diligently
    • Seek out a Licensed Financial Planner to get a second opinion on your finances
    • Develop an estate plan as an act of love to your loved ones/charities

    With proper monitoring and guidance, you can be on the right track to achieve your financial goals.

    About the Author

    Kam Teik Guan is a Licensed Financial Planner, and can be contacted at kam.teik.guan@ipp.com.my.

  • How A Credit Card Works in Malaysia

    How A Credit Card Works in Malaysia

    2020 was a challenging year for many, but undoubtedly, it also sped up the transformation of people’s spending habits, pushing all of us towards online channels. Try to recall your last online shopping experience. How did you pay? It most likely would’ve been through online banking, e-wallet or credit card. Many of us choose to pay using credit cards because of a particular bank’s promotion or to collect points.

    In the mid-1970s, credit cards were first introduced in Malaysia. Since then, it has become one of the most common payment methods and the main source of short-term borrowing. With credit cards, we can buy the item now but pay for it later when it’s due. Today, with the government’s cashless society initiatives, credit cards are playing their role everywhere, and aren’t limited to just physical payments. It can be used for monthly auto-recurring bills, reloading e-wallets, signing up for an easy payment plan (EPP) and more.

    It’s a reality that credit cards are a major payment method in our daily lives. However, to play well in the “game of credit cards”, we need to know the rules to abide by first.

    1. What’s The Entry Fee?

    There are two kinds of fees involved here.

    a) Service Tax

    Effective from 1 September 2018, all cardholders are required to pay an annual service tax of RM25 for each active credit card (principal card and a supplementary card will be charged separately). This fee is unavoidable but some banks do offer rebates for this.

    b) Annual Fee

    From a personal finance perspective, you should only opt for a zero annual fee card! Unless you have strong and valid reasons, you should avoid a card that charges you hundreds or thousands of ringgit in annual fees.

    2. What You Need to Know?

    To avoid falling into traps, it’s better to know some jargon first.

    a) Credit Limit

    Treat it like a pre-agreed loan amount. This is the maximum amount that the bank grants to us for our spending. To determine the credit limit, banks usually look at two factors – our income and credit history. If we spend more than our limit (ie. breaking the rules of the game), be prepared to get a fine!

    b) Minimum Payment

    Ideally, you should endeavour to pay your outstanding balance in full. However, at the very least, you’re required to pay the minimum amount, which is 5% of the outstanding balance subject to a minimum of RM50. However, please take note for instalment payments like easy payment plans (EPP), the full instalment amount must be paid. If you can’t pay the minimum payment before the due date, be prepared to get a fine as well.

    c) Interest-Free Period

    This is the tricky part. We do enjoy an interest-free period of 20 days from the statement date provided all outstanding balance is fully paid. The last day of this interest-free period is usually referred to as the due date. Many people will have a wrong perception that they will always enjoy the interest-free feature for all new purchases, even when there’s an outstanding balance on their cards. However, this isn’t the case. If you have any outstanding balance on your credit card, the interest-free period won’t apply to the outstanding balance as well as any new purchase.

    For example, if someone has an outstanding due balance of RM1,000, and he/she makes another new purchase of RM1,000 with the same credit card, the finance charge will be calculated based on the RM2,000 balance (outstanding and new purchase) instead of the previous balance due of RM1,000.

    3. Are There Penalties?

    If you can’t play the game well, you might need to pay a penalty.

    Most people know that credit cards charge high-interest rates. However, between interest rate and convenience, people tend to opt for convenience first. A swipe of a card will always be the top choice compared to a loan application, which can take a few weeks to be approved!

    a) Late Charges

    Everyone knows credit cards work under the buy-now-pay-later mechanism. However, if we don’t make the minimum payment before the bill’s due date, a late payment will be charged. Usually, the amount will be 1% of your outstanding balance (subject to a minimum of RM10, or up to a maximum of RM100).

    b) Finance Charge

    If there is an outstanding balance that remains unpaid on the due date, a finance charge will be applied (usually people refer to it as interest). Bank Negara Malaysia implements a tiered interest rate system for credit cards, ranging between 15% to 18% depending on your repayment track record.

    c) Overlimit Fee

    If you spend more than your approved limit, an over limit fee will be charged. It varies across different banks, from RM25 to RM50 per month.

    These are some of the important things you must know before you apply for or start using a credit card. It’s important to take note because misusing credit cards can lead to financial ruin. Shifting your payment pattern to cashless can be rewarding. However, it can easily lead to overspending as well. According to the Department of Insolvency, Malaysia recorded 84,805 cases of bankruptcy between 2015 and 2019, with around 10% attributed to credit card debt!

    For credit card newbies, I have five important suggestions for you:

    1. Apply for only one card and get used to the full credit card payment cycle before applying for a second (if required).
    2. Limit your monthly credit card usage initially, then you can consider increasing later once you have proven to yourself that you can manage this well.
    3. If you can’t pay the full amount in cash now, don’t even think of making another purchase with your credit card.
    4. Check your credit card statement every month to review your “swiping pattern” and ensure there are no fraud / unauthorised transactions.
    5. Never pay the minimum amount for the month; full payment is a must by each due date.

    Financial literacy is not just about knowing about financial matters. Acquiring and consuming knowledge is easy in the internet era, but behaviour and habits are what counts. A credit card is a good financial tool if you use it wisely. Be responsible for your personal finance today as financial planning starts from small baby steps. If you need a professional to assist you along the journey, consider engaging a licensed financial planner to keep you on the straight and narrow path towards financial freedom.

    About the author

    Ocean Pon is a Licensed Financial Planner and can be contacted at oceanpon@finwealth.com.my

  • The Importance Of Building An Emergency Fund

    The Importance Of Building An Emergency Fund

    As we start this new year, there’s a lot of hope that 2021 will be a better year than 2020, and that our lives will resume some form of normalcy since the start of the Covid-19 pandemic. We’d all like to go around our daily lives in the way we were able to previously.

    Unfortunately, 2021 has started to unfold in a similar pattern to 2020, but we should remain optimistic and hope for the best. As with any new year, it’s a great time to set goals and have a fresh start. I believe many of us will have new year resolutions this season, some of which will revolve around finances.

    For many people, financial freedom, being debt free or cash rich is often on their goals or resolution list, but how many are able to achieve it? There’s a popular adage often attributed to Benjamin Franklin, the father of time management ” Failing to plan is planning to fail.” Many of us draft a new year resolution list but without proper planning, and setting goals, timeframe, and deadlines to meet, one will never achieve their plan.

    When Malaysia went into our first Movement Control Order (MCO) in March 2020, many Malaysians found themselves in financial difficulty as they were not prepared to face salary cuts, reduced working hours or even losing their jobs due to the economic shutdown. News has also been circulating of those who just managed to restart their businesses or get new jobs going back to square one as a result of MCO 2.0 due to the rising Covid-19 daily positive cases, currently at the four digit mark.

    Due to the uncertainty of such times, it’s important to reflect on where you are and where you want to be, as life altering events usually result in people taking a hard look at themselves to reform and transform. No doubt the pandemic has impacted many people in more ways than one, with saving habits being one of them. If you’ve planned your financials appropriately and have a sufficient emergency fund in place, you’d at least be able to support yourself and be less stressed in such times. One of the things that Covid-19 has taught us besides resilience and adaptability, is the importance of proper financial planning and having sufficient savings.

    The purpose of an emergency fund is to cushion the blow should unexpected events occur, such as medical bills, retrenchment, business closure, home emergencies home or car repairs. You’ll have peace of mind and less money worries if you know you have sufficient funds to tide you through difficult times. In addition, you’ll also have more confidence to save money for other financial goals such as retirement or your children’s education if you have an emergency fund in the first place.

    How Much is Sufficient for an Emergency Fund?

    Your emergency fund should cover at least 3-6 months’ worth of essential expenses. Of course, you can save for more than six months; some people have up to 12 months of savings or more! It depends on:

    • Family size – are you single, a breadwinner, or in a dual-earner family i.e. you or your husband/wife works?
    • How closely your job is tied to economic changes
    • Financial responsibility

    Essential expenses are bills that you can’t stop paying such as food, utilities, household essentials, rental or mortgage repayment, car repayment, insurance and medication. Gym passes, entertainment expenses, or Starbucks coffee aren’t essential expenses.

    Six months of fixed expenses is the guideline, but it’s acceptable to save more but be warned that keeping excessive funds in your bank account only is also not advisable as the money doesn’t generate additional returns for you and will be slowly eroded by inflation.

    How to Start an Emergency Fund?

    As with all other things in life, start with a small realistic goal. Determine an amount that you’re comfortable to set aside every month, for e.g. RM200. It doesn’t matter if you start small as long as it’s realistic and you can move forward. Once you have accomplished this, set a new savings goal that will require more effort e.g. RM500, slowly add to it until you have accumulated one month’s worth of expenses. Your ultimate goal will be to reach 3-6 months of your fixed expenses.

    Where Should I Keep My Emergency Fund?

    An emergency fund is all about keeping it safe. Hence, there’s no specific investment tool to keep your emergency fund, as long as it is safe, liquid and easy to access. Most people will prefer to save in a savings account or fixed deposit (FD).

    The reason for putting these funds into a safe investment tool is because if the money is in high-risk investments, there’s a risk that you could lose all the money. For example, saving an emergency fund of RM15,000 earning 2% interest in fixed deposits gives you RM300. If you were to invest in the stock market and can generate 8% annually, that’s RM1,200. While an extra RM900 may be significant to you, it isn’t guaranteed as you could lose all the capital you invested in the stock market if market conditions are unfavourable.

    Hence, don’t be greedy and just leave your emergency fund in a fixed deposit or savings account as the goal is liquidity, not high returns.

    Life can be unpredictable so it’s important to put aside a small amount of cash each month to cushion the blow of emergencies in difficult times. Many people strive for high-risk investments where they take on unnecessary risk to earn more money but are left with no basic savings. For those who don’t have this habit, start building your emergency fund from now. Learn from the past and don’t procrastinate. Once sufficient emergency funds are set up, it’s time to aim for your next financial goal, which can be for the short, medium or long term, depending on your life goals and/or values.

    About the author

    Yit Wei Yeing is a registered financial planner. She can be contacted at wyyit@genexus.com.my.

  • How to: Plan for Your Children’s Education Fund

    How to: Plan for Your Children’s Education Fund

    Among the Chinese, there is a saying: “再穷也不能穷教育”, which translates to: “Education shouldn’t be sacrificed even if we’re poor”.

    Parents believe that when their children are educated, they can secure a higher income and get better opportunities in life, allowing them to contribute back to the family and society in various aspects.

    Just like any investment, time can be your friend or your worst enemy. If you’re a parent with young children, why not start preparing the best angpao you can give your children now?

    To start planning for your children’s education fund, you should:

    1. Estimate the Cost of Education

    When estimating the cost of education, consider the following factors:

    • The type of studies your child may pursue.
    • Will you send your child to attend a local or an overseas university?
    • How much is the basic cost of living should your child attend an overseas university?

    Information on the fee structure and the overall cost of living are readily accessible on the internet. You can refer to this website to learn more about the fees and cost of education in Malaysia.

    However, bear in mind that these factors may change over time. Review the plan at least once a year to keep yourself updated on the latest developments and be sure to get the information from various sources to ensure that the cost of education and overall cost of living falls within a similar range.

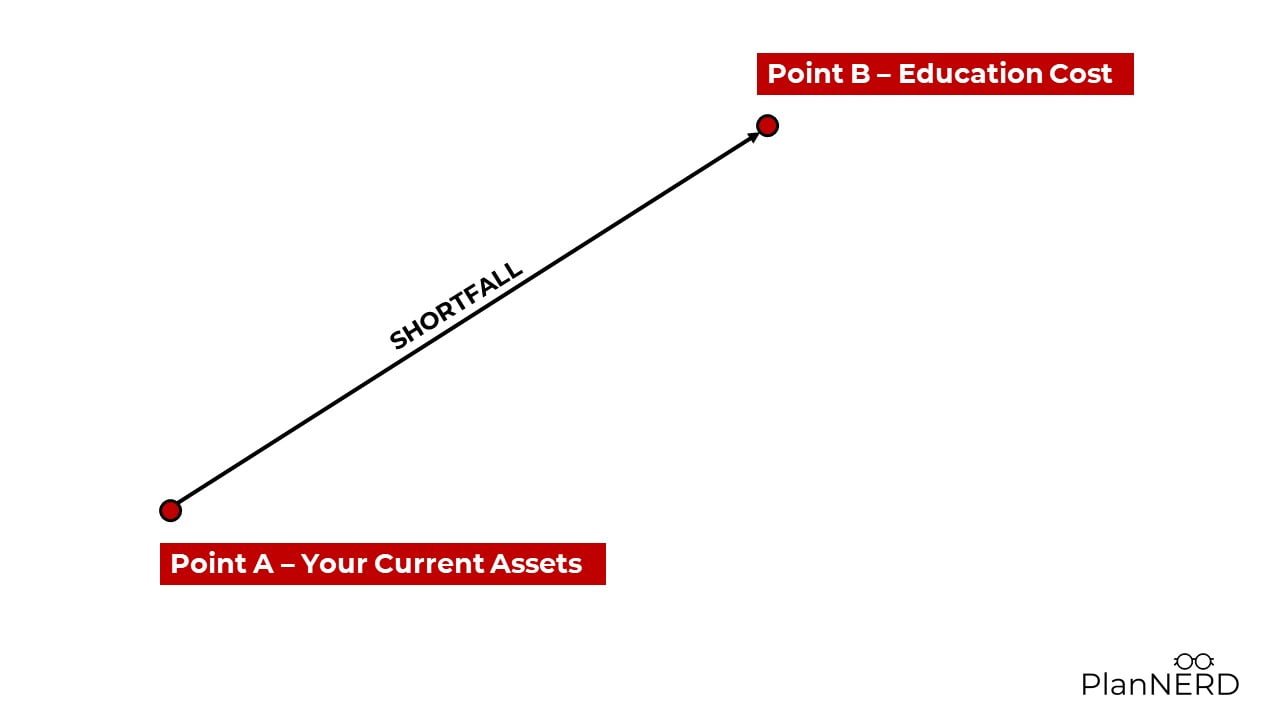
    2. Understand Your Current Financial Position

    current financial position graphic - children's education planning

    Now you know how much is needed to reach point B (cost of education), to calculate how much you need to set aside every month to cover the shortfall, you’ll also need to know how much you currently have – point A.

    Most people store their wealth in cash, properties, and other types of investments. You should ask yourself; what portion of the above-mentioned assets can be allocated for your children’s education?

    For example, you may want to allocate 10% to 20% of your cash for the sole purpose of funding your children’s education. If you have investment properties, you may also designate a property to be sold once your child reaches 18 years old. Some may even have endowment policies with insurance companies that may mature in 20 years.

    The key is to write down a list of assets that you will dedicate to its sole purpose of being your children’s education fund.

    3. Determine the Amount to Cover the Shortfall for Your Children’s Education

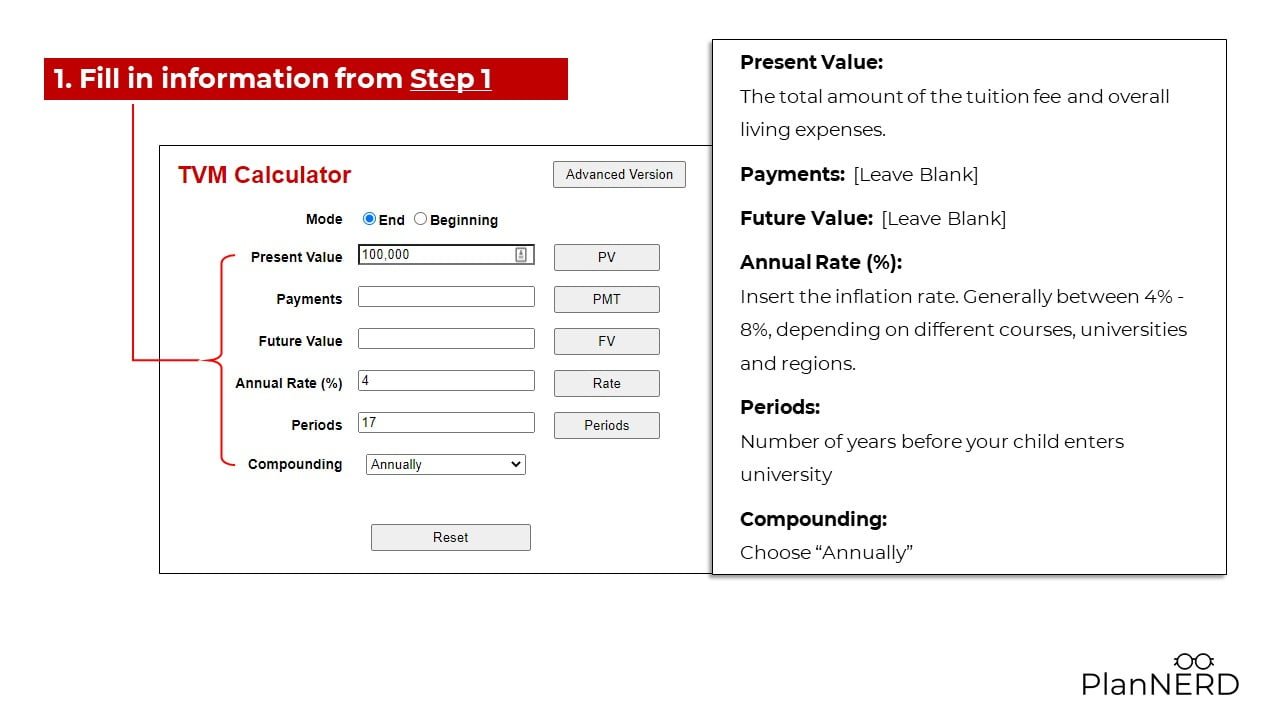
    In this step, we’ll use a free financial calculator to easily calculate how much you need to save/invest for your children’s education. You can access the calculator here.

    (i) Enter the following field with the information you had prepared in Step 1 above.

    Step 2 for FV calculations - children's education planning

    (ii) Click on ‘FV’

    step 2 for FV calculation- children's education planning

    The amount in the FUTURE VALUE box is the future value of the education cost that you entered.

    In this case, the cost of education today is RM100,000. However, with an inflation of 4% for the next 17 years, the cost of education will increase to RM194,790.05 when your child is ready to enter university.

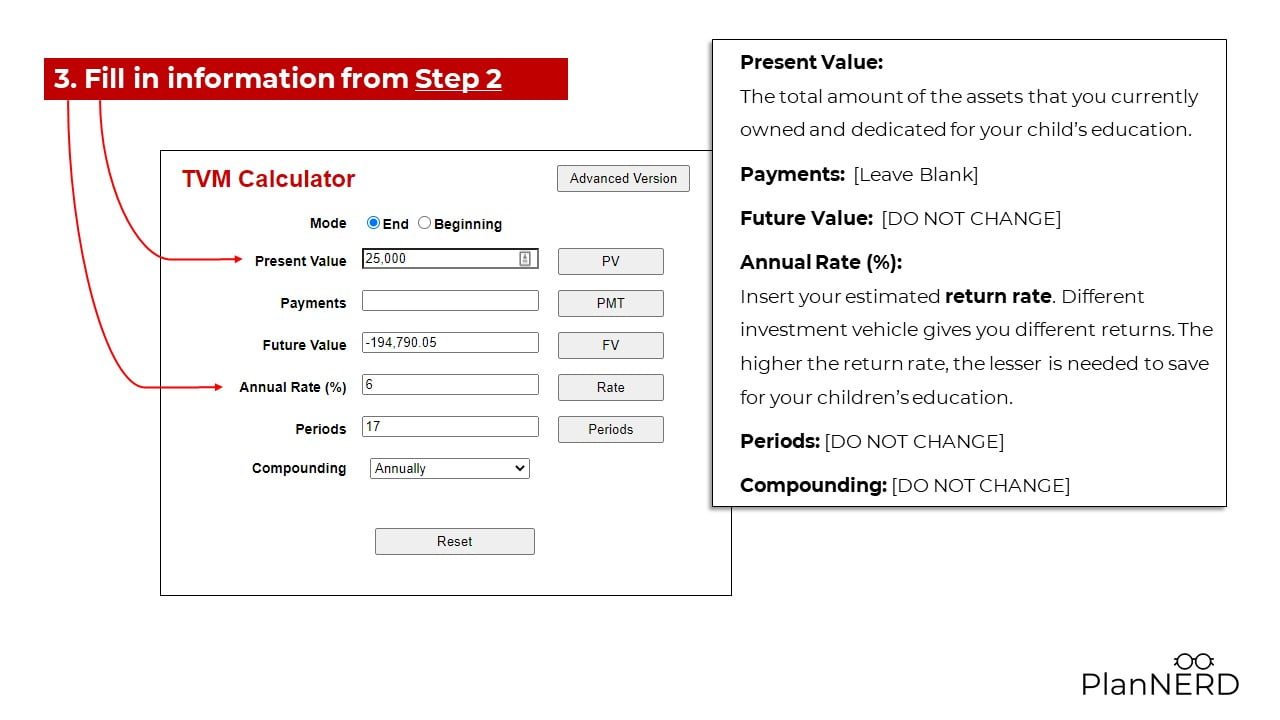
    (iii) Update the ‘Present Value’ and ‘Annual Rate’ field

    present value and annual fee table - children's education planning

    Next, you’ll need to calculate how much more is needed to cover the shortfall.

    Using the same example above, assume that you have RM25,000 now and you believe that you can achieve an average of 6% return rate for the next 17 years, update the Present Value and Annual Rate (%) column.

    (NOTE: do not refresh the website or change any other information.)

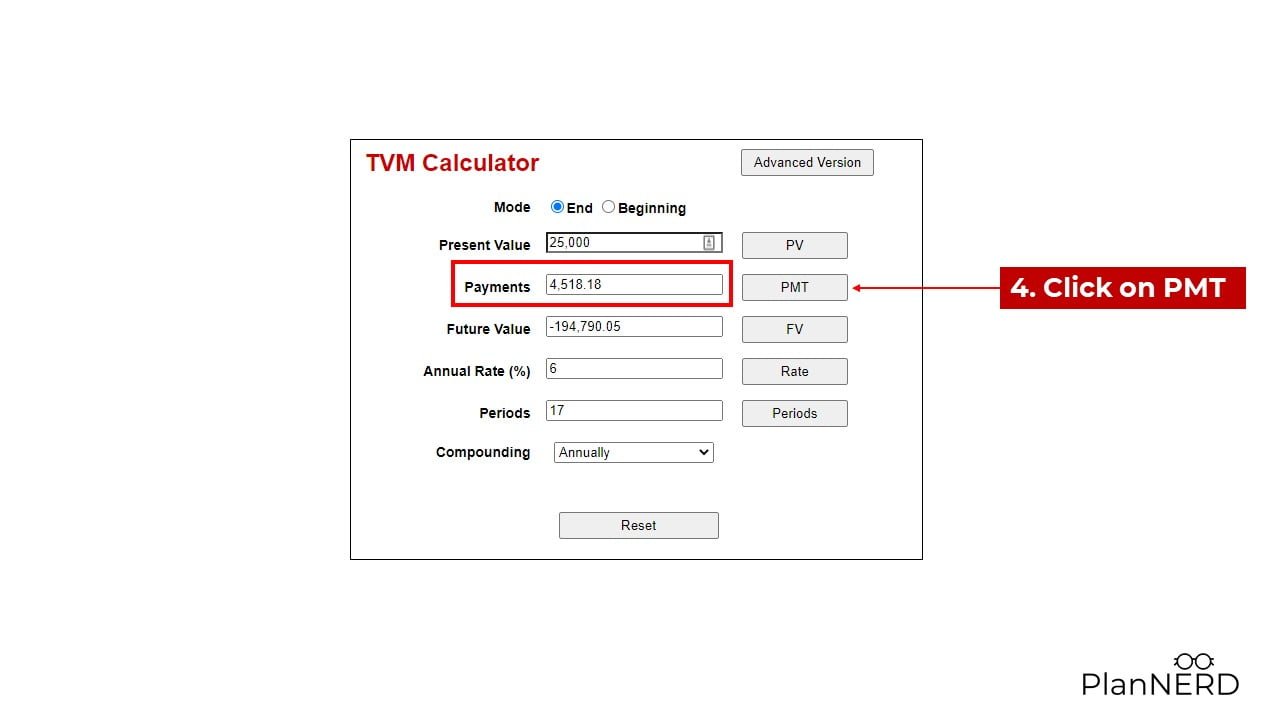
    (iv) Click on ‘PMT’

    pmt table to show the calculation flow under children's education planning

    The last step is to click on “PMT” to calculate the amount needed to save/invest every year to cover the shortfall in your children’s education fund.

    In this example, you will need to save RM4,518.18 every year, or roughly RM400 every month (with a return rate of 6%) to send your child to a private university in Malaysia in 17 years.

    4. Choosing the Correct Financial Vehicle

    There are plenty of choices when it comes to choosing an investment vehicle. However, we all know that most investment journeys aren’t going to be smooth sailing all the time, therefore it is very important to follow these three rules of investing:

    Preserve your investment capital

    One important rule that’s applicable in investing for children’s education is to preserve your investment capital. Sometimes, we can allocate a small portion of our portfolio to invest in high-risk investments. However, you don’t want to do that with your children’s education portfolio.

    For example, in order to recover from a 10% loss on an investment, you’ll need to have an 11% gain to return to the original capital position, a 25% loss would require a 33% gain to break even, and so on and so forth.

    There is no such thing as the best investment

    In short, what’s good for me may not necessarily be good for you. Having said that, when it comes to investing for your children’s education, you may want to pay some attention to PTPTN’s National Education Saving Scheme (SSPN). Parents saving money into SSPN-I can enjoy tax relief of up to RM8,000 per year.

    Keep your eyes on the prize

    Lastly, keep your eyes on the prize. Always remember your why. Constantly review your investment strategy to ensure that you don’t receive any unfavourable surprises when your children are approaching the age to register for tertiary education.

    5. Avoid Common Education Planning Pitfalls

    Ignoring retirement planning

    If you’re unable to cover the shortfall as calculated earlier, there are other ways to ensure that your children will receive a decent education, such as applying for an education loan from PTPTN or applying for a local public university.

    However, there are fewer options available if you can’t cover the shortfall in your retirement planning.

    Trusting the wrong ‘advisor’

    Many fraudulent “advisors” use the element of fear and greed in parents to convince them to invest in their unregulated investment products. Should you need the help of a third party in the education planning process, please ensure that you engage a licensed representative.

    Not reviewing savings and investments

    I may sound like a broken record by now but reviewing your investments and portfolio at least once a year is very important. If needed, you should also rebalance your portfolio to ensure they meet the objective of providing X amount of money Y years later.

    Conclusion

    Saving for your children’s education is a long-term goal that may seem like a huge commitment at first. With a carefully planned strategy, and making time your friend instead of your enemy eases the process significantly. No matter how much or little the amount is, start today. The earlier you start, the better the compounding effect will be, because:

    “Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn’t, pays it.”

    This article was originally published at planNERD.

    About the author 

    Marshall Wong is a licensed financial planner, and can be contacted through his website or marshallwong@fa.my.