On the topic of retirement planning, there are a lot of things that comes into mind. Savings, investment and retirement funds are just some of the issues that we need to face. How much do we need to save every month? Where to invest? Is RM1 million enough to retire?
Smart Investor spoke to Ismitz Matthew De Alwis, executive director & chief executive officer, Kenanga Investors Berhad to get more insights on this issue.
Ismitz Matthew De Alwis
Smart Investor: It is reported that 75% of Malaysians don’t even have savings of RM1,000. Why do you think most of us are not able to save?
Ismitz Matthew De Alwis: With rising inflation and poor personal financial habits, most Malaysians would not be able to survive for more than three months if they were to unexpectedly lose their main source of income. Although the Employees Provident Fund (EPF) and Private Retirement Schemes (PRS) withdrawal policies were relaxed to assist those significantly impacted by recent events, this has led to many depleting their retirement savings faster than planned.
I believe that it all eventually boils down to their personal finance fundamentals. Many forget that the process of building up sufficient retirement funds is not brief, but a lifelong journey.
Everyone seems to be talking about that magic RM1 million. It is achievable and will it be enough to retire comfortably?
Everyone begins their journey from a different starting line and the decisions we make along the way will affect our destination in the end. RM1 million may seem a big amount for some, but a drop in the pool for others.
Investors should focus on saving for a sufficient amount that is achievable and enough to retire (according to their desired lifestyle) without worry. The major factor is to plan early for their retirement.
6.1 million EPF members have less than RM10,000 in their savings, it doesn’t look too good. What can these people do to ensure they can retire well and not continue working until old age?
Make it a habit to review and evaluate your financial portfolio periodically and make the necessary changes when needed. This can reduce the chances of panicking and making rash decisions when difficult situations present themselves. I tend to link retirement planning towards building a well-rounded ship.
By actively evaluating their portfolios, they can ensure that their ship is well-fuelled and constructed with high-quality materials, to protect their growing cargo from rough waters and strong winds.
The younger generation these days seems to like working as a freelancer, running their own small business or becoming an e-hailing driver but with no EPF, how can they start planning for their retirement?
Proper research and planning are required before diving into any form of investment as there exists many products and options which all serve the same purpose: providing additional income. They can then set aside this additional income and park it under voluntary long-term saving schemes.
For example, here in Kenanga Investors, we offer OnePRS by Kenanga as a voluntary retirement scheme to assist investors to supplement their current savings for their golden years. With an increasing life expectancy and the rising costs of living, many are finding that their retirement funds are not enough to solve any potential financial difficulties during their retirement.
What are some of the investment vehicles that you would suggest for retirement planning?
There are usually two main factors when it comes to discussing preference, an investor’s investment horizon and risk tolerance. When planning for retirement, investors can opt for short, mid or long-term investment periods, while their risk tolerance depends on the person itself. Investors who are willing to take on higher amounts of risk to achieve higher returns or growth are categorised as growth or aggressive investors.
Moderate risk investors are those that are in-between and are willing to take some percentage of losses to achieve a steady growth rate. Also, low-risk or conservative investors are those that do not participate in high-risk investments, they often seek a steady stream of income with very low risk.
There is no one-size-fits-all option for retirement planning, as there exists a wide variety of investment products in the market that cater to various risk tolerance and investment goals. Some examples of these are unit trusts, real estate, bonds, deposits, stock trading, and exchange-traded funds. In short, be sure to first determine your risk tolerance and retirement goal before committing to any investment vehicles.
There will be an increase of senior citizens in Malaysia as the life expectancy of Malaysians increases. Undoubtedly, decreasing fertility rates and increasing life expectancy is fast forwarding Malaysia to the status of an ageing society.
Based on the Department of Statistics Malaysia, the total population of the country was recorded at 32.4 million in 2020, with a total 2.2 million of the population or 7.4% aged 65 years old and above. The World Bank defines a country as ‘ageing’ when the percentage of people aged 65+ is above 7%, thus, categorising Malaysia as one of the ‘ageing’ nations.
The 2020 report by the World Bank, titled: A Silver Lining: Productive and Inclusive Aging for Malaysia, estimated that Malaysia will be an ‘aged’ nation by 2044 and ‘super-aged’ nation by 2056 with at least 14% and 20% of the population aged 65 and above respectively.
Whether it is for ourselves or for our parents, are we prepared for aged care?
Dr Carol Yip
Responding to Smart Investor, Aged Care Group Sdn Bhd (ACG) chief executive officer, Dr Carol Yip says that many are still struggling and worry if there will be enough money to retire, especially when medical costs continue to rise.
“Have you ever spoken to your parents or your family members about this? Most of us have not talked about or planned on retirement with our parents or families,” Dr Carol points out.
She notes that it will be difficult when adults in their 40s and 50s need to take care of their aged parents’ medical and living expenses, in addition to what they may have to spend on their own medical and living expenses. The situation may worsen with sibling rivalry and unwillingness to share the financial burden of caring for aged parents.
Increasing Needs for Aged Care Service
Group chief executive officer of Seterra Group of Companies, Rashidi Yahaya said that more and more people are now looking for aged care for their parents. Seterra is a Syariah-compliant aged care company located in Bukit Damansara, with the goal to revolutionise the standard of Islamic aged care in Malaysia by setting a new world class standards in aged healthcare facilities.
“Inevitably parents will grow old. When they are no longer mobile or become bedridden, their children will find themselves inadequately ready to provide the necessary care,” he informs.
He explains that there is also a shift in the thinking of the elder community today. They do not want to burden their children when they grow old, and can accept living out their older age in a place that can fulfill both their medical/physical and spiritual needs.
Society at large has moved away from traditional family values where the elderly are mostly at home under the care of their family members, shares Angela Francis, a project coordinator for Ipoh-based Ozanam Retirement Village (ORV).
“Hence, it is becoming more necessary for people nowadays to start planning on how to secure and support themselves in their twilight years,” she says.
ORV provides an essential community living environment for seniors. It is an initiative by The National Society of St Vincent De Paul (SSVP) and the Titular Roman Catholic Bishop of Penang where Angela is the vice president of SSVP.
There are some critical perspectives regarding retirement living and aged care. In the old days, the responsibility to care for the parents lies on the children. Even today, some are still stuck with this perspective.
“You are not neglecting your duty as a son or daughter by sending your mother or father to a home as these homes could perhaps take even better care of them for you,” Rashidi explains. “We still have a duty to provide emotional, physical and spiritual support to the best of our ability.”
“For Muslims especially, there are special considerations and concerns. These concerns need to be balanced with providing the best aged care for our parents according to our means and the seeking of Husnul Khotimah, of finding peace and contentment in their final years,” he points out.
Are There Enough?
As Malaysia moves closer towards becoming a ‘super-aged’ country in less than 35 years, are there enough aged care facilities that can cope with the demands?
“Elderly people have multi-types of illness and will need a qualified multi-disciplinary team of trained staff.”
“We don’t have enough purpose-built licensed aged care facilities with professional managers and trained staff to provide quality care according to the define-specific old age illness like dementia, Parkinson’s disease, stroke, kidney failure, cancer, heart problems and frailty – just to name the common problems,” says Dr Carol.
Rashidi agrees with Dr Carol that the facilities for aged care needs are not enough, noting that the aged care sector is very under-served, especially for Muslims. That is why Seterra is pioneering a structured approach to retirement and elderly care for Muslims.
Rashidi Yahaya
“We sincerely hope there will be more Muslim players in the industry. New standards of caregiving and infrastructure, nutritious halal food and food for the spirit are needed to ensure a dignified ageing experience, and adequate medical care are just some of the factors that needs to be put in place,” he says.
In Malaysia, developers are already noticing the potential of this market segment and have invested in building retirement villages to cater to the anticipated growing market. In the last ten years, residential property developers have begun developing aged people-friendly residences. However, this is still not enough.
Current townships have more residential apartments, commercial buildings and shopping malls as compared to aged care related facilities which is not the main attraction for buyers. But the awareness is increasing. Will an aged care friendly ecosystem in the residential building be a game-changer?
“There’s no statistic to back the claim that it will be a game-changer. But I’ve worked with developers to build aged care facilities in their township development. It’s satisfying to see that most residents can easily get the help they need anytime as the aged care operates 24/7 in such development,” Dr Carol informs.
According to her, in Singapore, every township development or common area is required to have childcare and senior citizen centers among other community facilities. It is for the convenience of those who are staying in that particular housing area.
She strongly recommends that the elderly live their old age in a neighbourhood familiar to them. Even better if it is within the same neighbourhood that is within a 5 to 10 km radius, and there is a licensed aged care facility for them.
“We need to start engaging the stakeholders that are building smart cities for sustainable living. It would be to encourage them to include aged care support infrastructure, facilities and support services.
“The government has access to all the data and surveys from MyCensus; as well as health and medical conditions of Malaysians via public hospitals and clinics from the Ministry of Health. They should be able to predict the ageing needs based on that data. That’s where all the data comes in for a better projection, planning and execution,” she notes.
Lack of professional caregivers, affordable care, elderly-friendly accommodation and other related problems would require urgent attention before the silver tsunami overwhelms the country.
Is Aged Care Exclusive?
Who has access to aged care? Is aged care only exclusive to those in the wealth hierarchy (aka the one who can afford it)? Dr Carol insists that aged care should be inclusive to help those, and all in need.
“We have low-cost airlines, low-cost hotels, so the same should go for aged care. We need low-cost aged care facilities with proper care for the elderly. There is a need for more affordable aged care that people in need can access,” Dr Carol explains.
Aged care should be inclusive but are they affordable especially to those in B40 or M40?
“Today, I don’t think that the B40 segment can afford aged care, while the M40 can only afford to provide aged care amongst the family if the family comes together to take care of each other and their aged parents,” Dr Carol shares.
According to her, it has to be a shared effort and shared financial responsibility depending on how each adult child plans their retirement. If the M40 does not have family, they will need help from the community such as friends and neighbours.
She emphasises on the government’s role in providing support and incentives to make aged care affordable by categorising the population data by area or township, enforcing and implementing a continuum of care services that are easily accessible.
Non-Governmental Organisations (NGOs) have been playing an active role in many segments, especially in helping those in need.
Angela Francis
“As part of an NGO that serves the weakest and marginalised within society, we regularly encounter many of the elderlies who are abandoned and left to fend for themselves,” Angela says.
She adds that the growing need to provide care, better living standards and security to this vulnerable group in society has inspired and driven them towards the development and management of ORV.
“We want an eco-friendly environment. Hence ORV is being built in Taiping, Perak – a land surrounded by lush green foliage to harness the tranquility and peacefulness from nature,” she says.
“We would also want to ensure that we are giving the opportunity to the right target group, namely the elderly, to reside in the retirement village,” Angela explains adding that the majority of those using their services are in their 60s and 70s.
Islamic Aged Care
Aged care is needed across the board. It should be inclusive without any label, be it from a religious point of view or race.
“Out of the 1,400 aged care homes in Malaysia, none are registered as an ‘Islamic Aged Care’ home,” Rashidi informs.
On the hesitance of aged care in Malaysia especially for the Muslim community, Rashidi comments: “If one cannot take care of one’s parents because they are bedridden or seriously ill, it is the children’s responsibility to seek solutions to care for them. Letting others take care of their parents does not mean they are neglecting their duty. They are still providing for them to the best of their ability.”
The Muslim mindset about aged care or retirement homes needs to change. They must see that it is a natural progression of their own life and of their parents to undergo a new phase – to seek spiritual fulfillment, to handle all worldly issues and to have a dignified and peaceful ending with the best of care.
With the world evolving, aged care is not as typical as we think. The way we view things needs to change and come from different perspectives.
Placing your parents in an aged care facility does not mean you are abandoning your elderly parents. However, it must be followed by strict compliance as enshrined in the Quran and the Hadiths. “You still owe a very heavy duty to them and keeping your parents happy and fulfilled is still your responsibility which you cannot abdicate to a Rumah Orang Tua,” he emphasises.
Never Too Late to Start
Have we planned on how to survive our golden years? If you are to retire, how much money do you need? Would it be sufficient to cover for the rainy days?
RM2,500 per month looks to be sufficient for retirement. But depending on one’s lifestyle during retirement, it may not be enough. “With rising inflation, this amount will not be sufficient,” says Angela.
Sadly, according to the Employees Provident Funds (EPF), around 6.1 million contributors aged below 55 or 50% of total contributors only have RM10,000 or less, which means this group of contributors may only have RM42 per month to live for another 20 years after retirement.
“It is estimated that 39.2% of our population have ZERO savings for aged care (World Bank calculations based on the Department of Statistics Malaysia, EPF and KWAP). In addition to that, almost 50% of the ageing population in Malaysia falls into the B40 category. At Seterra, it is our objective to cater to all walks of society regardless of their faith, beliefs and ethnicity,” Rashidi informs.
According to a survey on ageing conducted by Ipsos in 2018: when asked what’s the worst thing about growing old is, globally 30% of those polled responded that they personally worry about not having enough money to live on in their later years,
So, how can we prepare for our ageing needs? It is never too late to start planning for your retirement. The rising cost of living, medical expenses and inflation should be factored into our retirement planning.
“Age is just a number. Choosing to work part-time during retirement can maintain a good mental health and earn an income,” says Dr Carol.
She also suggests the need to increase the retirement age to 65 and beyond, so that people can continue working for as long as they can. “It’s not that bad. It helps you to be physically, mentally and socially active.”
As for the younger generation, here’s a piece of advice from Dr Carol.
“Save more money than what is required by EPF. This is because when you retire, you may need your savings to help your aged parents, especially when your parents’ retirement income is insufficient to take care of their health and medical care. Get ready before the storm,” she advises.
When it comes to retirement planning, investment is one of the tools that can help us to achieve our goals. The famous quote by Benjamin Franklin rings true;
If you fail to plan, you are planning to fail!
Recently Smart Investor spoke to Isnaliyah Sarwadi, director, business development of PMB Analytics Sdn Bhd (PMBA) which is a subsidiary of Pelaburan Mara Berhad, to get her views on the topic at hand.
According to her, there are many investment vehicles to support our retirement planning, but the two vehicles that she believes could warrant the achievement of the goal are through unit trust and property investment.
Unit Trust and Property
Unit trust investment is one of the most common investment vehicles in Malaysia. It is easily accessible by everyone and it also has a very low entry barrier. You can start investing in unit trust from as low as RM100, which makes it affordable for everyone. It can also be used as a tool to invest regularly each month.
One must emphasize asset allocation and diversification strategies to benefit the most from unit trust investment. With just a small amount of money, you can already be exposed to global markets such as the United States, ASEAN, China and the rest of the world. Just ensure that it matches your investment objectives, investment horizon and risk tolerance level.
Secondly, there is property investment. With the right selection of property especially the right location, it can save you time and money to access to your work place. On top of that, price of a good property will always grow over a long period of time. When it appreciates in value, instead of selling it to buy bigger property (an upgrade of lifestyle), one may lower or maintain the lifestyle by buying two properties to accommodate two purposes (accommodation and investment).
Hopefully, when you combine these two investment vehicles, you will enjoy strong financial standing when you retire. These investments can also be liquidated and used for other purposes such as for your children’s education or to start off a new business.
Another tip by her is the new age comes with the latest technology. You must equip yourself with new skills as well. If you start saving early, over time, you will have money to start great things in life as the savings will enable you to start small businesses (become an entrepreneur). Immediately, the money will provide you with working capital or a deposit to buy machinery or vehicles for transportation to start the business. In addition, it will provide you money for upskilling since you will need to attend courses of your preference, for example, culinary, bakery, saloon, sewing, massage technique, writing technique, etc.
Why Aren’t We Able to Retire Well?
The reason that some of us are not able to retire well is caused by the low awareness of personal financial planning. We tend to spend more than what we earn, which then causes us to borrow in order to carry on with our lives.
The credit card debt trap which can be a very vicious cycle. Once you are trapped as you are only able to pay the minimum amount each month, it will be very difficult to get out of it. It can snowball to a huge amount over a period of time.
It all boils down into a mismatch of lifestyle against income. Ever heard of the quote, “We buy things we don’t need with money we don’t have to impress people we don’t like.”
We also tend to fall prey to “ponzi” schemes and scammers out there. We are easily blinded by the promise of getting rich instantly and receiving extraordinary monthly returns.
Tackling the Rising Inflation and Interest Rates
Finally, we have to deal with the issue of rising inflation and interest rates. Here are some tips that Isnaliyah is kind enough to share with us. To help us weather the storm, we should do the following:
Prudent management of cash flows and personal budgeting requires you to choose wisely between needs and wants
Structure your retirement portfolio well. The investment horizon is for the long term and should the market tumble, don’t panic and don’t abruptly restructure your existing portfolio.
Invest in upskilling so that you can look for additional income streams if the need arises.
Retirement planning is something that we should not take for granted. As the years pass so quickly, especially these days, we will be staring at the day we retire very soon.
If we do not take action, we may have to work until our golden age. So do not delay; start to plan for your retirement now.
There are times when one has to spend money even when there is little to go around. Arguably, there are three areas where money has to be spent. The areas are: Parents’ Allowance, Education and Giving Back to Community. Even though this may eat into existing funds, with Smart Spending Techniques and Money Allocation, the situation can be managed.
Must Spend Money
In one’s life, ‘Must Spend Money’ falls into three possible categories:
1. Parent’s Allowance
No matter how wealthy or poor the family may be, taking care of one’s parents – whether financially or physically − is part of a child’s obligation, at least in eastern culture. After all, we have enjoyed the great sacrifice, financial support and care of our parents and when we start to work, we should contribute a portion of our money to our parents as a token of appreciation.
The parent, in turn, should accept the child’s money even when it is not needed. This can help to shape the child into a more grateful and responsible human being. This, however, doesn’t mean that we should depend on our children’s financial support, if the situation allows it, we should be fully responsible for our own daily expenses.
A psychology counselor once told me that a lot of family crises arise from financial problems (or a lack thereof) caused by the husband’s failure or patial failure to fulfil his financial obligations to the wife or family. Tracking the root cause behind each case, she found that many of the individuals were not educated on the responsibility of giving money to the parents when they were single. It explains why they do not contribute to their families when they got married.
2. Learning Fund
Learning is life-long. Always allocate a portion of your money (plus time and effort) to learning, travelling and exploring as this will help you grow and acquire knowledge. If you want to have a better life and wisdom, or upgrade from your current level, you should always continue to improve your mindset, knowledge and soft and hard skills, no matter what age.
3. Community Give Back or Charity
Open your eyes and you will see so many people living far below their basic means and opportunities. When compared to them, we feel blessed about what we have and don’t have (such as bad weather, environment, natural disaster, lack of opportunity and so on). We are a part of community, enjoying its benefits and effort so never forget to lend your helping hand to give back to those who need money, effort, time and knowledge. If you agree with the concept of the power of giving, you will understand that the more you give, the more you will receive. The rich know this concept and that is why they keep on giving out and yet, still remain very rich. Warren Buffet once said he became what he is today (Super Rich) and is able to do what he wants, because he was born at the right time in the USA. His fate would have been very different if he had been born in another country.
Smart Spending
When it comes to spending wisely, how do you do that? Here are some cost-saving pointers:
Compare, Research, Make Informed Choices
Perform two to three comparisons before purchasing. Only buy when there is a promotion or large discount and only purchase necessities. Purchase items that have been re-packaged under the departmental store or supermarket label as they are usually 20 − 30% cheaper buit just as good.
Has anyone purchased their own engine oil instead of letting the car workshop decide everything for you? You might be interested in my experience about buying engine oil. A normal brand of fully synthetic engine oil can cost above RM200 (at promotional prices, it can be around RM170++). After reading many positive comments on an online forum, I purchased a departmental store brand engine oil (imported and repackaged locally) that only cost RM80-RM100 during the promotion period. I have been using this oil for several years now and it has, to date, not caused problems. You can apply the same technique too, to almost any other item to save money (but of course, you must also take the risk).
Bulk Purchasing
Let me share with you one of my uncommon practises. Normally, I will purchase another set of shoes or clothes or necessities (during offer periods) to prevent having to purchase a replacement at the normal price when the item is worn out/broken/lost.
Another way to save cost is to skip the intermediaries like a supermarket and deal directly with the factory where you can get the items at distributor’s price. Of course, some factories don’t deal with retail or the public. However, I have purchased baby diapers from the factory where I enjoyed more savings than even the supermarket promotional prices. Of course I needed to purchase 12 packs in three boxes but I knew the items would be fully utilised within nine months. I also enjoyed the free delivery that came with the bulk order.
For daily and heavy use items, you can do the same but do not over purchase until you need to keep the items in store for a few years; you will be losing your purchasing power by storing the goods over so many years.
Purchase Pre-Owned Items
Yet another way of saving is to purchase branded second hand but in good shape items. A statistical survey on self-made millionaires in the US during 80s and 90s (The Millionaire Next Door: The Surprising Secrets of America’s Wealthy by Thomas J. Stanley and William D. Danko) showed that a majority of them preferred to buy branded, high-quality but second hand cars. Their methods can be replicated, but when applying it here, add another requirement of low mileage. (Generally speaking, the second-hand car that gives the best value is aged between three to six years).
Money Allocation
Here are some money allocation techniques according to the book Secrets of the Millionaire Mind by T.Harv.Eker. It advises you to adjust according to your situation. As a rule of thumb, we should maintain 50% of our money on necessities, 10% on investment to work towards financial freedom, 10% on Long Term Savings which you can use for future big spending like house renovation, car and so on, 10% on education-life long learning, 10% on recreation, play or any self-rewarding activities and the last 10% on giving back to community or charity.
The other guideline is to maintain a healthy cash flow by making sure our monthly debts servicing ratio (DSR) for housing, car, education, personal and credit card loans over monthly income is kept below 40%, while 10% of the positive surplus is used for savings and investment in order to grow your wealth. The money spent on purchasing insurance should be within 15% of your monthly salary.
Yong Chu Eu is a Licensed Financial Advisor/ Head of Education Division of Fin Freedom Sdn Bhd (CFP, FAR, CMSRL, HRDF Certified & SIDC CPE Training Provider). He can be reached at ceyong@financialfreedom.com.my
Estate planning is the process of anticipating and arranging, during a person’s life, for the management and disposal of that person’s estate during the person’s life, in the event he or she becomes incapacitated or dies. Estate planning involves determining how an individual’s assets will be preserved, managed, and distributed after death.
Assets that could make up an individual’s estate include houses, cars, stocks, artwork, digital assets, life insurance, pensions, and debt. Individuals have various reasons for planning an estate, such as preserving family wealth, providing for a surviving spouse and children, funding children’s or grandchildren’s education, or leaving their legacy behind to a charitable cause.
Smart Investor recently got an early access to Estate Planning Malaysia Online Practice Academy that was just launched to the public. But before we begin, let’s look at what it is all about shall we?
What Is Estate Planning Malaysia Online Practice Academy?
It is a video-based learning that you can learn at your own pace. There’s also a section where you can read articles that was published on Smart Investor’s website as well.
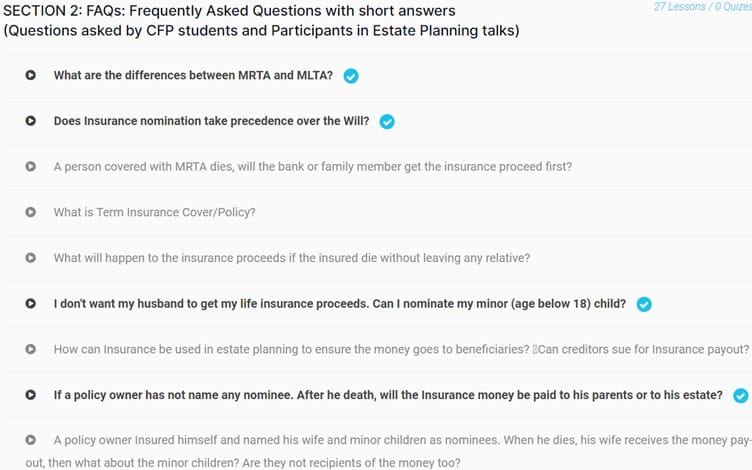
All-in, there’s 7 modules with 80 lessons contained in the platform.
SECTION 1: Weekly Zoom LIVE Tutorials with experienced estate planner, Lee Khee Chuan
SECTION 2: FAQs: Frequently Asked Questions with short answers (Questions asked by Certified Financial Planner@ CFP students and Participants in Estate Planning talks)
SECTION 5: Estate Planning Awareness Talks by Sifu Lee (recorded & presented by Lee Khee Chuan)
SECTION 6: Estate Planning Avatar Short Videos
SECTION 7: Smart Investor Articles Previously Published
The number of contents will increase over time, so that’s a bonus.
Here are 5 things that you will get from the Estate Planning Malaysia Online Practice Academy.
1. Integrated Approach To Estate Planning Course
For the first time in Malaysia, insurance agents, will-writers/estate planners/legacy planners, and CFP/RFP students/graduates who want to acquire practice knowledge of Integrated Estate Planning can now learn via this online practice academy.
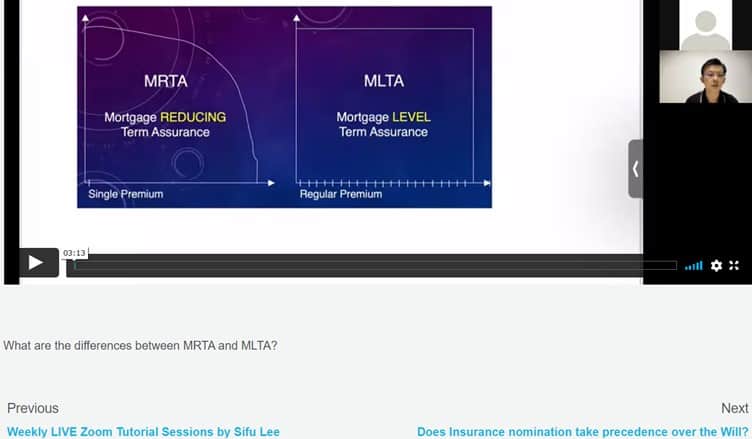
From the differences between MRTA and MLTA, to preparing a will yourself, to many other short videos that are easy to understand, all grounds are covered in this course.
2. Experienced Trainer
Lee Khee Chuan @ Sifu Lee brings with him his unique blend of academic background and experiences. He holds a B.A. with double majors in political science and psychology, and double minors in economics and Malay Studies from National University of Singapore (NUS). Since 1992, he has been in personal selling, as well as a company sales trainer, practitioner, lecturer, and columnist in estate planning.
He is a trainer, practitioner, and lecturer in the financial & estate planning industry since 1995. He has much to contribute to the industry with his writing, lecturing, practice, and training. His forte is in practice management focusing on integrated approach to estate planning. He brings his many years of practice experiences to this Online Academy and to impart and transfer his knowledge to his students.
He is the first financial adviser in Malaysia who advocates and promotes the integrated approach in estate planning. Hi strength lies in the integrated and practical aspects of estate planning. Many of his CFP students like his practical teaching and training methods in estate planning.
Made by the expert in the industry himself.
3. On A Platform That Is Very Easy To Use
You get to see everything at a glance and click on the content that you want to learn the most. Or you can follow step-by-step, completing it at your own pace.
Once a lesson is completed, it will be marked as complete which is useful so that you can track your own progress.
You can easily watch the previous video or click next to continue with the lesson.
4. In Layman Terms
It doesn’t get any simpler than the explanation by Sifu Lee himself. Don’t worry if you don’t have any financial background or estate planning in general, it is being presented in layman terms that is very easy to understand by everyone.
The practical knowledge combined with easy-to-understand lessons, makes for a very well-equipped understanding of the subject at hand.
5. Weekly Zoom Meeting
After you’ve gone through all the modules, you can always ask Sifu Lee via Live Zoom meeting every week. Should you have any queries about a particular topic or if you have a particular case study that you need help on, feel free to ask during this online meeting.
There will be a minimum of 40 weekly live sessions in a year with 2 hours duration per session. The value that you get from this personal touch is just amazing.
Smart Investor interviewed a few students who have enrolled in the online estate planning practice course and are learning the subject online. Angel Lee, a life insurance planner from Malacca was excited when learning it using the online portal.
She really loved the way those courses were prepared and presented, starting by highlighting the issues in estate planning insurance agents and estate planners often overlook. And then the video-ready lessons would provide the answer those questions. The master trainer’s teaching was clear, yet detailed, and she loved the many examples discussed in the online course. The examples are invaluable and help discover how estate planning can be applied to meet clients’ concern.
Adrian Lean, a unit trust and PRS consultant from Penang, found the estate planning course a comprehensive program and contains practicable knowledge typically sought by not only those interested in estate planning, but also for those who wish to expand their knowledge in this area. The course curriculum contained many gems, and he especially liked the unique integrated approach and the solutions presented in the course.
Overall, the course is a value for money package, and carries a distinction above other programs in the market today. He congratulated the academy and the master trainers who have done an excellent job in raising the benchmark for the estate planning industry in Malaysia.
Early Bird Discount If You Start Now
We all know how Malaysians love discounts, fret not. Estate Planning Malaysia Online Practice Academy in partnership with Smart Investor now offers a SPECIAL discount for 1st year for those who act now.
When I joined the financial industry in 2017, I was so lucky to meet my first customer. Not just because of the first investment business he gave to me, but also the lessons that he taught me.
I remembered the day when I first met him, I was introducing a unit trust fund to him, and he agreed to invest immediately after I finished my explanation. Since he was my first customer, I was being extra careful to avoid any mistakes in the process.
I asked him every question in the suitability assessment form:
Do you have investment experience in the past?
Do you understand about the investment risk?
How many percent of fluctuation can you accept?
Do you read and understand English?
The customer suddenly slapped the table, and said: “Why do you need to ask so many questions? Other banks did not ask all these questions when I invest with them! I told you, I’m ready to take risk when I invest. I can even accept the RM100k investment becoming a total loss.”
Knowledge Is Power
People may think that when one gets older, he/she should be less aggressive in investment. But this customer taught me that when one is fully equipped with knowledge, he/she will be able to make an informed financial decision despite of his/her old age.
Later, the customer topped up his investment after his first investment made profit within five months. But this time, the market was not going as smoothly as the first time. The unit trust fund was badly hit by the US-China trade war in 2018. The fund dropped ~20% in the first year of investing.
I asked the customer whether he want to switch his investment to other funds that were not affected by the US-China trade war?
Surprisingly, the customer did not worry about the paper loss of 20%. He told me that it is normal for the market to be up and down. He does not want to switch the fund because he has belief in China, and he is confident that the fund will rebound; and he has the holding power and patience to wait for it.
A year later, the fund recovered and the investment broke even at the end of the second year. 6 months later, the fund then made a 20% return. The customer was very happy with the annualised return of 7.63% after waiting for two and a half years.
Patience Is Key
Hourglass on dark background
In reality, most investors might quit the market and cut loss when the fund is at ~20% loss. Some investors might withdraw their investment when the fund finally breaks even at the end of second year. Only a few are able to see the return after waiting for two and a half years.
The customer taught me another lesson that when one has a clear investing goal and strategy, he/she will not worry unnecessary about the market’s volatility, he/she will always stick to the initial plan without making emotional decision.
It has taught me the importance of financial literacy and it resulted in my faith to become a licensed financial planner a few years later.
Thanks to my customer, I’m now a licensed financial planner currently and I’m also conducting financial management workshop regularly to educate Malaysians on financial literacy.
About the Author
Angel Chan is a Licensed Financial Planner attached to UOB Kay Hian Wealth Advisors Sdn Bhd. Besides providing comprehensive financial advisory to her clients, she is also committed to educate the public about the correct financial management mindset and methodology through article, YouTube video and Financial Management Workshop conducted by her and her team. Do reach out to her for more information.
The death of your loved ones is a terrible event, but it can’t be avoided and it’s a reality that we have to face. If you are married, it is your hope and wish that you and your spouse will get to grow old together.
But if it is fated that he or she passes away prematurely while we are not ready, here are 5 things that you should know.
1. Can I claim alimony (nafkah) for maintenance of myself or for my kids from my late husband’s estate?
It is a man’s obligation to provide for his wife and kids while he was still alive. But once he passes away, you can only demand for alimony from his estate are those that are overdue only while he was still alive.
Any claim of the unpaid alimony can be filed in the Shariah Court. You will then need to present the court order to the estate’s Executor/Administrator for the purpose of payment.
2. I have access to my husband’s bank account. Can I withdraw the money inside and use it to carry on with my life?
All the wealth of the deceased is considered as inheritance. The priority is to pay off all debts and for the expenses for giving out the inheritance. If there is balance, then it will be distributed to the next of kin.
If a family member needs the money to carry on living before the above is taken care of, then it requires the approval from all the heirs before it can be used. The amount that can be taken is the one allowed for her share of Faraid entitlement out of the total estate.
If it exceeds her share, then she needs to repay it or get consent from all heirs to allow it to be used.
3. My husband puts my name as the nominee for his Employee’s Provident Fund (EPF)/Tabung Haji/Takaful, can I use the money for my own benefit?
A nominee for his EPF does not make you the beneficiary. A nominee can only act as Executor/Trustee for the money and it can’t be used for your own benefit. Instead, it must be used for the administrative part of the estate and if there are any balance left, then it must be distributed according to the Syariah law inheritance to the respective heirs.
If an Executor/Administrator for the deceased’s estate have been appointed, it is better to surrender the money to ensure the transparency in administration and distribution of the estate, as well as to avoid conflicts.
Whereas a nominee for his Tabung Haji or Takaful depends on the type of nomination. If it being named on the basis of Hibah, then you can receive the money as beneficiary. But if the nominee is on the basis of Executor/Trustee, then you need to act in accordance of a nominee for EPF as mentioned above.
4. What are the steps to get a bigger portion from my share of Faraid?
Husband or wife of the deceased can make a claim for Matrimonial Asset (Harta Sepencarian) in the Shariah Court for the wealth that was acquired while you are both married. Through these claims, you are able to get a portion from the Matrimonial Asset that is decided by the Shariah Court as well as the portion based on Faraid.
5. What should I do if I was appointed as a trustee for my children’s estate who is still a minor?
All immovable property that is inherited by under-aged children needs to be registered under your name as a trustee.
For cash, it is best that you open a trust account for the children to be transparent. You need to ensure that the money will be managed and used for the welfare of the children. A trustee must be meticulous and make records or keep receipts on its usage and it must be used for the benefit of the children.
A Huge Burden
In managing the estate of someone who has passed away, the main objective is to ensure that the debt and expenses needs to be administered first, before the distribution can be made of what is left. Therefore, estate planning is very important, not only to ensure that the estate is managed well, but also to ensure the well-being of heirs is taken care of.
About the Author
The article is written by Ms Rahimah Binti Sazali, Assistant Manager, Estate Management Department of as-Salihin Trustee Berhad. as-Salihin offers full-fledged Islamic Estate Planning products and services such as Wasiat writing, declaration of Hibah, jointly acquired asset agreement, takaful trust and living trust.
Perhaps, if you are reading this, you might be in the midst of making some financial decisions. They could be:
Should I use EPF Account 2 to settle my mortgage?
Should I invest my bonus first or settle my liabilities?
Should I invest in unit trust, stocks, or properties?
Should I buy a new fancier car or a bigger house?
And, the list goes on. You get the idea.
Most people may be overwhelmed by them as a decision either way will move you forward or backward financially. Understandably, many will choose to procrastinate because it will seem to be the “safer” option since many financial decisions can be irreversible.
However, here’s the real problem: How do you make smarter financial decisions if you are not equipped with the right tools to make them?”
Here is a straightforward technique that we believe will be helpful for you to make sound personal finance decisions. The tool is known as the “Return on Net Worth Analysis” or RONW.
What is RONW?
RONW tells you how efficient you are in using capital. It is quite similar to the ROE (Return on Equity) ratio we often look at when analysing corporate financial statements.
Calculating Your RONW
Here is how to calculate it:
Step 1: List down all your assets and its value, including the projected return rate of each asset, such as “REITs − RM10k − 6%”, “Cash − RM20k − 3%”, “Rental Property − RM300k − 8%”, etc.
Step 2: List down all your liabilities, including the effective interest costs, such as “Credit Card − RM5k − 18%”, “Mortgage − 200k − 4.5%”, etc.
Step 3: Calculate the RONW
RONW = (Total return – total interest) / Net Worth
We have a full video demonstration. You can google “RONW KCLau” to find it on my website.
What does RONW Tell You?
If you have calculated your RONW and discovered:
Your RONW is Negative:
It means your net worth will shrink every year. You may start by clearing out debts with high interest rates such as personal loans and credit card debts to ease your financial burden. Then, you may follow up by adding productive assets to further improve your RONW figures from negative to positive.
Your RONW in Positive:
Congratulations! You have more productive assets than liabilities. If your net worth is still small, then, you may continue to grow both your net worth and your RONW. If both your net worth and RONW is significant, most likely, you are wealthy and are enjoying financial freedom.
Let’s say you have RM30,000 in your EPF account 2 and you are considering withdrawing it to clear RM30,000 off your mortgage. Is this a smart financial move? Let’s see. Based on the RONW, we would consider:
Returns from EPF:
RM30,000 x 6.9% = RM 2,070.
Interest Payable from Mortgage:
RM30,000 x 4.5% = RM 1,350
If you withdraw EPF to clear mortgage, we would save RM1,350 in interest payment but will forgo RM2,070 in EPF dividends. Thus, you would net out RM720 per annum if you go for it. Hence, the answer is a straight “No” based on the RONW formula.
2: Should I Invest or Settle my Liabilities?
First, it depends on how good you are as an investor and what liabilities you owe currently.
For instance, let’s say, you are a good stock investor who knows how to make 6% dividend yields from your stock investments. You have the following debt such as credit card debt of RM10,000 where the interest rate is 18% and PTPTN loan of RM10,000 where the interest rate is 1%. Today, you are given RM10,000 to either invest in stocks or pay off any of the two debts mentioned. What should you do?
The answer is obvious. You pay off the RM10,000 in credit card debt because its interest rate is higher than the 6% dividend yield from investing in stocks.
But, if there’s no outstanding credit card debt, then, you may invest in stocks that pay 6% in dividend yields as it is higher than the 1% interest charged by your PTPTN loan.
3: Should I invest in Unit Trust, Stocks or Properties?
Your investment objective is to maximise your RONW safely without taking unnecessary risks. So again, it depends how good you are in investing in unit trusts, stocks and properties. Some seasoned investors go all out to invest in stocks and properties.
4: Should I Buy a Fancier Car or a Fancier House?
Let’s start with a fancier car. Apparently, a car depreciates over time. But, the amount of your car loan and interest payment will increase after you’ve purchased or upgraded to a new fancier car. So, should you refrain from getting a brand new car? If you are now into improving your RONW, then, don’t do it. But, if you are not, then, you may go for it if it makes you happier.
Meanwhile, a fancier house might not affect your RONW as severely as having a more elegant car as properties appreciate over time. Nevertheless, you will still end up with lower RONW after upgrading to a bigger house.
Again, there is nothing wrong with upgrading your home as it does bring more joy to your family. RONW is a measurement of the efficiency of your capital and not the level of your happiness.
In conclusion, RONW is very similar to the way we look at the ROE of a company. Value investors love to hold shares of stocks with high ROE because that shows the efficient use of shareholder’s fund. On the personal level, if you know how to maximise your RONW, you will be doing way better than 95% of the population.
About the author
This article is co-written by KC Lau and Ian Tai.
Ian Tai is a Dividend Investor. Financial Content Machine. Producer of 200+ Articles, Weekly Host and Presenter at KCLau.com. Co-Founded DividendVault.com, an online educational membership site that empowers retail investors to build a stock portfolio that pays rising dividends in Malaysia and Singapore.
KCLau is a financial educator, having published seven books including the current bestseller Money Smart, and co-created a dozen online financial courses. He gives away his popular Money Tips e-book volumes free at his website: https://KCLau.com
For many Malaysians approaching retirement or already retired, one of their biggest fears is having a massive hole blown through their nest-egg which they have painstakingly built up over the decades to see them through their golden years.
For many people, the situation becomes even more tenuous as their retirement funds are barely sufficient to provide a comfortable level of living or last till end of life.
Two of the major risk factors that can reduce individual retirement savings are health and income shocks, says Mohd Sedek Jantan, head of Investment & Financial Planning / Investment Unit at UOB Kay Hian Wealth Advisors Sdn Bhd.
Health shocks are defined as unpredictable illnesses that diminish health status, he says. “Individuals facing health shocks are often affected by significant out-of-pocket (OOP) healthcare expenditures incurred to obtain healthcare and the income loss from an inability to work.
“The OOP spending has particularly serious effects on poor households, who tend to spend more on healthcare as a share of their income compared to their richer counterparts,” he says.
On the other hand, income shocks are referenced by how many significant drops in income a person has suffered over their working career, says Mohd Sedek.
“For example, the current Covid-19 pandemic has caused the unemployment of large numbers of people, while others are facing pay cuts. The income shock during the pandemic is more severe among young adults.
“Income shocks are strongly associated with an expected spending reduction and, at a certain level, the individual will liquidate their savings in order to put food on the table.”
Mitigating Against The Risk Factors
Mohd Sedek says like other expenses in retirement, planning can make a difference in managing such risks. He says healthcare costs influence retirement income planning, and as such, the impact of rising healthcare costs should be a priority consideration.
“The most economical way to absorb the health shock is by changing lifestyle,” he adds.
He says research studies on people’s behaviour have shown a causal relationship between unhealthy lifestyles and healthcare expenditure, where individuals who practise unhealthy lifestyles need more healthcare services, forcing them to spend more on healthcare expenditure.
Taking steps to improve health can reduce annual medical expenses, he adds. In the case of Malaysia, hypertension stands as an important area of worry for economic evaluations because of the wide range of issues involved for the individual and for society.
“It is one of the most expensive diseases as far as treatment is concerned, as it generates higher healthcare expenses than those produced by individuals with normal blood pressure.”
However, he notes there is a reduction in total direct costs of the hypertension population if each patient’s blood pressure becomes controlled.
“This reduction in direct costs can be achieved by changing lifestyle habits, for example: reducing dietary sodium intake, decreasing body weight, quitting smoking, and reducing alcohol intake. In addition, anti-hypertensive medications can lower the risk of cardiovascular mortality in hypertensive individuals,” he adds.
High Cost Of Medical Insurance
R. Sathia, co-founder and CEO of GFlex40, a Malaysian insurance technology company, concurs the highest risk factors that would lead to reduction of wealth for a majority of Malaysians are health issues, either for themselves or their closest family members.
“As it has been well researched, the cost of medical insurance in Malaysia is among the highest in Asia and continues to rise,” he adds.
He points out that Malaysia also suffers from among the highest obesity rates in Asia. “The risk factors increase chances of individuals falling ill, and when combined with the cost of healthcare can quickly result in depletion of any savings that have been built by individuals,” he adds.
To reduce the risk of this happening, Sathia says that apart from investing in maintaining one’s own health by way of exercise, diets, etc, another supplementary and important mitigant would be investment in the appropriate health or medical insurance plans.
“By procuring such a plan early in life, individuals can ensure they are covered for unforeseen circumstances later in life,” he advises.
For the individual there is little they can do to prevent the rising healthcare cost across the board in the market. “However, on a personal level, everyone can work towards limiting their exposure to such costs by living a healthy lifestyle from early in their life,” he says, adding this would include proper healthy diets and exercise.
Sathia notes that exercise is a particularly interesting topic when it comes to health/medical insurance.
“More and more insurance and Takaful companies are investing in health and exercise related insurances that track the lifestyle and exercise habits of customers through the use of electronic gadgets and apps.
“By availing oneself to such an insurance early and leading a healthy lifestyle, not only would the average person be able to improve on their overall health but they can also potentially reduce their own premiums as a result of their healthy lifestyle.
He also says there have been efforts across the world to factor in lifestyles and exercise behaviours through electronic monitoring as inputs in pricing health and medical insurance by technology driven insurance companies.
“These efforts coupled with efforts to optimise operations of third party administrators and hospitals would eventually be able to lead to a reduction of pricing,” he adds.
Wealth Protection Measures
So, whatcan we do to prevent rising healthcare costs from eroding our retirement nest-egg?
UOB Kay Hian Wealth Advisors’ Mohd Sedek says reviewing one’s current insurance plan is vital to ensure it does not eat up the retirement saving.
“As healthcare costs continue rising, it is important for each individual to have life and medical insurance. According to the Employee Benefit Research Institute (EBRI), healthcare expenses are the second largest component, and these expenses steadily increase with age.”
Further, it is important for the policyholder to review their insurance policy from time to time, to ensure having adequate protection for the future and safeguard the income-earning abilities.
Sound financial advice also plays an important role when it comes to retirement planning.
“Individuals, regardless of their income level, should engage with a certified financial planner to ensure the retirement saving is not just sufficient but also sustainable, to hedge it against healthcare cost,” advises Mohd Sedek.
A financial adviser, he says, will review the individual’s overall financial situation and address the solution based on their needs. From the analysis, the financial planner will help the individual to address the challenges by:
Estimating their expected out-of-pocket healthcare expenses, such as insurance premiums;
Creating contingency plans for unexpected expenses such as long-term care; and
Working closely with the client to help protect their wealth by integrating healthcare costs into the overall retirement plan.
He adds there are a number of insurance types and riders that can help to hedge the rise in healthcare costs, such as investment-linked products, medical card, critical illness coverage and specific elderly insurance.
In addition, the financial planner can explain the cost–benefit for each insurance plan, creating trust funds and other advanced planning strategies.
Risk Management Needed To Absorb Income Shocks
To mitigate against income shocks, individuals should do planning that includes matching up income streams, including guaranteed income, to fund recurring healthcare expenses such as insurance premiums.
Individuals may also plan on maintaining an emergency health savings fund for non-recurring health expenses, says Mohd Sedek Jantan, head of Investment & Financial Planning / Investment Unit at UOB Kay Hian Wealth Advisors Sdn Bhd.
Also, delaying withdrawal from the EPF can create a larger monthly benefit. “Hence, personal budgeting is important to achieve a clearer vision of personal finances so you can begin to plan your spending and saving and take control of your money.
“In short, budgeting helps you to ensure you have the right amount of money at the right time.”
And when doing budgeting, both regular events and extremely uncertain events must be dealt with. It is advisable for individuals to set aside at least six to nine months of living expenses in a money market account, one that offers liquidity and the safety of the principal.
“An emergency savings fund should be established so you don’t have to consider tapping your retirement savings,” he adds.
Dealing With The Medical Insurance Conundrum
If they can afford it, it is prudent for senior citizens to have medical insurance as it can help offset the medical expenses that they’ll incur as they age.
However, the flipside is that medical insurance premiums increase dramatically as we grow older, ironically at a time when we are no longer generating income.
So, is there a way out of this predicament?
Mohd Sedek Jantan, head of Investment & Financial Planning / Investment Unit at UOB Kay Hian Wealth Advisors Sdn Bhd, notes that age is one of the prime elements in the health insurance premium calculation because it impacts the medical support a policyholder may require.
It is significant to understand that an elderly insured individual will possess medical conditions quite different from those of a young or adult insured individual, he says.
“Typically, the premium amount increases on average about 5% to 8% for every year of age; it can be as low as 5% annually if you’re in your 40s, and as high as 12% annually if you are over age 50,” he says, adding that high-risk health status also has the potential to greatly increase costs.
As such, Sedek says it is advisable to buy health insurance “at a young age to avoid high insurance premiums”, as the policyholder is able to lock in lower premiums and reduce the total amount they will spend on life insurance over the course of a lifetime.
Advancement in technology is changing the way care is delivered; allowing elderly consumers to apply self-directed care, while availing healthcare professionals access to information essential to the healing cycle in an instant. Furthermore, technology allows for aged care businesses to answer consumer demand in areas that were previously difficult to access.
Frost & Sullivan stated (Major Trends & Attractions In The Global Aged Care Market, 2015), that increased use of technology in the aged care market not only has economic benefits, but enables the ageing populace to enjoy better quality of life. Consumers and care workers alike would have a smoother journey in the care experience when care is delivered to where and when it is needed.
Ageing populations around the world are rapidly growing and aged care businesses need to capitalise on this technological boon to succeed in the future. Hence, increasing attention is being given towards developing new technologies that will help capture quality data.
Taking stock of the local environment, let’s look into three key areas in healthcare that technology progress will enhance and propel news levels of consumer demand and quality service.
Living at Home Longer and Safer
For elderly people to live longer in their homes, wearable devices – such as smart bands, intelligent insoles, and so on – and smart home technologies are being developed in order to support them through improved remote monitoring.
Sensors will regularly track the individual’s health readings and feed data into a central monitor point for the overseeing healthcare professional to keep track in real-time and provide feedback/support from distant locations. In the event a possible fall or mishap occurs, an immediately response could be mobilised.
With the development of the Internet of Things (IOT), technologies that integrate various devices together have become increasingly sophisticated, to the point where sensors can alert a central monitoring system of a possible mishap if a resident of a home has not left a particular room for an unusual amount of time.
Lost and Found
Alzheimer’s Disease International reported that the number of dementia cases in Malaysia were estimated to double every 20 years. That is one new dementia case in every three seconds. Depending on the stage of the disease, persons with dementia may require 24-hour supervision.
In these cases, wearable technology is invaluable. Apart from tracking vital signs and providing reminders for the wearer to take their medication, some wearable devices incorporate GPS to track children and seniors alike, or detect if a user has been immobile for a prolonged period – in this case, it will call for emergency services or pre-set contacts numbers.
Assisted Daily Living
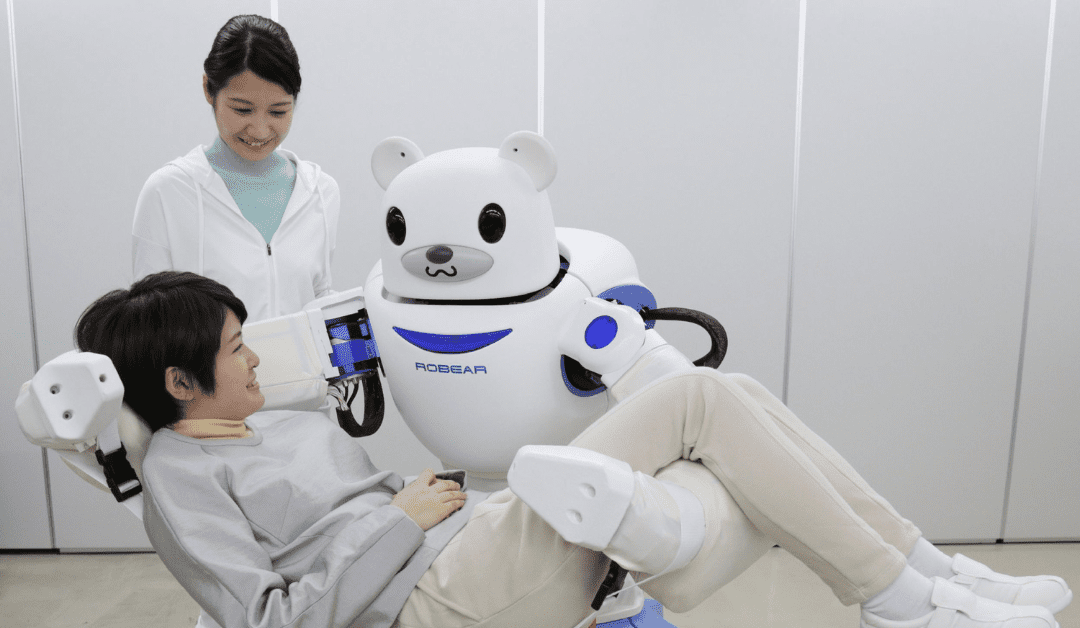
In Frost & Sullivan’s report, competition in robotics development is expected to grow intensively between 2020 – 2030. There are many benefits robotics could bring to aged care.
Robots can provide help with daily living activities such as cleaning and cooking, as well as assistance with exercise and transferring (for example: from chair to bed). They can also be companions, analyse emotional well-being and act to mitigate feelings of loneliness amongst the elderly.
In Japan, senior care robots are already being piloted. Therefore, we can expect to see more sophisticated robots in the future that could help elderly people do more and achieve better quality of life.
Technology Enhancing Care Quality
Melinda U, General Manager of Managedcare Sdn Bhd, says the ability to access and analyse well-documented information is crucial to making sound decisions for the best possible health outcomes, not only when care is needed but also for prevention.
“These technologies give empowerment to individuals by helping them to self-manage their health and to take action when alerted about a potential crisis early. For medical and healthcare professionals, it enables them to provide more timely interventions and efficient support.”
Integrating new technology into the aged care industry will create smoother processes in care delivery, provide better insights and establish superior customer care. Naturally, consumers will seek out businesses that can effectively showcase their ability to provide the best care to their clients.
Currently, there are many gaps within Malaysia’s care delivery process and aged care ecosystem in terms of efficiency and cost of care. Despite being in its infancy, Malaysia’s aged care industry is in a unique position to integrate and grow these technologies alongside its developing ecosystem.
“These technologies could cover the gap in service delivery, but they aren’t mainstream in Malaysia yet. There is still a lot of research and development going on in this area. However, Managedcare recognises its potential to complement our mission in making care more easily accessible and we are exploring these options” says Melinda.