Category: business

  • Fighting Over Equity Distribution, The Importance Of Succession Planning

    Fighting Over Equity Distribution, The Importance Of Succession Planning

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. Hopefully we can understand the importance of succession planning and make the necessary preparation.

    Elder Tan put down his chopsticks, looked up and smiled.

    His three sons and their spouses are seated together once again for a reunion dinner which the COVID-19 pandemic denied the family for two consecutive years. In the next table, the children are noisily tucking in their food and chattering away as well as occasionally peering into each other’s phones.

    Tan was a picture of contentment. He has raised his children well to be successful in their own right. He is proud of his eldest son Seong who is doing a good job taking charge of the hardware business that Tan had built from scratch. Danny, the No 2, is head of the engineering department in a construction firm while Chye, his street smart youngest son, is doing well in sales in his father-in-law’s spare parts company.

    “I want to tell all of you something…” Elder Tan interrupted the conversations at the reunion gathering.”

    Succession Planning Is About Being Prepared
    I want to retire and leave the family business to Seong,” he added. Seong looked at his father, beaming that he is getting just rewards for the hardwork that he had put in to run the business.

    “I’ll transfer the shares of the company to all three of you equally,” Tan said looking at his three sons. The expression in Seong changed on hearing that. He looked startled as he had expected the lion share for all his sweat, literally!

    “Equally with Danny and Chye! They didn’t lift a finger to help out in the business! And they now get equal share of the fruits of my toil? No way!!!” Seong now getting red faced with anger.

    He rose from his seat and smart-mouth Chye stopped him in his tracks with his remark: “What, you’re not happy?”

    The whole atmosphere changed as Seong lunged towards Chye. Danny stepped in between and after that, chaos broke out. A breakdown in family harmony over too-soon, unforeseen, unexpected equitable or inequitable distribution of family assets?

    Tan’s desire to be fair and thus, the equitable distribution of equity in the family business probably blindsided him from the possibility of a family feud erupting from it. Estate planning and succession planning needs to be skillfully handled and prudently managed to avert any unwarranted situation such as a family feud.

    Succession planning inevitably is critical for business, especially family-owned business. Business owners tend to underestimate and downplay its importance, ignoring possible downsides when they are no longer in charge. It holds true that failing to plan is planning to fail.

    A pre-planned succession such as through a Family Business Trust or a Family Foundation would be a prudent way to lay down instructions on conditions for ownership succession, management succession and rewards and conveyed impartially and professionally by an independent third-party such as a trustee would avert family feuds over inheritance.

    Three key areas need to be considered in setting up a business succession plan namely:

    • Ownership Succession. This will ensure that the shares of the family business will be protected and not likely to be fragmented over generations. The rightful heirs are clearly defined, thus enabling ring fencing against outsiders to own the family business
    • Management Succession. Successor is crucial for continuity of the family business. By having a capable candidate to be successor of the family business, it retains the goodwill of the family business and it improves the confidence of the investors, customers, and employees
    • Family Wealth Management. Proper planning and allocation of family resources effectively will maximise the benefit for each of the family members, such as in areas of financing family education, family medical and family reserves needs

    Business succession planning is an essential part of the risk planning for the business.

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.
  • How Can A Licensed Financial Adviser Help You?

    How Can A Licensed Financial Adviser Help You?

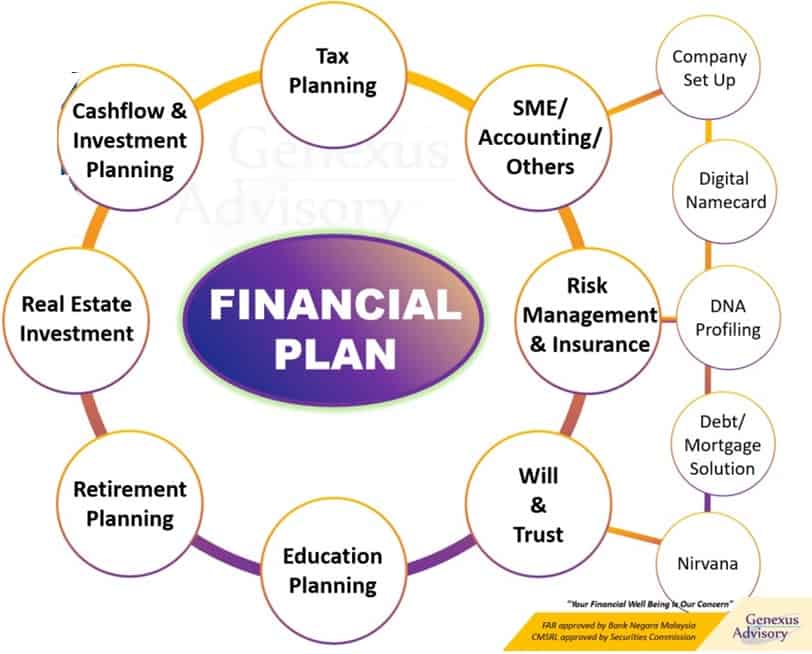
    Many people are always wondering what or who a “Licensed Financial Adviser”(LFA)” or a Financial Adviser’s Representative (FAR) is. Also, many do not understand what is a “Financial Plan”.

    Did you know that there’s only about 1,300 financial adviser in Malaysia, versus our population of 32 million?

    When their numbers are small and very little is known about them, surely a lot of myth and misconception that happens.

    How Can A Financial Adviser Help?

    Why do anybody need a financial adviser while we already have banks, insurance agents, unit trust consultants, estate planners, lawyers and accountants? What resources or values that an LFA/FAR could assist or deliver impact into their life?

    Most Malaysians have the impression that an LFA/FAR is “not focused” or “unprofessional” because he or she is able to provide financial services from multiple providers. For us Financial Advisers, financial providers are our resources and financial tools which are suggested to solve different individual or corporate needs.

    To clarify this misunderstanding, a Licensed Financial Adviser DOES NOT represent any company or financial providers. They represent you.

    All advice and solutions are solely based on your needs, and they will look into the financial market for the best financial tool to suit your life goals.

    Usually we are too busy earning money with our job or business, or too busy with family, that we barely have time to deal with their financial planning. People who are too busy making money for them to make a living, paying off debts and liabilities, is hardly able to get the latest investment updates, market outlook, insurance plans and taxes.

    Due to the lack of financial literacy and knowledge, many have become the victim of ponzi schemes or get-rich-quick schemes. This resulted in many Malaysians losing their wealth.

    Some went into huge debts, by applying personal loans, credit card cash outs, or even loan sharks and ended up a bankrupt. This is one of the reasons why bankruptcy statistics increase gradually every year. It is human nature to take risk and gamble, but why gamble when a Licensed Financial Adviser can help you better manage your finances and investments?

    Most of us gets mixed up with “investment” and “gambling”. Many Malaysians thought that investing in high-risk instruments like stocks, forex, crypto or private equities are similar to gambling. Whereas gambling is purely based on luck or a probability of winning chance.

    A good investment is when you have the knowledge and understand clearly about the instrument along with the risks and rewards. You can predict the results, whether it is an instrument that comes with low risk with low return, or high risk with high potential return. Also the time frame and financial goal or purpose of a particular investment.

    What’s even more important is to make sure that it is being regulated by by Bank Negara Malaysia, Securities Commissions Malaysia or Bursa Malaysia.

    A wise man once said, “Fast is actually slow. Slow is actually fast.” Deep thoughts, deep wisdom.

    A Licensed Financial Adviser is specialising in the Finance industry. They are well-trained professionals that are focused on Financial Planning. To deliver value to your family and businesses, solely based on your needs in order to achieve your life goals.

    Don’t wait no more, get in touch with a licensed financial adviser today.

    About the Author:

    Cheong Kwang Siang, CFP Cert TM
    FAR, CMSRL
    Genexus Advisory Sdn Bhd
    He can be contacted at cheongks@genexus.com.my

  • 3 Most Popular E-Wallet in Malaysia

    3 Most Popular E-Wallet in Malaysia

    An e-wallet or also known as digital wallet, is an electronic device, online service, or software program that allows one party to make electronic transactions with another party for buying goods and services. With the rise of smartphone usage, so does the popularity of e-wallet in Malaysia.

    Let’s check out the 3 most popular 3 e-wallet in Malaysia.

    Boost

    • Backed by Axiata Group
    • One of the pioneers in the Malaysian e-wallet market
    • Accepted at any UnionPay QR merchants
    • BoostUp Reward Programme and CashUp Cashback Programme

    GrabPay

    • Backed by Grab
    • Leverages the Grab Ecosystem for GrabFood, GrabRide and other provided services
    • Partnership with Maybank for cross platform use
    • Earn GrabRewards Points from every transaction

    Touch ‘n Go e-Wallet

    • Backed by Alipay and Touch ‘n Go
    • Taps into the large existing user base of Touch ‘n Go cards
    • PayDirect: link your Touch ‘n Go Card and pay toll fare directly with your e-wallet balance at participating highways
    • Money-back guarantee: full refund within five working days if your e-wallet is charged erroneously

    Each e-wallet in Malaysia comes with its own uniqueness. You should look at which is more convenient and brings the most benefits to you as a user.

    In terms of benefits, here’s what you can expect from the 3 e-wallet in Malaysia as per below:

    1. Convenience And Safety

    What is the first thing you take when you head out? Your wallet or phone? Frankly speaking, I will often forget my wallet, but never my phone. We heavily rely on smartphones today and with the high adoption of e-wallets among merchants, we can easily make payments without cash on hand. Besides, I think everyone has faced the awkward situation of having to squeeze the notes and “syiling” back into your wallet after receiving your change. With an e-wallet, problem solved!

    The safety of digital payments is also a concern for some, but data in the e-wallets are encrypted and some providers even provide money back guarantee features to ensure the safety of using their services. It can be also argued that e-wallets have helped to reduce theft cases, which usually occurs with physical cash!

    2. Spending Tracker

    Do you always get shocked when checking your bank balance? Clueless on where the money has gone? You can easily check your e-wallet where all transactions made are recorded. Gone are the days of forgetting where you spent your money. Keeping track of your daily spending is crucial to cultivating good financial habits. This provides an overview of your spending patterns and insight as to where you could improve.

    3. Promotions And Rewards

    While having many e-wallets has been confusing for some, the war to acquire users has been beneficial for us consumers. All e-wallets offer their own rewards, and it’s up to you to make the most of it:

    • Boost allows you to earn BoostUp coins with every transaction and exchange for gifts
    • GrabRewards Points comes with an extendable validity feature which technically makes it technically a “never expiring” points system (every point-earning transaction will extend the expiry date of your GrabRewards points till the last day of the 3rd month)
    • Touch n’ Go e-wallet rewards frequent user with cashback vouchers for selected merchants 

    All the e-wallet players partner with various merchants to provide attractive promotions to users in a bid to increase their market share. So look out for where you can save and earn through regular activities like refueling your car, buying groceries or even reloading your mobile credit. But please don’t use these promotions as an excuse to spend more than you need to!

    4. Private Assistant

    Paying your utility bills? Use e-wallet!

    Topping up your mobile credit? Use e-wallet!

    Sending money to your spouse? Use e-wallet!

    The utility of e-wallets is increasing by the day, and are no longer just avenues for sending or receiving money. Many can be used to pay for your parking, buy insurance, settling utility bills and more! There will be definitely more that an e-wallet can do in the near future.

    About the Author

    Ocean Pon is a Licensed Financial Planner and likes to help millennials make wiser financial decisions to achieve financial independence. He can be contacted at oceanpon@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth

  • Banking For Expats In Malaysia, 6 Things You Should Know

    Banking For Expats In Malaysia, 6 Things You Should Know

    It has become increasingly difficult to move money anywhere around the world, and it is set to get tougher. Fraud, cyber security, tax and compliance procedures, amongst other rising trends, are creating obstacles. Traditional banks are being marginalised by digital transformation in banking and non-banking sectors, with the ease of moving money around with crypto wallets, in Malaysia, and worldwide being a prime example.

    So, if you are an expatriate in Malaysia, or thinking of moving to Malaysia, you may be left wondering what’s the best option for banking.

    Let’s check out banking for expats in Malaysia.

    1. Setting Up A Bank Account

    Abstract blur and defocused hotel lobby interior for background

    Opening a bank account as an expatriate in Malaysia is straightforward and fast, if you have the relevant paperwork. If you do not then it is not possible. If you are employed in Malaysia, then you will be able to open a bank account at a local Malaysian, or international, bank.

    If you are not employed in Malaysia but own a residential property, then you should also be able to open a bank account. If you are considering starting up your own company in Malaysia then it is best to check that it will be possible to open a corporate bank account in Malaysia before you take the time and expense to establish a legal identity.

    Due diligence on several aspects of opening a company should be done in Malaysia, and in any other Asian countries, before you decide to proceed. You may find that it is possible to open a company but not possible to open a corporate bank account in Malaysia, or elsewhere. Check before you get started on the incorporation to avoid wasted effort and expenses.

    2. Banking For Expats: Multi-Currencies

    Caution should be exercised when you open a multi-currency account in Malaysia, or anywhere in the world. You may find that, despite having a choice of accounts to keep your hard-earned currencies in, when you transfer foreign currency from abroad your bank in Malaysia will convert all currencies into Malaysian Ringgit initially.

    This is fine if you intend to spend most of your money in Malaysia, but if you want to hedge against currency volatility then you may lose out on any initial transfer on the exchange rate and on currency risk.

    3. Digital Wallets

    ebelia rm300 million e-wallet credit

    Digital wallets are hot. They are useful too. If you have not already tried using one, or more, digital wallets, then what is stopping you exploring? There are currently over 40 similar providers but this space is likely to reduce to a few niche players in the future.

    The Covid-19 pandemic has accelerated the adoption of e-money payments in Malaysia, and globally, with transaction value crossing RM30 billion (between January and September so far in 2021, according to data from Bank Negara Malaysia.*

    Points earned from spending through your e-wallet may be going to waste and if you look at the amount of money you, and your family, will save in a whole year using e-wallets then this may be a good motivator. E-wallets also mean you do not have to handle cash for shopping and small purchases.

    Read: What are The Many Benefits of E-Wallets in Malaysia?

    4. Fraud And Cyber Attacks

    The two major security issues a local or an expatriate faces with their bank account in Malaysia, or anywhere in the world, are fraud and cyber risks. Malaysia is reportedly a leader in cyber security amongst Asian countries. Does this really mean your bank account is safer in Malaysia than somewhere else?

    Reportedly, Malaysia leverages policy capacity with a broad network of international intelligence alliances to rate highly in the cyber-power rankings. Malaysia came in fifth out of 194 states in the 2020 Global Cybersecurity Index constructed by the International Telecoms Union, a United Nations agency.

    With 98.06 out of a possible 100 points, Malaysia was only fractionally behind Singapore and South Korea, and equal with Russia and the United Arab Emirates. It has been in the top 10 since the first report was released in 2014. However, the best way for you, and your family to prevent losses through cyber attacks is to be vigilant when banking online.

    5. Benefits Of Domestic And Overseas Credit Cards

    credit card 101 rules

    Cashback is one benefit of shopping with a local Malaysian credit card. If you are an expatriate and want to make the most of your earnings in Malaysian Ringgit then it is probably a good idea to spend most of what you earn in Malaysia. From time to time, a few countries may not allow you to exchange your hard-earned Malaysian Ringgit for foreign currency when you travel overseas, or the exchange rate may be unfavourable.

    If you are sending Malaysian Ringgit savings back home, or to an overseas investment, then you may also be caught by a dip in the value of the Malaysian Ringgit. Remember, it is usually best to have more than one credit card just in case there are simultaneous cyber and fraud attacks on both your credit cards at the same time, leaving you stranded overseas without means to pay for a night out or accommodation.

    Some international credit cards offer no international currency charges, as well as favourable exchange rates, so take a look around at what is on offer. You may find that using an overseas credit card in Malaysia is low on cost and favourable on exchange rates.

    Read: How Credit Card Works in Malaysia: Credit Card 101-Know the Rules Before Playing The Game

    6. Money Transfers

    Most banks around the world now require that you give a reason for any money transfer from your own bank account to a third party. Any bank transfers of a substantial sum must be investigated by the bank and a report made to the central bank, Bank Negara.

    You can save yourself time, money and stress by making money transfers of small amounts, less than US$10,000 or foreign currency equivalent, if you want to avoid unnecessary hassle. Some crypto currency wallets do not require you to state a reason for your money transfer and, if you have not already tried, you may be interested to transfer funds around the world using cryptocurrencies.

    It is not as difficult as you may think with many transfers simply requiring you to cut and paste an ‘address’ into their portal, then press send.

    A lot of wasted time and money is not down to banks, it is down to you. Becoming more aware of the benefits of non-bank and digital banking options, and their associated risks, could save you pennies or earn you pounds.

    So there you have it, the available options on banking for expats in Malaysia.

    About the Author

    Dr. Jonathan Di Rollo (PhD Econ) has been actively and passively investing in Asian markets for more than 20 years.

  • The New Heir: Managing Your Inheritance

    The New Heir: Managing Your Inheritance

    Managing an inheritance can be life-changing and for many people, as it can open up many new possibilities. The biggest question one would probably face, therefore, is how your new inheritance should be managed to benefit you the most.

    Whether wealth management is something that you are familiar with or whether your inheritance suddenly puts you in an entirely new financial situation, receiving a substantial amount of money or a property can be overwhelming if you don’t know what to do with it.

    With that in mind, Smart Investor spoke with experts to give you a clearer understanding on managing your inheritance.

    Set Up a Trust

    Azhar Iskandar Hew, Group Chief Executive Officer of Rockwills Trustee Berhad

    If your inheritance comes in the form of cash or property, the best way to handle an inheritance from the perspective of the heir, would be to cooperate with the executor or trustee on obtaining details required for probate application and to track the progress of the estate.

    Upon receiving the inheritance and if the inheritance comes in the form of cash, one option is to set up a trust with a professional trust company. You then execute a trust deed in which the terms for the use of the cash can be clearly written down.

    At the same time, the heir can also mention who should inherit the cash and how it is to be distributed, should anything happen to him. This way, the heir or settlor of the trust would have control over the distribution or usage of the cash.

    Some of the main instructions in the trust can include directing the trustee to pay for the settlor’s maintenance, medical bills, children’s education and family’s living expenses on a regular basis. By doing so, the money will not be given to anyone in one lump sum which can be wrongly invested or misused.

    Of course, another advantage of a trust is that unauthorised persons will not be able to touch the cash, as only the named beneficiaries can receive the money.

    It’s All About Priorities

    inheritance

    Kenney Khew, CFP
    Philip Wealth Planners

    Upon receiving your inheritance, you should first of all, list down all your financial goals and prioritise them according to your preferences.

    Put aside an amount (at least 6 months of your gross salary) into an Emergency Fund. This is recommended, as you would then have money to fall back on in the event of an urgent matter that is out of your control.

    With the cash you should also pay off your debts, including your credit card debts, outstanding housing loan, car loan, student loan and any other personal loans.

    It is also recommended that you put aside an amount of money for your children’s education fund according to the calculations made based on future values of tuition, transportation, living, and course fees. In this case, you must also take into consideration the inflation, as well as exchange rates.

    Be sure to also purchase a term life insurance of up to 80 years old. The rule of thumb is for the sum insured to be 10 times your annual income. A medical insurance plan is also important in this context. By doing so, you will be able to protect your assets against mishaps as to not affect your future plans.

    The remaining money can further be used to invest in properties. You can rent out these properties to earn extra income and what’s more, this is a form of passive income that would benefit you in your golden years.

    I Just Inherited a Property – Now What?

    inheritance

    Gor Sheau Shuenn, CFP
    Blueprint Planning

    If you’re lucky enough to receive an inheritance, you should consider what the assets are and how much you will be receiving. If cash is the legacy you’ve received, it should be invested in a proper mixture of different portfolios, as otherwise, liquid assets are bound to be spent too frivolously.

    However, if the inheritance you will receive comes in the form of a property, there are a few factors that need to be considered:

    1. Has the mortgage of the property been paid off in full; if not, what is the loan repayment amount?
    2. Is the property currently being rented out? If so, is the rental yield positive?
    3. What are the appreciation possibilities of the property in the future?
    4. Who is going to manage the property, and will the return be able to cover the maintenance cost?             

    If all answers to the above questions point to a resounding ‘yes’, the property will be all the more attractive as you will receive rental income and capital gain for the disposal of the property.

    At the end of the day, it doesn’t really matter whether the legacy you’d inherited comes in the form of cash or property. All that matters is how the legacy can assist you in shortening the period of time you will need to achieve your financial goals.

    The Financial Planning Factor

    inheritance

    Kevin K.M. Neoh, CFP CERT TM
    MBA, VKA Wealth Planners Sdn Bhd

    It is perfectly normal to do nothing while you consider what to do with your inheritance. Ride out the emotional period and contemplate what you hope to achieve from this fund or inheritance with a clear mind to avoid mishandling or making poor decisions. Even if it means waiting for a couple of years as you do some soul-searching, go for it.

    Should you be the sole beneficiary of this inheritance, why not consider investing or managing it based on your financial plan, or in a manner that will support your life goals and values? Proper management and budgeting is important to ensure that the windfall will not be squandered unnecessarily.

    While you sit on your inheritance, it is also important to note that inflation will erode the purchasing power. Therefore, the need to find an instrument that can yield at least above inflation rate is important because it tends to shield the inheritance from being eroded by inflation.

    Don’t change your plan or your spending habits just because you have received an inheritance. In fact, try to use this as an added advantage to help you realise your life and financial goals.

    Making the Most of Your Inheritance Money

    inheritance

    Yong Chu Eu, FAR, CMSRL, CFP®, Shariah RFP
    Founder, managing director and principal trainer of Money & Life Academy

    Your inheritance can be divided into 3 parts:

    a) Untouched – This portion of your inheritance money can be put into liquid investments (property, insurance, PRS or EPF) and locked down

    b) Investment – Done according to your risk profile and availability of knowledge and time. You can also purchase stocks or unit trusts with the purpose of growing the money, or use it to start a business in a field that you are passionate about

    c) Spend – upgrade your lifestyle with comfort, quality and safety in mind, further your studies, clear off your debts, travel, or give back to the community

  • Financial Management Basics In 3 Steps

    Financial Management Basics In 3 Steps

    Despite the well accepted fact that everybody has unique circumstances, in general each of us should do the following in order to have a solid financial management:

    • Establish an emergency fund;
    • Ensure sufficient insurance coverage is in place for your dependents in the event of death or at the onset of critical illness;
    • Ensure you and your partner have wills on how your estate should be distributed in the event of death.

    Emergency Fund

    financial emergency

    The foundation to a great financial management is that we should set aside some money or follow a disciplined effort to build up an emergency fund that is equivalent to at least 6 months of our income. For a safer and secured future, you may want a buffer of 9-12 months and more if you have a young family.

    It does not always have to be an accident or hospitalisation. Many times, we associate emergency funds with these events.

    There are many other forms of emergency or unexpected events such as usual sickness, retrenchment, dental issues, or when one is out of job after resigning and yet to land a new offer.

    This emergency fund should be kept in a deposit or money market account, which will give ease of liquidity when it is needed.

    With adequate emergency funds backing you up, things could not possibly go too wrong as you have a buffer to support you through the rough tide. Thus, it is advisable not to invest any of your savings until you have accumulated this buffer fund.

    Insurance Coverage

    financial insurance

    Just think about how much is needed to settle your debt today if something untoward happened to you? Most of us have mortgage, credit card, study loan (such as PTPTN), hire purchase and so on.

    How will your dependents continue to survive with these challenges and financial hurdles? What’s even worse is if you’re the sole breadwinner of your family, or you contribute a huge chunk to the household income?

    If you were to become ill for long-term, how much of your current income or savings can continue to support you and your family, and for how long?

    That is why in financial management, we need to ensure that we have at least this amount of life insurance coverage in place. Also, ensure that you have a basic medical insurance in place, so that your emergency fund and hard-earned savings will not be wiped out overnight by hefty hospital bills.

    There are many types of insurance products; some are good for you, and some are good for the one who sold you the products; so, be sure to read the fine print, and know what you’re signing for.

    What’s better is to work with someone who is independent and not tied to a product provider. This way, the chances are that your best interest is likely to be more protected.

    Write a Will

    financial will

    A Will is a legal document that sets out who is to benefit from your property and possessions (your estate) after your death.

    There are a number of ways to make a Will, but to be on the safe side, it is advisable to seek the assistance of a licensed financial advisor on how your Wills should be drafted in order to cater to your unique situation and wishes.

    It is important to have a Will in place as if you were to die ‘intestate’ (without a Will), there is a danger that your assets may not reach your family or beneficiaries. Furthermore, it will relatively take a longer time for the court to issue a clearance order.

    Depending on your circumstances, you may wish to include guardianship arrangements in your will so that, in the event that your children are left parentless, there will be someone to take care of them: you obviously need to get the agreement of the people you intend to name as guardian(s) beforehand.

    Conclusion

    The three areas mentioned above may look unimportant to most people, or appear to be ‘simple’; however, we should not underestimate its importance for a solid financial management.

    The benefit of having an emergency fund allows the person to have the ability to handle unexpected events without having to incur mental stress that usually comes when we deal with money issues.

    It also reduces the chances of enlisting an external party to assist us. Moreover, if any form of loan or borrowings was involved today to address any unexpected issues, it simply means we have to pay back in the future.

    Thus, having an emergency fund could help prevent these from happening. I would say the same is true with regards to having adequate insurance coverage, especially personal accident and medical insurance.

    While the first two areas provide flexibility and ability for an individual to deal with unexpected events without having to trouble others, preparing a Will or paying attention to estate planning can help ensure that our family members do not have to deal with the emotional pain of losing out their family member

    It also makes the process of unfreezing and distributing the estate much easier; thus, preventing them from going through more troubles, that potentially could drag up to years, or create tension and conflict among the surviving family members.

    By building up this financial cushion (and taking concerted efforts to maintain it), you will protect yourself when things go the wrong way. This allows you to be in a better position to work out alternatives, in order to focus on the next important step in peace.

    About the author

    kevin neohKevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my.
  • The 4 Stages Of Side Hustle For A Bigger Investment Capital

    The 4 Stages Of Side Hustle For A Bigger Investment Capital

    We are living in one of the most volatile period over the past few decades, where it feels like a series of black swan events arises back to back (to back). However, as investors, we know that in every crisis lies great opportunities. Some of us will try to time the market, and rest of us will DCA (Dollar Cost Average). All of us wants to invest when the market is low and reap theHus profit when the market recovers.

    In times where price of goods are high and employment income stays relatively stagnant, how do we allocate more capital into our investment portfolio? In this article, we will explore the best ways to start a side hustle to complement your investment capital and how to make it successful.

    What Is A Side Hustle?

    Side hustle is simply a second income that you can generate to help you to be financially free. A side hustle is any type of business that you can run while you are working on a full time job. Side hustles can be a small business that you run from your house, or they can be a big business that you run from an office.

    You can start a side hustle with minimal initial investment. It can be anything from selling your own crafts, to selling products on marketplaces, to providing a service to paying clients.

    A side hustle is a great way to make some extra money, learn new skills, and network with interesting people. 

    Now let’s look at the 4 stages of side hustle.

    1. Choosing A Side Hustle (Ideation Stage)

    Thoughtful creative asian man in glasses thinking while making post on social media, looking away, pondering or making decision, holding smartphone, choosing something in internet.

    There’s no shortage of ideas for a side hustle. The challenge is finding one that’s a good fit for you and that you can be successful with.

    Here are a few tips for choosing a side hustle:

    • Start with something you’re interested in or that you’re good at
    • Find a need that isn’t being met and fulfilled
    • Think about what you can offer that others can’t
    • Start small and grow your business gradually

    2. Building An MVP (Creation Stage)

    Once you’ve chosen a side hustle, the next step is to get started. This is where the rubber meets the road.

    This is where you need to start thinking about your MVP. What is an MVP?

    An MVP is your minimum viable product. The idea is to build a simple product that can be tested and experience by potential customers. Even though your MVP is not a finished product, it is the first version of your product.

    The goal with an MVP is to test your idea, market, and product to see if they are viable. One of the most painful experiences is to invest your heart and soul into a product that no one cares about.

    3. Getting Customers (Acquisition Stage)

    Marketing Ideas Share Research Planning Concept

    This is where things get tricky. How do you get customers?

    Getting your first 10 paying customers can be difficult. Here are a few ways that you can experiment, but bear in mind that there is no one-size-fit-all solution. 

    • Find individuals and businesses that are in need and ask them to try your service or product,
    • Work with a local business and get them to try your service,
    • Post your service or product on marketplaces like Fiverr, Shopee or Lazada,
    • List your service or products on the social media,
    • Offering a part of your service or product for free to build trust and credibility.

    You may also consider building a community around your service or product.

    Your community will be made up of people who are interested in what you sell. As you build a community around your product, you will be able to recruit people interested in your product.

    4. Growing Your Side Income (Expansion Stage)

    This stage is optional. You may treat your side income as a real business that may one day replace your full-time job, or, it can also be a side project that let’s you earn a comfortable side income while doing something you love.

    However, should you want to grow your side income, you may want to strengthen your process within your business/company from end-to-end. You may no longer rely on your notebook and your memory to handle the increased number of transactions within your business.

    There are plenty of digital tools from book-keeping to human resources to customer relationship management software. You may also want to look at business automation software that can help you with your business.

    Having a proper process in place is important because it allows you to delegate your work systematically should you wish to hire employees to help you with your business. Having a clear process makes it easier for you to monitor your team’s performance and causes less confusions between you and your employee.

    Protecting Your Hard Work

    Last but not least, let’s not forget why do we want to start a side hustle – that is to increase our investment capital. Building multiple streams of income help hedge against the sudden change of events.

    However, when times are good, remember to invest for the future. You will never know when do you need to use it.

    To sum up, investing in a side hustle can be a great way to supplement your investment capital. In return, you can get a second income that will help you to be financially free.

    Source: PlanNERD.io

    About the Author

    marshall wong insurance

    Marshall Wong is a financial planner holding licenses from the Securities Commission Malaysia and Bank Negara Malaysia. He can be contacted via email at Marshall@plannerd.io

  • Overcoming A RM1,700 Monthly Deficit To Buying Three Properties Worth RM1.1 Million

    Overcoming A RM1,700 Monthly Deficit To Buying Three Properties Worth RM1.1 Million

    A story of a typical Malaysian walking a path less travelled. Ian approach me to help resolve his debt problem.

    “Where do I go? Who can I turn to?”

    I met Ian (not his real name) when I went back to serve as a coach in one of the property investment courses I previously attended in 2013. He was introduced to me by a friend, who said that I needed to help him.

    During our first meeting at Old Town Coffee at Kuchai Lama over lunch, Ian shared with me that he was working as a Graphic Designer and has been working for more than 10 years but finds it very hard to have any savings. I see him as someone who has a dream, and ambition because he told me “People around me, my colleagues, friends and even relatives have already had their own families and even owned a few properties”.

    Yet he is still single and haven’t bought his first property nor started any investment.

    This was his situation:

    • Credit card debts, personal loans & Car Loan close to RM66,000
    • Negative cash flow of RM 1,767 (Outflow more than monthly salary)
    • Earns RM5000/month salary
    • His CCRIS has been badly affected, as he wasn’t prompt in paying his debts
    • Total commitments and loans of RM4,870/month (97% of his salary)

    To be honest, I thought he was in a worse-off situation. But after reviewing his situation, I share with him two strategies to resolve his situation. The first strategy is called Debt Consolidation Strategy, as he had multiple loans which needed to manage.

    The second strategy was to use the World’s Simplest Money Management System, which help him not to fall back into the same situation moving forward.

    Here is his situation before and after:

    Ian’s situation before applying the Debt Consolidation Strategy

    Ian’s situation after applying the Debt Consolidation Strategy

    ” If there’s the slightest chance for you to make a change in your life, don’t let go of it. Keep moving and going and you will find a way.”

    After applying the strategy, he managed to:

    • Reduce RM3,152/month after restructuring his debts from RM 4,870 to RM 1,718 per month
    • Ian could now save RM1,650/month as a result (Monthly salary having surplus)
    • Save on interest of 7-9% on average for his credit card debts & personal loans
    • Bought his first property for RM200K & subsequently another RM900K with his property investor team
    • Avoid being ‘EARMARKED’ by not going to AKPK else he wouldn’t be able to buy property. (I don’t have anything against AKPK, as they genuinely help people restructure their debts, but they need you to pay off your debts fully before taking on new debts)

    Ian Was A Mr Nice Guy To Others, But Is He Nice To Himself?

    So with these two financial strategies, Ian can free himself from his debt problem and pursue his dream of owning his own property. What I notice about Ian was, that he was an easy-going and easy to ‘trust people kind of guy’ which led him to this problematic situation.

    This same trait led him to trust his friend, his friend’s MLM products because he didn’t know how to say NO. And as a result, he doesn’t know how much he has spent over the years. After this experience, he is much more aware of his financial situation.

    How Do You Restructure Your Loans When Your CCRIS Is Not Great?

    “How do you qualify for more loans since Ian’s CCRIS is koyak?” If this is the same question you are wondering about, congratulations!

    It means two things. Firstly you are very aware of what you are reading and you probably have a high Financial IQ. Secondly, you could be in the same situation and you need help. Regardless, the solution to your problem is simple but not easy if you are not equipped with proper financial education.

    Learn how to overcome your debt situation by enrolling to Debt-Free Code here.

    *DISCLAIMER – All strategies listed here are not a recommendation or advice. The article is written purely for the purpose of education and journaling only. The content of this article is an expression of my opinion and should not be taken as professional advice. If you are seeking professional advice, please consult me personally. You should do your own research and/or seek expert advice when overcoming your debt circumstances.

    Source: J Advisory

  • Is Malaysia Property Still Worth To Invest In?

    Is Malaysia Property Still Worth To Invest In?

    Malaysia property might not be as hot as previous years, but the interest is still there. With the recent hike in interest rates and more hikes expected later this year, the instalment for properties will go up.

    This then begs the question as to whether Malaysia property is still a good investment?

    First of all, let’s look at some stats.

    Malaysian House Price Index

    Source: National Property Information Centre (NAPIC)

    House prices in Malaysia went up by almost 100% from 2010 to 2022 with the average price went up from RM220,154 to RM433,430.

    But there has been a steady decline in recent years caused by the pandemic where demand went down and supply going up. The concept of supply and demand has influenced Malaysia property price to a certain extent.

    Source: National Property Information Centre (NAPIC)

    The number of transactions were seen climbing up towards the end of last year before falling off a little bit.

    OPR (Overnight Policy Rate) Is On The Rise

    Source: Bank Negara Malaysia

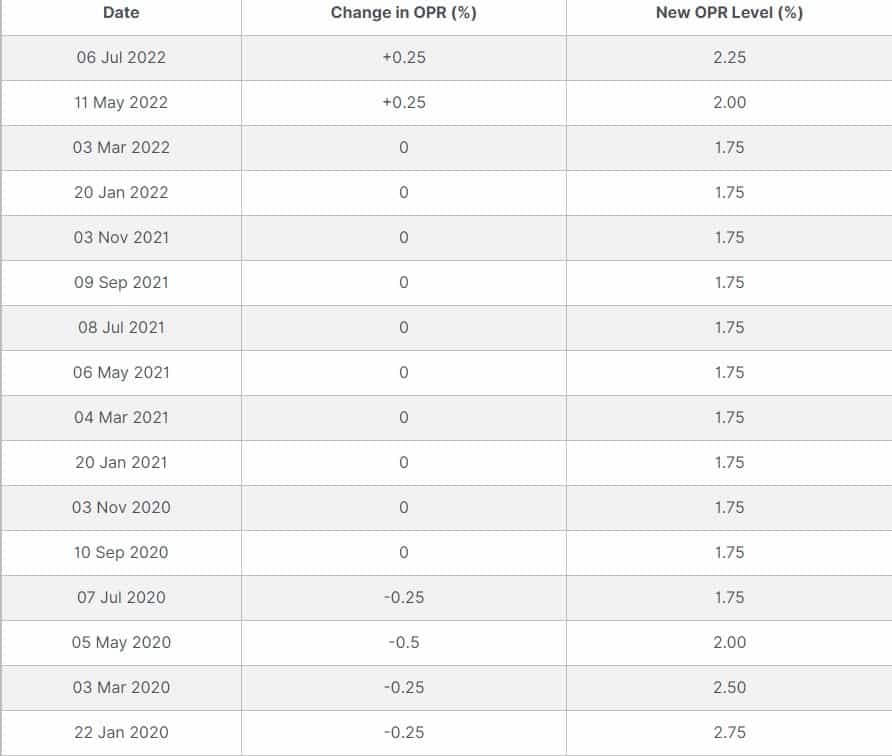
    Malaysia have been enjoying a very low interest rate since the pandemic begin. But with the recent OPR hike by Bank Negara Malaysia, this would have caused interest rate to rise, and subsequently the monthly instalment for houses to increase as well.

    Analysts are predicting a few more rounds of OPR increase to curb the rising inflation by end of this year, which could cause house purchases to cool off.

    The Rise Of Inflation

    Source: Department Of Statistics Malaysia

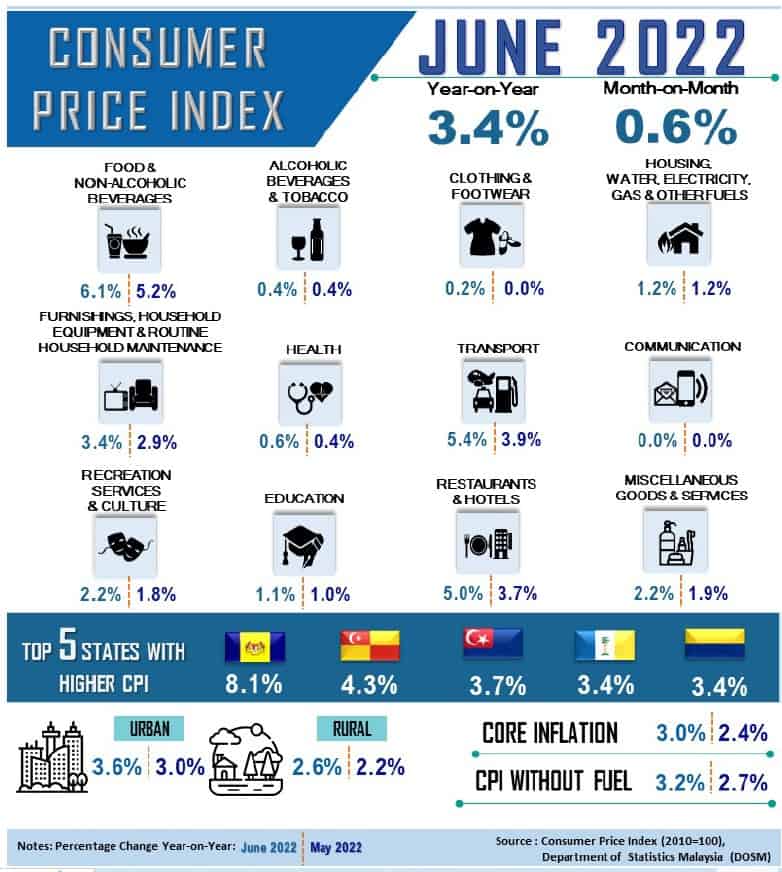
    Malaysia’s inflation increased 3.4%to 127.4 in June 2022 as against 123.2 in the same month of the preceding year. The Food index increased 6.1% and remained as the main contributor to the rise in the inflation during the month of June 2022. 

    When faced with high inflation, there will be lesser disposable income as everyone will be tightening their budget. Only those who have made the necessary preparation and is prioritizing in buying a house over other needs, will buy it.

    The others will then have to rent, so more renters are expected to be on the market.

    Ultimately only you can answer whether Malaysia property is worth investing in. Do you have the holding power? Are you able to find below market value and irresistible deals from the property market?

    As the saying goes, it is about ‘buying low and selling high’. Do your homework and remember the mantra, ‘location, location, location’.

    For more tips and tricks:

    Do you know how much is your Home Loan eligibility? Not sure how much you can borrow from the bank? 

    Get your TechRevo credit report + Home Loan Eligibility which includes:

    • Credit history up to the past 12 months [CCRIS] 
    • Bankruptcy, Legal Suits, Legal action from banks, SAA, and Trade Bureau (Section E)  
    • Max home loan eligibility calculation up to 12 mortgage favorable banks in Malaysia 
    • CCRIS + Credit report + Calculator 

    It only takes 5 minutes. Click here now to get 50% off -> https://www.smartinvestor.com.my/techrevo

  • Clear Signs You Need To Refinance Your Home Mortgage Loan

    Clear Signs You Need To Refinance Your Home Mortgage Loan

    Home loans and home loan applications may be complicated, with changing interest rates, bank policies, and government regulations. These and other factors lead to constant movement in what a lender can and can’t accept. As a result, countless Australians reach a point where they must shift lenders to take advantage of a better mortgage available elsewhere.

    “Refinancing is tricky and time-consuming. Thus, it’s important to determine whether or not this choice is viable for you. Refinancing your mortgage is a big financial choice you’ll have to make. If done correctly, it can save you a fortune in the long haul.” says Shane Perry of Max funding—Australia’s leading second mortgage loan provider.

    If you’re trapped in the same situation, take a closer look at these five tell-tale indicators that you need to refinance your home mortgage loan:

    1.  Low Rates On Offer

    People refinance their mortgages for various factors, one of which is the availability of low-interest rates. Interest rates fluctuate a lot, so don’t pay too much attention to everyday fluctuations. When considering refinancing, it’s a good idea to keep an eye on the trends. Similarly, it’s critical to compare your current mortgage interest rate to the rates offered by mortgage lenders.

    2. Your House Is Now Worth More Money

    Secondly, you may choose to refinance if you’ve made significant renovations or improvements or the value of the homes in your neighbourhood has increased. Also, you may consider refinancing, particularly when you have a massive personal debt such as credit card, personal loans, etc., that you’d want to combine to payout or consolidate.

    However, note that if your house’s assessed value improves, your home equity will likely rise, giving you greater borrowing capacity.

    3. Your Income Or Credit Has Improved

    Your income and credit score mainly determine the interest rate on your mortgage.  Refinancing can help you get a better rate if you’ve earned additional income or your credit score increased after closing your mortgage.

    4. Your Arm (Adjustable Rate Mortgage) And Mortgage Interest Rates Are Increasing

    The combination of an ARM with rising mortgage interest rates is not a desirable match since it may substantially raise the total cost of your house when rates increase. If you find yourself in this situation, you should consider refinancing and switching to a fixed-rate mortgage.

    5. You Want To Remodel Your Home

    People who consider refinancing and get cash out often do so for various reasons. Home equity loans let homeowners borrow money against the value of their houses. You can spend the money to remodel your property and make changes to enhance its long-term worth.

    Is Home Mortgage Refinancing Right For You?

    Mortgage refinancing, along with many other financial transactions, is complicated and needs careful analysis by homeowners seriously considering it. Consider the signs listed above and connect with a trustworthy lender to get immediate answers to your questions. This will assist you in deciding whether or not refinancing is suitable for you.