Category: business

  • Do You Have a Plan B?

    Do You Have a Plan B?

    Lee-Wang’s story is not unusual these days. He and his family have been living in Asia for more than 25 years. But as his business expands globally, he spends more and more time shuttling between countries.

    The globetrotting businessman is in the process of getting his citizenship through a Portuguese golden visa programme that offers a real estate investment route to gaining residency and potential citizenship in the country and hence European citizenship.

    A big driver is for his two children to have the ease of travel a European passport offers in the future. The golden visa programme in Portugal is the most popular in Europe.

    Portugal Golden Visa Programme

    financial plan b passport

    It was launched by the Portuguese government in 2012 to stimulate investment into Portugal and has since encouraged several billion Euros in real estate investment and over 2,000 family applications each year.

    An investment of €500,000 is required in real estate in Portugal. The property, either residential or commercial, can be rented for income. Any number of properties can combine to make up the €500,000 minimum investment.

    Joint buyers can pool investments into one property. The property can be mortgaged for any investment exceeding the minimum.

    Portugal has a very favourable tax regime for anyone considering living in the country. No taxes are charged on overseas income for the first 10 years.

    For those non-resident individuals, tax is charged at 28% on income derived in the country. This can be reduced with expenses for rental income.

    Capital gains tax is 28% and there are allowances for costs and depreciation. There is no inheritance tax in Portugal. Applicants can apply for permanent residency after five years and Portuguese citizenship after six years.

    Global residency and citizenship programmes have been in existence since the 1980s. The demand for the benefits of such programmes expanded rapidly in recent years. The new golden visa programmes in Europe and the Caribbean have wide appeal across many countries.

    However, not every country and programme are the same. There are significant differences relating to investment level, family qualification, permanent residency, minimum stay, citizenship and passports, and not to mention, the differing economic states and real estate investment prospects in each country.

    The EU Context

    plan b european map
    Colorful Isolated Europe in Watercolor

    A number of European countries offer golden visas through investment in real estate, government bonds and donations. A citizen of any EU country is a citizen of the EU. Citizenship and a passport from any EU country allow the holder to live, work, study or travel visa free to any EU country because they are a European citizen.

    A resident of any Schengen countries can travel freely throughout the Schengen zone without border controls even though they may not have a European passport.

    The Schengen Area is the area comprising 26 European countries that have abolished passport and any other type of border control at their common borders, also referred to as internal borders. It mostly functions as a single country for international travel purposes, with a common visa policy.

    Based on experiences, some of the motivations behind global residency and citizenship planning are:

    Investment Return

    Most programmes offer real estate investment as the route to gaining a golden visa from that country. Long, medium and often short-term investment horizons lead to significant capital gains for real estate.

    Safe Haven Investment

    The USA and Europe remain safe havens for investment with clear property ownership laws, democratically elected governments and established taxation rules.

    The laws of the Caribbean countries offering citizenship programmes are based on UK law with democratically elected governments.

    Legacy for Family

    plan b family legacy

    Once the investment is made and the visas, residency cards and citizenship are granted then the ties and contacts with that country begin to increase.

    Children can be included, they eventually move on perhaps for an education, eventual jobs, eventual citizenship and the next generations have firm roots which they have either put down or have the option to do so.

    Education for Children

    Once permanent residency is established by living full time in the country, children can be educated under either the state or private education system.

    Looking to the future, as European citizens, children can gain access to universities in English speaking countries such as the UK at European and not international rates (a substantial saving).

    Some Caribbean countries offer higher education offering ease of access to universities in the USA.

    Ease of Travel

    plan b ease of travel

    A golden visa will lead to a residency card or eventually citizenship and a second passport. In all cases this can significantly improve an applicant’s ease of travelling throughout the world.

    A European passport allows the holder to live, work and travel anywhere in the EU including countries outside the Schengen Zone, such as Switzerland, the UK and Ireland.

    Second Passport

    The second passport and citizenship option arise from all the Caribbean programmes and several golden visa programs in Europe.

    Taxation

    plan b tax

    Taxation is a big concern for most wealthy investors. This is an area where more detailed planning will be needed. The Caribbean countries offer low or no taxation on overseas income.

    In Europe, some countries such as Portugal impose no further taxation on overseas income for the first 10 years of residency.

    No doubt, there are changing times ahead, with residency and citizenship planning or getting a Plan B already becoming an essential part of an offshore wealth management strategy for high net-worth individuals.

    On a final note, beware of fraud. The demand for second citizenships has created opportunities for fraud and misrepresentation.

    Be sure to perform the necessary due diligence or hire a qualified advisor or consultant specialising in such programmes. Get the right advice that is balanced and independent.

    About the author

    YH Wong has over two decades of experience in the financial services industry. His clients include high net worth investors and boutique institutions such as family offices and investment partnerships in the region. He is currently a senior partner with Satori Consultancy Ltd, a financial services company regulated by the Mauritian Financial Services Commission. He can be reached at yhwong@satoriconsultancy.com.
  • Rich Debt, Poor Debt

    Rich Debt, Poor Debt

    Debt seems to give a negative impression. Sometimes it even gives people the chills just by hearing the word. But what is debt? Both layman and business dictionaries define debt as something that someone has given permission to borrow but with conditions to repay.

    Now when it comes to organisations around the world, debt is used as an engine that creates financial leverage and multiplies yield on investment; provided returns generated by debt exceed its cost because the interest paid on debt can be written off as expenses.

    Looking at this, is debt a good thing? Does debt put you in a better position or worse? Does debt make you RICHER or POORER? The answer is: “It depends!”

    Poor Debt

    We have seen tremendous growth in lifestyle expenditure. The unfortunate part of this culture is the increase of debts which makes people poorer. Let’s take the credit card as an example; 40% of credit card holders’ debt revolve around their credit, which means they only pay the minimum or part of the due amount after spending in full every month.

    This trend has been rising for some time now. When you spend beyond your means and revolve unnecessarily, especially on lifestyle lavishness, you are paying a high price for your indulgences as the payback for your expenditure is compounded by a whopping 18% per annum.  

    To make matters worse, most of these lifestyle extravagances depreciate in value.

    Responding to this trend, the personal loan product emerged as another form of new age credit. It gives easy cash access as it requires no asset pledged or charged as security. Many people are attracted to this sudden access to large volumes of cash that can be used for anything desired.

    What’s more, its fixed low monthly payback instalment makes borrowers believe they have more control of their finances this way. The personal loan is another lending facility that gives the after effect of one week of pure enjoyment and five to seven years of dreadful commitment.

    Running a debt on a credit card and personal loan is EXPENSIVE. It will cost you three to four times MORE than a home loan / mortgage.

    In a nutshell, a poor debt is basically spending your future money for current or past expenditure and it does not generate anything for your future.

    Rich Debt

    Please see the situation below on how a debt that can make you richer.

    John buys the same asset worth RM1M, and after three years, he also sold it at RM1.2M and made a handsome profit of 20%. He paid the entire asset of RM1M in cash. This was his capital outlay.

    Amanda buys an asset worth RM1M, and after three years, she sells it for RM1.2M, making a handsome profit of 20%. She had the cash to buy the asset but she took a loan to finance 90% of the asset. Her capital outlay was only RM100,000.   

    Who is a smarter investor? Who made more money? Who is financially more resilient?

    1. Amanda only used RM100,000 to make RM200,000 in three years.
    2. While on the other hand John used RM1,000,000 to make RM200,000 over three years.

    Amanda applied the power of SMART Leveraging. Amanda leveraged using debt, which she intentionally created, and a debt that is clearly controllable both in paying down and its desired outcome to increase her ROI (return of investment) percentage from 20% to 200%.

    On top of that, she had funds for emergencies and additional money to invest on other opportunities that give better ROI than a savings plan. Doesn’t that make more financial sense? Amanda successfully leveraged her way for higher gains.

    So, What is the Power of SMART Leveraging?

    To simplify it, let’s say you have an objective to achieve, you know how to achieve it but all you need is something to leverage on to make it happen. A mortgage is a cost-effective way of borrowing. Interest rates on mortgage is no doubt the cheapest form of borrowing available in the market because it is secured with property.

    What this is creating is that you are now boosting your wealth with effective returns. Just like the example of Amanda and John − Amanda has successfully increased her wealth by using only 10% of the asset value to give her a return of 200% after three years.

    Worth a read : 3 Important Steps For Your Mortgage Application

    Borrowing is Not New

    We borrow to buy our homes. We borrow to buy cars, which is a depreciating asset but at times, a necessity. We also borrow to buy lifestyle indulgence goods.

    Most of the time we borrow to do things that are not financially productive.  SMART Leveraging can be incredibly productive when it is understood and used properly.

    Therefore, equip yourself with the right financial knowledge and start using mortgages as a wealth creation tool. It can be used as arbitrage to leverage what you don’t have and yet benefit based on the total current value of the property when it appreciates over time.

    The key here is;

    A mortgage allows us to leverage and leverage allows us to do more with less.

    About the Author

    Gary Chua is the Chief Executive Officer of Smart Financing Co.

  • Is Malaysia Going To Go Bankrupt?

    Is Malaysia Going To Go Bankrupt?

    Lately, after Sri Lanka became bankrupt, numerous messages have been circulating on social media claiming that Malaysia will go bankrupt next.

    You might have seen them on FB, Insta, and Tik Tok or forwarded WhatsApp messages that we are doomed next.

    But do these claims hold? Let’s examine the numbers.

    How Does A Country Go Bankrupt?

    A country’s economy collapses when it has no or zero cash reserve, exports and economic activities.

    In Sri Lanka’s case, rampant corruption, economic mismanagement and meddling with the constitution by the ruling elite have led Sri Lanka to bankruptcy, affecting millions of citizens in the island nation.

    They are now facing fuel and food shortages, high inflation and endless political turmoil. Sri Lanka is now drowning in its worst-ever economic crisis and pleading for other nations’ help to keep its economy afloat.

    Following a 70% drop in foreign exchange reserves since January 2020, Sri Lanka has struggled to pay for essential imports such as food and fuel. Its foreign currency reserves fell to US$2.31 billion in February, a fall of US$779 million from December 2021 through January 2022.

    What led to these dire situations was a series of unfortunate events.

    Here Are Some YouTube Videos Which Explain The Crisis In Detail:

    Why Sri Lanka is Collapsing: the Coming Global Food Crisis

    Gravitas Plus | Explained: Sri Lankan economic crisis

    How One Powerful Family Destroyed A Country

    To summarise the videos, some key factors diagnose the health of a nation’s economy. Let’s have a look.

    Foreign Exchange Reserve

    Sri Lanka’s Foreign Exchange Reserve

    Malaysia’s Foreign Exchange Reserve

    Foreign reserves are the foreign currencies a country’s central bank holds as backup funds in an emergency, such as a rapid devaluation of its currency.

    It is good practice to hold foreign exchange reserves in a currency that is not directly connected to the country’s currency. Therefore, most reserves are held in U.S. dollars, the most traded currency in the world.

    Countries use foreign currency reserves to keep a fixed rate value of their currency, maintain competitively priced exports, remain liquid in case of crisis, pay external debts and provide confidence for investors. Therefore, an increasing foreign exchange reserve is ideal. Malaysia, in comparison to Sri Lanka, has a strong foreign reserve which has been increasing while Sri Lanka’s foreign reserve has been declining.

    Balance Of Trade

    Sri Lanka’s Balance of Trade

    Malaysia’s Balance of Trade

    Balance of trade (BOT) is measured as the difference between the value of a country’s exports and the value of a country’s imports for a given period.

    A positive trade balance (surplus) is when exports exceed imports, while a negative trade balance (deficit) is when exports are less than imports. A trade surplus does not necessarily indicate a healthy economy, nor does a trade deficit necessarily indicate a weak economy.

    While a trade surplus helps in creating employment and economic growth, it may also lead to higher prices and interest rates within an economy. When based solely on trade effects, a trade surplus means high demand for a country’s goods in the global market, which pushes the price of those goods higher and leads to a direct strengthening of the domestic currency. On the other hand, a trade deficit can be beneficial to countries that import heavily and simultaneously invest in economic development.

    Malaysia, an export nation, has a consistent trade surplus, while Sri Lanka has had a trade deficit for the past years. Unfortunately, Sri Lanka did not invest heavily in economic development activities.

    Malaysia’s Export Category

    Sri Lanka’s Export Category

    Moreover, Malaysia’s exports are varied, well diversified and highly valued, mainly contributed by the Electric and Electronics industry, Oil and Gas and palm oil. Sri Lanka’s exports, on the other hand, are highly dependent on the low-value clothing and agriculture industry, and their GDP heavily relies on tourism.

    Government Debt To GDP

    Sri Lanka’s Government Debt to GDP in Percentage

    Malaysia’s Government Debt to GDP in Percentage

    The debt-to-GDP ratio compares a country’s debt to its gross domestic product (GDP). The ratio indicates a country’s ability to pay back its debts by comparing what it owes with its production.

    The higher the debt-to-GDP ratio, the higher its risk of default and the less likely the country will pay back its debt.

    Even though Malaysia has gone through a series of economic and financial recession crises before, it has never failed to pay interest and mature debts, proving Malaysia’s reputation and capability as a debtor with a good repayment record.

    Article 98 (1) (b) of the Federal Constitution stipulates that the Government must prioritise debt charges over other operating expenses. The External Borrowing Act 1963 provides that offshore borrowings cannot exceed RM35 billion. As of the end -of June 2022, this debt amounted to RM29.4 billion.

    The Provisional Measures for Government Financing (Coronavirus Disease 2019 (COVID-19)) (Amendment) Act 2021 stipulates that the statutory limit of Government debt cannot exceed 65% of GDP. At the end of June 2022, statutory debt accounted for 60.4% of GDP.

    In addition, 97% of the Federal Government’s total debt is in the Ringgit denomination. This reflects prudent debt management as exposure to foreign exchange risk is minimal.

    Is Malaysia Going To Go Bankrupt?

    Based on Malaysia’s economy, the big answer is NO.

    However, as I explored more about the circumstance which led to the Sri Lanka crisis, I couldn’t help noticing parallels between the political and economic situation in Sri Lanka and Malaysia. The situation in Sri Lanka warns us about where we could be headed if we don’t address similar structural problems in Malaysia.

    We can avert the crisis Sri Lanka faces if we are willing to learn the lessons the island nation offers.

    The problem in Malaysia is social economics, which is stagnant. To elaborate more on social economics problems, here is the list:

    • Lack of proper economic policy and implementation of the policy
    • Lack of policies to control fake demand induced inflation, especially in the property market
    • Lack of technological innovation and skills appreciation in STEM
    • Lack of policies to ensure proper business ethics and transparencies in the business industry
    • Lack of law enforcement leading to rampant corruption
    • Lack of political stability

    Therefore, we, the Rakyat should exercise our rights by electing competent leaders at the next general elections to ensure Malaysia does not go down the path taken by Sri Lanka.

    Source: J Advisory

  • Protecting Your Overseas Assets

    Protecting Your Overseas Assets

    We now live in a more connected world, thanks to technology and easy travel access to other countries, which is why it has become increasingly normal for us to have our wealth scattered around the world.

    However, I would like to urge you not to overlook and forget to protect your assets that are outside of Malaysia when you invest overseas.

    Different Jurisdiction, Different Law

    We often tend to take things for granted with regards to presuming that the laws and taxes where our foreign assets are domiciled are similar to the set of laws and taxes in Malaysia. As such, many Malaysians will kick-start their foreign adventure without even knowing what will affect them.

    One such drastic difference that we must know from day one is perhaps the presence of estate tax or inheritance tax. If you have assets in countries like the US, your estate (US-situated asset) may be subjected to two levels of estate taxes, namely at the Federal and State levels.

    Estate tax is a form of tax levied on the taxable estate, meaning after making certain adjustments to the gross estate value such as deducting funeral expenses and donating to charities, among others. It can rack up to as high as 40% of excess of US$5mil for resident and $60,000 for non-resident (on the Federal level).

    My Client’s Experience

    One of my clients, Mr. Y had experienced a great loss when his brother passed away. His brother is a Malaysian who is domiciled in Singapore a decade ago.

    Mr. Y’s brother had accumulated his wealth both in Singapore and Malaysia prior to his death and had left behind a self-drafted will – one that was drafted about 6 years ago, with its contents neither reviewed nor changed since. Mr. Y’s brother had also appointed his younger sister, who resides in Johor Bahru, to be the executor of his Will.

    However, when Mr. Y’s brother passed away suddenly, his sister refused to be the executor of the will since she couldn’t make time to go to Singapore on such a short notice.

    What’s worse, Mr. Y’s brother did not leave behind a list of his assets and liabilities, which meant that they had to first find out what these assets were, and where they were located.

    This responsibility was passed to Mr. Y, who had to write in to every financial institution to inquire if his brother had maintained any accounts with them. This process took Mr. Y several months, and brought him down to Singapore numerous times.

    To avoid leaving a mess for our beneficiaries, consider these options to ensure that our foreign assets are protected from the two things that are inevitable in life: Death and Taxes.

    1. Making a Will

    asset

    While a will can lead to a smoother and simpler process of distribution, we also need to understand that not every will is executable.

    The most important thing about writing a will is not about the instructions, but who the executor of the Will should be. Taking into consideration distance and proximity to decide who the executor should be might not help the situation a bit; instead the executor of the will has to be, first and foremost, someone who is capable and, at the same time, trustworthy.

    As the executor might pass away before the testator, or may not have the time to handle the tedious task of executing the will, the will also needs to be monitored from time to time.

    Another point to note would be that we should have multiple wills to separate Malaysian assets from foreign assets in different jurisdictions, especially when immovable assets such as properties are involved.

    This will save precious time and money for both beneficiaries and executors as they can execute concurrently, rather than having to wait or decide where to apply for Grant of Probate (original will is needed to apply for probate).

    2. Setting up a Trust or Foundation

    A Trust or a Foundation is the recommended solution if you have a sizeable asset to leave to beneficiaries. The requirement for applying Grant of Probate is not applicable in this case as the transfer of assets into the Trust will have to occur prior to death of the settlor or founder.

    Indeed, a Trust or a Foundation is the solution for investors who need a higher level of planning as compared to the use of will. A will’s role is to mainly dictate the intention on distribution of assets, while a Trust goes beyond and preserves it upon death.

    A Trust or Foundation can be maintained for few generations, and some can be perpetual, provided that the funds and asset size are big enough. This can ensure succession for future kin and also allow the settlor to still have control over how beneficiaries can receive from the Trust or Foundation as there will be a Trust deed or Foundation Charter that contains the wishes of the settlor.

    3. Insurance Wrap Account

    assets

    An easier way to protect our paper assets overseas would be through the use of a life insurance wrapper. This is an open-architecture account whereby an investor can put in any form of liquid assets such as equities, bonds, mutual funds, bank deposits, ETFs, and even currencies into the account.

    This life insurance wrapper allows investors to trade and buy stocks directly from major exchange such as the New York Stock Exchange and Tokyo Stock Exchange, and buy funds from renowned company such as JP Morgan, BlackRock and Fidelity.

    Life insurance wrapper accounts can only be done via a Licensed Financial Planner and the account will be registered in tax havens such as Isle of Man, Cayman Island, the Bahamas and Panama, thus allowing protection from tax leakage as all investment returns are tax-free.

    When we open a life insurance wrapper account, we will be able to nominate beneficiaries, thus allowing for smoother transfer of assets when death occurs, and at the same time maintaining protection from tax.

    About the author

    kevin neohKevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my.
  • Spend Only on the Things that are Important to You

    Spend Only on the Things that are Important to You

    In today`s challenging economic environment, people from all walks of life are suffering from financial predicaments that also affect their spending.

    Rising Inflation, decrease in value of the Ringgit, increase in prices of goods & services, petrol and cost of living in general, is drastically reducing purchasing power and adding on to the woes.

    According to the statistics from the National Health and Morbidity Survey 2015, one in three adults in Malaysia, either consciously or unconsciously, suffer from mental health problems.

    Financial constraints and stress, as well as family and career problems, are among the key factors which contribute to the rise in mental health problems.

    So, what is the solution for this predicament? It’s none other than financial wellness

    Financial wellness focusses on knowing how to plan, save and invest your money so that you can successfully work toward achieving your financial goals. It’s not about how big is the pay check; rather, it`s very much dependent on one`s right financial habits or behaviour.

    Achieving true financial wellness is more than outward prosperity and has less to do with dollar signs than it does with how money affects your life and your relationships.

    Therefore, to achieve financial wellness, individuals must equip themselves with the right financial habits and knowledge.

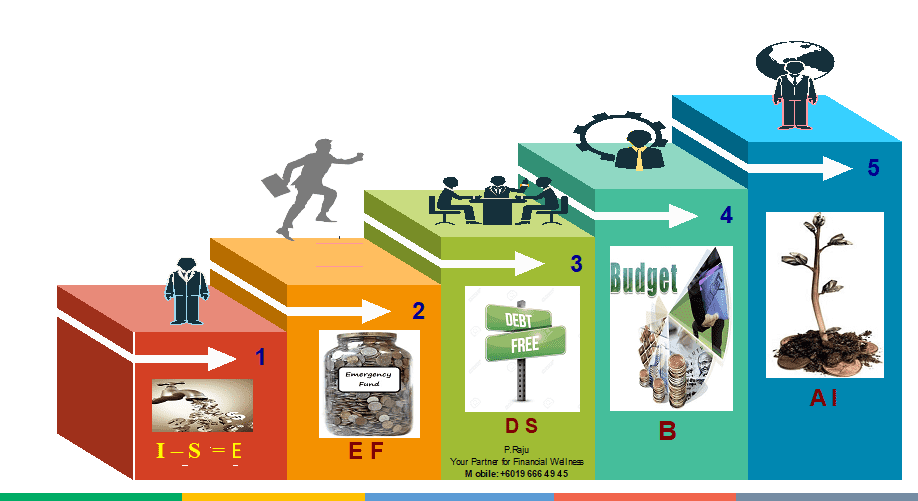
    5 steps to achieve financial wellness

    So, the 5 important steps to achieve financial wellness as described in Figure 1 are as follows:

    Step 1: Be a Conscious Spender to Save Money

    Step 2: Be prepared for Rainy Days

    Step 3: Minimise your leakages by Managing Debts

    Step 4: Be Control of Your Money via a Budget

    Step 5: Consistent Accumulation & Investing of Money

    In the first instalment of this financial wellness article, we will focus on the first step, which is Be a Conscious Spender.

    Conscious Spending

    spend

    Step 1 pretty much implies that you decide exactly where you’re going to spend your money, after you have paid yourself of course. At this stage, you’re also actively choosing to spend on some things and not on others.

    According to American personal finance advisor and entrepreneur, Ramit Sethi, who is also the author of the 2009 New York Times Bestseller on personal finance, I Will Teach You To Be Rich, “The heart of frugality is choosing to spend on the things that are important to you while cutting back ruthlessly on the things that aren’t.”

    So, conscious spending is very important since it fosters every virtue, teaches self-denial, cultivates the sense of order, trains to forethought, and so broadens the mind.

    In a nutshell, it depends on the ability to control one`s money by becoming a conscious spender and focus on needs, then wants, and subsequently cultivate consistent saving habits.

    As you start to practice conscious spending, your financial behaviours or habits improves, which is really the key to achieve financial wellness.

    To put conscious spending in action, you have to learn to ask yourself the questions below before you make a purchase:

    • Will I use this?
    • Can I get this cheaper?
    • Can I wait to buy this?
    • Why am I buying this?
    • Is there something else I’d rather spend the money on?

    Conclusion

    Financial behaviours or habits are formed in individuals over time; it cannot happen overnight. However, once you get it going, it would become very difficult to shrug it off.

    About the author

    Raju Periasamy is a Certified Member of the Financial Planning Association of Malaysia (FPAM) and a Licensed Financial Planner with Phillip Wealth Planners Sdn. Bhd.  He can be contacted at rajuperi@gmail.com

  • Financial Planning for the Middle-Class Rakyat

    Financial Planning for the Middle-Class Rakyat

    Financial planning has often times been associated with the rich. Most people have the perception that only rich people can afford to plan their finances. Is this a fair observation?

    So does this mean that if you are not rich, you should drop the idea of financial planning? What if you are in between these two extremes – the middle class or middle-income people?

    I have constantly observed how the middle-income group struggle more compared to the low-income group. When you’re in the latter, you live a lifestyle more driven by need.

    However, if you belong to the middle-income group, the decision-making process is based more on the want factor, not need anymore.

    How then can the middle-income group reduce their disadvantage and propel themselves toward their aspirations and dreams? Below are some ideas that one can explore:

    Be Aware

    When it comes to investing, you cannot wait until you have enough money, and then only start to think about investing.

    The popular belief is that we can only manage our financial affairs once we have surplus. However, in actual, those who have surplus are those who have done planning, and make it a point to ensure they do the needful.

    Cash-flow management is crucial

    If you manage your cash-flow and debt obligations, you would end up having surplus because without surplus, it’s impossible for one to have savings.

    Protect your savings

    It’s not easy to accumulate savings nowadays; thus, you need to learn to protect it efficiently. We cannot afford to overlook or ignore risk management as this can help protect our savings when financial losses occur.

    Watch your credit behaviour

    Those who are in credit card or debt crisis have once told themselves that they would just use the credit card for rebates and free-gifts, and that they would make sure they pay the billed amount every month.

    The only trouble with this plan is that before you realise it, you are barely making minimum payments, and the amount balloons into a huge outstanding in no time.

    Moreover, interest payment is one of the tiny leakages that will have long-term impact on our ability to save.

    Start early but small

    According to Figure 1 below, a person who starts investing RM12,000 today with no additional new contributions thereafter, will need an investment that generates 10% per annum to have RM130,016 twenty-five years from now.

    financial planning
    Future value of investment

    However, another individual who started with RM6,000 (50% lesser) would require an investment that is 50% less risky (5% per annum) throughout the same time period, to generate RM134,863. The trick is to cultivate the discipline of adding RM200 a month to the savings pot.

    It’s much easier to save a smaller amount than wait for your capital to become significant, as smaller amounts can also grow to become substantial.

    Stay ahead of inflation

    A person who invests his savings in a way that is right and in-line with his risk capacity, will see his wealth grow and become inflation-proof in the long run.

    If you do nothing about inflation, you will find it tougher to maintain your lifestyle. This is due to your shrinking purchasing power, and since it is more likely that your income level will stay stagnant or grow slowly, you will then find that your freedom will be limited by your purchasing power.

    The only way to give our wealth some chance to at least maintain its purchasing power is to put it to work.

    When you invest, you must bear in mind to invest in instruments that are suitable with your risk profile and is regulated at the same time.

    Work on your investment literacy

    A person in the middle-income group may have some disposable income, which they would want to invest, after taking care of their lifestyle.

    However, be aware of scammers who are out to ‘steal’ our money, influence us to make bad investment decisions, resulting in losses or wasted opportunity.

    It is therefore important to have a basic knowledge of investment literacy to conduct appropriate due diligence on investment proposal that is presented to us.

    Financial planning is not for the cheapskate

    One misconception people have is that when we embrace financial planning, we will have to accept a frugal lifestyle.

    However, the whole point of financial planning is to put the aspirations and life goals of a person at the core; as such, it’s rather counter intuitive if you will have to live a frugal lifestyle.

    If you embrace financial planning, what you’ll essentially do is look at your personal finance in totality, make decisions that are smarter and less attached to your urge and emotions for instant gratification.

    It doesn’t mean you have to eat lesser, or not go out with your friends. We all need a life to build our network.

    All said and done, we need to go through a process to manage our financial affairs to ensure that at the end of the day, we will have enough ‘financial muscles’ to help us achieve our life goals.

    About the author

    kevin neohKevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my.
  • Should I Give Up Paying Insurance Premiums In Difficult Times?

    Should I Give Up Paying Insurance Premiums In Difficult Times?

    Insurance is an important element of any sound financial plan, and a proper Risk Management plan should cover personal risk (Premature Death, Total Permanent Disability, Dreaded Diseases, Personal Accident and Hospitalisation), property risk (car, house and its contents) as well as liabilities insurance.

    Having these insurance policies in place can protect your income, savings, retirement, and peace of mind if uneventful situations were to take place.

    Without an insurance policy, the consequences of a tragedy can be much worse, especially with the rising cost of health care that can create a heavy financial burden on your family.

    A proper life insurance can be used to pay off mortgages, car loans, and credit card debts, leaving other remaining assets intact for your family in the event of the breadwinner’s premature death.

    Life insurance proceeds can also be used to pay for final rite expenses. Better still, life insurance can create an estate for your heirs.

    Although insurance is a very important aspect of our lives, yet most people treat it as least important, or even strike it off from their financial budget list.

    Spending hard-earned cash on vacations, shopping, movies, expensive data plans and dining is seen as more important than paying for a life insurance premium.

    Before signing up for an insurance plan, you should first look at your Net Worth Statement to see how much debts you have incurred. Your insurance must be able to cover the debts so that it will not be passed down to your family in the event of a premature death, disability or critical illness that can result in a loss of income.

    Therefore, you should either adjust your cash flow and expenses, or increase your earnings in order to find extra money to maintain the premium payments and excess money for savings.

    Even if you have been retrenched, you must not stop paying your insurance premium, or worst surrender the policy. Make sure that your insurance is intact to cover you in this critical moment.

    However, should there arise a situation when you are really tight for money, there are a few options that can be taken to make sure the insurance cover stays intact. Let’s have a closer look at them:

    Car and Home Insurance

    insurance

    Car insurance premium is mandatory as it is required by the law; so, premium payment is a must.

    Same goes for your house fire insurance premium as it is required by bank if your house is still under mortgage.

    Life Insurance

    You can consider a temporary term, investment-linked, or a whole life non-par insurance policy, which has an affordable premium but comes with big protection to address the problem of huge debts.

    If you have an existing traditional whole life policy, you have the option of allowing the policy to exercise auto premium loans (APL) to make sure the protection is not affected due to temporary non-payment of premiums. However, this is only a temporary measure.

    You cannot allow APL to exhaust all the accumulated cash values as your policy will then become lapse.

    You may wish to convert the policy to an extended term assurance, where there is no further future premiums to be paid, and the sum covered will remain the same until the new revised term of coverage expires. You can even convert the policy to be a paid-up policy with the reduced sum assured.

    Health Care Insurance

    You’ll never know when you may fall sick or get injured. But you do have options when it happens if you continue to pay your health care insurance premium.

    You can lower the premium by considering a standalone health care plan, which has a more affordable premium as compared to packaged plans. But this pretty much depends on your age, gender, health conditions and the coverage amount.

    Also, if you are paying a high premium for a bigger coverage, you may want to consider reducing the coverage and get a deductible health care plan with a very low premium.

    If you’re planning to do some changes to your existing health care plan, make sure you are aware of the exclusions, waiting period, pre-existing illnesses, as well as other terms and conditions of both the new and the old plan; otherwise you might lose your coverage.

    Thus, with the above options, there is no excuse for not paying your insurance premiums.

    In any case, before making any of the above decisions, it is best to seek professional advice so that you can make a more informed decision.

  • What Does it Take to Retire Comfortably?

    What Does it Take to Retire Comfortably?

    The issue of retirement is haunting everyone, especially now with the rise of inflation and interest rates. It is happening not only in Malaysia, but the rest of the world. This makes retirement planning harder and it makes us wonder, what does it take to retire comfortably?

    According to Husaini Hussin, chief executive officer of Private Pension Administrator Malaysia (PPA), the reason why most Malaysians are not able to save is because they are poor with financial planning. 

    “We don’t normally live within our means and do not have a plan for the long term, such as building up our retirement funds,” said Husaini.

    To overcome this, we must set aside one third of our monthly salary to have two thirds of our last drawn salary as income replacement in order to have adequate funds upon retirement. This fund will then need to last us throughout our golden years. With Malaysians living on average up to 77 years of age, it is definitely a challenge to have sufficient funds to retire comfortably. Therefore, it is always good to start planning for retirement as soon as possible.

    Husaini Hussin

    For those who contributed to the Employee Provident Funds (EPF), at least there is something for your retirement. But according to statistics, 6.1 million EPF members have less than RM10,000 in their savings. This amount is not enough to sustain even for a year.

    Husaini suggested that all of us start saving for our retirement as early as possible. 

    “Start with a small amount, then gradually increase the saving once our salary increases. By building a regular saving habit and with the help of compounding growth, it helps to build up our retirement funds,” Husaini remarked.

    What About Those with No EPF?

    The younger generation these days prefer to have freedom and flexibility, which has given rise to a new generation of freelancers, small-time business owners or e-hailing drivers, with all of them not contributing to EPF, hence there is no retirement fund for them.

    So how can they start planning for their retirement?

    “It has to start with the right awareness, that they need to begin planning for their retirement as soon as possible,” mentioned Husaini. 

    It is important to start a saving habit and set aside some money each month and make contributions to a bona-fide scheme such as PRS which is a voluntary long-term saving and investment scheme to help people save for their retirement.

    On the issue of scams, Husaini mentions that this is due to greed, negligence, carelessness and naivety. Even though there are a lot of legitimate investments out there, people still fall for scammers, which is now to the tune of billions of Ringgits. Based on Bank Negara Malaysia’s Financial Capability and Inclusion Demand Side Survey 2018 (FCI Survey 2018), most Malaysians are lacking in financial literacy with one out of three Malaysians rate themselves to be low in financial knowledge.

    We can avoid scams by educating ourselves and getting credible information by visiting the official websites, such as the Securities Commission Malaysia (SC), Federation of Investment Managers Malaysia (FIMM), Financial Planning Association Malaysia (FPAM) and the likes, before making any investment. Also, we can seek investment advice from a licensed financial planner instead of online gurus with no evidence of qualification. 

    Malaysians from all walks of life are invited to visit PRS LIVE website, which is a one-stop learning centre on retirement and PRS. There are insights, articles, news and videos available for visitors to read and have a better understanding on retirement planning. 

    “At PPA, we advocate Private Retirement Schemes (PRS). It was launched by the government in 2012 as a voluntary long-term saving and investment scheme to help Malaysians save more for their retirement. With the regulatory framework developed by the SC, PRS forms the third pillar of Malaysia’s multi pillar pension framework,” added Husaini.

    How Do We Cope with the Rising Inflation and Interest Rates?

    retirement

    We can do this by reassessing our spending habits and to clearly define our “needs” and “wants”. If inflation is making it difficult to stay within budget, take a moment to reassess your cash flow.

    With the rise in interest rates, this will cause our spending to reduce and hopefully it can help us to save. But there is so much that we can do to reduce our expenditure, perhaps it is time that we earn additional income by getting a second job.

    Other than saving regularly towards our retirement funds, we should also set aside some sum towards an emergency fund. We can then dip into when we need access to cash during a crunch period. Studies have shown that people having access to an emergency fund would not touch their retirement savings. 

    In order to achieve a happy retirement, we need to have the mindset of ‘saving before spending’. Allocate a certain amount of savings before deducting your expenses for the month. 

    “This ensures we will always set aside a sum for our retirement savings, rather than to wait until the end of the month to see if we have anything left to save after all expenses,” Husaini mentioned.

    Because chances are, we might not have anything left to save if we did not allocate ahead. Another consideration is to save now and indulge later. 

    Start saving for the life you want with as low as RM100 to enrol in PRS via PPA’s PRS Online service today and stand to enjoy more PRS treats during the #ISaveinPRS Treats Contest period until 20 December 2022. For more information, visit https://www.ppa.my/isaveinprstreatscontest/ 

  • Double-Up Your Property Investment With These Rules!

    Double-Up Your Property Investment With These Rules!

    Property investment is a lucrative business even when market sentiments are not exactly encouraging. Many investors will tell you that they still make money and this is the best time to find the ‘hidden gems’ of properties, especially those below market price by understanding the market trend.

    For those with a deep pocket, investing in property might be easy for them initially, but the challenge later on will be on how efficient they can strike a balance between monitoring their investment profitability at the same time invest in more properties.

    Here are some rules that have helped property investors achieve their property investment objectives and may help you in your property investing journey as well.

    Rule of 72

    property

    Dubbed as the eighth wonders of the world by renowned math genius Albert Einstein, who formulated the famous formula E=MC2, the rule of 72 is really worth understanding, especially in doing property investment as real estate is a business where you practically “double-up” your money invested.

    The rule of 72 indicates how fast the money you invested can grow by 100%. It shows you the number of years to double up the original money invested into your property. For instance, if you have invested RM50,000 into a property promising an 8% return annually, you would double-up the money in just 9 years.

    Say you get lucky and purchase a similar property at RM50,000 but with a 15% return annually, you would have doubled-up the money invested in less than 5 years.

    The rule of 72 works because of inflation. Can you still remember how much a pack of nasi lemak costs 20 years ago and compare it to now? Moreover, your home mortgage should decrease over time, but at the same time, your rent increases. 

    Take the same example and you will know the amount of money according to your age. For instance, if you invested in a property with RM50,000 with an 8% return at age 31, the value will increase to RM800,000 by the time you reach 67 years old.

    The rule of 72 essentially summarises one of the most powerful forces in the history of human’s economy – the power of compound interest.

    If you know how to apply the rule of 72 in your property investment journey based on the annual rate of return, you can then plan your retirement almost more accurately; therefore the notion that people can retire before the retirement age of 60 by investing in the right property is one that is practical and possible to achieve.

    Rule of 78

    Did you know that making payments before they are due does not necessarily reduce the total interest owed to the lender? This is a misconception that sometimes makes investors confused.

    The Rule of 78 is also known as the sum of digit. This rule will guide you to understand how the annual interest is calculated, as well as help in differentiating how much of your monthly instalment is actually going into paying the capital and interest respectively.

    This rule is applicable based on an assumption that investors are looking to take a fixed interest rate with a fixed period loan.

    Apply this rule when it comes to investing in property. Take the balance of your mortgage loan and multiply the balance of your annual interest rate. Then divide by 365. From the total amount multiply number of days per month. Quite a tricky calculation this is! 

    These days, a number of mortgage consultants are offering services where they can help you save on interest by splitting your repayments and paying them at different times. 

    Rule of 1%

    This is the fastest method an experienced property investor will use before deciding to invest in a property.

    Basically the rule of 1% states that any property you invest should be able to be rented out at 1% of the purchase price of the property.

    So for a RM600,000 home, the rental at 1% will be RM6,000. Some investors will increase this percentage from 1% to 1.5% and even 2% for greater cash flow.

    The rule actually helps investors do a quick estimation if the monthly rent recovered will be sufficient enough to cover or exceed the monthly mortgage payment.

    Let’s say you put 20% down payment for a property worth RM600,000, you would have a mortgage of RM480,000; so according to the rule, the monthly rental cannot be less than 4,800.

    Rule of 50%

    property

    Besides the rule of 1%, investors will also consider the rule of 50%. This rule basically states that 50% of your rental income will be used or allocated for the expenses incurred on your property.

    For instance, let’s assume you have a property renting at RM1200. Thus, you should plan to pay RM600 (0.5 x RM1,200 =RM600) on your expenses not including the mortgage. Essentially, this indicates that you have RM600 left to pay mortgage before getting the profit.

    The Cap Rate

    Capitalisation rate or Cap Rate is a good method to calculate the rate of return if you buy or invest in a property because it measures the property’s value relative to your cash flow.  

    This is done by having the total amount of net income divided by the cost of the property or asset.

    For instance, let’s say you buy a home at RM300,000 and your expenses such as property taxes, repairs, maintenance and insurance averages out to RM500 per month. If your rental is fetching you RM1,500 per month, then your net operating income is RM1,000 per month or RM12,000 per year.

    So using the formula provided, you will get a return of 4%. But is 4% a good rate of return? It depends on many other factors such as location, security, opportunities for growth and so on.

    There are many more rules that experienced investors will use other than those stated above. Share your thoughts and feedbacks by sending me an email at aicheng@skbrothers.com

    About the Author

    This image has an empty alt attribute; its file name is chan-ai-cheng-241x300.jpg

    Chan Ai Cheng is the General Manager of S.K Brothers Realty (M) Sdn. Bhd.

  • Is Travel Insurance Worth Investing In?

    Is Travel Insurance Worth Investing In?


    The quick answer is No. Why? Because if you buy travel insurance, you won’t be getting any returns once it expires, and therefore, not worth investing into.

    Travel insurance, like any other insurance products, is meant for risk management. Generally, there are four ways to deal with risks:

    1. Risk Acceptance;
    2. Risk Avoidance;
    3. Risk Reduction (Control); and
    4. Risk Transfer

    Risk acceptance simply means we accept that risks exist, and deal with the consequences on our own. It’s about being aware of the possibility that risks will arise from certain events in our lives, and not choosing to deal with it until it actually happens. And when it does, we are confident of shouldering it on our own.

    Risk avoidance is about being aware of the existence of certain risks and taking necessary steps to avoid it. One classic example of avoiding risk is when people decide to keep their money in bank deposits instead of investing it because they want to avoid the risk of capital loss.


    Risk Reduction or control is about taking calculated risks, instead of avoiding it altogether. It’s about taking reasonable measures to minimise losses or reduce the chances of a certain event from happening.

    For instance, the cash deposit “investors” above may now decide to take 10% of their savings and invest in fixed income instruments, which is a safer bet; hence taking calculated risks.

    Risk transfer might be the preferred approach for most people, because we are able to transfer the risk to a third-party. Therefore, we don’t “buy” insurance products to make a profit, but to transfer the risk of financial losses to a third-party called insurance company

    Coming back to travel insurance, most of the time, we are willing to spend a substantial amount on hotels, transport, food and sight-seeing, but are very reluctant to pay for a travel insurance. This is Risk Acceptance at play.

    Travel insurance covers us throughout a travel period to a specified destination country from a specified origin country.

    These days, we can buy travel insurance together with flight tickets as most flight operators conveniently include a subscription for travel insurance into the purchasing process.

    Sometimes, we would knowingly uncheck the travel insurance option because we want to save some money.

    If we can splurge big bucks on a flight ticket, why not pay a little more (less than RM50) for travel insurance? If you decide otherwise, wait till you see the medical expenses in a foreign country!

    Covered Area

    insurance

    Make sure you provide the correct destination because travel insurance is categorised based on a geographical area; unlike life or health insurance where it is based on your occupation, health and medical history.

    Usually, countries are clustered into:

    • Area 1: Australia, Brunei, Cambodia, China (excluding Mongolia, Nepal & Tibet), Hong Kong, Macau, India, Indonesia, Japan, South Korea, Laos, Myanmar (Burma), New Zealand, Pakistan, Philippines, Singapore, Sri Lanka, Taiwan, Thailand, and Vietnam only.
    • Area 2: Overseas EXCLUDING USA, Canada, Iran, Syria, Belarus, Cuba, Democratic Republic of Congo, North Korea, Somalia, Sudan, South Sudan and Zimbabwe.
    • Area 3: Overseas EXCLUDING Iran, Syria, Belarus and Cuba.

    Benefits

    A comprehensive and reasonable travel insurance package should provide coverage for the following:

    • Personal accident
    • Medical expenses (sickness and accident)
    • Emergency medical repatriation and evacuation
    • Loss of personal items such as phone, passport, money etc.
    • Travel inconvenience such as flight delay or cancellation, missing baggage, etc.
    • Hijacking of flight

    Smart Way to Buy Travel Insurance

    Annual Insurance

    If you are a frequent traveller, you may want to consider buying annual travel insurance, instead of buying one for each trip.

    Basically, travel insurance is priced for the number of days one spends in a foreign country. If you travel at least 8 times a year for say 1-5 days, you can probably save a little by taking up an annual travel insurance product. Besides, the coverage is slightly better for an annual package.

    More importantly, you do not have to repeat the process of buying travel insurance each time before your departure.

    Family Package

    insurance

    Some insurers provide family packages, where premiums are cheaper with a slight discount. This is only suitable if you’re travelling with your spouse and child, as it does not cover your parents, in-laws and siblings.

    However, if you’re travelling as a couple, it’s better to stick with individual insurance, as a family package may be slightly more expensive.

    Direct Purchase from Insurer

    This means we buy directly from an insurance company, instead of going through their distributors, namely flight operators, insurance agents, and banks.

    When we buy through a distributor, the cost is higher since we will be paying the premium rate printed on the marketing material or brochures. However, if we purchase directly from an insurance company, the premium can be 25% cheaper.

    Certain insurance companies have made it easier for us to directly purchase from a user-friendly website. You can complete the process within 10 minutes, and even nominate beneficiaries.

    I had once bought travel insurance from an insurance company’s website when I was inside a taxi on the way to airport, just two hours before my flight. That is how we can fully utilise technology to help us.

    Let’s not give excuses like “it’s expensive”, “I do not know how to buy”, or “I have forgotten to buy travel insurance” any more.

    The world is getting dangerous as we speak, with act-of-war, illnesses, and tragedies. Our country may be safe and protected from natural disasters or disease, but when we leave home soil and set foot in other countries, nothing is certain!

    About the author

    kevin neohKevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my