Category: business

  • How A Credit Card Works in Malaysia

    How A Credit Card Works in Malaysia

    2020 was a challenging year for many, but undoubtedly, it also sped up the transformation of people’s spending habits, pushing all of us towards online channels. Try to recall your last online shopping experience. How did you pay? It most likely would’ve been through online banking, e-wallet or credit card. Many of us choose to pay using credit cards because of a particular bank’s promotion or to collect points.

    In the mid-1970s, credit cards were first introduced in Malaysia. Since then, it has become one of the most common payment methods and the main source of short-term borrowing. With credit cards, we can buy the item now but pay for it later when it’s due. Today, with the government’s cashless society initiatives, credit cards are playing their role everywhere, and aren’t limited to just physical payments. It can be used for monthly auto-recurring bills, reloading e-wallets, signing up for an easy payment plan (EPP) and more.

    It’s a reality that credit cards are a major payment method in our daily lives. However, to play well in the “game of credit cards”, we need to know the rules to abide by first.

    1. What’s The Entry Fee?

    There are two kinds of fees involved here.

    a) Service Tax

    Effective from 1 September 2018, all cardholders are required to pay an annual service tax of RM25 for each active credit card (principal card and a supplementary card will be charged separately). This fee is unavoidable but some banks do offer rebates for this.

    b) Annual Fee

    From a personal finance perspective, you should only opt for a zero annual fee card! Unless you have strong and valid reasons, you should avoid a card that charges you hundreds or thousands of ringgit in annual fees.

    2. What You Need to Know?

    To avoid falling into traps, it’s better to know some jargon first.

    a) Credit Limit

    Treat it like a pre-agreed loan amount. This is the maximum amount that the bank grants to us for our spending. To determine the credit limit, banks usually look at two factors – our income and credit history. If we spend more than our limit (ie. breaking the rules of the game), be prepared to get a fine!

    b) Minimum Payment

    Ideally, you should endeavour to pay your outstanding balance in full. However, at the very least, you’re required to pay the minimum amount, which is 5% of the outstanding balance subject to a minimum of RM50. However, please take note for instalment payments like easy payment plans (EPP), the full instalment amount must be paid. If you can’t pay the minimum payment before the due date, be prepared to get a fine as well.

    c) Interest-Free Period

    This is the tricky part. We do enjoy an interest-free period of 20 days from the statement date provided all outstanding balance is fully paid. The last day of this interest-free period is usually referred to as the due date. Many people will have a wrong perception that they will always enjoy the interest-free feature for all new purchases, even when there’s an outstanding balance on their cards. However, this isn’t the case. If you have any outstanding balance on your credit card, the interest-free period won’t apply to the outstanding balance as well as any new purchase.

    For example, if someone has an outstanding due balance of RM1,000, and he/she makes another new purchase of RM1,000 with the same credit card, the finance charge will be calculated based on the RM2,000 balance (outstanding and new purchase) instead of the previous balance due of RM1,000.

    3. Are There Penalties?

    If you can’t play the game well, you might need to pay a penalty.

    Most people know that credit cards charge high-interest rates. However, between interest rate and convenience, people tend to opt for convenience first. A swipe of a card will always be the top choice compared to a loan application, which can take a few weeks to be approved!

    a) Late Charges

    Everyone knows credit cards work under the buy-now-pay-later mechanism. However, if we don’t make the minimum payment before the bill’s due date, a late payment will be charged. Usually, the amount will be 1% of your outstanding balance (subject to a minimum of RM10, or up to a maximum of RM100).

    b) Finance Charge

    If there is an outstanding balance that remains unpaid on the due date, a finance charge will be applied (usually people refer to it as interest). Bank Negara Malaysia implements a tiered interest rate system for credit cards, ranging between 15% to 18% depending on your repayment track record.

    c) Overlimit Fee

    If you spend more than your approved limit, an over limit fee will be charged. It varies across different banks, from RM25 to RM50 per month.

    These are some of the important things you must know before you apply for or start using a credit card. It’s important to take note because misusing credit cards can lead to financial ruin. Shifting your payment pattern to cashless can be rewarding. However, it can easily lead to overspending as well. According to the Department of Insolvency, Malaysia recorded 84,805 cases of bankruptcy between 2015 and 2019, with around 10% attributed to credit card debt!

    For credit card newbies, I have five important suggestions for you:

    1. Apply for only one card and get used to the full credit card payment cycle before applying for a second (if required).
    2. Limit your monthly credit card usage initially, then you can consider increasing later once you have proven to yourself that you can manage this well.
    3. If you can’t pay the full amount in cash now, don’t even think of making another purchase with your credit card.
    4. Check your credit card statement every month to review your “swiping pattern” and ensure there are no fraud / unauthorised transactions.
    5. Never pay the minimum amount for the month; full payment is a must by each due date.

    Financial literacy is not just about knowing about financial matters. Acquiring and consuming knowledge is easy in the internet era, but behaviour and habits are what counts. A credit card is a good financial tool if you use it wisely. Be responsible for your personal finance today as financial planning starts from small baby steps. If you need a professional to assist you along the journey, consider engaging a licensed financial planner to keep you on the straight and narrow path towards financial freedom.

    About the author

    Ocean Pon is a Licensed Financial Planner and can be contacted at oceanpon@finwealth.com.my
  • The Importance Of Building An Emergency Fund

    The Importance Of Building An Emergency Fund

    As we start this new year, there’s a lot of hope that 2021 will be a better year than 2020, and that our lives will resume some form of normalcy since the start of the Covid-19 pandemic. We’d all like to go around our daily lives in the way we were able to previously.

    Unfortunately, 2021 has started to unfold in a similar pattern to 2020, but we should remain optimistic and hope for the best. As with any new year, it’s a great time to set goals and have a fresh start. I believe many of us will have new year resolutions this season, some of which will revolve around finances.

    For many people, financial freedom, being debt free or cash rich is often on their goals or resolution list, but how many are able to achieve it? There’s a popular adage often attributed to Benjamin Franklin, the father of time management ” Failing to plan is planning to fail.” Many of us draft a new year resolution list but without proper planning, and setting goals, timeframe, and deadlines to meet, one will never achieve their plan.

    When Malaysia went into our first Movement Control Order (MCO) in March 2020, many Malaysians found themselves in financial difficulty as they were not prepared to face salary cuts, reduced working hours or even losing their jobs due to the economic shutdown. News has also been circulating of those who just managed to restart their businesses or get new jobs going back to square one as a result of MCO 2.0 due to the rising Covid-19 daily positive cases, currently at the four digit mark.

    Due to the uncertainty of such times, it’s important to reflect on where you are and where you want to be, as life altering events usually result in people taking a hard look at themselves to reform and transform. No doubt the pandemic has impacted many people in more ways than one, with saving habits being one of them. If you’ve planned your financials appropriately and have a sufficient emergency fund in place, you’d at least be able to support yourself and be less stressed in such times. One of the things that Covid-19 has taught us besides resilience and adaptability, is the importance of proper financial planning and having sufficient savings.

    The purpose of an emergency fund is to cushion the blow should unexpected events occur, such as medical bills, retrenchment, business closure, home emergencies home or car repairs. You’ll have peace of mind and less money worries if you know you have sufficient funds to tide you through difficult times. In addition, you’ll also have more confidence to save money for other financial goals such as retirement or your children’s education if you have an emergency fund in the first place.

    How Much is Sufficient for an Emergency Fund?

    Your emergency fund should cover at least 3-6 months’ worth of essential expenses. Of course, you can save for more than six months; some people have up to 12 months of savings or more! It depends on:

    • Family size – are you single, a breadwinner, or in a dual-earner family i.e. you or your husband/wife works?
    • How closely your job is tied to economic changes
    • Financial responsibility

    Essential expenses are bills that you can’t stop paying such as food, utilities, household essentials, rental or mortgage repayment, car repayment, insurance and medication. Gym passes, entertainment expenses, or Starbucks coffee aren’t essential expenses.

    Six months of fixed expenses is the guideline, but it’s acceptable to save more but be warned that keeping excessive funds in your bank account only is also not advisable as the money doesn’t generate additional returns for you and will be slowly eroded by inflation.

    How to Start an Emergency Fund?

    As with all other things in life, start with a small realistic goal. Determine an amount that you’re comfortable to set aside every month, for e.g. RM200. It doesn’t matter if you start small as long as it’s realistic and you can move forward. Once you have accomplished this, set a new savings goal that will require more effort e.g. RM500, slowly add to it until you have accumulated one month’s worth of expenses. Your ultimate goal will be to reach 3-6 months of your fixed expenses.

    Where Should I Keep My Emergency Fund?

    An emergency fund is all about keeping it safe. Hence, there’s no specific investment tool to keep your emergency fund, as long as it is safe, liquid and easy to access. Most people will prefer to save in a savings account or fixed deposit (FD).

    The reason for putting these funds into a safe investment tool is because if the money is in high-risk investments, there’s a risk that you could lose all the money. For example, saving an emergency fund of RM15,000 earning 2% interest in fixed deposits gives you RM300. If you were to invest in the stock market and can generate 8% annually, that’s RM1,200. While an extra RM900 may be significant to you, it isn’t guaranteed as you could lose all the capital you invested in the stock market if market conditions are unfavourable.

    Hence, don’t be greedy and just leave your emergency fund in a fixed deposit or savings account as the goal is liquidity, not high returns.

    Life can be unpredictable so it’s important to put aside a small amount of cash each month to cushion the blow of emergencies in difficult times. Many people strive for high-risk investments where they take on unnecessary risk to earn more money but are left with no basic savings. For those who don’t have this habit, start building your emergency fund from now. Learn from the past and don’t procrastinate. Once sufficient emergency funds are set up, it’s time to aim for your next financial goal, which can be for the short, medium or long term, depending on your life goals and/or values.

    About the author

    Yit Wei Yeing is a registered financial planner. She can be contacted at wyyit@genexus.com.my.

  • MRTA vs MLTA: Which Mortgage Life Insurance to Pick

    MRTA vs MLTA: Which Mortgage Life Insurance to Pick

    Most millennials are taught from a young age that owning a property, especially their own home, should be one of their life goals.

    This leads to them saving up diligently from the day they enter the workforce with the dream of owning a property someday, either for their own stay or investment purposes.

    However, you should remember that getting the keys to your own property is not an endgame.

    Having signed the mortgage loan agreement, most will assume the best and expect to live until the loan is fully paid off.

    But in the unfortunate event that you are no longer around to pay off the loan, it is important to ensure that you leave behind an “ASSET” and not a “DEBT” for your loved ones. On top of that, you have to distinguish what is the difference between MRTA vs MLTA.

    Why Should I Have Mortgage Insurance?

    These days, most mortgage tenures range from 30 to 35 years.

    This is a very long time and should unforeseen circumstances like pre-mature death, disability or serious illnesses occur, your joint-borrower or next of kin (spouse, parents, children etc.) will need to continue servicing this debt until it is fully repaid. In other words, your debt has become their liability.

    Therefore, it’s important to have mortgage insurance to protect against these risks even if the property is meant for investment purposes.

    Some may argue that if the property is bought as an investment, it’s not necessary to have mortgage insurance as the property can be sold should the unforeseen happen. However, you must remember that the property market is cyclical in nature.

    What if tragedy strikes during a crisis or market downturn? Your next of kin may need to sell the property at distressed prices and suffer financial losses from the sale just to pay off your outstanding loan.

    So in order to safeguard against these risks, it is very important to have mortgage insurance and also a will to smoothen the process for distribution of your estate.

    The two most common mortgage insurances are MLTA (Mortgage Level Term Assurance) and MRTA (Mortgage Reducing Term Assurance).

    The Difference between MLTA and MRTA

    Generally, an MLTA offers not only protection for the amount of outstanding loan, but also functions as savings since the amount insured will be consistent throughout the duration of the loan.

    If nothing happens at the end of the loan tenure, you will receive back the total premium that was paid over the years. On the other hand, an MRTA covers the money owed to the bank from the loan.

    The coverage decreases over time and if nothing happens at the end of the loan tenure, you won’t get any money back.

    As for the protection coverage, both MLTA and MRTA offer basic life coverage (Death or Total Permanent Disability) with the option to include critical illness coverage depending on your needs.

    For MLTA, you can appoint anyone as your beneficiary whereas for MRTA, the sole beneficiary is the bank.

    In addition, MLTA is also transferable which means you can sell off a property and replace it with another property under the same MLTA.

    Even if you refinance your loan, you do not need to replace it with a new MLTA. For MRTA, it is non-transferable as it is tied to your loan with the bank.  

    In terms of cost, an MRTA is more affordable. The premium for MRTA is paid as a lump sum and can usually be bundled into the mortgage loan.

    As for MLTA, you can choose to pay your premiums on a monthly, quarterly, semi-annual, or annual basis.

    So What Should I Do?

    In most cases, the banks will typically offer you mortgage insurance (MRTA) together with the loan.

    However, it is not compulsory for you to take up this mortgage insurance from the bank so don’t feel pressured into getting it.

    Instead, seek consultation with your financial planner to discuss which option is best suited for you.

    About the author

    Billy Teoh (RFP) is a licenced financial planner, and can be contacted at billy.teoh@ipp.com.my.

  • How to: Plan for Your Children’s Education Fund

    How to: Plan for Your Children’s Education Fund

    Among the Chinese, there is a saying: “再穷也不能穷教育”, which translates to: “Education shouldn’t be sacrificed even if we’re poor”.

    Parents believe that when their children are educated, they can secure a higher income and get better opportunities in life, allowing them to contribute back to the family and society in various aspects.

    Just like any investment, time can be your friend or your worst enemy. If you’re a parent with young children, why not start preparing the best angpao you can give your children now?

    To start planning for your children’s education fund, you should:

    1. Estimate the Cost of Education

    When estimating the cost of education, consider the following factors:

    • The type of studies your child may pursue.
    • Will you send your child to attend a local or an overseas university?
    • How much is the basic cost of living should your child attend an overseas university?

    Information on the fee structure and the overall cost of living are readily accessible on the internet. You can refer to this website to learn more about the fees and cost of education in Malaysia.

    However, bear in mind that these factors may change over time. Review the plan at least once a year to keep yourself updated on the latest developments and be sure to get the information from various sources to ensure that the cost of education and overall cost of living falls within a similar range.

    2. Understand Your Current Financial Position

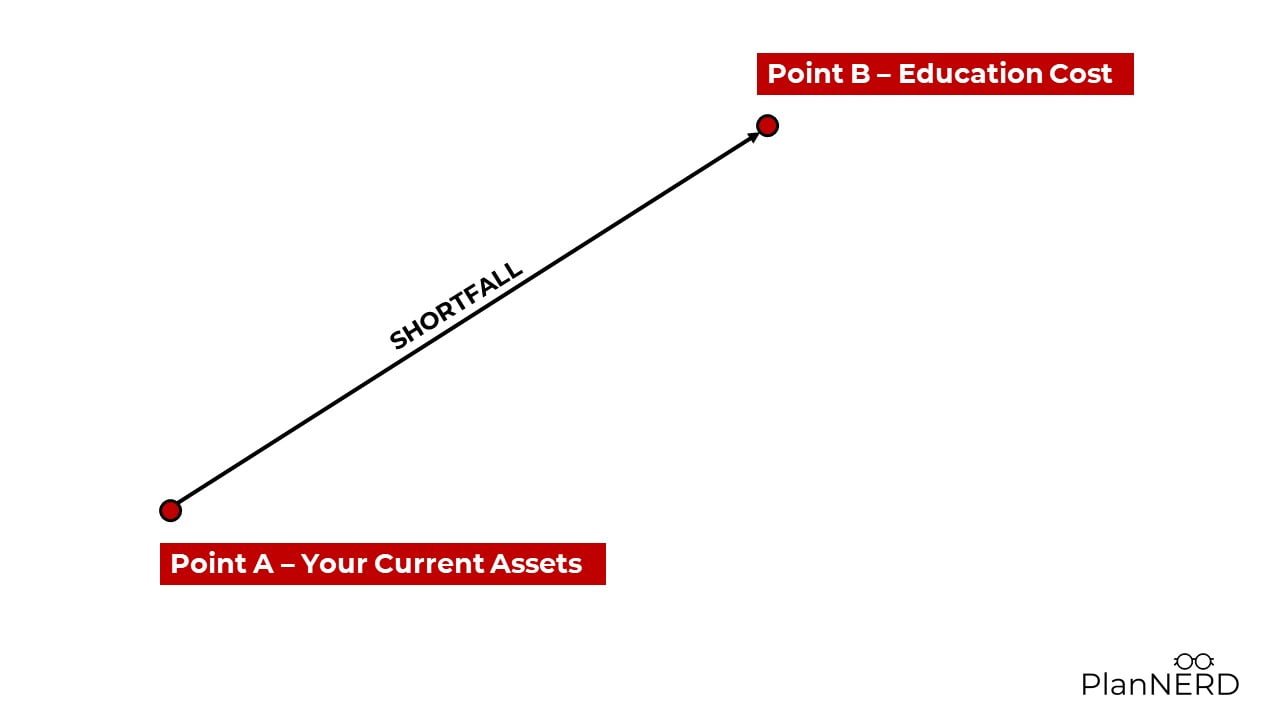
    current financial position graphic - children's education planning

    Now you know how much is needed to reach point B (cost of education), to calculate how much you need to set aside every month to cover the shortfall, you’ll also need to know how much you currently have – point A.

    Most people store their wealth in cash, properties, and other types of investments. You should ask yourself; what portion of the above-mentioned assets can be allocated for your children’s education?

    For example, you may want to allocate 10% to 20% of your cash for the sole purpose of funding your children’s education. If you have investment properties, you may also designate a property to be sold once your child reaches 18 years old. Some may even have endowment policies with insurance companies that may mature in 20 years.

    The key is to write down a list of assets that you will dedicate to its sole purpose of being your children’s education fund.

    3. Determine the Amount to Cover the Shortfall for Your Children’s Education

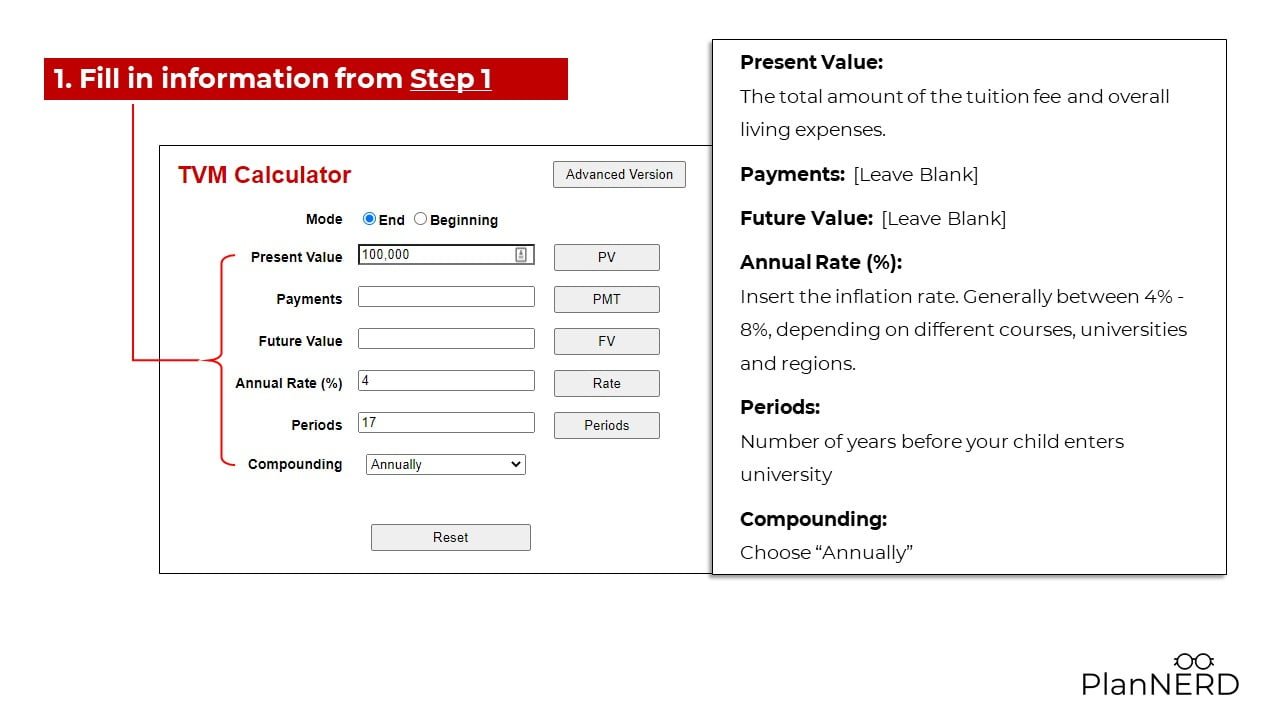
    In this step, we’ll use a free financial calculator to easily calculate how much you need to save/invest for your children’s education. You can access the calculator here.

    (i) Enter the following field with the information you had prepared in Step 1 above.

    Step 2 for FV calculations - children's education planning

    (ii) Click on ‘FV’

    step 2 for FV calculation- children's education planning

    The amount in the FUTURE VALUE box is the future value of the education cost that you entered.

    In this case, the cost of education today is RM100,000. However, with an inflation of 4% for the next 17 years, the cost of education will increase to RM194,790.05 when your child is ready to enter university.

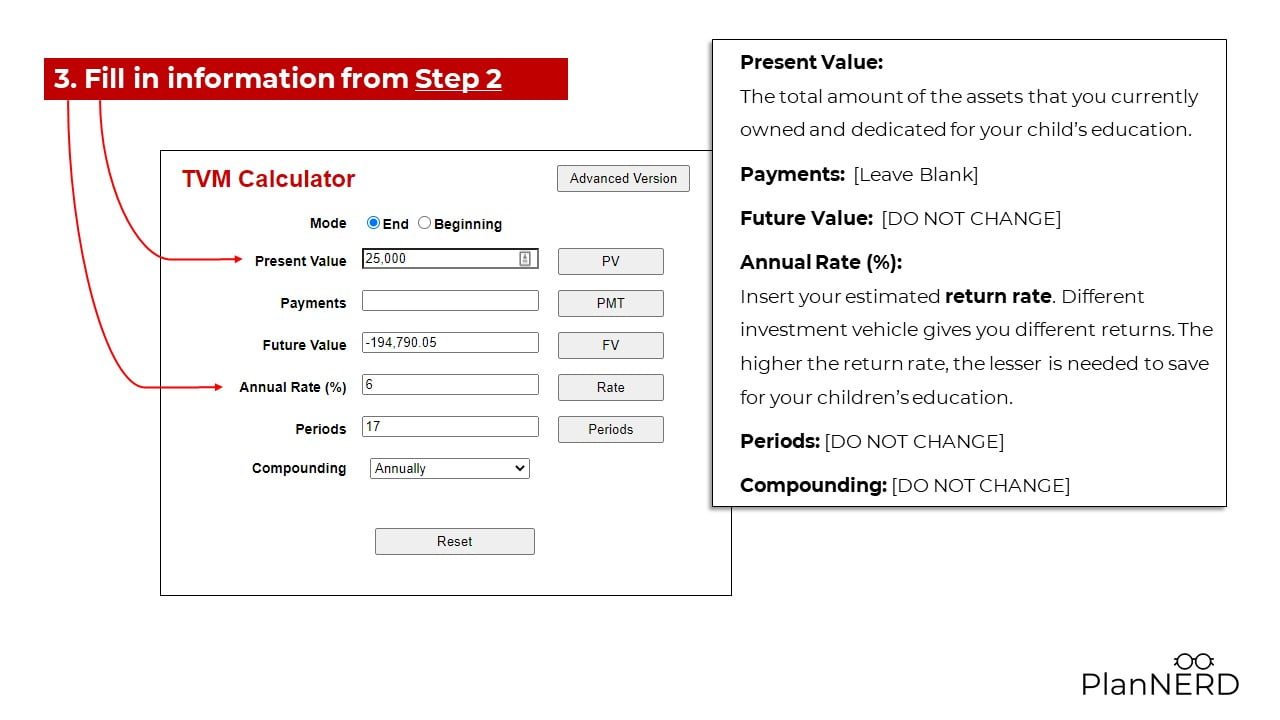
    (iii) Update the ‘Present Value’ and ‘Annual Rate’ field

    present value and annual fee table - children's education planning

    Next, you’ll need to calculate how much more is needed to cover the shortfall.

    Using the same example above, assume that you have RM25,000 now and you believe that you can achieve an average of 6% return rate for the next 17 years, update the Present Value and Annual Rate (%) column.

    (NOTE: do not refresh the website or change any other information.)

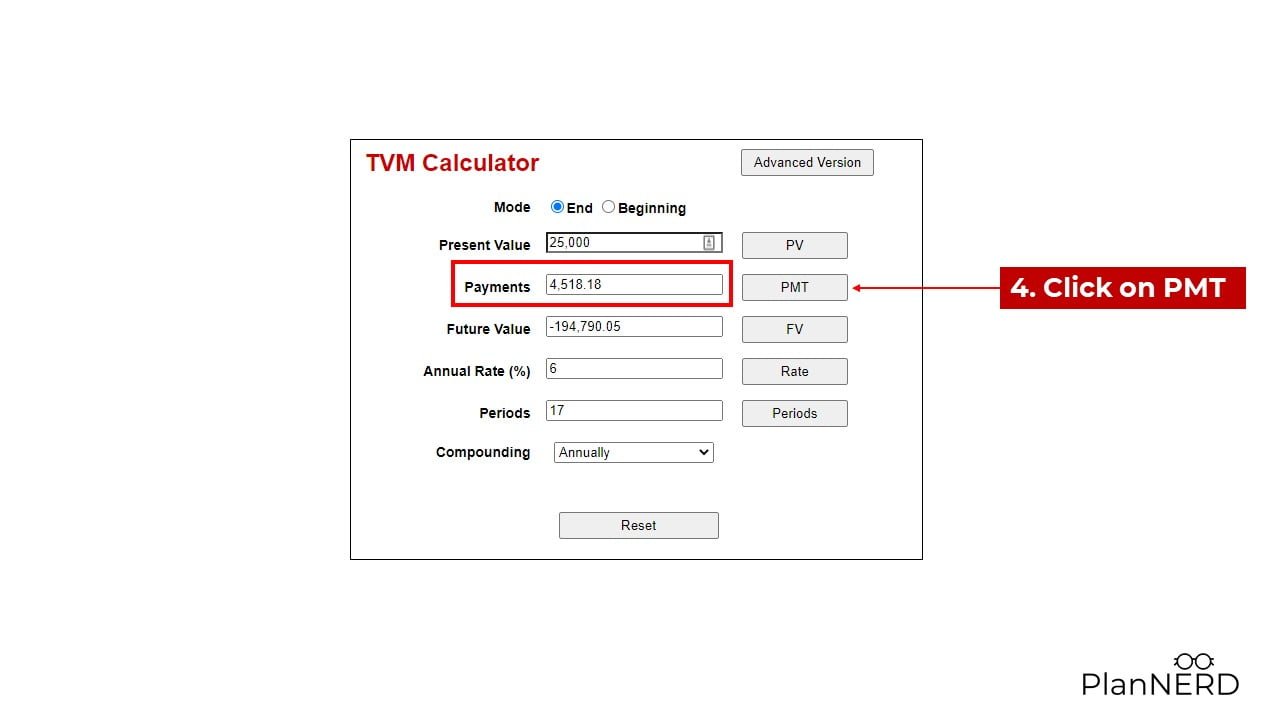
    (iv) Click on ‘PMT’

    pmt table to show the calculation flow under children's education planning

    The last step is to click on “PMT” to calculate the amount needed to save/invest every year to cover the shortfall in your children’s education fund.

    In this example, you will need to save RM4,518.18 every year, or roughly RM400 every month (with a return rate of 6%) to send your child to a private university in Malaysia in 17 years.

    4. Choosing the Correct Financial Vehicle

    There are plenty of choices when it comes to choosing an investment vehicle. However, we all know that most investment journeys aren’t going to be smooth sailing all the time, therefore it is very important to follow these three rules of investing:

    Preserve your investment capital

    One important rule that’s applicable in investing for children’s education is to preserve your investment capital. Sometimes, we can allocate a small portion of our portfolio to invest in high-risk investments. However, you don’t want to do that with your children’s education portfolio.

    For example, in order to recover from a 10% loss on an investment, you’ll need to have an 11% gain to return to the original capital position, a 25% loss would require a 33% gain to break even, and so on and so forth.

    There is no such thing as the best investment

    In short, what’s good for me may not necessarily be good for you. Having said that, when it comes to investing for your children’s education, you may want to pay some attention to PTPTN’s National Education Saving Scheme (SSPN). Parents saving money into SSPN-I can enjoy tax relief of up to RM8,000 per year.

    Keep your eyes on the prize

    Lastly, keep your eyes on the prize. Always remember your why. Constantly review your investment strategy to ensure that you don’t receive any unfavourable surprises when your children are approaching the age to register for tertiary education.

    5. Avoid Common Education Planning Pitfalls

    Ignoring retirement planning

    If you’re unable to cover the shortfall as calculated earlier, there are other ways to ensure that your children will receive a decent education, such as applying for an education loan from PTPTN or applying for a local public university.

    However, there are fewer options available if you can’t cover the shortfall in your retirement planning.

    Trusting the wrong ‘advisor’

    Many fraudulent “advisors” use the element of fear and greed in parents to convince them to invest in their unregulated investment products. Should you need the help of a third party in the education planning process, please ensure that you engage a licensed representative.

    Not reviewing savings and investments

    I may sound like a broken record by now but reviewing your investments and portfolio at least once a year is very important. If needed, you should also rebalance your portfolio to ensure they meet the objective of providing X amount of money Y years later.

    Conclusion

    Saving for your children’s education is a long-term goal that may seem like a huge commitment at first. With a carefully planned strategy, and making time your friend instead of your enemy eases the process significantly. No matter how much or little the amount is, start today. The earlier you start, the better the compounding effect will be, because:

    “Compound interest is the eighth wonder of the world. He who understands it, earns it; he who doesn’t, pays it.”

    This article was originally published at planNERD.

    About the author 

    Marshall Wong is a licensed financial planner, and can be contacted through his website or marshallwong@fa.my.

  • What Is Financial Wellness?

    What Is Financial Wellness?

    We have a choice daily on how we want to manage our lives. Every day we decide whether we’re willing to go the extra mile in ways that contribute to our financial needs. At times we drown ourselves in our work to chase that paycheck and ignore our own personal health. 

    We stress about things that are out of our control, like pay cuts and job loss. It does not help that we are constantly bombarded with our mobile from the first thing we grab when we wake up and the last thing we see before going to bed. Currently, the average person is seeing up to 10,000 advertisements every single day. 

    It’s just a matter of time before we start fighting back or drive ourselves crazy. How are we supposed to feel in control when we are constantly bombarded by even living our daily lives? The whole goal is mastering our money control in pursuit of our dream life. We’re not meant to suffer all of our lives in search of happiness

    “Pain is inevitable, suffering is a choice.”

    Focusing On Financial Wellness 

    I’ve realised it’s vital to pursue financial wellness because we must have a purpose behind all the effort we put into earning money. Some people can master their finances completely and even reach financial freedom but may be extremely unhappy. 

    The current COVID-19 pandemic has not helped either, genuinely showing just how many people are unhappy in general, often falling into the rabbit hole of depression. It’s easier to understand financial freedom or financial independence, but the concept of “financial wellness” is a whole other story. 

    This is more of a personal take on looking at how we manage money. We’re not only focusing on the monetary aspect of finances but our emotional health too. I like that it’s not only focusing on the numbers but the dream we had before being buried by the numbers game. 

    When you think about financial wellness, it’s not typically something you can seek out a doctor for. It’s a whole new term that looks deep into the needs and wants of our soul. It’s taking an entirely new picture of the state of our wellbeing. It’s not only focusing on how much money you need in the bank or investments but also on taking care of your health and making sure you don’t destroy your body and relationship to pursue something as fleeting as money. 

    Often I feel I’m stuck in a financial trap where I’m bombarded with many boxes I need to tick to get my life “right”. But looking at financial wellness, I’m looking at myself in the mirror and asking what I need to do to feel happier and healthier. 

    It’s easier to just merely set a target number to reach. Let’s say you wanted to hit RM2 million to secure financial freedom, but in hindsight, you only needed RM1 million. The difference between this and financial wellness is that it brings you back to the present moment, focusing on the now instead of incorporating someone else’s thoughts and ideas into your race, which creates unnecessary fear that may not seem like the best-fit dreams. 

    This pandemic has taught me to just really slow down and reflect. I’ve been in such a deep pursuit of my short-term and long-term dreams that I forgot how much I’ve achieved along the way. The act of chasing has literally made me feel burnt out. 

    Knowledge Is Key to Financial Wellness

    The Society for Human Resource Management (SHRM) has started to recognise the impact of financial stress on people and how it affects their work quality. When employees have high financial pressure, they’re more likely to bring that stress to work, which can impact the quality of work and relationships with managers, resulting in a negative effect on the bottom line. Money affects most things, but money is not everything, although the pressure of financial goals can create this illusion. 

    As I reflect on my childhood and how I was taught to manage my finances, it has always been drilled into me that we need to save as much as we can because we are not rich. There were so many limitations when it comes to purchasing something nice, and I didn’t grow up enjoying many luxury holidays or getting expensive gifts. 

    My grandparents and even my parents are frugal people when it comes to managing their finances. They’ll go the extra mile to save as much as they can of their money. My mother would even go to different stores and compare prices just to get the best deal. This limited belief had me thinking that I needed to work extra hard to reach financial freedom, but in fact, it shouldn’t be so hard. 

    Typically, parents will try to shield children from issues relating to money as much as possible, which was no different when I was growing up. We never talked about exactly how much we had in the bank or how much we should be spending. My parents had one mantra – save as much as you can. 

    Thankfully, the abundance and accessibility of knowledge we have now have made it much easier to learn about managing our finances. Through the many psychological training sessions I sat through, I came to realise that it’s possible to have a balanced life without sacrificing mental health.

    “1 in 3 Malaysians have mental health issues, with highest prevalence among those aged 16-19 years as well as those from low income families.”- Ministry of Health Malaysia.

    This trend is not going down, and I believe it’s steadily increasing with many households affected by the current health crisis. 

    What Can I Do When Everything Feels Out of Control? 

    The most essential thing that you can practice is breathing. Studies have shown that practising breathing exercises may trigger body relaxation that benefits both physical and mental health. One thing I have learned during this pandemic is the value of our breath. How valuable is something we take for granted daily until it’s taken away? 

    Focus On What You Can Control

    Understand that you can control your input, but you can’t control the result of it. You can possess the time and effort spent preparing for a job interview, but you can’t control whether you’ll get the job. 

    You could work diligently on a task, but you can’t control how your boss would react to the end product. Just like any financial decision we make, we can’t control the outcome of it. We can either focus on the financial distress we face or look at it from a positive perspective by assessing our financial capability to turn the current situation around. 

    Therefore, financial wellness considers various aspects of our well-being and our financial goals. It’s not merely focusing on monetary value but also covers all aspects of well-being.

    About the author

    Nurul Yahi is a financial enthusiast and you can find her at dearduit.com, and on TwitterInstagram and Facebook.

  • The Best Alternatives to Fixed Deposits

    The Best Alternatives to Fixed Deposits

    We’ve seen how the COVID-19 pandemic has hit us in many ways last year, and 2021 looks like it won’t be any different. Looking at the aspect of interest rates, it’s cheaper to borrow money now than ever before. However, the direct impact of cheaper loans will be the rate of return on your investments such as fixed deposits. What are the alternatives to fixed deposits?

    Gone are the days when one could earn a comfortable yield of 3 to 4% per annum; we’re looking at less than 2% right now!

    As an investor, should you maintain the status quo and let your funds float in fixed deposit, or should you re-strategise to see if there are any other products that could give you interest rates like before, or maybe even more?

    Here are some steps you could explore in order to bring your portfolio back to its glory days:

    Start the ‘New Normal’ in Investing

    Let’s face it, storing all of your hard-earned savings for emergency funds and future retirement in fixed deposits isn’t really a crisis-proof strategy.

    Your parents and grandparents may have taught you that fixed deposit is a safe haven, but with the banks’ overnight policy rate (OPR) currently sitting at interest rates of 1.75%, can it still be considered that?

    Imagine teaching the same investing values to the next generation – they’ll be forced to earn more just to keep up with inflation! Why not teach them something valuable such as financial literacy? This starts with you.

    There’s More to Life than Just Fixed Deposits

    Keep an amount that you’re comfortable with as your nest egg in fixed deposit, which could range from 6 to 12 months’ worth of expenses. Invest the excess in platforms that can meet your medium to long-term needs such as purchasing a home, getting married, children’s education as well as your retirement.

    The cost of basic life necessities such as home, food, clothing, and medical will continue to rise faster than your salary increments, which is much better than simply collecting poor returns from low-interest rates.

    Thus, it’s vital that you make your money work hard for you, or else you’ll need to work harder and longer for less pay!

    Decide Now and Adapt

    The COVID-19 pandemic has swept away what used to be comfortable safety nets, like fixed deposits for example.

    Businesses are shutting down, pay cuts are a norm and exploring additional income is more common now than ever for many. Investors who used to fear dividend-based and equity funds are now more open to exploring these asset classes. 

    That’s the beauty about human beings – we’re all survivors. When push comes to shove, we’ll do whatever it takes to survive.

    Do the same with your investment portfolio. You’ve worked hard all your life, so avoid letting these hard earned funds slowly slip away by not maximising your returns. How does investing in Tesla, Geely, Proton, Alibaba, Facebook and Microsoft sound like to you?

    Consider Investing in A Foreign Currency

    For investors who have specific goals such as migration or sending your children abroad for education, you can consider beginning your investment journey in foreign currencies such as GBP, USD, SGD and AUD.

    The benefits of doing this earlier could save you the cost of currency conversions later. Your funds will already be in foreign currency and when the time comes to execute your goal, you save yourself the conversion differences. Use these savings to boost your retirement instead. 

    Work with a Licensed Financial Planner

    The benefits of working with a professional such as Licensed Financial Planner is the unbiased advice you’ll get as well as recommendations on potential investment products that suit your risk tolerance.

    By tapping into their experience, you’re able to cut short your learning process and immediately hop onto the investing bandwagon that goes beyond just fixed deposits. What if there are ways to help you earn an average annual return of 5% to 10%? Would you be willing to give yourself the chance to learn and explore?

    The way forward in this current pandemic setting is to continue to be nimble in everything that you pursue.

    If you’ve always relied on your salary (otherwise known as active income), you ought to start somewhere in building your passive income.

    If your passive income is not growing at the rate that you want it to be, review what works, what doesn’t and explore other options that could take your portfolio further. Change is constant, and the decisions you make determine your destiny.

    Decide and choose what’s best for you. One simple change could drastically change the course of your future!

    About the author

    Suean Chung is a Financial Advisor, approved and licensed by Bank Negara Malaysia and the Securities Commission Malaysia. She can be contacted at sueanchung@harveston.com.my.

  • Should I Adopt Dollar Cost Averaging?

    Should I Adopt Dollar Cost Averaging?

    There are multiple ways to invest, with one of the more passive ways recommended by many is dollar cost averaging.

    “Dollar-cost averaging (DCA) is an investment strategy in which an investor divides up the total amount to be invested across periodic purchases of a target asset in an effort to reduce the impact of volatility on the overall purchase. The purchases occur regardless of the asset’s price and at regular intervals; in effect, this strategy removes much of the detailed work of attempting to time the market in order to make purchases of equities at the best prices.” – Investopedia

    At the core of the fancy lingo used above, it means you put a fixed amount daily/monthly/yearly into a certain investment so that you average out your buy-in price.

    Think of it like gardening where you need to tend to the plants regularly and conscientiously in hopes that it will grow well.

    Dollar-cost Averaging Illustration

    For example, let’s say you’re buying into a Real Estate Investment Trust (REIT) counter on any market in Malaysia. Why? Because in most cases, it gives you steady dividends and that’s why it’s a good place to exercise dollar cost averaging.

    Assume that you allocate RM500 per month to contribute to REIT 1. Every month you diligently buy up RM500 worth of shares in REIT 1.

    I want to present two scenarios here.

    If the prices go up monthly by 10 sen:

      Amount Invested Cumulative Investment Price Investment Value % Gain
    Month 1 500 500 1 500
    Month 2 500 1,000 1.10 1,050 5%
    Month 3 500 1,500 1.20 1,646 10%
    Month 4 500 2,000 1.30 2,283 14%
    Month 5 500 2,500 1.40 2,958 18%
    Month 6 500 3,000 1.50 3,670 22%

    If the prices go down monthly by 10 sen:

      Amount Invested Cumulative Investment Price Investment Value % Loss
    Month 1 500 500 1 500
    Month 2 500 1,000 0.90 950 5%
    Month 3 500 1,500 0.80 1,345 10%
    Month 4 500 2,000 0.70 1,677 16%
    Month 5 500 2,500 0.60 1,937 23%
    Month 6 500 3,000 0.50 2,114 30%

    Can you see the effect it has?

    Pros and Cons of Dollar Cost Averaging

    As you can see in the illustration above, with a 50% increase/decrease in the stock price by month six, the total returns/losses are reduced.

    Yes, it’s a double-edged sword. You minimise your potential losses and hopefully when it rebounds, you’ll get more returns. However, you also lose the full upside if the stock goes up in price.

    The other potential risk here is that in most dollar cost averaging mechanisms, you set a fixed time in a month to invest that sum, such as the start or end of the month, when your salary is in etc. The issue here is that you could also be unlucky in that every time it’s time to invest, it’s at the higher price point for the month. That’s not fantastic but luck does play a part.

    Then why do people recommend dollar cost averaging? If I were to guess, it’s because it gives people the “sense of calmness” that you don’t need to worry about the market’s ups and downs and just need to periodically invest a sum like clockwork.

    I must add on that this was also popularised by mutual funds. At least, that’s where I heard this method being used the most, but I’m sceptical as they’re partially motivated by the sales charge.

    Which brings me to… the case of commissions that we’re paying for any investments (depending on the amount). By doing a monthly dollar cost averaging investment, we’re technically paying 12 times a year at the highest commission rate (in most cases due to smaller investment size).

    With that said, I do think there are uses for dollar cost averaging.

    What Do I Use Dollar Cost Averaging On?

    My journey on dollar cost averaging began with mutual funds. I’ve tried dollar cost averaging via direct debit on mutual funds a long time ago. The market was going up monthly and hence my cost was averaging up. Then one fine day the market decided to take a dip. That’s when I realised that the amount I’ve invested thus far actually suffered a much bigger loss due to my average cost being higher. Hence, I stopped doing dollar cost averaging.

    Another asset that I’ve used dollar cost averaging on is bond funds via robo-advisors because their prices rarely fluctuate too much, but currently the only other investment asset that I practice dollar cost averaging on is gold.

    Averaging Down vs Dollar Cost Averaging

    What I prefer is to use the concept of “averaging down” in my investments.

    I can’t control how the market moves and whether the prices will go up or down after I invest. What I can control is how and when I invest.

    My approach is to always keep a basket of potential stocks in my watchlist. With this shortlist of stocks, I can then monitor where prices are heading. Rather than investing into a stock or any asset when the prices are up, I’d only invest when the prices fall to a target price.

    When investing in a stock or asset, it’s possible that the price will fall below the invested prices. This is where averaging down shines as it takes on the benefit of dollar cost averaging to minimise losses and amplifies the profits via more investment in the particular asset. This is on the assumption that you’re investing in a fundamentally strong asset whereby prices will eventually turn around. However, it could take years in some cases, so patience is needed.

    If prices are above my invested price, then I’d only think about when to realise that investment into profits. I’d seldom add on unless there is a particularly compelling reason to do so and would rather scour my watchlist for other stocks to invest in instead.

    This approach is obviously not too relevant for short term traders but can be beneficial to the long term investors.

    But how about non-stock related investments?

    Modified Dollar Cost Averaging

    For assets such as robo-advisors, bond funds and gold, I do recommend the use of some form of dollar cost averaging. However, I’d keep the monthly amount small.

    Upfront I will invest a lump sum amount and when prices fall substantially, I’ll average down again with a lump sum amount. Hence, I keep a close eye on the prices of these investments and have a ready cash pile to go in when prices are right.

    This is my take on dollar cost averaging. I don’t use a straight up dollar cost averaging strategy as I believe with some active management, I can reap more benefits from my investments.

    About the author

    This article was originally published at betweenthemoney.com, a personal finance website by Jason Loh that focuses on money matters and investment topics for Malaysians

  • FA Advisory: A Journey in Progress

    FA Advisory: A Journey in Progress

    If there’s a word to define FA Advisory, it would be ‘progress’.

    This takes precedence over terms like ‘success’ or ‘achievement’, FA Advisory Sdn Bhd general manager Bryan Zeng muses. This is simply because the financial advisory firm adopts a progressive culture that allows its practitioners to be forward-looking in their unwavering purpose of helping their clients navigate their financial journey.

    “We don’t believe in the status quo. As an organisation, we must continue to progress, and because of that we move the organisation towards innovation. We continue to innovate our processes, and build robust infrastructure so we are able to support our financial practitioners to carry out their duties to the highest standards of professional advice,” he tells Smart Investor.

    But first, a quick history of FA Advisory.

    Established in 2009 under the name Uniplan Advisory Sdn Bhd, the Kuala Lumpur-based firm changed its name to FA Advisory in 2013 when it became a member of the Financial Alliance Group based in Singapore which is, today, the largest independent financial advisory firm in Singapore.

    Home to 67 licensed financial planners across Malaysia, FA Advisory is a one-stop centre for wealth management and financial planning solutions. It offers professional and unbiased advisory services based on detailed analyses of their clients’ financial situations and goals.

    This is followed up with the firm’s capability to implement financial solutions – drawn from their comprehensive range of wealth management services – that best suit their clients’ needs, thus allowing them to enjoy flexibility in mixing and matching the financial benefits they seek.

    Navigating Turbulent Times

    The COVID-19 pandemic has forced businesses of all kinds to rethink how they work and interact with customers. While this is very much the case, it is business as usual for FA Advisory.

    “What we do is regularly engage and communicate with our clients. We do this through various means, including holding talks where we invite our clients to either educate or inform them of the happenings in the markets, and this has been done since day one,” Zeng reveals.

    And so, when the pandemic hit, FA Advisory diversified their touchpoints and increased the frequency of their outreach. This is done by making full use of online meetings/webinar facilities, as well as social media platforms such as Facebook and YouTube.

    Despite the convenience offered by technology, Zeng is quick to point out that the significance of personal engagements is still very much emphasised in their daily operations.

    “During the first month of the Movement Control Order (MCO), we held daily Zoom meetings with our financial planners to communicate, empower, share, and learn from each other,” he recalls, adding their financial planners in turn reached out to their clients with personal telephone calls and messages to show care and encouragement.

    As FA Advisory is about the client, and providing the client with the best possible financial advice, Zeng reveals that when the pandemic led to a nationwide MCO, there were a myriad of issues impacting their clients’ lives.

    “We acted swiftly to provide relevant information to enable our clients to make the right decisions. We have created over 15 YouTube videos to address the concerns related to the stock market volatility. In addition, we have been hosting a bi-weekly webinar on market updates for our clients since March,” he says.

    In fact, the team at FA Advisory had rallied together to create infographics, slides and webinars to guide their clients on the deferment of life insurance premium payments and loan moratorium, alongside other Covid-19 relief initiatives by government agencies and private sectors.

    “It warms our hearts when we receive acknowledgement and messages of appreciation from our clients. If anything, the pandemic has strengthened our resolve and conviction in our mission to champion purposeful financial advice for our clients and elevate life quality for all,” says Zeng.

    The Road Ahead

    Financial planning as an industry has witnessed impressive growth over the past few years, and the pandemic has all but accelerated it as the awareness about financial planning continues to grow and consumers become more informed.

    So, what does this mean for the industry?

    “One of the things that the Covid-19 pandemic has taught us is the importance of being financially prudent. Even as Malaysia progresses towards becoming a high-income and developed nation, the demand for quality advice will continue to grow, and the industry will offer a great career path for young people,” Zeng opines.

    Positive growth notwithstanding, he cautions there are various challenges ahead. Among these is that we live in an age of information overload, with misinformation, fake news and outright scams threatening the financial well-being of individuals and households at unprecedented speed and reach.

    “We must play our part to continue promoting financial literacy and dispensing sound financial advice to members of the public. The advent of fintech has disrupted the financial services industry by empowering consumers with innovative products and myriad choices with great efficiency.

    “Thus, the job of a financial planner is increasingly demanding, and as a firm, we are constantly building our advisory capabilities to address the increasingly complex needs of tomorrow’s consumers.”

    As such, continues Zeng, the future of financial planning will definitely be client-driven.

    “We believe we are in a good position to capitalise on this as our business model has always been client-centric with a personal touch. We are delighted to be in this rewarding profession that enables us to make a meaningful contribution to improve people’s lives,” he concludes.

    By Bernie Yeo

  • The Financial Happiness Formula: Applying DMAS to Life

    The Financial Happiness Formula: Applying DMAS to Life

    Life can be complicated if we choose to make it so. As adults, we should know what makes us happy. Yet, most of us adults have fewer happy moments now compared to when we were younger. Is there a financial happiness formula?

    After years of working experience, I’ve come to realise that the easiest way for us to achieve Financial Happiness is by going back to basics.

    Most of us started our experience in dealing with numbers during our kindergarten years. We learnt about numbers, how to count and perform mathematical operations, geometry, and other math concepts from young till high school and beyond.

    Due to not regularly practising these equations in everyday life, it’s not surprising that most adults develop misconceptions with the order of operations to be performed while solving a mathematical expression (BODMAS – acronym for Bracket, Order, Division, Multiplication, Addition, and Subtraction).

    How Does One Reach Financial Happiness?

    It is normal for us to begin practicing Addition from young, and by the time we joined the workforce, we would’ve become experts at this. Our environment trains us to view the Addition of new “wants” or “needs” positively; as something to be desired.

    However, it’s rare for young adults to be taught how to differentiate between wants versus needs. The perception that “more is better than less” leads us towards the trappings of the proverbial rat race.

    We fail to leverage our understanding of BODMAS in our financial life and furthermore, we aren’t aware of how it plays a vital role in our effort to pursue Financial Happiness.

    BODMAS is the golden rule for solving equations and guides us on how to solve mathematical problems by following the correct sequence, otherwise, our answers may be wrong if we fail to follow the rules. When we apply the BODMAS rule to solve equations, we must first solve the Bracket.

    Subsequently, we solve the Order (that mean powers, roots, etc), then we continue with Division, Multiplication, Addition, and Subtraction. The key point to note is that Division and Multiplication rank equally, and in fact take precedence over Addition and Subtraction.

    Applying DMAS to Life

    Taking a leaf out of the BODMAS system, I’d like to suggest that DMAS (Division, Multiplication, Addition and Subtraction) can be the core approach to solve our personal financial matters.

    Let’s go through an example to see how we can achieve Financial Happiness by applying DMAS in our daily life.

    By following the proper arrangement, we always start with either Division or Multiplication.

    Division is the action of separating or process of splitting things into equal parts. This action and process is so much more meaningful when we apply it to determine our life priorities, for example in areas such as health, relationships, career or how we deal with money.

    Obviously, we all understand that these priorities are equally important and deserve equal attention throughout our lifetime. 

    In fact, changes in life stages and socio-culture environments might lead or force us to make disproportionate choices.

    Common life problems such as financial or health, marriage and family, or career pressures often occur due to mistakes and failure to maintain the balance while fulfilling our needs.

    Hence, a proper and systematic rebalancing strategy (also an important strategy in investment management) will enable us to review our situation and ensure we reposition ourselves at the appropriate ratio.

    Multiplication gives the results of combining groups of equal sizes whereby we can consider it as repeated addition, creating a larger whole. Multiplication in finance is always related to the rule of compounding, and it amplifies our financial condition, either positively or negatively.

    If we start off on the wrong foot, we’ll most likely end up with a bigger mistake. This can be clearly seen in the increasing number of Malaysians declared bankrupt or affected by overwhelming debts, especially credit card debts.

    We should recognise that the rule of Multiplication is not limited to money but also other scarce resources such as our networks and knowledge.

    As long as we’re able to identify the appropriate resources we want to grow, by putting enough time and effort, we will reap what we sow.

    After applying both Division and Multiplication, you may now continue with Addition and Subtraction.

    Addition of two whole numbers results in the total amount. In life, we tend to add new compartments by fate or chance. Given the same 24 hours a day or 365 days a year, we never tire of being attracted to new things and adding them to our bucket list.

    All of us have a different threshold and we should know better the tipping point of fulfilling our own desires as we become older and more experienced.

    Always take into consideration the results you will likely get from Division and Multiplication mentioned above. When the time is right, consider adding a new skill to grow your career, a new asset class into your investment horizon, or a good hobby or habit that helps you to excel in life.

    Subtraction is the operation of removing objects from a collection. It’s not an easy task for us to practice even though more people are now attracted to the KonMari Method. With respect to financial matters, you may want to consider the two subtractions below:

    1. Get rid of negative financial thoughts
    2. Eliminate unwanted financial habits

    There are no shortcuts to Financial Happiness. It only seems impossible if we don’t act at all. Apply the basic rules of DMAS patiently and wisely, and you will have an easier journey to achieve Financial Happiness.

    About the author 

    Jess Hon is a Licensed Financial Planner and can be contacted at jesshon@finwealth.com.my.

  • Does Value Investing Work?

    Does Value Investing Work?

    For decades, value investing has been popular with financial luminaries like Ben Graham and Warren Buffett, who is arguably the most famous investor in the world. Buffett is renowned for his investing style which is “value investing”. Many are curious about what value investing is and whether the concept still works in an environment where the Covid-19 pandemic is plaguing the whole world.

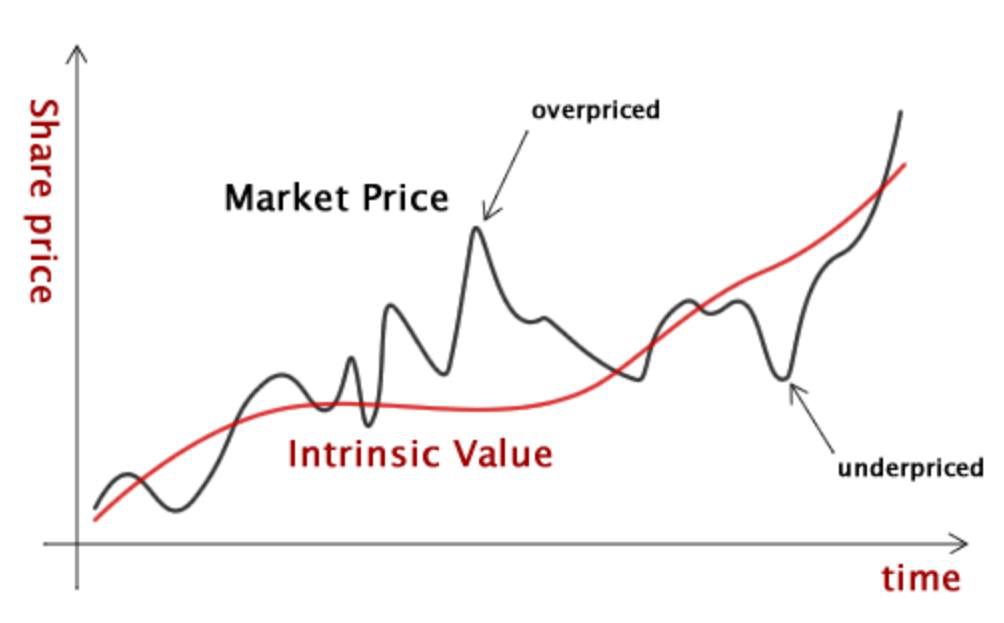
    Firstly, investors must understand how value investing works. In layman terms, value investing is a strategy for taking advantage of the market at the right moment. It’s based on the idea of “appraising” stocks, with value investing advocating hunting for stocks that are undervalued based on their “intrinsic value”, before buying them, holding them and weathering the volatility of the market. In theory, a company’s stock value should be the same as its market price but in many cases, this doesn’t hold true. It’s possible that stocks could be overvalued and at other times, it’s undervalued.

    To carry out this strategy, the investor will be required to analyse the company’s fundamentals and project the future profits that the business is going to generate in its lifetime and with that the investor is able to assess whether the company is underestimated in the market or not. If so, you get to buy its stocks at a bargain in the hopes that the market will turn in their favour over the long run. These value stocks are being sold below their intrinsic value and have huge potential to grow in the future when the price is adjusted accordingly.

    Although the concept seems simple, value investing is extremely difficult to implement properly and requires rigorous analysis to determine what the “underlying value” of a stock is. In today’s environment, investors must consider geopolitical factors, fiscal or monetary policies, currency, business model, supply and demand of the company’s services or products, and other underlying factors.

    stock analytic chart

    Understanding Value Investing is Vital before Making any Investments

    If you look at the chart above, the red line indicates the company’s potential or intrinsic value. In the beginning, due to its low value, the market misinterpreted the situation and quickly undervalued its stock. Value investors wait for this golden opportunity to buy the shares at a discounted price. They know the company has future growth potential. Then, they sell their stock when the market price is overvalued, earning them a nice, big profit. 

    For example, let’s take Microsoft whose product is widely used and accounts for 76.56% share of its industry as of December 2020 according to Statista.com and has about 1.5 billion active users worldwide. On average, its net income margin is about 25% per year and it consistently manages to turn over healthy profits. Despite the Covid-19 outbreak, its products were still massively used but during the pandemic selloff in March 2020, it lost about 25% of its share value. 

    Putting the factor of the COVID-19 outbreak aside, this company maintained good, continuous growth, and its share value grew about 23,000% in the last 30 years. Using the value investing strategy, one will see a huge opportunity in this company due to its nature of business, as well as the demand for its service and product continuing even during a pandemic. 

    (*Note: This should not be taken as financial advice or a buy recommendation.)

    Like all investment strategies, patience and diligence to stick to the investment philosophy is a requirement. There will be days when an investor may want to purchase some stocks because the fundamentals are sound, but he or she may have to wait if it’s overpriced at that time.

    If investors are unable to properly carry out this strategy themselves or commit to the time needed to invest themselves, it’s always advisable for them to seek for professional advice or seek a proper licensed financial planner or financial advisor to assist them. These professionals will be able to offer advice according to the investors’ risk appetite, goals and objectives. Other factors will also be used to evaluate the investors’ current financial condition before such advice is given.

    Conclusion

    Therefore, do buy the stock that is most attractively priced at that moment, and if there is none that meets the criteria, just sit and wait and let the cash sit idle until an opportunity arises. The bottom line is, value investing is a long-term strategy, it requires hard, there is no short cut and it works as Warren Buffett is still a devoted advocate of this strategy.

    About the author 

    Alex Ng Wern Ping is a licensed financial planner, and can be contacted at alexng.alpineadvisory@gmail.com.