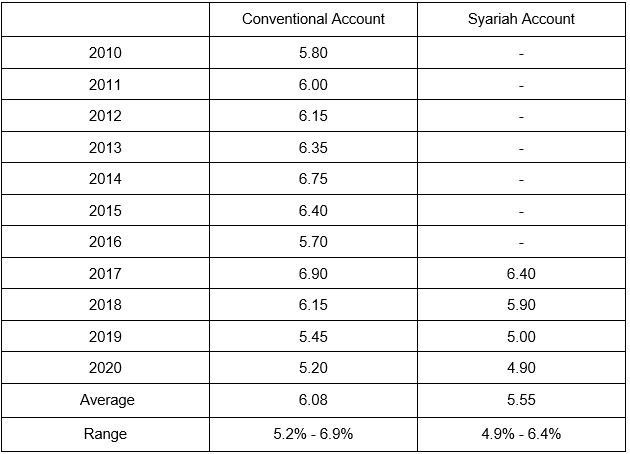
Category: business

  • What Is Your Money Mindset?

    What Is Your Money Mindset?

    This is the first part of this six-part series, where these topics will guide those who have just started to work or have just started their journey to build a strong financial foundation. Before we set out to achieve anything, it always starts with our mindset. 

    How do you know what your money mindset is? It’s how you feel about and view money. It helps to form your decisions on how you manage money by saving or spending it. How you believe money can work for or with you, will decide how you live your life in the future. Every single day, you’ll make many small decisions that will push you forward financially or set you on a reverse course; it’s entirely up to you! 

    Some of the great money mindsets are listed below:

    • I have the ability to spend but I also empower myself to say “No”
    • Everyone has their own path and I have mine
    • Achieving financial goals are possible when I work towards them

    As Henry Ford said, “Whether you think you can, or think you can’t – you’re right.”

    Here are three ways to improve your money mindset:

    1. Money is a tool, not a goal

    Think of money as the fuel to your car. Is fuel considered the destination or is it one of the raw materials needed by your car to bring you to your destination? 

    If your answer is the latter, that’s correct! We exchange our time, energy and skills to earn money to buy us the things we need or want. Through your various life experiences, you may think that money is the answer to everything, but this isn’t true if you don’t know how you would like money to help you in life.  

    When you start seeing money as a tool, it’ll help you think about what your actual goal is. A simple goal could be living a life filled with fun and joy, where you enjoy travelling and eating – this will require money in order for you to fulfil this goal. 

    As you start setting goals for yourself to aim for, they also provide a purpose for your money to work on and naturally, you will start allocating your money to where it should belong. 

    2. Money needs to be managed

    Did you know that most winners of the lottery actually end up losing all the money they won and go bankrupt in a few years? This is hardly surprising because if a person doesn’t know how to manage RM1,000, then they will definitely not know how to manage RM10,000. The same logic also applies to you. If you work smart and hard to earn the money you have, why not take the initiative to learn how to manage, allocate and save your money? 

    You can set up a few accounts to save and segregate your money. For starters, these could be a savings account, fixed deposit and money market. Although these accounts may not serve as long-term wealth builders, you can use them to practice saving what you earn. When you continue practicing this, it then develops to become a habit. 

    Assume your total take home pay for the next five years of working is RM200,000. How much do you think you would like to keep from this amount? Would you like to save RM20,000 or RM40,000 or even more? What you want to save entirely depends on you. 

    3. Using money is like two sides of the same coin

    The “opportunity cost” or “trade-off” is defined as the loss of alternative choices when you make a decision on how to use your money. This is the same thing that happens if you flip a coin – it either lands on heads or the tails, and never on both sides.

    For example, let’s say you decide to save RM10,000 every year from your take home income of RM50,000. By saving this RM10,000, you gain additional money in your savings account. However, you may miss out on having more fun by travelling, purchasing new gadgets, or buying new furniture that you might want to have. 

    Before making any decisions regarding money, learn to think about the potential opportunity cost or trade-off that you have to make. Will it be something you’re willing to miss out on? Would the trade-off matter in the years to come? Would your decision help to build the life that you want in the future? 

    If the decision isn’t urgent and involves an amount of money that’s a lot to you, and you’re not comfortable making it, then don’t. There is no harm in pausing and thinking through or seeking opinions from the financial planners that you know. For all you know, you may have just saved yourself from future troubles if the initial decision goes against you. 

    Finally, improving your mindset isn’t a “been there, done that” type of destination. It’s a continuous effort to enhance and practice, just like how we build our body muscle, otherwise our body muscle will slowly turn into…body fat. 

    Stay tuned for my next topic in this series!

    About the author 

    Fong Woon Bing is a licensed financial planner who has coached, improved and broadened the mindsets of many people whom he works with, bringing them closer towards achieving their life and financial goals. He can be contacted at fongwoonbing@vka.com.my
  • Tax Obligations For Self-Employed Entrepreneurs

    Tax Obligations For Self-Employed Entrepreneurs

    With the rise of self-employed entrepreneurs, here are some tax compliance obligations and common oversights.

    There has been a dramatic growth in recent years on the number of self-employed entrepreneurs in Malaysia. From 2017 to 2018 alone, this number increased from 2.57 million to 2.86 million, an increase of 11.3% (source: Department of Statistics, Malaysia). In 2018, the self-employed are the second largest category (19.3%) in the Malaysian workforce out of a total of 14.8 million working adults.

    Malaysia adopts a self-assessment system where taxpayers are responsible to determine their own tax liability and to submit their tax returns accordingly. As the number of self-employed entrepreneurs continues to grow in the Covid-19 economy, it is important for the self-employed to be aware of one’s tax obligations especially in the area of tax compliance. Failure to do so could result in penalties and additional tax payable.

    A self-employed person is an independent contractor or a sole proprietor. The self-employed consists of sub-contractors working in the trades or construction sectors to professionals such as doctors, lawyers, accountants, engineers, and management consultants. Recent iterations include freelancers working in the commonly named “gig economy” (such as e-hailing drivers).

    Here are some tax compliance obligations a self-employed individual should take note of:

    1. Registration of Tax Identification Number (TIN) and submission of tax return

    A self-employed individual should register for a TIN when the person has taxable income which exceeds a threshold of approximately RM28,000 per annum. A TIN can be registered at the nearest Inland Revenue Branch (IRB) branch or via e-Daftar at the IRB website.

    For entrepreneurs running a business, the income tax return (Form B) will need to be submitted by 30 June the following year (eg. Form B for the year of assessment 2020 is due by 30 June 2021*extended to 30 September 2021 due to Government movement control, IRB website)

    2. Estimate of Tax Payable

    Under the Malaysian tax regime, a taxpayer pays income taxes on a “Pay-As-You-Earn” basis. Where an individual taxpayer receives other than employment income, the IRB may issue a Form CP500 setting out the estimate of tax payable under an instalment scheme. The Form CP500 is determined based on the tax liability of the previous year. What should you take note of:

    • The tax estimate is six (6) bi-monthly instalments commencing from the month of March every year.
    • Each tax instalment payment needs to be made within 30 days from the due date.
    • The remittance slip (Form CP501) should be submitted together with the instalment payment.
    • Should there be a need to revise the tax estimate which affects the instalment amount, you must submit Form CP502 to the IRB not later than 30 June each year on the revision payments. The IRB will issue a Form CP503 if the application is successful.
    • The penalty for late payment of 10% shall be imposed on the unpaid amount if the tax instalment payment has not been paid within 30 days from the due date.
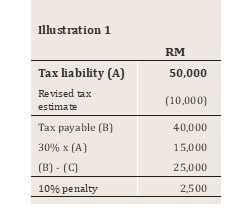
    • Where there is a difference between the revised tax estimate submitted and the final tax liability which exceeds 30% of the tax payable, the difference will be subject to a penalty of 10%.

    The following illustration shows the impact when an estimate of tax payable is inaccurate.

    3.Employer’s Responsibilities

    As an entrepreneur, you might hire employees to expand your business. In this case, you will be considered as an Employer for tax purposes. The responsibilities of an Employer are as follows:

    • The Employer is to inform IRB of any new employees within one month from the date of commencement of employment.
    • Submission of Return of Remuneration by an Employer (Form E) to the IRB on or before 31 March each year. <continues…>

    [ You may read the full article HERE ]


  • How COVID-19 Affected Our Favoured Investment Themes

    How COVID-19 Affected Our Favoured Investment Themes

    Schroders identifies eight themes that could transform the world, but how are these being affected by the coronavirus?

    At the core of thematic investing at Schroders is the belief that the most powerful and persistent investment themes are those where human ingenuity ignites innovation to address imbalances in the world. These imbalances may be between populations and resources, or between supply and demand in individual industries.

    As we all know, necessity is the mother of invention. As coronavirus throws the whole world into turmoil, humanity’s ingenuity and powers of innovation are being mobilised to fight the disease, care for our populations and adapt our work and home lives to a new set of economic, political and social realities.

    Covid-19 is exacerbating existing tensions between populations and finite resources and dislocating supply and demand relationships in countless industries. Bearing this is mind, we examine the impact of this crisis on the eight investment themes that we think have the potential to transform the world we live in:

    1.HEALTHCARE INNOVATION

    “Crisis highlights importance of healthcare innovation”

    This pandemic underscores the critical societal importance of healthcare innovation as countries seek to prevent and cure disease while wrestling with ongoing demographic and budgetary challenges. Central to our investment thinking in this area is the belief that science and technology will be crucial as companies harness data, computing power and medical knowledge to meet these goals.

    We believe this will drive further breakthroughs in advanced therapies, medical technology, and healthcare services as well as in digital healthcare where technology in the form of ‘telehealth’ has shown its worth during this crisis as a means of making healthcare provision more responsive and efficient. As governments realise their vulnerability to pandemics, the drive to spend more on healthcare in the future can only intensify.

    2.SMART MANUFACTURING

    “Smart manufacturing essential as demand fluctuates”

    Amid the acute demand and supply shock experienced by the global economy, manufacturers are also having to innovate. We expect to see companies developing local supply lines alongside their existing global networks while investment in data analytics will be imperative as a means of understanding and managing volatile demand and disrupted procurement in the future.

    Investment will also take place in other smart manufacturing themes, including advanced manufacturing such as 3D printing, automation in the shape of robotics, sensors and controls, and advanced materials like lightweight composites as companies harness exciting innovations in hardware, software and materials to deliver greater agility.

    While manufacturers face undoubted short-term headwinds, the disruption caused by Covid-19 demonstrates the importance of manufacturing innovation to ensure responsiveness and productivity in both good times and bad

    3.CHANGING LIFESTYLE

    “E-commerce and well- being are growing lifestyle trends”

    […continue to read this full article HERE ]

  • How to Make a Financial Plan for Myself As a Beginner?

    How to Make a Financial Plan for Myself As a Beginner?

    A good financial plan creates a roadmap or a guiding light for your financial life journey. It’s more than money and gives you an overall picture of where you stand financially and where you’re heading to. It should include financial details about your cash flow, savings, debts, investments, insurance, and any other aspects of your finances. Financial planning is an ongoing process that allows you to get your money and life under control so that you can reduce stress, fear, and worries about your future life. I think everyone should have one, and it can be done in your own style or with a financial planner. Remember, financial planning is not only for the wealthy or people earning a high income. You don’t need sophisticated software or tools to draw up your own financial plan; instead a blank piece of paper will help you to kick start the process. Start by listing down what you have (assets eg. savings account, EPF, investment account, investment property, business, etc.) and what you owe (liabilities eg. mortgage loan, car loan, personal loan, credit card, study loan, etc.), income (cash inflow) and expenses (cash outflow). This will give you a snapshot of whether you’re at a financial surplus or deficit, making it easier to work out a financial plan – covered in the next step.

    Setting goals for your financial plan

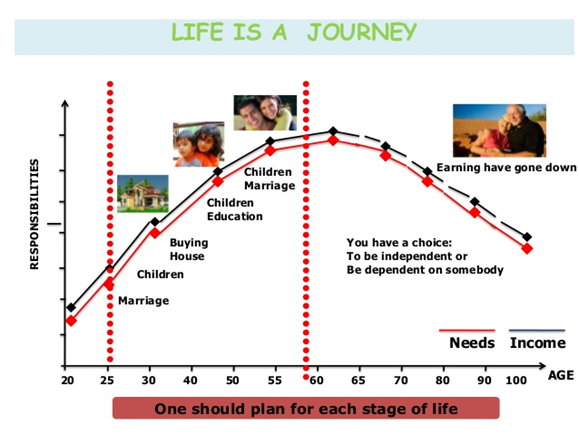
    This is where you decide how to design your own life. When crafting your own financial plan from the viewpoint of what your money can do for you, you’ll make saving and investing feel more intentional than overspending it. Your goals should be inspirational, measurable, and realistic – ask yourself where do you see yourself in five years’, 10 years’ or even 20 years’ time? It’s important because it gives you direction to achieve your financial goals at different life stages and it also influences how you plan your career as well. For example, there will be different needs when doing financial planning in your 20s, 30s, 40s and 50s. In your 20s, you might want to make sure you have sufficient emergency savings that lasts for at least three to six months so that in emergencies you won’t  be running on credit. Don’t forget to factor in insurance and ensure you get adequate coverage for personal accidents and a medical plan. In your 30s to 50s, you’ll likely be experiencing high commitments due to getting married, raising kids, preparing university tuition fees, and funding your retirement fund. As you progress from different life stages, you’ll need to regularly keep an eye on your allocations for investing and spending. If you know that these things will happen in your 30s to 50s, you may save and invest more in your 20s or prolong the retirement age from 55 to 60.

    Monthly budgeting for your financial plan

    The next step is to allocate your monthly budgeting – what is coming in and what is going out to understand your spending habits and only able to take a balance between spending and savings. It depends on where you live and how you spend – living in an urban area may result in spending more due to higher rent, eating out more etc. If you don’t spend more than half of your income, then you can start saving enough to fund your goals. Of course, you can’t own the whole world, but you can own the things that you value the most!

    Executing your financial plan

    This is all about allocating your resources or cash surplus to fund your goals. Saving and investing must come into play and you should consider the types of financial products, the risks, returns and liquidity, as well as understanding your risk tolerance. For example, if you set aside 15% of your gross income for long-term goals like retirement, you may consider investing in stocks or equity funds that aim for capital appreciation. For shorter goals like saving for an emergency fund, you wouldn’t put your money in a high-risk fund because you might need it quickly in an emergency. It’s best to have separate accounts for different funding purposes.

    Review your financial plan

    Lastly, review and monitor your financial plan regularly to ensure you exercise strict discipline with the flexibility to adjust accordingly in the future, especially when entering different life stages. It’s easy to talk and plan, but execution remains the most challenging task as we may not have the discipline to stay on track. So, reviewing, monitoring and fine-tuning acts as reminders of your goals all the time. It’s best if you can make it measurable so that you can reward yourself with small gift when you are on track!
      A good financial plan is not a beautifully written document that is presented nicely to you. It’s a tool to track your progress and help you reevaluate plans after a life milestone such as getting married, raising a kid, buying your first property, upgrading to a new car, preparing for a kid’s college fee, or building your retirement fund. When everything is handled, you can enjoy living your life. The small steps you are taking now will definitely have a huge, positive impact on your future.

    About the author 

    Eewen is a licensed financial planner and strongly upholds the belief that financial wellness is all about money bringing a positive impact into your life. She can be contacted at keaheewen@vka.com.my
  • What I Learned From a Free Financial Health Check

    What I Learned From a Free Financial Health Check

    Nowadays, the words “health” and “healthy” are very important. While the pandemic has taught many people different lessons, one of the most central ones is that it’s important for us to be healthy. Without good health, all other things may not take place, or be sustainable. The concept of being healthy isn’t just limited to medicines or the fitness industry – it’s also widely used in the financial industry. These days, there are plenty of marketing messages that have the phrase “Financial Health” or “Financial Health Check” in a big, hard-to-miss font! At a glance, it seems that we can get free financial health checks from different companies that offer different kinds of products. Life insurance companies offer this, banks may also offer this service, and in social media, we can see many different individuals, or product companies offering this, for free! As a curious person, I tend to try out new things. And the most memorable one, I’d say, is one by a reputable insurance company offering a financial health check. I logged in to the portal to do mine; a few questions were asked about my age, marital status and whether I have children. It then asked me to rate a few scenarios that “concerns me”:
    • Hospitalisation
    • In the event I’m diagnosed with critical illness
    • In the event I’m disabled
    • In the event I meet with an accident
    • If I’m concern about money for my children’s education
    After these questions, the next segment asked me to indicate how much insurance I have in respect to the areas mentioned above, followed by a question of how much of my current income goes to insurance premiums. Boom, the results came out and I was eager to see if I’m considered financially healthy! The results show me, based on the coverage amount I keyed earlier, compared to people like me at this insurance company, whether I had higher or lower coverage for the respective areas. It even comes with a recommendation of what I “need”. You get it – according to this financial health check, I need more insurance products! Just like this, am I supposed to say I’m financially healthier than most just because I have higher coverage on death and total permanent disability? Am I supposed to feel concerned just because “people like me” at this insurance company have a RM20,000 paid savings plan, but I have RM0; does that make me a bad father? Comparing our situation to “people like me” as defined by a company, isn’t a good way to assess if we’re financially healthy. If this is a good approach, we should start comparing our situation to people in other countries, societies, and at other offices. But what is a fitting benchmark for this? If this is considered a good approach, then if “people like me” in this country have a high amount of debt, should I start going all out and accumulating debt? I’m not sure how this makes any sense. It may make sense to some, but I’m still looking for a good explanation! Comparison is the root of all evil and how we lose the clarity we need to live our own life. It also helps in feeding insecurity, jealousy, greed and other emotions that don’t empower us to be a better version of ourselves. I think that if we want to understand if we’re financially healthy, it’s because we want to know if we have a good financial foundation. It’s like a table with four legs; we want to know if these four legs are strong enough, or whether it’s unstable and at risk of collapsing. We need this information because we care about maintaining the table and want it to continue being stable so that what’s on the table will be sustained and maintained. In life, what’s on my table will be what’s important to me. For me, this includes my family, what kind of difference I can bring to the society, whether I’m making a difference, and helping people be better than they were the day before. But, without those four legs supporting my table top, these three items may not be around for long. In the context of money and life, we can start from these four legs to find out if we’re financially healthy.

    What are these four legs?

    Emergency savings

    For a start, I’d suggest looking at your emergency savings. If your savings can support you during sudden spikes in unexpected expenses, or ensure you go through challenging times when you lose your main income without having to lose sleep, your leg is quite stable and strong.

    Are you saving enough?

    Assess if you’re saving part of your income. A person spending all their income today will probably have to always look for money. The day their income stops, they’ll have issues maintaining the lifestyle they lead. On the contrary, a person who saves too much of their income today may not be able to enjoy life at all. Striking a balance seems to be important since none of us know if we’ll get the chance to enjoy our savings 20 years later.

    Debt and commitments

    Take a look at your debt situation. Do you have a habit of carrying outstanding debts forward month to month? How much of your take-home pay are you using to pay off loan instalments? If this amount takes up most of your income, it means you probably have less freedom and flexibility to try something new, since there are weights dragging this leg down. This means you may not be able to put on more weight to your table top.

    Life goals

    Finally, how well have you been preparing to achieve your life goals? For instance, my family is important to me, and if I were to leave them too soon, how long can they continue with minimal disruption? Have I done anything to ensure my frozen estate can reach them as quickly as possible with minimal costs? Am I on-track to provide my child with the kind of education I want? By looking at your financial progress from this perspective, the benchmark you’ll use isn’t public, but rather what you want, and compared to where you are now. This allows you to fairly review the legs of your table. It’ll help you stay on-track and compare your current situation to your ideal goals instead of other people’s. The points above are the four basic areas I think we should review if we want to understand our financial health. Of course, there are more areas such as if assets are optimised or liquid enough, ways to legally reduce taxes, or reducing the fees and cost we pay when we grow our wealth, etc. But this is a good starting point. When was the last time you did a financial health check? By being part of the Money Warriors Community, you can learn how to make improvements to the four basic areas – save more, spend with peace of mind, reduce your debt, and be brave when you think of money.

    About the author

    Kevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my. 
  • How Much Risk Should You Take With Your Investment Portfolio?

    How Much Risk Should You Take With Your Investment Portfolio?

    During these turbulent economic times, people may be tempted into taking drastic action with their investment portfolio. For example, if a RM100,000 investment is reduced to RM80,000, that may trigger various reactions towards that RM20,000 loss, such as selling all or some portion of the investment, buying more of that investment, or even doing nothing at all. 

    These possible reactions from different individuals can provide some important insights into risk profiling. With the current volatile market conditions, understanding investment risk and implementing a systematic investment plan would assist investors to meet their long-term financial goals. Investors might typically ask “What are the risks involved in portfolio investment? What is a safe investment portfolio? How much risk should I take?”

    1. Volatility, market information and noise traders

    Proper research prior to investing is crucial as it’s important to understand the types of risk associated with each investment. However, investors tend to be confused between the concepts of ‘risk’ and ‘volatility’. In financial terminology, risk refers to the probability of losing an investment capital based on the expected return on any particular investment. Meanwhile, volatility measures price fluctuations in a security, portfolio or market segment. Typically, market news, such as changes in the company’s management team or an announcement about share dividend payouts, can result in stock price volatility. 

    There’s a growing number of information channels now serving the market, to the point that investors aren’t able to monitor every piece of information released. In fact, many investment decisions are influenced by emotions rather than rationality, which makes them difficult to manage. This is because emotional investment reactions cause short-term volatility. For example, positive news usually gives happiness to the investor, while negative news can lead to excessive reactions.

    Emotional investments are usually revealed through the distinction between informed and uninformed investors (noise traders) and how they interpret market information. Meanwhile, noise traders refers to investors who trade based on what they falsely believe to be special information or their misinterpretation of useful information regarding the future price or payouts of a risky asset.

    One of the factors of noise trading is the need for liquidity. To be specific, investors may liquidate an investment in order to reduce the risk factors. They tend to buy and sell on market reaction. This is an impulsive action based on irrational exuberance or emotions, such as fear or greed, without any major consideration on the long-term returns.

    2. Making informed investment decisions

    In reality, investors become highly emotional upon experiencing losses to the point of even selling off their investment. Therefore, frequent updates of risk profiling are essential in order to match the investment portfolio with the investor’s risk appetite. By performing risk profiling, investment advisers would be able to identify the investor’s level of required returns and their risk appetite in terms of capacity and tolerance. As a result, their investment objectives could be better achieved.

    Risk profiling involves three types of risk measurement: risk capacity, risk required and risk tolerance. Risk capacity is a mathematical measure of the maximum level of risk that the investor could manage before it affects his/her financial goals. Therefore, this should be determined in the early phase of the risk profiling process, and act as a reference for the investment portfolio risk. Furthermore, risk capacity could be used during risk analysis to help determine the choice of appropriate risk responses. Moreover, it would also help manage financial risk shifts in the long term. This is also influenced by the investor’s financial factors, such as promotion or job loss, new-born child, or health issue that could lead to unpredictable medical bills.

    While the risk capacity indicates the maximum level of risk that an investor can manage, the risk required refers to the optimal level of risk managed by the investor to achieve the desired level of investment return. Reaching this level is essential to fulfil the investor’s investment objectives and it also shows the direct correlation of the required risk with the investor’s required level of return.

    3. Systematic investing

    There are two concepts to be considered by investors in systematic investing, namely diversification and dollar-cost averaging. Based on classical finance theory, an investor’s risk-averse traits will determine the proportion of allocation between a number of risky and less risky assets.

    Asset allocation refers to a strategy used by individuals to divide their investment portfolio between diverse categories to minimise their investment risks. This strategy is in line with the saying ‘do not put all your eggs in one basket’. Moreover, investors can choose to invest in the money market, fixed income and equity market. The asset allocation in the investment portfolio will reflect the investor’s need for growth, income and liquidity. Therefore, the allocation should cover the investment horizons, risk-free rates and expected returns on risky assets.

    The dollar-cost averaging (DCA) strategy implements a regular and periodic purchasing of an investment.  DCA gained popularity among financial advisers and individual investors after the recession throughout the mid-1960s. Furthermore, it encourages the investment of the same amount of money rather than the same number of shares each period. As a result, investors can purchase more shares at a lower price compared to when the shares are priced higher.

    4. Periodic review

    It’s highly recommended that investors should regularly review their investment portfolio to make sure that their investment performance is in line with their expected returns and investment objectives. In the current volatile market, some investments may present good performance at times, while there are times when their performances won’t be as good, and vice versa. If this isn’t done, an investment with poor performance could significantly affect the whole portfolio’s returns, especially if it constitutes a big part of the portfolio.

    By reviewing the investment portfolio, investors would be able to separate their emotions and tactical decisions from their pure investment processes. However, the key question is when investors should review their investment. In general, a review of investment portfolios should be done with their financial advisers on a yearly basis, but additional reviews should also be done when investors go through different stages of life.

    To illustrate this point, during the early stages of an investor’s career, he or she would usually need a combination of liquidity and growth in their portfolio. Throughout their employment period, their risk and return preferences will reflect that they have stable incomes and they may experience an increase in their commitments and goals. Following that, as they approach retirement, the investment portfolio should primarily reflect their need for income, including several stages of growth to manage the effects of inflation. 

    Conclusion

    Investor anxiety over a decrease in investment value by more than 30% is inevitable. In fact, when the market faces extreme volatility, some investors choose to rely on their instinct to make investment decisions instead of data and trends. While there may be a few extraordinary individuals who may make the right calls, most individuals end up making huge mistakes. 

    Essentially, risk is a natural component of investment. However, greater knowledge regarding the risks associated with investment and the practice of risk profiling would assist investors in determining their comfort level and building their portfolios and expectations accordingly.

    About the author

    Joe Tiong, CFP, Investment and Financial Planning Unit at UOB Kay Hian Wealth Advisors Sdn. Bhd. Her expertise is focused on financial planning and wealth management across an investor’s life cycle. She is also responsible for equipping financial advisors with the right skillset and materials in conducting business. She can be contacted at joe.tiong@uobkayhian.com

  • Legacy Planning – It’s Now or Never!

    Legacy Planning – It’s Now or Never!

    Legacy planning. Estate planning. Succession planning. What do all these phrases mean? Am I too young or is it too early to consider such plans? Life as we know it, does not always go according to plan. For example, an unexpected pandemic may have forced a career change on you. Suddenly, you need to dip into your retirement fund for some emergency funds – which would leave you with a depleted income when you reach the age of retirement. What is more worrying is that when your business encounters financial trouble, it leads to more money being pumped from your retirement fund into the business. Would your retirement plan that was created a decade ago still be sufficient? Would you still be able to leave a legacy for your family and protect them from uncertainties in life? Unlikely. It is common for us to think of investment and insurance after settling down, but what about legacy creation and why is it important?

    Legacy planning

    Legacy planning takes on many meanings for different people. However, the focus remains – will I have a lasting and positive impact on the lives of my loved ones? While some have given some consideration to their legacy, most have never put it in writing, and even fewer have established a plan of action. affin maximiser As a doting provider, you would want your family to inherit the fruits of your labour and ensure that they will always be well looked after especially in later years. With legacy planning, it allows you to pass on what is most important to your loved ones without compromising your current and future lifestyle. With adequate legacy planning, you will be able to increase your estate, enjoy greater liquidity and ensure fair distribution should any unforeseen circumstances occur while benefiting from financial freedom in your golden years.
    Estate equalisation and succession planning

    For those who own a family business, one of the challenges is figuring out how to pass on the business to the next generation, especially when one child participates in the business and the other does not. While you want to leave a good legacy for your family, you would also like to ensure that the inheritance is fairly distributed to maintain the peace and harmony of the family. With fair distribution it can help to mitigate family problems which may arise when the distribution of an estate appears unevenly allocated. If your wealth changes your life for the better, you are successful. If your wealth changes others’ lives for the better, you have created a legacy. What legacy will you leave behind? When is the right time for such commitment? The answer is now or the sooner the better. However, there are a few things to be considered such as:
    1. How much do you want to invest?

    Are you looking to invest a lump sum, or set aside a regular monthly amount? And how much money do you – make available for investment? Is this your emergency fund? You are advised not to use your emergency funds for investment.

    2. How long do you want to invest?

    Certain investment products run for a fixed period, so if you have a specific date in mind as to when you need access to your funds, then some product types might not be necessarily right for you.

    3. What is your risk profile?

    How do you feel about investment risk? As the saying goes: the higher the risk, the higher the potential returns. Imagine if you incur losses on your investment; what is your risk appetite and how much loss can you stomach?

    4. How much flexibility do you need?

    It is important to note that when you invest your money, it can get tied up and is no longer easily accessible. But, if you have a sudden need for cash, how quickly and easily can you liquidate your asset? And what is the penalty for doing this? It is always a good idea to consult an appropriate professional or financial adviser on the particular investment in relation to your own circumstances. Alternatively, you could consider Affin Maximiser, an investment-linked plan with flexible investment options to help you gain more. You can choose to invest into different investment funds across both local and regional markets to diversify and balance the risks of your investment portfolio. Top-up your investment for more potential returns and get rewarded with loyalty bonus and extra allocation as you invest.

    AFFIN Maximiser

    Your investment objectives may change over time, and Affin Maximiser gives you greater flexibility to reallocate your investment funds or change your selection of funds without any switching fee. As you may have different financial needs at different life stages, this plan allows you to withdraw your investment funds in part to accommodate your financial needs at any time. Being more than just an investment tool, this plan also provides insurance protection of up to four times in the event of death or total permanent disability. From now till 31 July 2021, all Affin Bank customers can enjoy a fuss-free enrolment via the Maxi Easi Campaign with no medical check-up required. If you have a moderate risk appetite, are able to commit to a long-term investment and looking for protection at the same time, then this might be a suitable plan for you. Or, if you are unsure of your risk appetite, feel free to speak to our Affin Personal Banker/Relationship Manager at your nearest Affin Bank branch. Click here to learn more about this product.
  • 5 Things You Must Know About The EPF Investment Scheme

    5 Things You Must Know About The EPF Investment Scheme

    “Soo Yee, I can’t make any investments. I don’t have money left every month, how do I even invest?” This is a common reply when I bring out the topic of investment. And no, you don’t really need a large amount of cash savings to start investing! Did you know that you have the option to invest your EPF monies into EPF approved investments via the Member Investment Scheme (MIS)? Let me explain more below.

    1. EPF Member Investment Scheme (MIS)

    MIS was introduced back in November 1996 for EPF members to diversify, boost and strengthen their retirement savings. In short, if you have enough funds in your EPF account 1, you can invest part of the funds into EPF approved investments via appointed fund management institutions (FMIs) including Unit Trust Management Companies and Asset Management Companies.

    2. Advantages of MIS

    a. Allows you to enhance investment returns

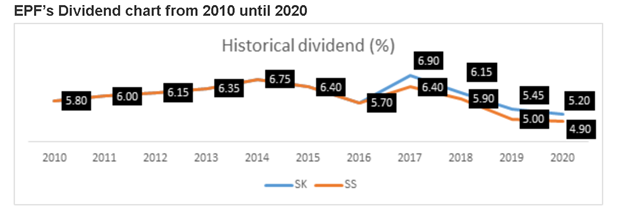
    At the end of February 2021, EPF announced the 2020 dividend rate for Conventional accounts and Syariah accounts, paying out 5.2% and 4.9% respectively. But what has the historical rate of EPF dividends looked like?
    EPF's evident chart, epf member investment scheme
    SK = Conventional Account SS = Syariah Account The graph above is taken from the EPF website (as of 26 May 2021) epf graph - epf member investment scheme So while EPF has been paying a solid return each year, MIS provides the opportunity and potential for you to increase your investment returns and boost your retirement savings overall.
    b. Enables you to increase exposure to foreign markets

    Have you thought about where EPF decides to invest your money? As at December 2020, EPF invested 67% of its investment assets in Malaysia and the remaining 33% outside Malaysia. The numbers show that the majority of your EPF money is invested in Malaysia. So if you’d like to have greater exposure to foreign markets, you can diversify your investments overseas via MIS.

    c. Empowers you to have some control over your EPF investment

    You can now choose to invest according to your risk profile. There are EPF approved investment options for you to match your objectives and risk appetite.

    3. Disadvantages of MIS 

    a. No guarantee of investment returns

    For all its benefits, please note that any investment done via MIS doesn’t come with any guaranteed return, while EPF has a minimum guarantee of 2.5% dividend. You might get a higher or lower return compared to the EPF dividend rate, depending on your actual investment return. You are solely responsible for the investment via MIS that you made.

    b. Not entitled to EPF dividends

    One of the big downsides is that the EPF money that you channel into MIS is no longer eligible for EPF dividends. Basically, you’re on your own. However, if you’re confident about your investment, this shouldn’t concern you.

    c. MIS investments come with fees

    Investment fees (such as sales charges, management fee and trustee fee) might eat up your investment returns. You must ensure that your investment returns (after deducting fees) will still be on par with EPF dividends at the very least.

    4. How much can you invest under MIS?

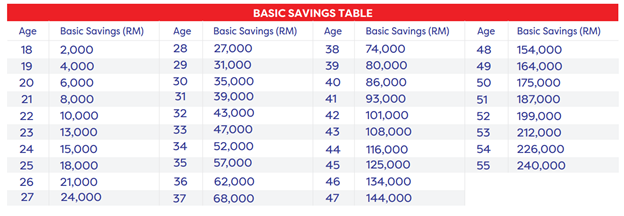
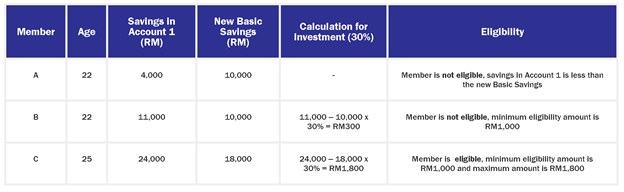
    You may invest up to 30% of savings in excess of basic savings in account 1 with EPF. You may continue investing via MIS every three months as long as your balance in account 1 exceeds your required basic savings and fulfills all EPF requirements. To confirm your eligible investment amount for MIS, you may check it under the i-akaun website. Go to i-akaun website →  withdrawal tab →  withdrawal eligibility → member investment scheme. The number that appears next to the member investment scheme is the amount eligible to invest via MIS. Alternatively, you can also do a self-calculation of how much you can invest under MIS. The formula is as below: (EPF account 1 value – required basic saving in account 1 based on your age) x 30%
    basic savings table - epf member investment scheme
    Basic Saving Table from EPF website (as of 26 May 2021) The minimum savings benchmark set by the EPF will be updated from time to time. You may check out the latest minimum savings required on the EPF website.
    simple epf calculations - epf member investment scheme
    Sample calculation from EPF website (as of 26 May 2021)

    5. Your investment options under MIS

    You may invest via EPF in approved Unit Trust Management Companies and Asset Management Companies under MIS. epf member investment scheme mis

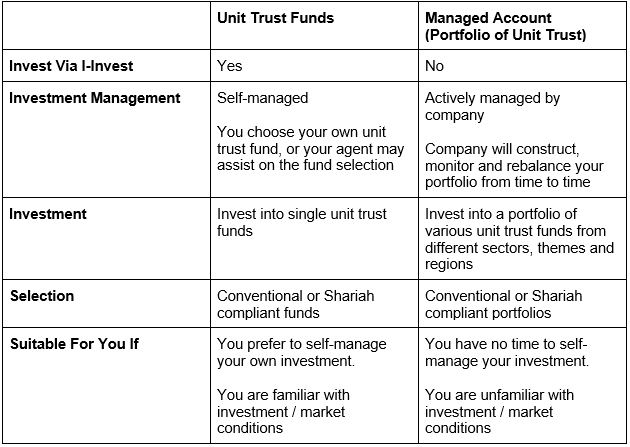
    Difference between investing into unit trust funds compared to managed account (portfolio of unit trust)

    difference in investing in unit trust fund and managed accounts - epf member investment scheme In summary, any investment that you may choose to do via MIS comes with pros and cons. Do research and understand all the risks that you’re taking before proceeding with investing. If you have further enquiries on EPF investment via MIS, I suggest that you seek out a financial professional to discuss and design an investment plan that matches both your risk profile and investment objectives.
    About the author

    Kuah Soo Yee is a Licensed Financial Planner (CFP) who is passionate about helping people make sound financial decisions and achieve their financial goals, and recently launched her own app. Her personalised strategies and advice have helped many to gain better clarity and take firm control of their financial future. She can be contacted at soo.yee@ipp.com.my Website LinkedIn Facebook Instagram  
  • What is Financial Wellness – It’s Not Just About The Money

    What is Financial Wellness – It’s Not Just About The Money

    Taking personal finance to another level by looking at it from a more holistic view.  How has the past year been for you? I’ve done a lot of reflection on myself and how I want to further evolve when things get a little more normal for the coming year (fingers crossed)! One thing I personally learned is about life and recognising that money is just a tool. We must make sure we use it correctly in order to work towards financial wellness.
    “People first, then money, then things.” – Suze Orman

    Reflection on the path to financial wellness

    The stoic path to wealth mentions that the fear of losing all our wealth is creating a monster inside us and therefore turning the chase for wealth into fear of losing it. This eventually turns money into our master and we’re enslaved by fear until we almost lose touch with ourselves. There is a saying “Money is the root of all evil”. But in actual fact, the full quote is “the love of money is the root of all evil.” It’s the greed for wealth that is bad as it can corrupt minds, and the need to keep accumulating more and more is the real issue.

    Money is not the end goal

    Personal finance is not about the money we have or about creating more wealth. Its main purpose should be more holistic, ie. leading the life you were born to lead, no matter what your financial status is. You’ll see money in a different light if you began your career with a student loan. Even before starting your career, you’ve already created a load of fear by accumulating a large amount of debt. This results in your mind becoming clouded with thoughts of the repayment of loans first and pushing aside all other goals or dreams. I personally experienced it as a child; teachers kept telling me to finish school, get good grades, go to university, get a degree and get a good paying job. As a child I thought that was the dream, but it didn’t turn out the way I imagined it would as a child. We were repeatedly told this fairytale, and subconsciously I believed it. But now that’s not the case. How can we take a holistic approach around our personal finances and take back control of our life? Believe me, we’re not meant to suffer through life constantly worrying about paying bills.

    Reflecting on your childhood dreams 

    Have a goal in mind. You already knew what you wanted when you were a child. In fact, there’s a good chance you were so good at it. Try asking your parents or other close family members what you were like when you were around the age of 9 to 12. It’ll give you some insights about your strengths and your childhood dreams. I grew up observing how passionate my parents were and how they were willing to give their all to their career. At the end of the day, my parents still had time to spend with us and go on a little vacation once in a while. It was a nice balance. That’s currently what I want to strive for – a balanced life between my career and family. I’m not saying I don’t want to be rich (who doesn’t), but it’s not my main focus right now. Between juggling two young kids, my husband works long hours because he enjoys the work he does. Even though in my opinion, he deserves to be paid better, it matters less. There’s been a string of financial decisions we made that may be a sin in the personal finance community focused on accumulating wealth. But we needed to make those decisions to get to where we need to be in life. Our goals were bigger than wealth accumulation.

    Using my finances to find peace 

    We can never be free. I believe there’s no such thing as financial freedom. This is because I realised just when I thought we were “free”, something would suddenly hit us like a bomb and I would think “Here we go scrambling again”. Getting married is expensive. Staying married is expensive. Having kids is expensive. I remind myself of my battles daily. If my needs are covered, I am willing to forgo some of my wants. How precious and priceless is the laughter of a child?

    Just do you 

    It‘s terribly hard to maintain a balance and I personally struggle with this on a regular basis. Turning off the work switch and being present was a difficult process. Being frugal and being disciplined in managing our budgets has a big impact on our long term finances. But this just makes me exhausted. There’s no point stressing about maximising my savings or the future so much that I forget to be present. The goal is not the money – it’s my life. I’m not going to kill myself just to keep striving towards this illusion that my future will be far brighter if I continue maximising my savings and investments. I choose to enjoy every step of the journey instead, without mentally burdening myself. Use your wealth-building experience to create happiness for yourself and inspire others to do the same. Remember it’s not about the numbers and figures in your portfolios, but what you do with the money.
    “Wealth consists not in having great possessions but in having few wants.” – Epictetus 
    Move from survival mode to thriving mode. Choose not to be trapped in the illusion of not having enough. You’re enough! If you’re in survival mode, you’ll trap yourself in the rat race. Therefore, there’s no room for helping others and all you’ll think about is how to make yourself better instead of the community around you.

    About the author

    Nurul Yahi has a background in Business Administration majoring in Islamic Financial Planning. She’s a financial enthusiast and you can find her at dearduit.com. You can also find Nurul on Twitter, Instagram and Facebook.
  • Should You Invest Your i-Sinar EPF Account 1 Withdrawal?

    Should You Invest Your i-Sinar EPF Account 1 Withdrawal?

    Back in December 2019, the Covid-19 outbreak was triggered in Wuhan, a city located in the Hubei province of China.

    The virus continued to spread and eventually escalated into a global pandemic which devastated every single corner of the world, causing radical changes in the way we live as well as social, economic, technological, and political policies.

    Amidst the economic doldrum in China, there have been interruptions in exports and imports, while global supply chains have been disrupted significantly.

    With a strongly connected and integrated worldwide trading relationship, the contraction in the global supply chain led to a big drop in global economic activities.

    Furthermore, governments around the world have been forced to implement harsh restrictions on human activity to curb the spread of the virus.

    These travel restrictions further burdened the financial markets and led to dramatic falls in global economies.

    It’s been a similar situation in Malaysia, with the implementation of various Movement Control Orders (MCO) costing millions of people their jobs across varied industries, leaving many Malaysians suffering from salary reduction, furlough, or unemployment and retrenchment.

    This impact has become apparent since the outbreak and many of them have turned to alternative jobs like driving Grab cars, venturing into the food and beverage industry, online vocations, or direct selling to make ends meet.

    In December 2020, the Employees Provident Fund (EPF) launched a new scheme which allowed members to prematurely withdraw their EPF savings in order to aid their cash flow during the difficult economic times posed by the Covid-19 pandemic.

    What are i-Sinar withdrawals?

    The EPF i-Sinar initiative enables EPF members to make a partial withdrawal from their savings in EPF Account 1.

    This initiative was launched by the EPF for the purpose of easing the financial burden of members who’ve been affected by the Covid-19 pandemic, helping them sustain their livelihood. The withdrawal amount will vary, depending on each member’s needs and of course their available balance.

    Unfortunately, Malaysians are taking advantage of this opportunity to maximise their withdrawals and spending it on non-necessities.

    In fact, without realising it, they’re withdrawing and spending their retirement savings nested in the provident fund!

    According to a survey conducted by UCSI, among 809 people in Malaysia who have withdrawn from or planned to participate in the i-Sinar scheme, 47.2% of the respondents realised that the withdrawal will affect their retirement funds, 22.6% of the respondents were uncertain, while the remaining 30.2% of respondents didn’t realise the huge impact it would have on their retirement funds!

    Returning to fundamentals, EPF serves as a social security organisation that primarily provides retirement benefits for the private sector and pensionable employees in Malaysia. Since 1951, it has proven to be a responsible and efficient custodian of its members’ retirement savings.

    With the introduction of i-Sinar, this can potentially lead to a significant reduction in our retirement savings. The reason for this is that it leads to fewer dividends earned, missing out on the compounding interest in future.

    If our savings are insufficient to sustain our retirement years, we may be compelled to delay our retirement further and continue to work, or may even be forced to downgrade our retirement lifestyle to one that is humbler or minimalist.

    For individuals who’ve withdrawn their i-Sinar, what else they can do to manage the money beside spending it?

    Well, upon fulfilling current needs, you’re highly encouraged to utilise the balance for better purposes such as investing. This is one of the instruments that’s able to grow our wealth through capital gain and appreciation in the value of an asset over time.

    As with any savings fund, the benefit of putting money in EPF is the dividends and the compounding interest that you could accumulate over the years.

    However, many EPF members have also opted to withdraw their i-Sinar and invest it into different investment vehicles which could offer potentially higher returns compared to EPF dividends.

    Let’s use an example to illustrate this: Ms. Maria, aged 35 has withdrawn RM10,000 via the i-Sinar withdrawal facility and invested this into an investment vehicle that has the potential to generate 15% returns annually.

      EPF DIVIDEND ALTERNATIVE INVESTMENTS
    PRINCIPAL RM10,000 RM10,000
    ESTIMATED ANNUAL RETURN 5% 15%
    AGE 40 12,763 20,114
    AGE 45 16,289 40,456
    AGE 50 20,789 81,371
    AGE 55 26,533 163,666
    AGE 60 33,864 329,190

    The table above explains how her i-Sinar withdrawal may grow from RM10,000 in the subsequent 25 years to RM329,190 thanks to higher returns and compound interest. If she doesn’t withdraw her i-Sinar and let it nest in EPF, she will only receive RM33,864 in the 25th year!

    According to the aforementioned survey conducted by the UCSI Poll Research Centre, it shows that almost half (47.7%) of T20 income group earners who were polled said they used or would use their i-Sinar withdrawal for investment purposes.

    Although the hardship faced during Covid-19 pandemic didn’t affect the T20 respondents as much as the others, they still saw this as an opportunity to invest and plan better for their retirement funds!

    In a nutshell, the i-Sinar withdrawal is a good initiative to ease the financial burden of Malaysians who have been affected by the Covid-19 pandemic, helping them sustain their livelihood.

    Despite part of the population not being affected much by the pandemic, they still continue to think about withdrawing their i-Sinar for investment purposes so that it can potentially generate better returns for their retirement funds. So instead of spending it on unnecessary items, invest it if possible!

    Click here to learn more about i-Sinar.

    About the author

    Edmond Tang Zhen Han is a certified financial planner that is passionate about helping people achieve financial literacy in order for them to reach financial freedom. He can be contacted at edmondtangzh@genexus.com.my