Category: business

  • Hong Leong Investment Bank Enhances Digital Capabilities with Online Onboarding for its Shariah Trading Account

    Hong Leong Investment Bank Enhances Digital Capabilities with Online Onboarding for its Shariah Trading Account

    KUALA LUMPUR, 15 OCTOBER 2024 – Customers can now enjoy a fully online
    onboarding experience when applying for Hong Leong Investment Bank (“HLIB” or the
    “Bank”) accounts and products, including for the Shariah Trading Account which allows
    customers to access, buy, and trade stocks which are Shariah-compliant.

    This is in line with the Bank’s commitment to making investments more accessible and
    convenient for customers. By enhancing its digital investment platforms and optimizing its
    onboarding processes, HLIB is taking another step forward to ensure that our investors can
    start and grow their investment portfolios with ease from anywhere, at any time.

    The Shariah Trading Account is designed to cater to the growing demand for Shariah-
    compliant investment solutions. The comprehensive trading account enables investors to
    trade in a wide range of Shariah-compliant securities on the Bank’s digital trading platforms,
    including HLeBroking and HLeBroking Mobile, and is equipped with Shariah indicators for
    Shariah-compliant stocks.

    Lee Jim Leng, Group Managing Director of HLIB, commented, At HLIB, we are
    committed to providing our customers with an end-to-end investment experience which
    provides widespread access to a variety of investment options. Ensuring a fully digital
    onboarding experience, especially for our Shariah Trading Account, is a testament to our
    ongoing efforts to enhance our digital capabilities and build solutions around the needs of
    our customers. We believe that this will provide our customers with greater convenience and
    accessibility, allowing investors to start and grow their Shariah or conventional portfolios
    from anywhere, at any time.”

    In line with the Bank enhancing its digital investment offerings for customers, HLIB has also
    announced the launch of HLeBroking Flexi Trade. Flexi Trade offers customers additional
    trading limits based on cash or shares on hand, while enabling customers to enjoy attractive
    brokerage rates of as low as 0.08% when trading with cash upfront. For trading limits in
    excess of cash upfront, customers can also enjoy brokerage fees of 0.18% for contracts
    worth RM100,000 and above, and 0.38% for contracts below RM100,000.

    This flexible trading feature provides other exciting benefits, including a limit that is double
    the cash pledged and up to three times the share value pledged as collateral. It also offers
    customers immediate trade confirmation and online settlement, while providing
    complimentary access to HLIB’s industry-leading trading tools and market research.

    Online onboarding for the Shariah Trading Account and HLeBroking Flexi Trade are now
    available to all HLIB customers.

  • Driving Fair Wages: Finance Professionals Urged to Address Inequality for a Sustainable Future

    Driving Fair Wages: Finance Professionals Urged to Address Inequality for a Sustainable Future

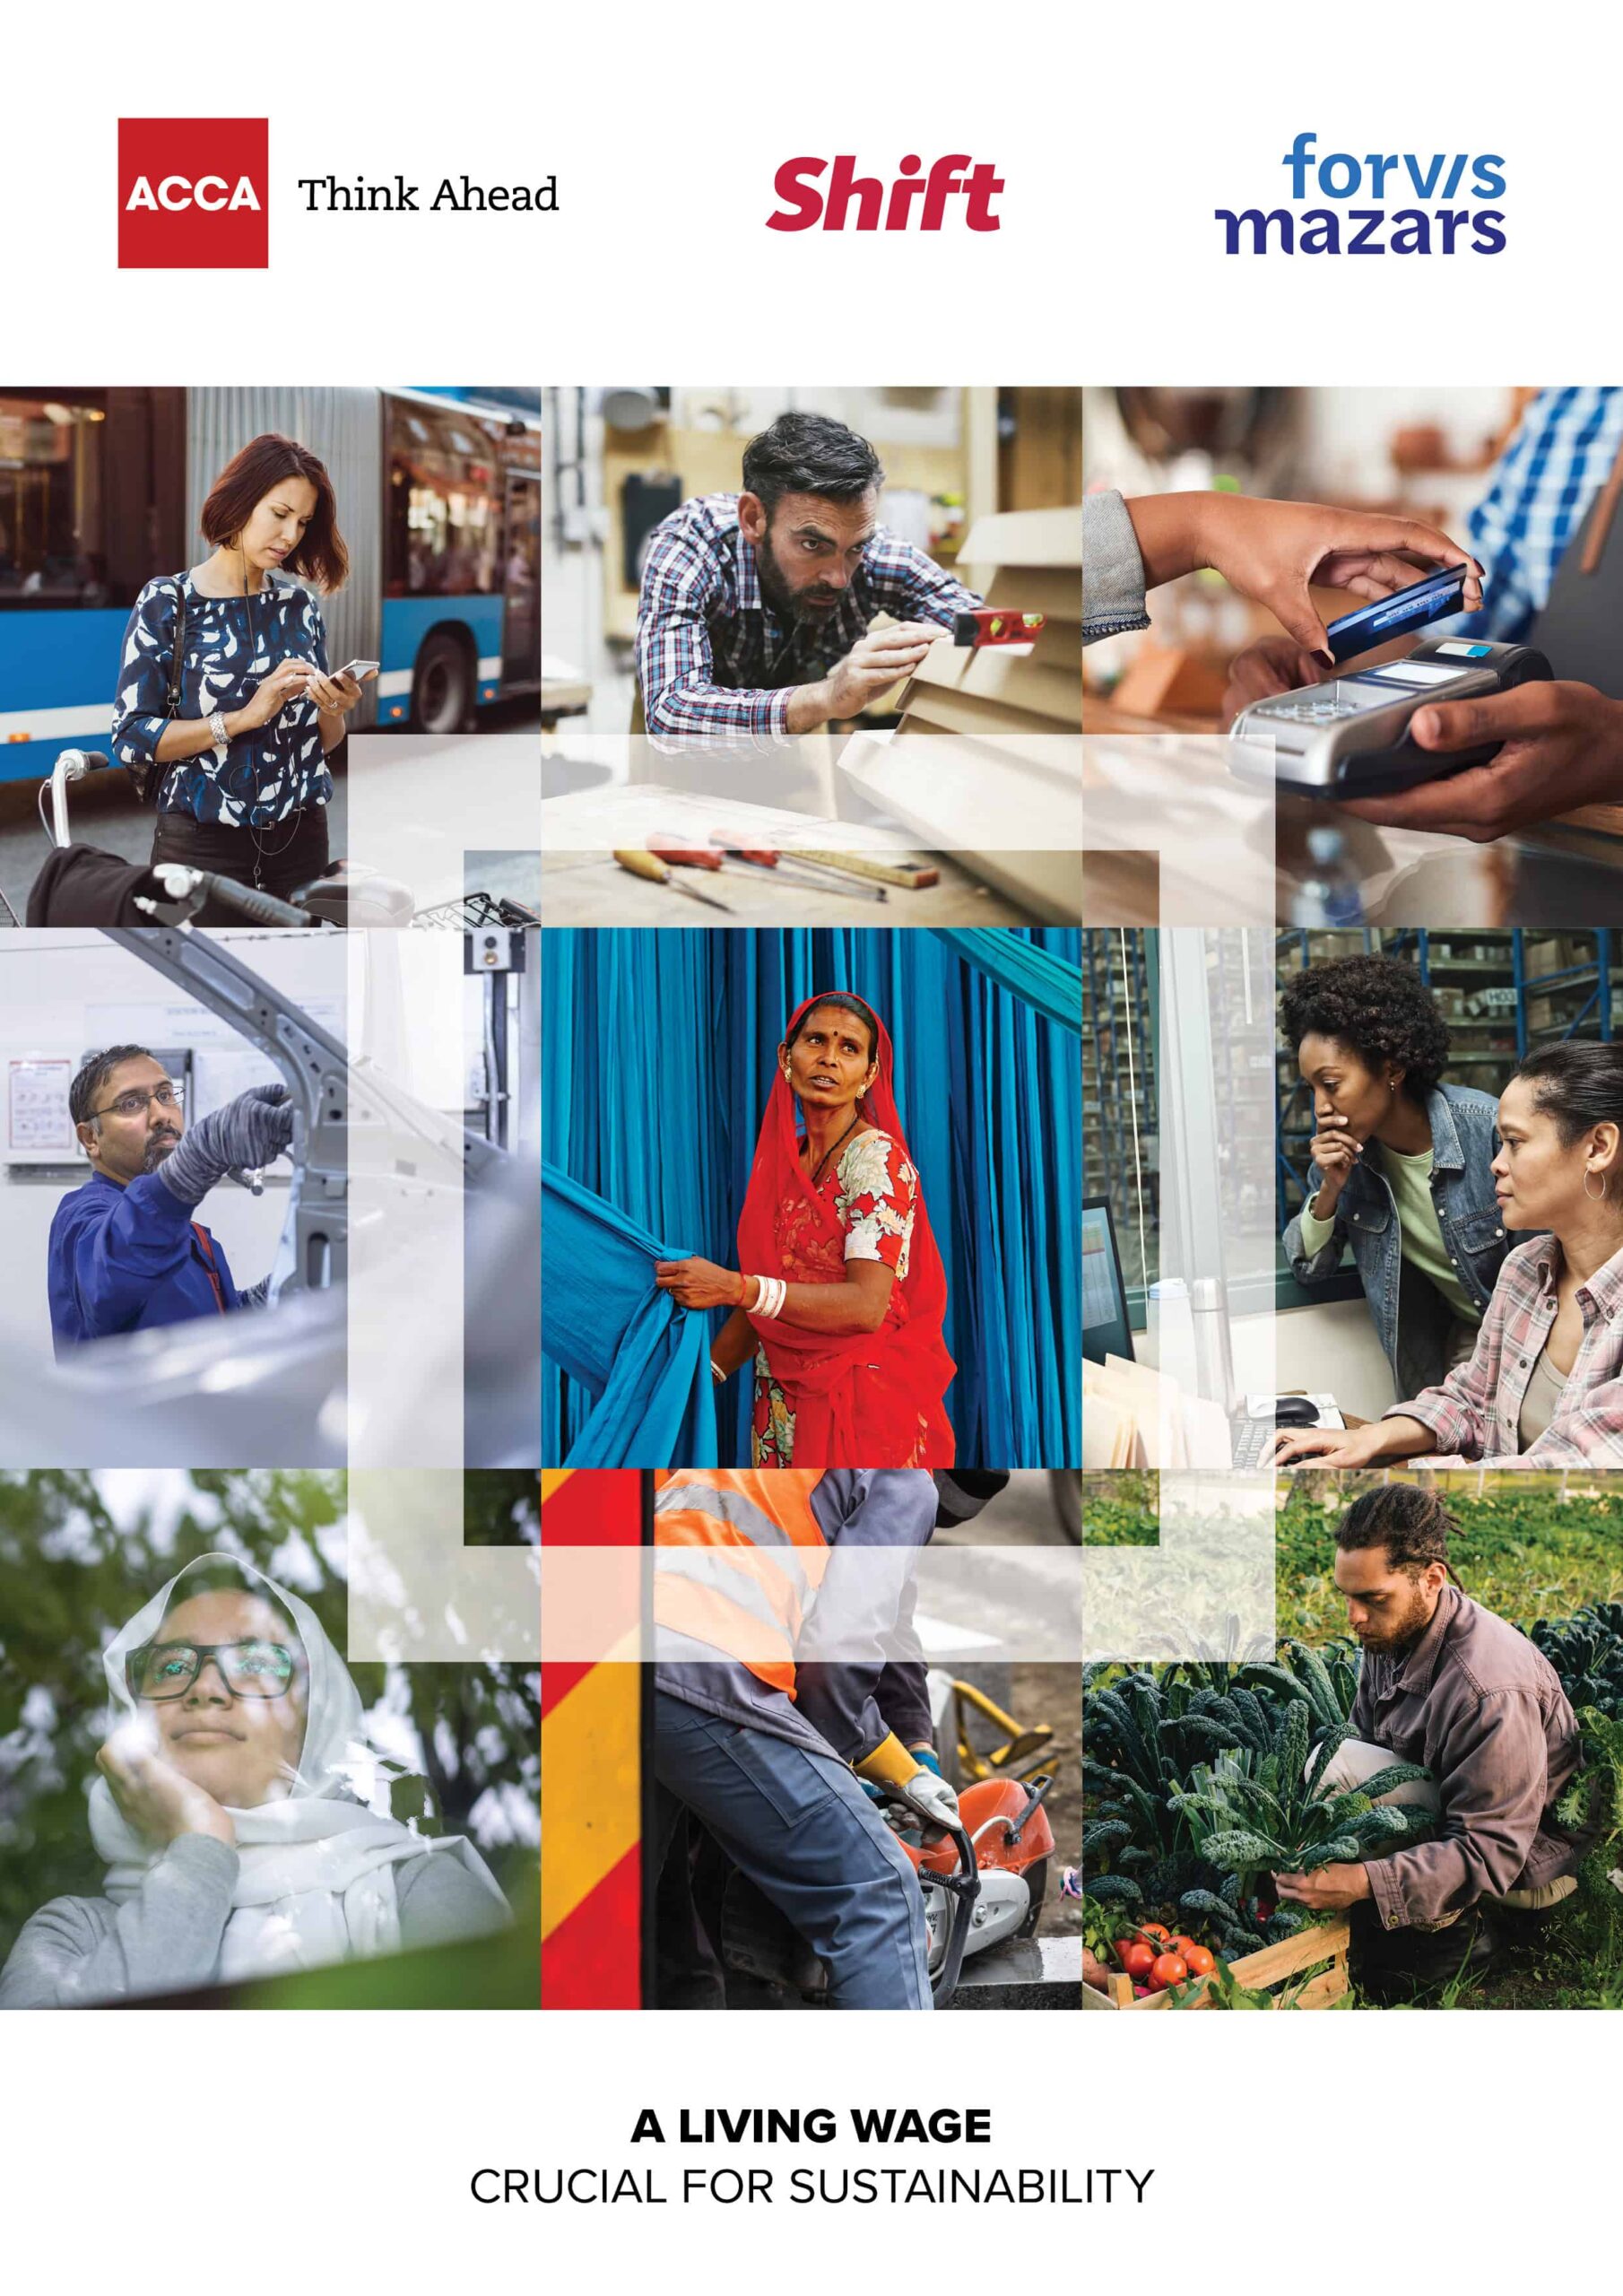
    KUALA LUMPUR, 1 October 2024: A new report highlights the need for finance professionals to champion  living wages as a key factor in reducing inequality, advancing human rights, and promoting sustainability.  Produced by ACCA, Shift, and Forvis Mazars, the report also reinforces findings that paying a living wage  not only boosts productivity and reduces staff turnover but also enhances economic stability. 

    The report, ‘A living wage – Crucial for sustainability’, urges finance and accountancy professionals to  address wage inequality and play a pivotal role in driving sustainable business practices. It stresses that  without prompt intervention, wage disparities will continue to undermine economic and social systems  globally, including in the Asia-Pacific (APAC) region. 

    Using the insights from over 1,000 survey respondents across 93 countries and discussions with more  than 50 finance and business professionals, the report provides compelling evidence for the socio economic multiplier effect of living wages. It finds that paying a living wage benefits not only workers but  also employers, economies, and governments.  

    Paying workers below a living wage is inconsistent with preserving and enhancing the value of human  capital. Business and investor initiatives involving leaders from across all regions are increasingly  highlighting the importance of paying living wages to reduce inequalities and the related risks to societies,  economies and financial systems. Yet only 33% of Malaysia-based respondents felt that it was a  responsibility which extended to their first-tier suppliers and even less beyond this. 

    The report highlights the undeniable link between living wages and sustainability, with 87% of Malaysia based survey respondents recognising this connection. Living wages reduce inequality, boost economic  stability, enhance business resilience, support human rights, strengthen supply chains, and meet growing  regulatory and investor demands for socially responsible practices. 

    Helen Brand OBE, Chief Executive of ACCA, stated: “Accountancy and finance professionals are held  to the highest ethical standards. The right of all employees and contractors to a living wage is an ethical  responsibility and as a result finance professionals have a unique role and opportunity to drive it as a core  part of their sustainability activities.” 

    Caroline Rees, President and Co-founder of Shift, emphasised: “A living wage is a fundamental human  right. Organisations’ responsibility under international standards to respect human rights means paying  workers in their own organisation adequately, and using their purchasing practices and business  relationships to advance living wages also for workers in their value chains. Change doesn’t happen  overnight, but chief financial officers can and should drive demonstrable progress on this crucial issue.” 

    Richard Karmel, Managing Partner – London, Forvis Mazars, added: “Organisations face significant  transitions as their business models seek to become more sustainable. The inability to pay a living wage  throughout a value chain, including in one’s own organisation, can only bring into question whether that  business model is sustainable. Now is the time to critically appraise the viability of these business models  and to make tough choices with a human capital focus.”

    A Malaysian Perspective 

    In Malaysia, addressing wage disparities is particularly critical, given the country’s commitment to reducing  inequality as envisioned in the Ekonomi Madani framework, which aims to elevate the dignity and status of  the nation with two main focuses: restructuring the economy to make Malaysia a leader in Asian economies  to ensure that the enlarged wealth is benefitted equitably by the Rakyat. By advocating for living wages,  finance professionals in Malaysia can help align business practices with national development goals. 

    The report urges finance professionals across to elevate living wages to board-level discussions, integrate  them into sustainability strategies, and lead by example in their value chains, starting with Tier 1 suppliers. Regulatory frameworks like the European Sustainability Reporting Standards (ESRS) and the Corporate  Sustainability Due Diligence Directive (CSDDD) are increasingly emphasising living wages. Finance  professionals in the APAC region, including Malaysia, must prepare to meet these growing demands for  socially responsible practices, ensuring their organisations are well-positioned for future regulatory  requirements. 

    Full report can be read online here: https://stories.accaglobal.com/living-wage/index.html

  • Smart Tax Planning for Financial Success

    Smart Tax Planning for Financial Success

    By Annie Wong


    Starting 2 January 2022, even zero-income full-time students in Malaysia are required to file their tax returns with the Inland Revenue Board of Malaysia (IRBM). The question arises: How many of us are still unaware of these changes?


    In the ever-evolving economic landscape, staying informed about recent changes that impact our financial lives is crucial. Within this dynamic field of taxation, subject to constant change, it is essential to equip ourselves with effective tax planning strategies.


    Despite being Malaysian citizens, not everyone is aware of their tax obligations. For instance, according to Act 8331, Finance Act 2021, a new section 66A (1)(c) mandates that any citizen aged eighteen and above must have a Tax Identification Number (TIN).


    As of 1 January 2022, even if Malaysians are 18 years old with no income, they are required to report ‘0’ in their BE form. While 7.8 million TINs were automatically generated for eligible citizens, many still believe that being a full-time student with no income exempts them from filing tax returns.


    During the Tax Forum 2023, Abang Ehsan Abang Abu Bakar from the Tax Compliance Department of LHDN suggested that eligible citizens, especially new taxpayers, should complete their tax return filing before 31 May 2024. The IRBM has introduced a Special Voluntary Disclosure Programme 2.0 from 6 June 2023 to 3 May 2024, allowing new taxpayers to file tax returns for YA 2022 and earlier without penalties.


    Consider a working adult earning less than RM30,000. Should they fill out a tax filing? Yes, they should. While it wasn’t necessary previously due to their chargeable income being non-taxable, the amendment, effective 1 January 2022 mandates all citizens aged 18 and older to report and submit their tax filings.


    Why does a full-time student with no income need to report now? IRBM cannot distinguish between zero earnings and substantial income unless it is reported. According to an EY report in November 20222, Malaysia’s shadow economy accounted for 18% of GDP in 2019, approximately RM250 billion. The shadow economy comprises underreported business income, non-registered businesses and illicit activities. Deputy Finance Minister Ahmad Maslan mentioned in an interview on 17 October 2023, that TIN and e-invoicing are expected to shrink Malaysia’s shadow economy. Now we understand; it is part of the government’s strategy to tackle the shadow economy!


    Strategic Tax-Saving Tips

    To legally save on taxes, engaging in proper tax planning at the beginning of the year is essential. One key strategy involves maximising deductions through available tax relief, charitable contributions and tax-exempt investments. Here are some tips categorised into four groups:


    General Tax Relief: According to the Budget 2024 proposal, several beneficial tax reliefs have been added. For instance, expenses incurred for dental and medical check-ups for yourself, your spouse, parents and children are claimable up to RM1,000. Participating in up-skilling courses and retaining the receipt from the organiser can result in a claim of up to RM2,500. Contributions to the Private Retirement Scheme (PRS) offer tax relief up to RM3,000 until YA 2025.


    Additionally, optimising the use of tax-advantaged accounts, such as the Employees Provident Fund (EPF), is crucial. The voluntary contribution initiative of EPF, i-Saraan3, allows self-employed members and gig economy employees to contribute up to RM100,000 per annum, with a special incentive of 15% for the total contribution, up to a maximum of RM500 for the current year. Combining approved scheme contribution relief and voluntary contribution/life insurance relief can result in a maximum tax relief of RM7,000.


    Employee Perquisites: Employees working for a business entity can negotiate a better remuneration package with allowances, benefits-in-kind and perquisites. For example, Joshua, a general manager with over 15 years of experience in a pharmaceutical company, proposed to his boss a daily meal allowance and a travel allowance of RM6,000 per annum, respectively. All these allowances are tax-exempted perquisites, and Joshua doesn’t need to pay a single cent in tax for these benefits. Additionally, Joshua requested a company car.


    Let’s assume the company provides him with a car valued at RM180,0004; his additional taxable income is only RM8,800. After deducting all personal tax reliefs, if Joshua’s tax bracket is 25%, he only needs to pay RM2,200 (RM 8,800 x 25%) per year to enjoy a luxury car with a driver every day. A long-service award is given by the company, and the first RM2,000 is tax-exempted as well. So, if you are a long-service employee, why not consider requesting a substantial award from the company?


    Benefits for Married Employees: Employees who are married with children can explore opportunities for additional benefits. Children’s allowance perquisites were raised from RM2,400 to RM3,000 during the Budget 2024 proposal. Parents with children under 6 years old can claim up to RM3,000 per household by sending them to a JKM-registered kindergarten. Saving RM8,000 into Skim Simpanan Pendidikan Nasional (SSPN) is eligible for each parent until YA 2024.


    Business Owners (LLP or Sdn Bhd): Business owners, particularly those in the Small and Medium Enterprise category, can strategically repackage remuneration to maximise tax savings. Declaring dividends instead of drawing a high salary package or director fees can be a tax-efficient move, especially to keep the total annual chargeable income below RM 100,000 and benefit from lower tax brackets ranging from 15% to 24%.


    These are some practical tips for optimising individual tax returns in 2024. Additionally, starting on 1 August 2024, the government will implement e-invoicing for companies with revenue exceeding RM100 million. This change is set to be a game-changer in the tax landscape. Moreover, it will become mandatory for all taxpayers, including SMEs, from 1 July 2025.


    To learn more strategies for optimising tax returns, minimising liabilities and strategically timing financial transactions, proper tax planning is required. By understanding the taxation framework, one can take control of their financial destiny by making informed choices that align with their long-term goals. May this year be a great and prosperous one for most of us!


    About the Writer


    Annie Wong is a dedicated and accomplished trainer with over a decade of experience in training and SME business consulting. She holds a Bachelor of Science degree from Campbell University, graduating with Summa cum laude honours. Presently, Annie is globally recognised as a Certified Financial Planner (CFP CERT TM Professional) and a Certified Professional Trainer (CPT, IPMA, UK). She is licenced as a CMSRL Financial Planner by the Securities Commission Malaysia, and her expertise has positively impacted numerous individuals and businesses.


    Sources

    (1) Act 833, Financial Act 2021.

    (2) Shadow Economy: www.freemalaysiatoday.com/category/highlight/2023/10/17/governments-grand-plan-to-tackle-shadow-economyClick here to enter text.

    (3) i-saraan: www.kwsp.gov.my/en/member/contribution/i-saraan

    (4) Benefits-in-kind: http://lampiran1.hasil.gov.my/pdf/pdfam/PR_11_2019.pdf
  • Understanding Your Relationship with Money for Better Financial Health

    Understanding Your Relationship with Money for Better Financial Health

    By Kevin Neoh

    Have you ever wondered if money were a person? What kind of relationship would you have with this ‘person’? Will this be a person who gives you a lot of stress each time you think about them or one with whom you enjoy having a quality and mutually beneficial relationship?

    Why Your Relationship with Money Matters

    Like many other things, such as our car, house or devices, money is also a tool that we use to help us accomplish specific goals or meet various needs. Other than being a tool we use to buy things, it is also a reflection of your values, beliefs and emotions. How you think and feel about money can affect your financial health, your happiness, and your wellbeing. That is why it is important to have a good relationship with money, one that is based on awareness, understanding and empowerment.

    How Your Beliefs Shape Your Behaviour

    “We begin learning about money indirectly from a young age, observing how adults handle or act around money, starting as young as three years old.”

    Our relationship with money is influenced by our beliefs, which are formed through our past experiences, culture, family and personality. We begin learning about money indirectly from a young age, observing how adults handle or act around money, starting as young as three years old.

    Our beliefs can be supportive or non-supportive, conscious or unconscious, rational or irrational. The truth is that they can either help us or hinder us from achieving our goals.

    For example, if you grow up in a family where money is often a scarce resource, you might develop a focus on saving money and have difficulty spending, even though, as an adult, your situation allows you to live comfortably. Likewise, another person who had a similar childhood might grow up believing that there will always be insufficient money and one should spend while it’s there, or that because one is deprived of many things growing up, one should enjoy them whenever they can. Similar experiences may have produced an opposite belief and thus, different behaviours around money.

    This is why our beliefs about money can shape our financial health. For instance, if a person grew up constantly believing that money is bad, that it causes pain, and that it leads to arguments in the family rooted in money issues, this person may feel uneasy having money and thus will find ways to spend it without consciously wanting to. As a result, this person will hardly have savings, may have debts and may be unable to plan their future with confidence.

    As another example, a person who witnessed their loved ones lose most of their wealth due to a stock market crisis might grow up thinking that investing in the stock market is too risky, to the point that one might lose everything. Hence, this person might stay away from investing in the stock market without consciously realising why.

    It is worth noting that there are no right or wrong beliefs; they are all part of us. Our beliefs are what help keep us comfortable and safe. However, as our circumstances, economy and way of life change, certain things that used to be true or worked in the past may no longer be the same. Therefore, it is sometimes worthwhile for us to examine our beliefs and discuss them with someone who can be impartial.

    How to Examine and Change Your Beliefs

    The first step in improving our relationship with money is becoming aware of our beliefs and understanding how they influence our behaviours. This awareness can be achieved by paying attention to our thoughts, feelings and actions when dealing with money.

    You can also ask yourself questions, such as:
    • What did I learn about money from my parents, friends or society?
    • What are the benefits and drawbacks of my beliefs?
    • How do they align with my values and goals? In what ways may they limit me?

    The second step is to challenge and change your beliefs if they are limiting or harmful. This can be done by seeking evidence that contradicts your beliefs, finding alternative explanations or adopting new perspectives. Additionally, you can use affirmations, visualisation or meditation to reinforce positive beliefs.

    Relationship with Money & Financial Health

    When we have a better relationship with money, we can make more informed financial decisions, placing us in a position to thrive and flourish. This involves being able to cope with financial stress and work towards achieving our financial goals.

    As we strive to improve our financial health, it’s essential to be mindful that what society or conventional thought considers financially healthy may not be an ideal benchmark.

    Having a substantial amount of money in the bank or earning a high income does not necessarily equate to good financial health. For instance, a person with a high income, lacking an understanding of their money beliefs, and harbouring a non-supportive relationship with money may struggle to retain their income, ending up with significant debts.

    Similarly, someone with a high net worth due to reluctance to spend may miss opportunities to leverage their wealth for an ideal and fulfilling life.

    TL; DR

    If you feel that this article is not something you expected, that’s because it isn’t. In fact, the message I am trying to convey to the reader here is that instead of focusing on growing our wealth, finding the next-best-investment or buying the latest financial product, our focus should shift from a product-oriented to a human-oriented approach. We should give considerable thought to nurturing good financial health.

    Traditional financial advice or practices like budgeting, paying yourself first, investing regularly and spending within your means can help nurture our financial health. We may also benefit from seeking financial education and advice whenever needed. However, if we have not spent some time understanding the relationship we have with money and the beliefs that drive this relationship, all the hard work and efforts we put in might not matter much for our wellbeing in the long run.

    Remember, money is not an end but a means to an end. Money is a tool to serve your needs, not the other way around. Therefore, this is why it makes sense for us to begin by asking, “What kind of relationship do we have here?”

    ABOUT THE WRITER

    Kevin is the Head of Financial Planning at VKA Wealth Planners. As a Certified Financial Planner (CFP) and Certified Financial Coach (CeFC), Kevin works with clients to transform their relationship with money, empowering them to take charge of their lives and live the best life they desire. Kevin can be reached at kevinneoh@vka.com.my.

  • Steering The Malaysia’s ESG Landscape

    As we step into 2024, let’s explore the evolving world of investing, where the buzz around ESG (Environmental, Social, and Governance) principles is gaining momentum. Malaysia is at the forefront, setting ambitious goals for carbon neutrality by 2050. Join us on a journey to discover practical tips for everyday investors to align their portfolios with responsible spending.

    MALAYSIA’S ESG PROGRESS

    Malaysia’s commitment to ESG is evident through its ambitious plans. The nation’s focus on renewable energy, sustainable cities, and a green economy showcases dedication to environmental stewardship. Keep a keen eye on these trends as they can significantly influence your portfolio’s performance.

    GREEN ENERGY AND SUSTAINABLE CITIES

    Major companies in Malaysia are actively adopting green energy, with local giants opting for electricity from renewable sources. Initiatives like the Green Electricity Tariff and the Net Energy Metering Nova program demonstrate a robust commitment to sustainable practices. To support these efforts, Malaysia incentivizes electric vehicles, targets 31% renewable energy in its capacity mix by 2025, and aims for carbon neutrality by 2050. Investors should consider the potential growth of companies aligning with these green initiatives.

    SUSTAINABLE FINANCING

    Malaysia stands out globally in sustainable financing, issuing the world’s first sovereign US-denominated sustainability sukuk. With a focus on eligible social and environmentally friendly projects, the government plans to issue up to RM10 billion of sustainable sukuk in Budget 2022. This move creates unique investment opportunities for those looking to support socially responsible projects. The PwC report on “ESG Deals Creation and Impact Investing in Malaysia” emphasizes how companies listed in FTSE4Good Bursa Malaysia (F4GBM) Index, demonstrating strong ESG business practices, have been able to deliver higher valuation multiples and investment returns.

    CORPORATE ESG PERFORMANCE

    Public-listed companies in Malaysia are outperforming in ESG metrics compared to their ASEAN counterparts. Ranking second on the MSCI All Country Index ESG Leaders Index, Malaysia’s companies demonstrate a commitment to sustainable practices. The FTSE4Good Bursa Index and the FTSE4Good Bursa Malaysia Shariah Index provide valuable insights into companies leading in ESG and Shariah-compliant solutions. Investors can leverage these indices to make informed decisions aligned with their values.

    SECURITIES COMMISSION INITIATIVES

    The Securities Commission (SC) Malaysia is taking significant steps to foster sustainable practices. The introduction of the Leading for Impact Programme and the Principles-Based SRI Taxonomy public consultation paper in 2021 are clear indications of Malaysia’s commitment to advancing ESG principles. The SC’s focus on sustainability risk management, disclosures, and the development of the sustainability index showcases Malaysia’s advanced stage in policy and regulatory actions related to ESG.

    BUDGET 2024: SHAPING THE FUTURE OF ESG

    Budget 2024 is a game-changer for the ESG space in Malaysia. Sustainability is now integrated into economic policies, reflecting the government’s commitment to making Malaysia an investment destination while achieving carbon neutrality by 2050. The budget allocates RM2 billion for the National Energy Transition Roadmap (NETR) and a RM200 million startup fund for the New Industrial Master Plan (NIMP) 2030, reinforcing Malaysia’s dedication to a low-carbon economy. A RM900 million loan fund for SMEs to enhance business productivity through automation and digitalization demonstrates a focus on long-term sustainability through resource optimization and waste reduction. Guarantee funds of up to RM20 billion for SME entrepreneurs, especially in the green economy, technology, and halal fields, further boost investor confidence. Putrajaya’s transformation into Malaysia’s low-carbon city, utilizing solar panels and electric vehicles, sets a benchmark for sustainability, influencing ESG from an investment category to a mainstream strategy.

    EXPERT INSIGHTS ON BUDGET 2024

    Experts highlight Budget 2024’s emphasis on promoting domestic direct investments and attracting venture capital for high-innovation start-ups and green growth. The allocation of funds towards Malaysia’s National Energy Transition Facility (NETF) and encouraging financial institutions to provide up to RM200 billion in financing fosters a favourable environment for foreign climate investors. The focus on green investments is expected to stimulate both local and foreign investments in the renewable energy sector, propelling Malaysia towards a low[1]carbon economy. This aligns with global trends where investments in low-carbon energy technology reached a record level of USD1.1 trillion in 2022.

    ENSURING LONG-TERM SUSTAINABILITY

    Budget 2024 takes mid-term steps to encourage sustainable economic instruments through tax exemptions and deductions up to 2027. This includes tax deductions for companies participating in the voluntary carbon market and increased funding for Ecological Fiscal Transfer for Biodiversity Conservation (EPT). The emphasis on impact investing, supported by tax exemptions for social enterprises, aligns with Malaysia’s goal of becoming a prominent regional SRI hub. These measures aim to drive long-term ESG programs and initiatives.

    BALANCING IMMEDIATE NEEDS AND FUTURE SUSTAINABILITY

    While Budget 2024 focuses on promoting investments into conservation and the transition to a low-carbon economy, there are concerns about capacity enhancement needs and legal infrastructural gaps. Awareness needs to be raised among SMEs about the importance of sound ESG management. The budget lays the groundwork for economic instruments to facilitate Malaysia’s transition towards a low-carbon economy, but there is room for a broader focus on ESG factors to ensure long-term success.

    BLOOMBERG FIRESIDE CHAT – MALAYSIA’S ESG ACCELERATION

    In a recent Bloomberg fireside chat, Muhamad Umar Swift, Bursa Malaysia’s CEO, discussed how COVID-19 has spurred ESG adoption in Asia. Umar shared insights into Malaysia’s sustainability journey, highlighting Bursa Malaysia’s ESG initiation in 2010 with a vision to be ASEAN’s leading sustainable marketplace. ESG evolution in ASEAN focuses on education and Bursa Malaysia’s role in setting ESG transparency standards. Attracting global assets is a priority, aligning with local sustainability mandates and exploring avenues for sustainable investment. Regulatory influences, inspired by the E.U.’s Taxonomy, play a crucial role in attracting capital. Looking forward, public awareness is key to fostering a positive cycle. Bursa Malaysia actively encourages sustainable investment, aspiring to embed ESG values into the broader culture and society.

    GLOBAL COMPARISON

    Compared to ESG-focused budgets in neighbouring countries, Malaysia’s Budget 2024 takes commendable steps. However, lessons from Australia and Singapore highlight the importance of waste management, community education programs, and industry regulation for cohesive ESG practices.

    PRACTICAL TIPS FOR EVERYDAY INVESTORS

    Now, let’s translate these developments into practical tips for everyday investors: 1. Diversify with ESG Funds: Consider allocating a portion of your portfolio to ESG-focused funds. These funds invest in companies meeting high ESG standards. 2. Stay Informed: Regularly check ESG ratings of companies in your portfolio. Websites like FTSE Russell ESG ratings can be valuable resources for this information. 3. Explore Sustainable Sukuk: Keep an eye on opportunities in sustainable sukuk. These investments not only provide financial returns but also contribute to socially and environmentally responsible projects. 4. Engage in Sustainable Initiatives: Support companies actively involved in green initiatives. As consumers, your choices can influence corporate behaviour. 5. Long-Term Vision: Remember, ESG investing is a journey, not a destination. Companies embracing sustainable practices today may offer long-term value.

    LOOKING AHEAD

    As Malaysia advances in its ESG journey, there are exciting prospects for responsible investors. The upcoming trends in energy transition, food security, circular economy, and mobility transformation offer avenues for sustainable investments. Keep an eye on these developments to stay ahead in the evolving landscape of responsible investing. In conclusion, ESG is not just a financial trend; it’s a collective effort to create a better future. As you navigate the world of investments, consider the impact your choices can have on the environment, society, and corporate governance. Together, let’s shape a future where responsible spending is not just a choice but a way of life. Happy investing!

    (Sources: Bloomberg, The Star, PwC)

    This story is a contribution from Sajesh Kumar Paramasivam – Senior Partner at TorchBearer Consulting, a wealth management company that specializes in family wealth building through expert guidance.

  • Securing Your Legacy

    Wealth, often earned through generations of hard work and dedication, can be a double-edged sword when it comes to succession planning. The proverbial saying, “Wealth doesn’t pass through three generations,” underscores the challenges faced by families in preserving their financial legacy. In this article, we delve into the potential pitfalls and time bombs associated with wealth succession and explore viable solutions, with a spotlight on the Labuan Private Foundation – a powerful tool that has been successfully employed by business magnates since the 1980s.

    WEALTH DOESN’T PASS THROUGH THREE GENERATIONS

    The conventional wisdom that wealth typically follows a three-generation cycle adds a layer of complexity to succession planning. The first generation labours to build wealth, the second generation manages and holds it, and the third generation often faces challenges in preserving and growing the inherited fortune. Labuan Private Foundations provides a strategic means to break free from this cycle by establishing a robust structure that safeguards wealth for the long term.

    “By placing assets within the secure confines of a foundation, you create a financial firewall that safeguards the family’s wealth from external threats, ensuring the legacy endures.”

    FRAGMENTATION OF BUSINESS OWNERSHIP

    One common hurdle in wealth succession is the fragmentation of share ownership, particularly in businesses structured as Sendirian Berhad (Sdn Bhd). Passing down a family business can lead to conflicts among heirs, potentially jeopardizing the very foundation of the enterprise. Labuan Private Foundation offers a powerful solution by concentrating business ownership within a perpetual structure. This not only ensures continuity in ownership but also establishes a clear framework for decision-making, mitigating the risk of internal disputes.

    PROTECTION AGAINST CREDITORS AND BANKRUPTCY

    The looming threats of business creditors and bankruptcy claims pose significant risks to the sustained prosperity of a family’s wealth. Labuan Private Foundations may act as a shield, providing a protective layer against potential bankruptcy risks faced by descendants. By placing assets within the secure confines of a foundation, you create a financial firewall that safeguards the family’s wealth from external threats, ensuring the legacy endures.

    CONFLICTS OVER WEALTH DISTRIBUTION

    Wealth distribution can become a battleground, especially when children-in-law become stakeholders. Labuan Private Foundation can be instrumental in resolving such conflicts by offering a structured mechanism for wealth holding and distribution of residual income. With clearly defined rules and regulations, the foundation ensures that only those capable and responsible are entrusted with the management and growth of the family’s wealth, fostering a sense of fairness among heirs.

    TAX EFFICIENCY IN AN EVER-CHANGING LANDSCAPE

    Governments worldwide continually refine tax laws, introducing new challenges for business owners seeking to preserve their wealth. Labuan Private Foundation presents a proactive solution by optimizing tax liabilities. This strategic tool allows families to stay ahead of potential tax law changes, ensuring that the financial legacy remains intact and continues to grow. As governments explore avenues to claim a share of wealth through capital gains tax and other mechanisms, the Labuan Foundation becomes a vital ally in preserving your hard-earned assets.

    THE IKEA FOUNDER’S BLUEPRINT

    The success of the IKEA founder’s wealth-holding structure, established in the 1980s, serves as a useful example for business owners navigating the intricate landscape of succession planning. This family wealth planning strategy, rooted in the structure of a private family foundation, enables the IKEA legacy to endure and thrive across generations. By adopting a similar approach, you, too, can fortify your wealth kingdom and transform it into a legacy for your descendants.

    THE LABUAN PRIVATE FOUNDATION ADVANTAGE

    Labuan, a reputable offshore jurisdiction, provides a conducive environment for the establishment of private family foundations. These foundations offer a unique blend of flexibility, security, and tax efficiency, making them an ideal choice for proactive business owners focused on securing their financial legacy. Key advantages of Labuan Private Foundations include:

    Perpetual Existence: Labuan Private Foundations enjoy perpetual existence, ensuring that the wealth-holding structure remains intact across generations. This longevity is a crucial element in breaking the three-generation wealth cycle.

    Concentration of Control: By concentrating control within the foundation, business owners can ensure that only competent and trustworthy individuals manage the family’s business interests. This concentration minimizes the risk of mismanagement and internal conflicts.

    Creditor Protection: Labuan Private Foundation provides a robust shield against business creditors and potential bankruptcy risks faced by heirs. The separation of assets within the foundation acts as a protective barrier, preserving the family’s wealth.

    Transparent Succession Planning: Clear and transparent rules within the foundation’s structure facilitate smooth succession planning. This minimizes the likelihood of conflicts among heirs and promotes a sense of fairness in wealth distribution.

    Tax Efficiency: Labuan’s favourable tax environment, coupled with the other benefits afforded to private foundations, ensures that families can proactively manage and optimize their tax liabilities. This is especially crucial in the face of evolving tax laws.

    In the intricate realm of wealth succession, Labuan Private Foundation can be a powerful tool for business owners aiming to transform accumulated wealth into a legacy. By adopting a proactive approach and establishing a robust wealth-holding structure, akin to the successful blueprint employed by the IKEA founder, families can navigate the challenges associated with wealth transfer and ensure the preservation and growth of their financial legacy for generations to come. The Labuan Foundation, with its unique advantages, stands as a testament to the efficacy of strategic planning and foresight in securing the prosperity of your ‘wealth kingdom’.

    Lee Khee Chuan holds a B.A. from the National University of Singapore and is a Chartered Financial Consultant (ChFC), Chartered Life Underwriter (CLU), CFP professional, and Fellow of Life Management Institute (FLMI) USA. He is also a licensed financial adviser representative with more than 25 years of experience in estate planning. He shares a lot of valuable insights at: www.estateplanningmalaysia.com

  • Personal Finance In The Cyber Age

    In an era dominated by technology, the integration of digital solutions in personal finance has revolutionized the way we manage our money. While this digital transformation brings convenience and efficiency, it also raises significant concerns about the security of our financial data and investments. As we navigate the cyber age, it is essential to adopt proactive measures to protect our wealth from constantly evolving digital threats.

    THE GROWING CONCERNS OF CYBERSECURITY IN PERSONAL FINANCE

    Recent years, accelerated by the pandemic, have witnessed a surge in cyber threats targeting personal finance, ranging from identity theft to financial fraud. As we become increasingly reliant on mobile devices for financial transactions, cultivating essential habits for better mobile security is paramount. Regularly updating your mobile operating system, using strong and unique passwords, enabling biometric authentication, securing your internet connection, and being cautious of phishing attempts are crucial in fortifying your digital defences. Financial institutions, recognizing the gravity of the situation, have implemented advanced security measures to safeguard customer accounts. One notable measure is the increased adoption of Two-Factor Authentication (2FA), adding an extra layer of protection by requiring users to provide two forms of identification before accessing their accounts. This significantly reduces the risk of unauthorized access even if passwords are compromised.

    DIGITALLY SECURING YOUR FINANCES: A COMPREHENSIVE APPROACH

    In the digital age, relying solely on the security measures provided by financial institutions is not enough. Individuals must take personally proactive steps to digitally secure their finances. If you are in public accessing anything private, a secure Wi-Fi connection is critical in preventing unauthorized access. Regularly monitoring bank statements for unusual activities is another vital practice. Additionally, using reputable antivirus software helps create an additional layer of defence against malware and phishing attempts.

    Understanding the security protocols of your financial institution and platforms is also crucial. Investigate the encryption methods used, the strength of their authentication processes, and the transparency of their security practices. By doing so, you ensure the safety of your funds within the digital realm.

    LEARNING FROM PAST EXPERIENCES: SAFEGUARDING YOUR FINANCIAL HEALTH

    The financial landscape is constantly evolving, and learning from past experiences is essential to safeguarding your financial health. A case in point will be even banks can collapse, such as what happened with Silicon Valley Bank in 2023 from a bank run. One needs to regularly reassess your financial strategies, diversify your investments, and stay informed about market trends. All these are crucial aspects of maintaining a resilient financial stance.

    Diversification, spreading investments across different asset classes and geographic regions, is a key strategy to mitigate risk. While it does not eliminate the possibility of losses, diversification helps protect against the catastrophic impact of a single point of failure. Regularly reviewing and rebalancing your investment portfolio is crucial for adapting to changing market conditions and maintaining a resilient financial stance.

    A GUIDE TO PROTECTING YOURSELF FROM FINANCIAL FRAUD

    As financial transactions increasingly shift to digital platforms, the risk of falling victim to financial fraud grows. Practical tips to protect oneself from scams include being cautious of unsolicited communications. Verify the legitimacy of emails, messages, and websites, and never click on suspicious links. Setting up transaction alerts on your accounts can help you detect and respond to any unauthorized activity promptly.

    Additionally, make it a practice to regularly review your credit report. This not only helps you monitor your financial health but also enables you to identify any unusual activities or signs of identity theft promptly. Monitoring your credit report can be the early warning system needed to prevent long-term financial damage.

    Another increasingly important tip is to avoid the installation of unknown .apk files. Cybercriminals often use malicious applications to infiltrate mobile devices, gaining access to sensitive financial information. Stick to official app stores, and only download apps from trusted sources to minimize the risk of installing harmful software.

    BASICS OF SPOTTING A SCAM: STRENGTHENING YOUR FINANCIAL DEFENCE

    Understanding the basics of spotting scams is a fundamental skill in the digital age. Common signs of scams include unsolicited requests for personal information, promises of quick and high returns, and pressure tactics. Be sceptical of investments that promise overly high or guaranteed returns and always conduct thorough research before committing your funds. Moreover, educating yourself about the latest scams and fraud trends is essential. Cybercriminals continuously evolve their tactics, so staying informed about emerging threats enhances your ability to identify and avoid potential risks. Cybercriminals are becoming increasingly sophisticated, including disguising themselves as legitimate organizations and falsifying documents proving their credentials.

    NAVIGATING THE CYBER AGE WITH CONFIDENCE

    In the rapidly evolving landscape of personal finance, embracing the digital age comes with both opportunities and risks. While technology enhances the convenience of managing our finances and lowers costs, it also exposes us to heightened cybersecurity challenges. To navigate this landscape with confidence, individuals must adopt a proactive approach to securing their financial data and investments. By cultivating good digital habits, understanding the security measures of financial institutions, learning from past experiences, and staying informed about the latest scam trends, we can safeguard our digital wealth and enjoy the benefits of the digital age without compromising our financial security.

    This article is a contribution from Stephen Yong Chuan Seong. Stephen is the Executive Director at Wealth Vantage Advisory Sdn. Bhd. (WVA). His role and responsibilities include driving the firm’s strategic growth, especially in business partnerships & collaborations, financial products & solutions, and branding & marketing. Stephen also works actively to promote financial literacy among Malaysians. He is the Founder of MyPF. my which is an award-winning top-five personal finance platform in Malaysia.

  • Protecting Your Welfare and Financial Interests in The Face of Mental Incapacity


    When it comes to personal financial and estate planning, there is one crucial area that many financial advisors often overlook. This area pertains to a situation that can befall anyone, irrespective of their will. Imagine finding yourself in a situation where your mental capacity is gradually slipping away. Making sound decisions becomes increasingly challenging, and managing your financial and business affairs seems nearly impossible. You’re gripped by frustration and depression, and eventually, you lose control over everything.

    The ability to make prudent personal financial and business decisions is what sets you apart as a successful business owner or a competent professional. Now, picture a scenario in which you lose this defining trait, the cornerstone of your self-image and business success.

    As your mental capacity wanes or deteriorates, the dire consequences unfold. You begin to lose control over both your personal financial and business matters. When you reach a point where a significant part of your mental faculties has eroded, you lose control over everything. You find yourself in a distressing situation where your own wellbeing and personal welfare are no longer within your grasp but in the hands of others.

    In the eyes of the law, as outlined in Section 52 of the Mental Health Act 2001, when you can no longer manage your personal affairs due to mental incapacity, your decision-making power is wrested from you and given to a committee appointed by the court.

    ONLY UPON DEATH

    Wills and nominations, typically, only take effect upon death. For example, a written will only become relevant upon your demise. All the nominations you’ve made in your EPF and life insurance policies come into play only after you pass away. Moreover, your life insurance policy’s death benefit remains unclaimed until a death certificate is submitted.

    Whether you’ll receive the total and permanent disability (TPD) cover benefit from your life policy depends on whether your state of incapacity aligns with the policy’s definition and terms and conditions. Most TPD benefits are disbursed six months after the insured individual becomes completely unable to engage in income generating work, with a waiting period of six months from the date of disability.

    It’s crucial to note that any testamentary trust established through your will instrument will not take effect in the event of incapacity. This trust, embedded in your will, can only be activated upon your death.

    DEMENTIA

    Dementia is a pressing concern. According to the World Health Organization, around 8.5% of older adults in Malaysia, roughly 260,000 people, are grappling with dementia. It’s a condition characterized by a loss of cognitive functioning, impacting thinking, memory, and reasoning to an extent that hinders daily life and activities.

    Dementia is not a sudden occurrence; it’s a progressive disease. Over time, individuals afflicted with dementia often require support in managing their affairs and daily activities. What’s worth noting is that dementia is not an inevitable consequence of aging; it’s a syndrome marked by cognitive function deterioration, memory loss, and behavioural changes. While it’s predominantly associated with older individuals, it can also affect younger people, and there’s currently no cure.

    In recent times, the media has reported prominent cases of individuals being subjected to court inquiries to determine their mental capacity and the potential appointment of a committee to oversee their personal, legal, and financial affairs.

    A TRUE STORY

    In December 2019, the son of the late Tun S. Samy Vellu filed a summons in the Kuala Lumpur High Court to ascertain his father’s mental capacity under Section 52 of the Mental Health Act 2001. He sought to determine if his father was mentally disordered, as his father had been unable to access his bank accounts due to his condition, prompting the legal action.

    There was another case involving the son of a 92-yearold millionaire businessman who filed a suit to evaluate his father’s mental health. He claimed that his father’s mental faculties had been declining over the past few years, leading to communication difficulties and memory loss. He applied for a court order to determine his father’s mental capacity to instruct lawyers on his behalf and to appoint a committee to manage his father’s affairs and estate if he was found mentally incapable.

    In conclusion, business owners and professionals who take pride in their ability to maintain full control over their personal and business lives are strongly advised to plan for the unexpected event of incapacity. Losing everything in such a situation can be avoided with proper planning.

    About the Author

    Lee Khee Chuan is a Securities Commissionlicensed financial planner representative. He is passionate about advising business owners and professionals on the importance of a comprehensive approach to estate planning. You can reach him at: leekheechuan@gmail.com

  • The Far-Reaching Impact of Inflation


    In an era of rapidly evolving economies and financial landscapes, the term ‘inflation’ has become a constant companion in financial dialogues. The global economy is in a perpetual state of flux, and understanding the manifold effects of inflation has become necessary in safeguarding our financial interests and aspirations.

    CAUSE AND IMPACT OF INFLATION
    Inflation’s genesis lies in the interplay of various factors. It can be spurred by increased demand, supply constraints, or external shocks. It impacts economies by distorting price signals, complicating long-term planning, and introducing volatility.

    For individuals, the ripple effects of inflation are deeply personal. Imagine the struggles of a family trying to maintain the same quality of life as costs rise. Retirement planning becomes more complex as the purchasing power of savings diminishes. The challenges are real, and the necessity of informed financial decision-making cannot be overstated.

    In recent years, Malaysia has grappled with inflationary pressures, influenced by global economic shifts and internal dynamics. Rising fuel and commodity prices, coupled with supply chain disruptions have contributed to a higher cost of living for Malaysians.

    Inflation is as violent as a mugger, as frightening as an armed robber, and as deadly as a hitman.” — Ronald Reagan

    SMALL BUSINESSES: WEATHERING THE STORM OF INFLATION
    The tumultuous waters of inflation often hit small businesses the hardest. While larger corporations might have the resources to cushion the impact, small businesses are more vulnerable due to their constrained budgets and limited pricing flexibility. When costs rise due to inflation, small business owners face the difficult decision of whether to pass on these increased costs to customers, potentially risking a decline in sales, or to absorb the costs themselves, potentially eroding their profit margins.

    Imagine a local bakery that relies on purchasing ingredients like flour, sugar, and butter. As the prices of these essentials rise, the bakery faces a conundrum. Passing on the increased costs to customers might lead to fewer purchases, as customers tighten their belts in response to rising prices. Alternatively, the bakery might choose to maintain prices, absorbing the increased costs, which could threaten its long-term sustainability.

    CORPORATIONS: DANCING WITH INFLATION ON A GLOBAL STAGE
    At the other end of the spectrum, multinational corporations must navigate the dynamics of infl ation across various countries and regions. In Malaysia, as inflation exerts its influence, these corporations face the challenge of aligning global strategies with local market conditions. Rising inflation in Malaysia can
    impact the cost of production, the price of goods, and the overall economic landscape.

    Consider a multinational technology company with operations in Malaysia. Inflation can lead to higher wages for local employees, increased costs for raw materials, and potential disruptions in the supply chain. To maintain profitability and competitiveness, the company must find a delicate balance between managing costs and delivering value to customers.

    STATISTICS SPEAK LOUDER THAN WORDS
    The impact of inflation is not merely a theoretical concept— it’s a reality backed by data. In Malaysia, statistics from recent years paint a vivid picture. Inflation rates, often measured by the Consumer Price Index (CPI), can provide insights into the extent of price increases. For instance, in 2021, Malaysia witnessed an average inflation rate of around 2.7%, a noticeable uptick from the previous year.

    Additionally, rising fuel and commodity prices have contributed significantly to Malaysia’s inflationary pressures. The World Bank reported that the average price of crude oil increased by more than 50% from mid-2020 to mid-2021. This uptrend in commodity prices can create a domino effect, impacting various sectors of the economy and ultimately trickling down to consumers.

    The impact of inflation is not merely a theoretical concept — it’s a reality backed by data.”

    A POWERFUL PERSPECTIVE
    Inflation’s impact is far-reaching and multi-dimensional, affecting individuals, businesses, and entire nations. Its effects on purchasing power, investment decisions, and economic stability are undeniable. Malaysia’s experience with inflation underscores the challenges faced by small businesses and corporations alike, reminding us that adaptation and resilience are key in turbulent economic times.

    As we navigate the currents of inflation, the wisdom of Ronald Reagan’s words holds true: inflation is a formidable adversary. To thrive in its presence, we must equip ourselves with knowledge, foresight, and a willingness to adapt. Inflation might be a force to be reckoned with, but armed with understanding, we can turn its challenges into opportunities for growth and innovation.

    THE FIVE EFFECTS OF INFLATION
    Inflation is no one-trick pony; its effects reverberate across various domains of the economy. From the wallet in our pocket to the boardrooms of multinational corporations, its impacts are undeniable:

    1. Purchasing Power Erosion
    Inflation gnaws away at the purchasing power of money. As prices climb, the same amount of money buys fewer goods and services. This translates into a diminished standard of living for individuals and families.

    2. Income Redistribution
    Inflation often redistributes wealth, sometimes in unexpected ways. Those who hold assets like real estate and stocks might witness their values surge, while those relying on fixed incomes, like retirees, find their purchasing power dwindling.

    3. Uncertainty in Investment
    Inflation generates economic uncertainty that affects investment decisions. Investors tend to seek protection against rising prices, thus adjusting their portfolios to include more inflation-resistant assets like commodities and inflation-indexed bonds.

    4. Interest Rate Fluctuations
    Central banks respond to inflation by adjusting interest rates. Higher inflation can lead to higher interest rates, which affects borrowing costs for businesses and individuals alike, potentially curbing spending and economic growth.

    5. International Competitiveness
    Inflation can influence exchange rates, impacting a nation’s international competitiveness. A depreciating currency might boost exports but also lead to higher costs for imported goods, affecting trade balances.

  • Trust In Transition: Ensuring Legacy Security Amidst Blended Family Dynamics

    In the intricate tapestry of family dynamics, Claire’s concerns (as you will read in the below true story) resonate with a challenge that many families face: the delicate balance between love and the protection of hard-earned assets. As we delve into Claire’s story, it becomes evident that estate planning and the establishment of trusts play pivotal roles in addressing these concerns, especially within the context of Malaysian law.

    This narrative serves as a poignant reminder of the importance of estate planning in safeguarding familial harmony and preserving financial legacies. In the context of Malaysia, where familial relationships are deeply intertwined with traditional values, the concept of estate planning takes on even greater significance.

    Within Malaysia’s legal framework, several statutes underscore the significance of estate planning and trusts. The Wills Act 1959 governs the creation and execution of wills, allowing individuals like Claire to stipulate the distribution of their assets upon their passing. Additionally, the Inheritance (Family Provision) Act 1971 ensures that adequate provision is made for the family members of a deceased person, highlighting the importance of thoughtful estate planning to avoid future conflicts.

    TRUE STORY
    Claire had become increasingly concerned as she noticed her husband, Krishna, growing happier by the day. It wasn’t that she didn’t share in his joy, but rather, she was troubled by the sudden return of his estranged son, Jay. Memories of the bitter quarrel that had driven Jay away were still fresh in her mind. Back then, Jay had demanded his inheritance from his late mother’s estate, but Krishna, citing his son’s youth, had refused. Tempers flared, hurtful words were exchanged, and Jay stormed out.

    Recalling that painful time, Claire had seen Krishna suffer deeply. It took the arrival of their own children to help him heal from the heartbreak. More than a decade had passed, and now, out of the blue, Jay stood at their doorstep. Unbeknownst to Claire, Krishna and Jay had reconnected secretly over the past six months, and it was Krishna who had extended the invitation for Jay to return.

    Krishna was overjoyed at Jay’s apparent change of heart, while Claire remained sceptical. Jay’s newfound kindness towards her, as well as his half-siblings, felt suspicious to her. A nagging thought took root in her mind – could there be ulterior motives behind Jay’s return? She couldn’t shake off the feeling that Jay’s intentions weren’t entirely pure. With Krishna aging, Claire feared Jay might be angling for a signifi can’t share of his father’s assets by mending their relationship. The prodigal son seemed intent on reclaiming his status as the favoured child, and Claire couldn’t ignore this undercurrent.

    The more Claire dwelled on her suspicions, the more anxious she became. She worried about the fate of her hard-earned money and assets in this blended family dynamic. As her husband’s wealth and their shared property were involved, she pondered whether Jay could eventually lay claim to her estate. Could he inherit a portion of her assets if she passed away before Krishna? These questions weighed heavily on her mind.

    Estate planning in situations involving blended families is inherently complex. Claire and Krishna’s case warranted a careful approach. One viable strategy was the utilisation of a Testamentary Trust, a legal arrangement outlined within a will that designates a trustee to manage specific assets for the benefit of named beneficiaries over a designated period. For instance, Claire could stipulate in her will that her assets, including her half-share of the house, would pass to Krishna and her two children upon her demise through a Testamentary Trust. To ensure her intentions were upheld, Claire might appoint a licensed trust company as the trustee, ensuring her assets would be held and distributed according to her wishes.

    In the context of Malaysia, where familial relationships are deeply intertwined with traditional values, the concept of estate planning takes on even greater significance.

    Alternatively, Claire could establish a Declaration Trust. This arrangement would empower her to serve as the primary trustee during her lifetime, with a licensed trust company stepping in as a substitute trustee after her passing. By executing this plan, Claire could ensure that part of her assets would not be transferred to Jay, even if Krishna’s will dictated otherwise. Assets she intended to safeguard for her children could be held within this trust structure, safeguarding her wishes.

    Navigating the intricacies of estate planning within blended families could be made simpler through these trust mechanisms. Whether employing a Testamentary Trust, a living trust, or a Declaration of Trust, individuals like Claire could assert their intentions without being overridden by their spouse’s conflicting desires, particularly in cases involving children from previous marriages. This thoughtful approach could alleviate Claire’s concerns and secure the future of her assets, bringing a measure of peace to this complex family situation.

    The true story of Claire, Krishna, and Jay was written and submitted to SmartInvestor by Rockwills. The Rockwills Group of Companies has operations in both Malaysia and Singapore, providing solutions and support services in the areas of succession, administration, and distribution of wealth. Rockwills started in 1995 and is the pioneer in the region to provide retail Trust, Will-writing and Will custody services. Rockwills is also licensed, respectively, in both Malaysia and Singapore to carry on trust business, and its services include acting as trustee of many family trusts and executor of many estates. Other services include the provision of comprehensive estate planning advice and offshore services.