Category: business

  • Special Needs Trust: I’m Nobody’s Child

    Special Needs Trust: I’m Nobody’s Child

    The following story is based on an actual series of events, with some names and circumstances fictionalised. Any similarity to any person’s name, character, or history is coincidental and unintentional. It is about special needs trust and how it works in the real world.

    Elsie thought she had it all when she walked down the aisle with her beau and then to be blessed a year later with a beautiful bouncy baby, Ann.

    Little did she reckon that life would be cruel. It all started one afternoon when little Ann turned blue. It was heart-wrenching for her to see the baby so sickly with her life hanging on a thread. But Ann was a fighter. She survived but became mentally handicapped.

    A much relieved Elsie prepared herself for the long haul of bringing up a special needs child. Her whole life was now dedicated to Ann, which took a toll on her relationship with her hubby. They grew more and more apart, and it eventually led to a divorce.

    Read: Bob’s Dilemma: How To Convert Highly Illiquid Assets To More Liquid And Easily Realisable

    As a single parent of a child whose condition requires special attention, Elsie juggled between work and caring for her child. We were always overhanging and worried that Ann should not be around to care for her.

    A friend advised her to set up a Trust for her daughter, but she brushed off the idea, mistakenly thinking that it was something in the League of the Rich. She took comfort that she had many siblings and started to set aside money for her brother to use for Ann’s maintenance, just in case.

    Unfortunately, Elsie and her brother both died in a car accident. The money kept by the brother for Ann was frozen in his bank account, pending a letter of representation from the courts. In the meantime, the immediate needs of the special child were left unattended while the uncles and aunties bickered about who should take care of her and who should advance the money for the maintenance costs. Ann became nobody’s child.

    Read: How A Buy-Sell Agreement Can Help Business Partners In The Future

    Special Needs Trust Comes Into The Picture

    Elsie could have averted such a situation by setting up a Special Needs Trust with a trusted company to take care of her medical needs and maintenance. With increasing awareness and understanding, more people now know it is not true that a Trust can only be set up by wealthy people.

    In this case, she could have started by using her life insurance policy, unit trust investments, or even money in her bank account as the source to fund her Special Needs Trust instead of placing it in her brother’s account. Even if the sum is modest, she could set it up first and then increase it over time. In fact, the cheapest and fastest way to set up a trust is to fund it with a life insurance policy.

    Through the Special Needs Trust, she can also instruct the trustee to use the trust properly to pay for the upkeep of the house where her child is staying and maintenance costs for supporting the child. Instead of relying on help from relatives, she could also have instructed the trustee to make regular maintenance payments out of the income earned from the trust property.

    Read: The Amazing Reconciliation Of Father And Son, And This Reflected Inside The Will

    Generally, it is also better to appoint a licensed trust company instead of an individual to be the trustee because an individual is liable to die, fall ill or meet with an accident, become incapacitated, or even become bankrupt.

    Besides these problems, other possible risks may arise, such as monies being handled dishonestly or incompetently and failing to cater to the child’s care. For those parents who have children, whether with special needs or not, give them a good head start in life by planning and setting a special needs trust specifically for them, especially if you are a single parent.

    Read: Money Caused Breakup Among Four Close Friends, That’s Why it Is Important To Plan For The Succession Of A Business

    About Rockwills International Group

    Rockwills International Group, now in its 28th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in trusts, succession, management, and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and holds more than RM25 billion in assets under trust.
  • Be A-Z Ready For Tomorrow With Allianz Malaysia

    Be A-Z Ready For Tomorrow With Allianz Malaysia

    Allianz Malaysia Berhad recently launched ‘Be A-Z ready for tomorrow’, an educational  campaign to help Malaysians secure the retirement lives they dream of.

    Planning for retirement is more than just ensuring you have adequate finances. The Campaign, will look to help Malaysians understand the importance of retirement planning, with a keen focus on protection and types of insurance coverage that is vital at every stage of life for a sound retirement life.

    Allianz Malaysia believes that planning for retirement should encompass overall protection including medical, personal accidents, protection of assets, and having a good support system, in addition to having sufficient savings. Adequate protection is necessary as rising medical costs and unexpected events are likely catalysts for financial setbacks during one’s golden years.

    Allianz Malaysia Chief Executive Officer, Sean Wang said a general rule of thumb is that a retiree would need two-thirds of their last drawn salary to retire comfortably.  

    “When we were studying the market, we learned that Malaysians’ top priorities for retirement are to live debt-free, have sufficient funds for medical emergencies for themselves and family, whilst maintaining their pre-retirement lifestyles. These things will be hard to achieve if people are only leaning on passive savings to finance their golden years.“

    A study conducted by YouGov, a global public opinion and data company, showed that only 38 percent of Malaysians have taken proactive steps to plan for their retirement. In fact, when it comes to retirement planning, most are heavily dependent on passive modes such as saving accounts and EPF.

    The study which focused on understanding Malaysian retirement priorities found that those intending to plan for their retirement were receptive to protection plans like Life and Medical insurance.

    “When planning for retirement, you need to tick as many boxes as you can. Allianz Malaysia through our life and general insurance business offer the best of both worlds, and have crafted a complete suite of solutions to help Malaysians fully realised their retirement dream with no worries,“ he added.

    For a Total Retirement Plan, that ticks every box, Allianz Malaysia recommends having sufficient protection such as critical illness coverage and medical coverage to safeguard yourself from events which may deplete your retirement funds and lead to financial catastrophe.

    For example, our medical plan HealthInsured offers the most comprehensive medical coverage and comes with an option which many are not aware of. Customers can opt for a suitable deductible level to save insurance costs while being covered by an employer and remove the deductible upon retirement when there is no more employee benefit.

    Besides that, an individual that has a significant other and/or has children should also consider a robust protection plan that protects the family like Allianz PrimeCover with high death benefit coverage or leaving a legacy with certainty to the loved ones with our Allianz Legacy Plus.

    Malaysians should also consider having Personal Accident plans like Allianz Shield Plus to safeguard themselves in the event of injuries, disability or death, with Cashless Hopsital Admission and Discharge Benefit to further optimise their retirement protection.

    In addition, Allianz Malaysia will also provide additional support to its customers through the Allianz We Care Community.

    Via the We Care initiative, the Company collaborates with several partners from different sectors such as home care, pharmaceutical, and home medical devices among others, in offering our customers the complete retirement support they will need.

    For more details on our ‘Be A-Z ready for tomorrow’ campaign, or realising your retirement dream, please visit allianz.com.my

    About Allianz in Malaysia

    The investment holding company, Allianz Malaysia Berhad, a subsidiary of Allianz SE, has two insurance subsidiaries – Allianz General Insurance Company (Malaysia) Berhad (“Allianz General”) and Allianz Life Insurance Malaysia Berhad (“Allianz Life”). Allianz General is one of the leading general insurers in Malaysia and has a broad spectrum of services in personal lines, small to medium enterprise business and large industrial risks. The GWP for general insurance business for financial year 2022 reached a mark of RM2.66 billion. Allianz Life offers a comprehensive range of life and health insurance and investment-linked products and for the financial year 2022, Allianz Life recorded a GWP of RM3.37 billion and is one of the fastest growing life insurers in Malaysia. Allianz Malaysia has 32 branches nationwide. In 2021, Allianz Malaysia won The Edge Billion Ringgit Club (BRC) Financial Services (below RM10 billion market capitalisation) award for the highest growth in profit after tax (PBT) over three years. The Company also bagged the Malaysia International Business Awards 2021 (Life Insurance category) and three awards at the Global Banking & Finance Awards: Insurance Brand of the Year Malaysia 2021; Best General Insurance Product Malaysia 2021; and Best Insurance Social Media Engagement Malaysia 2021.

    To learn more about Allianz Malaysia, visit allianz.com.my 

    Facebook: facebook.com/AllianzMalaysia/ | Instagram: instagram.com/allianzmalaysia/

    LinkedIn: linkedin.com/company/allianzmalaysia/

    About Allianz

    The Allianz Group is one of the world’s leading insurers and asset managers with more than 122 million* private and corporate customers in more than 70 countries. Allianz customers benefit from a broad range of personal and corporate insurance services, ranging from property, life, and health insurance to assistance services to credit insurance and global business insurance. Allianz is one of the world’s largest investors, managing around 683 billion euros** on behalf of its insurance customers. Furthermore, our asset managers PIMCO and Allianz Global Investors manage about 1.6 trillion euros of third-party assets. Thanks to our systematic integration of ecological and social criteria in our business processes and investment decisions, we are among the leaders in the insurance industry in the Dow Jones Sustainability Index. In 2022, over 159,000 employees achieved total revenues of 152.7 billion euros and an operating profit of 14.2 billion euros for the group.

    *Including non-consolidated entities with Allianz customers.

    ** As of December 31, 2022

  • Financial Planning Firms Clone Scams

    Financial Planning Firms Clone Scams

    The public is advised to be wary of dubious investment schemes that use the name of legitimate financial planning firms. Please check the Securities Commission Malaysia website for the latest Alert List.

    The current modus operandi of the scammers are:

    1. Use financial planning companies key names on bogus companies to confuse the public,
    2. Add members of the public to social media chat groups while pretending to be represent legitimate financial planning firms,
    3. Offer dubious investment schemes that promise high returns,
    4. Post bogus investor testimonials to show proof of transfer receipts and making profits to gain the confidence of potential victims.

    It has also come to the attention of the Financial Planning Association of Malaysia (FPAM) that nine financial planning firms who are FPAM’s Corporate Members had their names cloned to promote illegal schemes. Their actual names are:

    1. Wealth Vantage Advisory Sdn. Bhd. (eCMSL/A0349/2018)
    2. Genexus Advisory Sdn. Bhd. (eCMSL/A0338/2017)
    3. Excellentte Consultancy Sdn. Bhd. (eCMSL/A0320/2013)
    4. Alpine Advisory Sdn. Bhd. (eCMSL/A0362/2020)
    5. UOB Kay Hian Securities (M) Sdn Bhd (eCMSL/A0018/2007)
    6. CC Advisory Sdn. Bhd. (eCMSL/A0342/2017)
    7. Harveston Wealth Management Sdn Bhd (CMSL/A0275/2010)
    8. iFast Capital Sdn. Bhd. (eCMSL/A0229/2008)
    9. Kenanga Investors Berhad (eCMSL/A0227/2008)

    To protect yourselves from being scammed, please do the following before making any payments or investments:

    Anyone who have fallen victim to these scams should do the following:

    1. Immediately report to the National Scam Response Centre’s (NSRC) by calling their hotline 997
    2. Report to Securities Commission Malaysia (SC)

    This article is brought to you by Financial Planning Association Of Malaysia (FPAM).

    FPAM is a non-profit organization with a vision and mission to establish the global CFP CERT TM mark as the leading symbol of excellence for personal financial planning and to promote its recognition as a profession to benefit all Malaysians. We also strive to promote Financial Literacy across the breath of the population of Malaysia.

  • Bob’s Dilemma: How To Convert Highly Illiquid Assets To More Liquid And Easily Realisable

    Bob’s Dilemma: How To Convert Highly Illiquid Assets To More Liquid And Easily Realisable

    The following story is based on an actual series of events, with some names and circumstances fictionalised. Any similarity to any person’s name, character, or history is coincidental and unintentional. It is about how to convert highly illiquid assets to more liquid and easily realisable.

    Bob and Leonard were the best of buddies. They did everything together in school and through university, including courting the same girl until she decided on Leonard, whereupon Bob graciously withdrew.

    After graduation, Bob worked as a lawyer while Leonard became an engineer. After several years, Bob made a name for himself in law practice, while Leonard decided to leave his job and strike out as an entrepreneur.

    With some inheritance capital and savings, Leonard bought a small but profitable boutique hotel in Kuala Lumpur. At the same time, he embarked on some small development projects building shophouses, small industrial lots and housing schemes in the Klang Valley.

    Five years later, he had the opportunity to purchase a piece of land to build a 200-room resort hotel in Penang, and as this needed a substantial amount of money, he approached Bob to help arrange to finance. Bob recognised the project’s viability and managed to help him secure financing, as well as personally putting up 40% of the capital required by Leonard.

    The hotel was completed and began making money consistently. The company that developed the hotel soon embarked on the construction of an adjoining tower of 150 apartment suites, which units were slowly released for sale.

    No dividends were paid as profits generated from the hotel were ploughed back into the company to finance the apartment tower. Sales of the units had been strong, reaching 70% until the pandemic hit.

    By this time, Bob was in his 50’s and thinking of retirement. During the pandemic, he started thinking a lot about succession. What if he passed on suddenly? How would his family access his assets?

    Read: How A Buy-Sell Agreement Can Help Business Partners In The Future

    Estate Planning Is Crucial: Learn How To Convert Highly Illiquid Assets To More Liquid

    He reached out to me and got an estate plan worked out for when he was not around – some assets to be distributed through his will while some substantial ones were put into a living trust to be distributed in stages to avoid overspending by the beneficiaries. We didn’t discuss yet on the topic of how to convert highly illiquid assets to more liquid.

    But what niggled him was the 40% stake he had in Leonard’s company. His family was unfamiliar with Leonard or his business. Bob realised that after his demise, the close relationship, trust and understanding between the two shareholders would be gone. Which was like saying the two shareholders would be strangers to each other.

    He was worried that his stake, which was now substantial in value, may become worthless after his death in that his family, as minority shareholders, would not be able to influence dividend pay-out, if any, and the company’s direction. And no one other than Leonard would buy a 40% stake at a fair price.

    He felt it would be difficult to impose on Leonard to buy his stake at a time when he needed to fund his business expansion. Hence he felt the need to convert highly illiquid assets to more liquid.

    Read: Money Caused Breakup Among Four Close Friends, That’s Why it Is Important To Plan For The Succession Of A Business

    Convert Highly Illiquid Assets To More Liquid And Easily Realisable

    He talked to me about his dilemma and wondered whether I had a solution. I inquired about the details of the company assets and realised that his solution lay on how to convert highly illiquid assets to more liquid.

    So, I suggested that he propose to Leonard to swap his shareholding with unsold units that Leonard held. He gave a bit of a stunned reaction and said: “I should have thought of that.” And we both worked out what we thought was a fair exchange ratio, using cost instead of profit element (avoiding the need to revalue the hotel and apartment suites).

    We then brought the idea to Leonard, who liked the idea of being free from pesky shareholders if Bob was no longer around, and at the same time, getting rid of unsold stocks. A buy-sell with a trust was set up with our trust company based on the transaction carried out according to the agreed exchange ratio upon Bob’s death or mental incapacity.

    As it turned out, the solution worked after Bob had multiple strokes last year and had to be taken care of by his family, using proceeds from the sale of the apartment suites. Sometimes, I think the best solution is the simplest one.

    In this case, it is about how to convert highly illiquid assets to more liquid and easily realisable.

    Read: Hard Facts About The Executor Of A Will In Malaysia

    About Rockwills International Group

    Rockwills International Group, now in its 28th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and holds more than RM25 billion in assets under trust.

  • Oyen Pet Insurance: Not Just Another Insurtech

    If you were to ask a random person on the street if they own a pet and a personal insurance policy, there is a decent chance of the answer being yes. However, if you were to ask if they have pet insurance, the chance of an affirmative response is very likely to be low.

    Although many Malaysians still do not have any form of insurance, the average family is still likely to be covered with a medical or life insurance policy. But when it comes to insurance for pets such as cats and dogs, that is a whole other matter.

    Kevin Hoong Michelle Chin Oyen
    Oyen co-founders (l-r): Kevin Hoong, Michelle Chin

    This is where Oyen  comes into the market, with the company aiming to carve up a niche for themselves in the insurance sector. While the pandemic may have wreaked havoc on the economy, if it was not for this black swan event, the insurtech firm may never even have come to life.

    Michelle Chin, the co-founder of Oyen, recalls seeing almost everyone in her social circle introducing a pet into their lives as a result of the pandemic.

    “One of our friends adopted a second cat, and the cat was found to be suffering from liver disease and she spent a lot of money on treatments,” recalls Chin.

    This resulted in the other co-founder of Oyen, Kevin Hoong, wondering why there was a lack of pet insurance as a product. With a family background in insurance spanning 40 years, he was certainly well-placed to gauge the feasibility of spearheading the growth of a niche vertical.

    “We found out that there was one insurance company offering it in Malaysia – MSIG,” she remembers.

    “We then indicated our interest to launch a unique product offering with a niche focus on pet health, and the rest was history!”

    As for their friend’s cat, Chin shares that she has made a full recovery and is now insured with Oyen!

    How it works

    Claiming to be the “best pet insurance in Malaysia”, Oyen certainly works to live up to that tagline. It pays up to RM8,000 towards the cost of pet veterinary bills, which includes consultation, diagnosis, and treatment at the clinic and hospital.

    The more premium coverage plans also covers third-party injury; that is when your pet causes damage to the property of others or even other pets! This will include any legal fees, compensation and related medical costs up to RM30,000 for cats and RM50,000 for dogs.

    In addition, even the funeral expenses for your pet are covered under the premium coverage, which includes the burial plot and columbarium.

    Oyen is also transparent about what its pet insurance plan does not cover, listing all of these restrictions on its landing page; this includes aids and prosthetics, congenital conditions and surgical implants to name just three.

    Like many other insurtechs, it also strives to use simple language to convey the extent of coverage that your pet will receive. Such simplicity is at the heart of Oyen, which like all insurtechs, ultimately aims to simplify the process of purchasing insurance coverage, even for a segment like pets.

    Market challenges

    Running an insurtech company is never a walk in the park, let alone in such a niche like pet insurance, and with it comes a specific set of challenges.

    According to Chin, the biggest obstacle that Oyen faces is the lack of insurance knowledge in Malaysia. This often results in the company having to deal with and educate customers that cannot make head or tail of the insurance or claims processes.

    “We were surprised that 80% – 90% of those who enquire with us, have very limited knowledge of how insurance works,” she shares.

    “For example, we have had a lot of people who ask if they can claim for a vet bill that happened yesterday. Or they may be at the vet right now and they would like us to reimburse the cost!”

    She adds that customers also often ask about covering preventive and routine treatments, the responsibility of which lies with pet owners themselves.

    “Once people understand how the industry works, it is rather straightforward for them to consider getting their pets insured,” says Chin.

    Although the concept of pet insurance is still fairly new and relatively unknown to the wider public, it is not a new product in Malaysia, having been in the market since 2010. Chin says this is proof that insurance companies have already established that the market is big enough for them to introduce such a product.

    “We determined that there is a fast-growing demand segment through a few avenues,” she explains, adding that the pet care market in Asia-Pacific is growing, and is projected to continue growing at a compound annual growth rate (CAGR) of about 10% until 2028.

    “Pet humanisation has been rampant – people no longer treat their pets as pets, but as a family member, and even children.”

    This means that the way that people care for their pets is more extensive than ever before, with many now receiving home-cooked diets or even food prescribed specifically by pet nutritionists. Such pets also receive better healthcare treatments in general which could include pet hydrotherapy, physiotherapy and acupuncture to name a few. Some even go to the extent of conducting DNA tests on their pets to ensure proper lineage!

    “As the cost of pet healthcare increases, due to higher demand for better services and more advanced equipment, the need for pet insurance will increase as well,” predicts Chin.

    As for their future expansion plans, Oyen aims to provide “a holistic ecosystem in pet healthcare”. This means that any growth will be within the confines of the pet healthcare system first and foremost, instead of branching out to other insurance verticals.

    “If there are opportunities that arise from our pet healthcare focus, we will be happy to explore them.”

    When asked about what the long-term game is for Oyen, Chin is very clear as to what her ultimate goal is.

    “Becoming the pet healthcare super app in Asia Pacific!” she says unequivocally.

    Industry thoughts

    As part of the insurtech industry, Chin is certainly building something special in Oyen. However, she believes that there are still some industry blind spots that often get overlooked.

    “There is too much focus on the sexy parts of technology and digitalisation, and not enough on building empathy and simplicity into the user experience,” she notes.

    Her deft observation is that the space is awash with technological innovation, so that is not a weak point that needs to be addressed. However, many insurtechs end up chasing new breakthroughs and often ignore the human element that is required to quickly grow a loyal customer base. Rather than cutting-edge features, ease of use should be prioritised.

    “We need to identify how these technologies or innovations help improve the experience for customers both from a registration and quote journey, as well as claims,” she adds.

    With its customer-first approach, it will be of no surprise to anyone if Oyen continues on its current growth trajectory!

    By Caleb Khew

    A version of this story was published in Smart Investor March/April 2022; issue 372.

    If you liked this article, do check out these other reads on Smart Investor:

  • Budgeting Is So Yesterday: Here’s 3 Intelligent Approaches to Financial Management for Youths

    Budgeting Is So Yesterday: Here’s 3 Intelligent Approaches to Financial Management for Youths

    The usual monthly paycheck, a nice little work bonus, festive allowance from uncles and aunties — we all know the adrenaline rush of having some extra cash on hand.

    But let’s be real: more often than not, that money’s out of the bank just as quickly as it came in! While it could have gone to buying that shiny thing we’ve been eyeing for months, the reality is that many of us young adults know we can’t always blow it all on a luxurious lifestyle. We’re more likely to put it towards a loan we’ve been servicing, or a big (but essential) purchase that’s been put off for months, or even just clearing the monthly mountain of bills.

    In fact, that’s the case for an alarming 73 per cent of Malaysians aged 18 to 40: we’re all repaying some form of debt.

    We can promise ourselves that we’ll just “save more next time”. We can set aside stricter budgets for emergencies and rainy days. But with financial commitments piling up on top of ballooning costs, what else can we do on top of that?

    It’s not entirely about sacrificing that daily dose of coffee or the occasional self-care treat. It’s about knowing where the money should go.

    1. Turning credit cards and BNPL into friends, not foes

    We’ve all heard the horror stories: getting carried away by the convenience of living on credit, enjoying the financial freedom of delaying payment for expensive items that can be purchased immediately. Credit cards and ‘buy now, pay later’ (BNPL) platforms have long had a bad rep as massive debt traps, with some more careful Malaysians even avoiding the latter completely.

    In truth, though, they can actually be quite good for our financial health — as long as we approach them with a slightly different mindset.

    Rather than seeing them as a means to postpone payment (which could awaken the payment procrastinator in us), we as young Malaysians should instead fully leverage our youth and consider them as ways to start building a positive credit score! This is more likely to motivate us to pay our bills on time and reduces the chances of snowballing interest rates. Better yet: it also improves our financial standing for the loans that will really count in the future, like a housing or wedding loan.

    Mastering which purchases to use credit cards or BNPL for can also make us small profits. For instance, by using credit only for certain types of weekly or monthly purchases, we’re more likely to be able to pay each month’s bill in full — which many credit card companies now reward with extra cashback or reward points. Rack them up, and we may just be able to afford a fancy item off their redemption catalogue for free!

    2.  Start investing early, small, and diverse

    Investment can come off as an income stream for older folks who already have some spare money set aside. Less than 35 per cent of young Malaysians consider it a priority, an even smaller proportion than those who are prioritising their own businesses.

    Truth is, though, investing is an important way of growing wealth — which is all the more important now in the face of rising costs. Effective investing is less about the amount of money put into it, but rather about knowing what to invest in to suit your current age group and knowledge of the market. Even the smallest investment can make a huge difference over time.

    Often, young and inexperienced investors can be made to feel like they are “missing out” on more lucrative opportunities or that they are “misplacing” their investments. But I consider investing a lot like swimming: it’s always better to start small than jumping into the deep end from the get-go.

    Low-risk investments like fixed deposits, unit trusts, or Amanah Saham Bumiputera are recommended to start off with, especially since banking staff or trust agents will always be on hand to answer questions or profile any investment needs. Moreover, passive investment apps or platforms can also be a low-effort, digitised way to grow your wealth on the side.

    Dabbling in small-scale investments is a learning experience that can boost confidence to eventually diversify to higher-knowledge or more volatile ones, like the stock and capital markets. (And as always, remember that reward is proportional to risk, so tread cautiously!)

    3. Getting an expert opinion — that understands you

    With so many financial solutions and platforms out there, we’re not only spoilt for choice — we probably wouldn’t even know where to begin! It’s already natural instinct for us to turn to Google or social media to find information, so why not use that to connect with financial advisors that can cut through the noise as well?

    Financial consultancy has come a long way from the middle-aged man with a suit and briefcase. These days, they come in the form of a US$104 billion market: social media finfluencers (financial influencers) and modern advisory firms like Intelligent Consultancy.

    The financial consultant market is becoming increasingly younger, with advisors that are more relatable to the everyday Malaysian youth. They’re easier to connect with and understand: they do away with the fancy jargon, replacing that with easily digestible advice through social media content and personalised consultancy sessions.

    Debt management, personal loans, credit checking, even small business financing — advisors can help young Malaysians manage their financial health and work out payment strategies that work best with the lifestyles we hope to lead. Moreover, consultants and finfluencers may also have their own areas of expertise that can be a valuable source of financial upskilling and knowledge for us: investment security, stock market analysis, and even up-and-coming financing alternatives like Bitcoin or cryptocurrency.

    Even the best athletes have coaches, and for good reason! Financial advisors are uniquely positioned to help us devise strategies that not only meet our needs, but take us to the top: to future lifestyle aspirations, financial ambitions, and the big purchases we want to make — all without giving up that daily coffee.

    About the Author

    Keith Khor Kah Yong, Founder of Intelligent Consultancy

  • Alliance Bank Introduces Innovative Dynamic Card Number In Visa Virtual Credit Card

    Alliance Bank Introduces Innovative Dynamic Card Number In Visa Virtual Credit Card

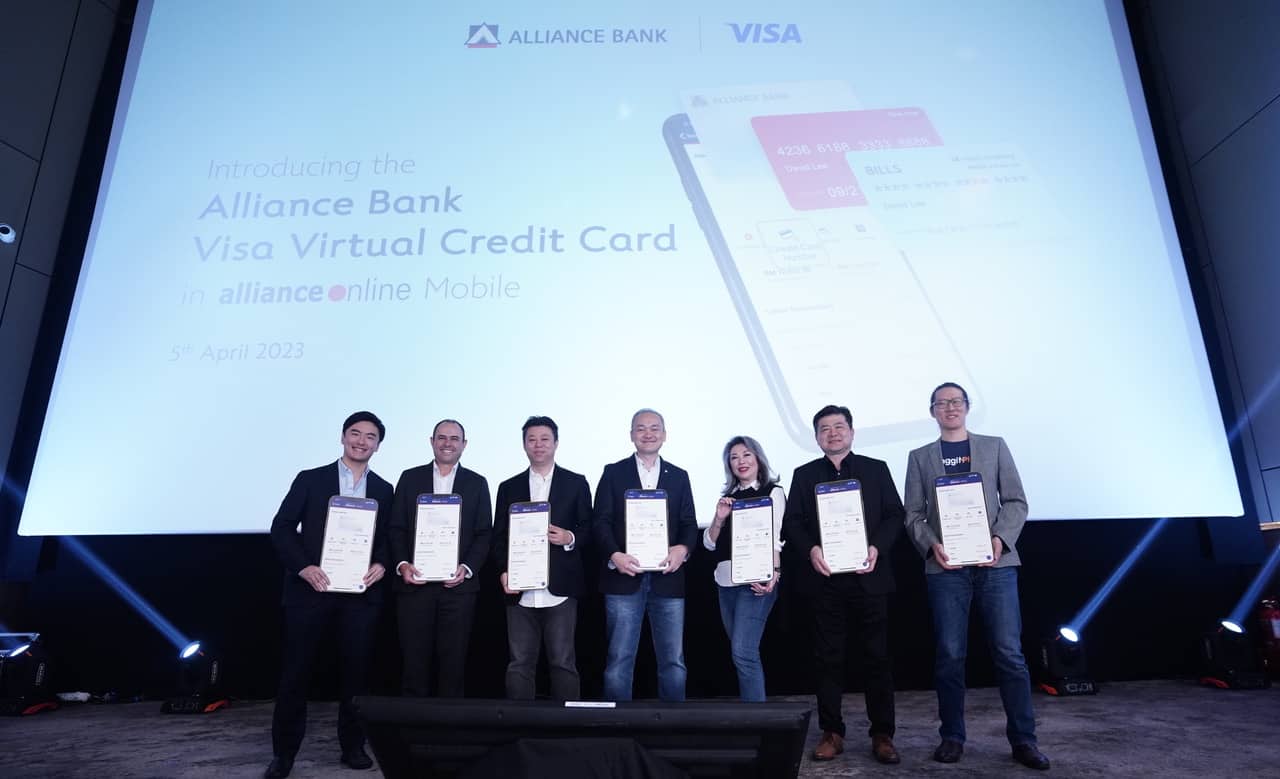
    Alliance Bank Malaysia Berhad (“Alliance Bank” or the “Bank”) continues to step up efforts to strengthen security of digital transactions with the introduction of Dynamic Card Number in its Alliance Bank Visa Virtual Credit Card. In partnership with Visa Malaysia (“Visa”), CTOS Digital Berhad (“CTOS”), Jirnexu (“RinggitPlus”), YTL Communications (“YES”) and Touch ‘N’ Go Digital (“TNG Digital”), this new payment solution will not only make online transactions more secure, but it will also greatly enhance the overall experience for credit cardholders.

    The enhanced feature generates a randomised 16-digit credit card number for every transaction which includes e-commerce transactions, streaming and subscription services to cater to customers’ various lifestyle needs. As part of Alliance Bank’s Acceler8 strategy, the Bank will continue to drive digital transformation to provide faster, better, and more personalised solutions for customers.

    The single-use Dynamic Card Number offers a more secure and safer way of making daily purchases and minimises the customers’ exposure to fraudulent risks, identity thefts and other  financial scams. Additionally, it also brings about a positive impact to the environment as it reduces production of plastic credit cards and helps to lower credit card footprint on online channels.

    Customers also have the flexibility to determine a dedicated Dynamic Card Number as well as the number of times it can be used for a particular subscription service. This enables customers to track and manage their digital transactions on-the-go more conveniently and securely via their mobile phones.

    “In line with Alliance Bank’s customer-first mindset, we constantly innovate and enhance our  suite of digital solutions to meet our customers’ expanding banking needs, and also deliver a seamless digital payment experience. The new feature on the Alliance Bank Visa Virtual Credit Card provides our customers with greater peace of mind by way of a more secure payment option, addressing concerns of credit card data breach at third party sites when they transact online,” said Ms Gan Pai Li, Group Chief Consumer Banking Officer of Alliance Bank.

    Sharing the same sentiment, Mr Ng Kong Boon, Visa Country Manager for Malaysia, said, “With more Malaysians relying on digital commerce, we believe it is important that they feel empowered and secure when making digital payments. Hence, we have partnered with Alliance Bank on this dynamic card number solution for the virtual credit card. We hope to give customers more confidence as they shop and pay for their purchases online.”

    “The virtual credit card will enable users a smooth experience when fulfilling their payments, reload and purchasing needs. Furthermore, the main edge of the virtual credit card is its dynamic card numbers which is in tandem with TNG Digital’s main aim for being a safe and secure eWallet in line with Bank Negara Malaysia’s standards,” said Mr Alan Ni, Chief Executive Officer of TNG Digital.

    With Malaysia recording 154 data breaches per 100 people in 2022 according to Surfshark, the introduction of the Dynamic Card Number aims to meet the market needs of more personalised and safe mode of payment for goods and services, especially among young professionals.

    The fully online application process is fast and simple, with digital submission of supporting documents such as EPF statements or salary slips. Successful applicants will be notified through a push notification.

    For more information on Alliance Bank Visa Virtual Credit Card or the Bank’s products and services, please visit https://www.alliancebank.com.my/cards/personal/credit-cards/virtual-platinum-credit-card.aspx

    About Alliance Bank Malaysia Berhad

    Alliance Bank Malaysia Berhad and its subsidiary, Alliance Islamic Bank Berhad, offers banking and financial solutions through its consumer, SME, corporate, commercial and Islamic banking, and stockbroking business. The Bank provides easy access to its broad base of customers throughout the country via multi-pronged delivery channels that include retail branches, Privilege Banking Centres, Business Centres, Investment Bank branches, and mobile and Internet banking.

  • The Amazing Reconciliation Of Father And Son, And This Reflected Inside The Will

    The Amazing Reconciliation Of Father And Son, And This Reflected Inside The Will

    The following story is based on an actual series of events, with some names and circumstances fictionalised. Any similarity to any person’s name, character, or history is coincidental and unintentional. Family in-fighting is common, but it should not hurt family ties and ultimately cause things to flow inside the will.

    David is a successful businessman who worked very hard building up his multi-billion dollar ceramic tile manufacturing business. So hard that he had little time for home and family, far less than he should have for bonding with his two sons, Ethan and Ben.

    Ethan was the older brother. A slow and steady person. Reliable. Non-controversial. Compliant. But unimaginative. He worked as the chief quality controller in his father’s business.

    Ben was a very bright child. The apple of his father’s eye during his younger days. The one his father hoped would take over the business in time.

    Read: He Had Everything But Children’s Harmony In The Family Business

    Don’t Make Hasty Decisions For Things Inside The Will

    One day, David called me to lunch at his office. Over dim sum, he told me he wanted to revise his will. Many years earlier, I had written a will for him when he wished to leave his business equally to his two sons and the rest of his assets to his wife.

    He instructed me to change his will to cut off Ben and set a small portion of his estate for a trust, RM10 million to be precise, to cater only for Ben’s basic needs for the rest of his life. I was shocked because his business, listed by then, was worth some RM500 million.

    “Are you sure?” I asked him. He suddenly looked downcast and said yes.

    “Why the great disparity between the allocations for the first and second son?” I asked.

    David said that Ben, after university, had worked in his company as the business development manager. Unfortunately, he became an alcoholic, to the deep disappointment of his father, and set a bad example in the office, often coming in late, slurring in his speech and reeking of the smell of alcohol.

    Read: Being An Executor Of Will Is Not As Easy As It Seems To Be

    Ties Can Be Repaired Before Finalising The Details Inside The Will

    I told him a clause would have to be added in the revised will to explain why he was excluding Ben from inheritance through the will. I also mentioned that he should talk with his wayward son before finalising the details inside the will.

    He said he had made up his mind, but I asked him whether he had considered that the underlying cause of the son’s behaviour and addiction could have been because he had been too harsh and draconian with the son without listening to his issues.

    He stopped in his tracks, stared into space and remained silent for a long while. He sent me off and said he would be in touch.

    After two months, he called me to meet again to discuss his new succession plans and to change the details inside the will. To my surprise, this time, his instructions were to leave the business 51% to Ben and 49% to Ethan.

    Anticipating my question, he said he finally concurred with Ben through a weekend trip. His son had turned to alcohol to vent his frustrations because of a perceived lack of listening ear from his father for many years. After many souls searching, the son had gone for
    rehabilitation treatment and managed to kick out his addiction.

    Needless to say, the father was ecstatic over his change and hence the revision of his will. Seeing the father and son reconcile after many years of misunderstanding was most satisfying as an estate planner. All because I had asked David a simple question, the family’s relationship improved, which was reflected inside the will.

    Read: Money Caused Breakup Among Four Close Friends, That’s Why it Is Important To Plan For The Succession Of A Business

    About Rockwills International Group

    Rockwills International Group, now in its 28th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and holds more than RM25 billion in assets under trust.
  • How To Save 50% Of Your Tax Payment?

    How To Save 50% Of Your Tax Payment?

    It is that time of year we have to file our taxes. I heard most employees file it quickly to get their refunds quicker. Is that the same for you too?

    I hope you have taken advantage of all your tax relief, especially if you earn more than RM7,000 a month. But is there a way to save 50% of your tax payment?

    I did a one-on-one with one of my Double Your Networth student, and she asked me, “How do I take advantage of my tax relief?” And I am grateful she ask me this question.

    Because sometimes I take for granted that everyone around me knows what to do. Especially since she earns RM25,000 a month, I know how paying taxes through her nose feels.

    I won’t go through all 15 categories, but  I prepared a simple tool I normally use to plan to see the difference between ‘taking advantage of the tax relief’ vs ‘not taking advantage of it’. Once you download it here, you can see how much money you will save & more importantly, and you can see your Effective Tax Rate (ETR)

    ETR is very important as I was misguided when I thought my ETR was 24% when my income was RM200,000 a year. But in reality, when you deduct all the tax relief, my ETR was probably at 10% of my total income.    

    Here is a quick summary of what Personal Tax Relief you can take advantage of (and the typical misses) depending on which category you are in for YA 2022. Only by knowing these details, will you be able to save 50% of your tax payment.

    Single Or Married Without Kids

    1. Self – RM9,000
    2. EPF – RM4,000 (if you are under the EPF scheme and not the pension scheme)
    3. Life Insurance – RM3,000
    4. Medical Insurance – RM3,000 (read here on what mistakes to avoid, I wrote a blog on this last year)
    5. Private Retirement Scheme – RM3,000
    6. Lifestyle – RM2,500 (purchase of books, laptop, tablets and smartphones and internet subscription)
    7. Additional lifestyle – RM2,500 (purchase of laptop, tablets and smartphones)
    8. Domestic Travelling – RM1,000
    9. Sports Equipment and Fees for rental – RM500
    10. Medical Fees for Parents – RM8,000 (do ensure you are the only 1 claiming & not claimed concurrently by your other siblings)
    11. Socso – RM250
    12. Vaccination – RM1,000 (Up to RM1,000 for yourself)

    Married With Kids Under 18 years old

    1. All the above
    2. SSPN – RM8,000 (most parents don’t take advantage of this for their kids)
    3. Ordinary Child Relief – RM2,000 per child (either parent can claim and not a claim by both parents)
    4. Lifestyle – RM2,500 (You can buy laptops, tablets and books for your spouse and kids as well. Since they can’t track, you can even buy laptops, tablets, and books for your nieces or nephew)
    5. Additional lifestyle – RM2,500 (if you have more than 1 child, you can claim additional on this purchase of laptop, tablets and smartphones)
    6. Child Education Insurance – RM3,000 (read here on what mistakes to avoid, I wrote a blog on this last year)

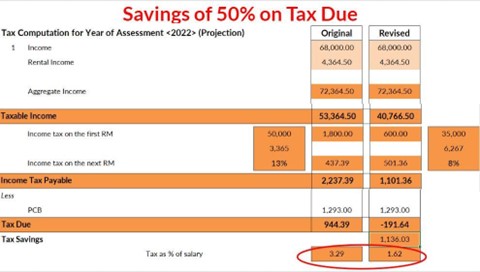
    Figure 1

    Here Is How You Can Save 50% Of Your Tax Or Effective Tax Rate (ETR)

    Mr Nair (not his real name) is working for a famous foreign Bank for 5 years. He and his wife have 2 kids. He manages to buy one property for investment purposes and is getting rental income.

    The main strategy to save 50% of your Effective Tax Rate is to maximize all your tax relief (if possible) OR spend/save consciously in areas with tax relief.

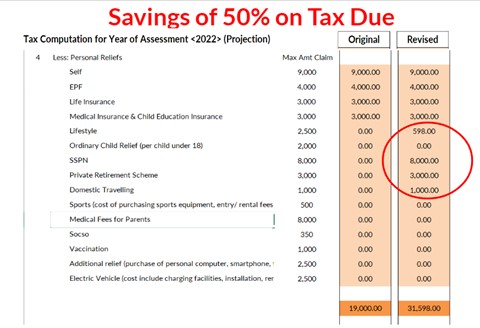
    For Mr Nair, all he needed to do was to:

    1. Maximize his SSPN by saving for his 2 kids – RM8,000 (RM4,000 each)
    2. Maximize his PRS by saving RM3,000 to any of the approved Private Retirement Unit Trust
    3. Take his family for a year-end holiday of RM1,000 (through approved operators and selected premises here – Item 8)
    4. Buy a basic smartphone for his son – RM598

    Figure 2

    You will notice in Figure 1, his tax bracket dropped from 13% to 8% because his taxable income dropped below the RM50,000 level.

    Hence he could save RM1,136 on something he needed to do anyway (to save for himself and his kids).

    In case you are tight on cash, one of the method I used was to transfer some of my existing investments / spare cash / emergency funds to my kids’ SSPN or my PRS. The idea is like “Move from your left pocket to your right pocket.”

    Is this something that benefits you? Yes, I know this is a bit late, but this doesn’t stop you from planning for this year (YA 2023), right? Hope you have a clearer idea on how to save 50% of your tax payment.

    *DISCLAIMER: All tax references have been taken from PWC’s website. All my sharing on how to save 50% of your tax payment is for educational purposes and is my personal opinion. It should not be confused with tax advice. Do consult a licensed tax consultant for proper tax planning.

    About the Author

    Ka Hoe is a Licensed Financial Planner having a “Financial Adviser Representative” (FAR) with Bank Negara and “Capital Market Service Representative License (CMSRL) – Financial Planner” with Securities Commission. He is also the Founder of J Advisory, a Personal Finance Academy that helps struggling Malaysians elevate their financial well-being with proven tools, systems and strategies.

  • Money Caused Breakup Among Four Close Friends, That’s Why it Is Important To Plan For The Succession Of A Business

    Money Caused Breakup Among Four Close Friends, That’s Why it Is Important To Plan For The Succession Of A Business

    The following story is based on an actual series of events, with some names and circumstances fictionalised. Any similarity to any person’s name, character, or history is entirely coincidental and unintentional. It is good to have a plan for the succession of a business.

    Gerald, John, Steven and Mazlan were close friends, dating back to schooldays. So close they would get punished together for naughty things that schoolboys typically did.

    The first two were involved in building up a successful business in manufacturing and distributing car interior accessories. At the same time, the latter two had also built up an equally successful business, this one in car exterior accessories.

    Because of the obvious synergies involved, they decided to merge and apply for listing. The structure that was decided on was one where a holding company (Car Listco) was formed to hold the two operating companies as subsidiaries. 25% of the shares in Car Listco would be offered to the public.

    Read: Tragic Procrastination On Estate Planning Documents

    The Succession Of A Business: Case Study Of Four Shareholders

    At the same time, the balance shareholding held by the four individuals would be swapped into an investment holding company (Holdco), which would then control Car Listco. The four shareholders held shares in Holdco with equal portions of 25% each. Car Listco was successfully listed and well received by the public, and the market price on listing was about twice the offer price.

    The four shareholders were very happy with the high valuation, translating into approximately RM60 million above the pre-listing value. And that was not all. Others were also prepared to pay a control premium for control of a listed company of some RM50 million at that time.

    This kind of structure is, in fact, not uncommon for companies preparing for listing. Somewhat innocuous. Until the four shareholders disputed distribution, Car Listco performed well for many years, selling through a larger distribution network after the merger and declaring healthy annual dividends.

    In the initial years after listing, Holdco received its share of dividends and distributed 80% of all it received, and shareholders were happy with the arrangement. But five years on, the first two shareholders, who were also partners in another business, began to have cash flow problems and pressured Holdco to distribute more, even suggesting liquidation of part of the stake in Car Listco.

    This led to many arguments and fractured the close relationship the first two had with the other two, which puts a pressure on the succession of a business. Compounding the problem, Mazlan died, and his brother, the only next-of-kin, took over his directorship, which became the last straw because of his lack of trust and aggressiveness towards the other shareholders.

    In the end, the shareholders decided to liquidate Holdco and distribute it individually to each shareholder to be free to do what they wanted with the shares. The result of this breakup was that the shareholders lost the control premium, therefore they have failed in ensuring the succession of a business.

    Read: Being An Executor Of Will Is Not As Easy As It Seems To Be

    How To Ensure The Succession Of A Business?

    So what went wrong? How did a successful merger and listing end with a breakup and loss of control?

    The crux of the problem was the lack of liquidity. The Holdco made up of friends’ stakes tied together at the outset was a mistake. While Car Listco shares owned by Holdco were liquid, the shares in Holdco were not, leaving no liquidity for shareholders in need.

    It would have been better had 51% shareholding been locked up in Holdco and the balance distributed to the individual founders so that they would have liquidity. This would have avoided the disputes they went through before liquidation. In addition, it would have been good to plan the succession of a business, where shareholdings with a buy-sell arrangement, so that the founders would retain control when any of them exited.

    Read: Unfulfilled Wishes, Learn How To Protect Yourself

    About Rockwills International Group

    Rockwills International Group, now in its 28th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and holds more than RM25 billion in assets under trust.