Category: Investments

  • Property Investing In A Post-Pandemic World, 4 Things To Consider

    Property Investing In A Post-Pandemic World, 4 Things To Consider

    Planning to do some property investing after the pandemic? Here are some factors to help you find rewarding deals.

    Real estate investment is one of the most preferred forms of medium to long-term investment, especially for Asians. It increases in value and generates ongoing passive income over time.

    Despite the Covid-19 pandemic that took a toll on Malaysia’s property industry, experts say the property market will likely recover in 2022 with renewed consumer confidence and the expected recovery in Malaysia’s overall economy. They anticipate that property investing will get better in the first half of this year before it begins to pick up in the second half.

    “All signs are pointing towards 2022 being a recovery year for the property market in Malaysia. It is predicted to be stable in the first half with gradual improvement in the second half. While many are adopting a wait and see approach, landed properties in the Klang Valley are hitting new highs each month,” says Chan Ai Cheng, President of the Malaysian Institute of Estate Agents.

    4 Factors To Consider In Property Investing

    With the attractive low interest rates and property prices on an upward cycle, it seems like a good time to snap up some good properties. However, you do need to have a sound knowledge before venturing into the world of investment properties.

    According to Chan, some of the factors to consider when investing in a property in Malaysia include:

    1. Purpose Of Property Investing

    Are you looking to make money through rental income or property appreciation? What you plan to do with the property makes a difference in deciding the type of property you need to buy. It also helps you narrow down the available options to find one that is better suited for your needs.

    2. Location And Neighbourhood

    Location is one of the most crucial factors to consider when investing in property. Other factors include accessibility and connectivity, amenities, plans for future development, proximity to transportation network, and how safe is the location from natural calamities like floods or landslides.

    “For me, I look for properties within easy reach of areas I am familiar with. There may well be opportunities in other localities, but it is always best to invest in locations you know best. You would have better knowledge of the neighbourhood, past prices, and potential for the area compared with buying on one’s hunch,” she explains.

    3. Type Of Property

    The main three types of property investing include residential, commercial, and industrial.

    “In Malaysia, most investors buy residential properties with a minority investing into commercial and industrial properties,” Chan says.

    Popular residential property options include landed properties like terraced houses, semi-detached houses, or bungalows. For non-landed properties, they include highrise or strata residential properties such as condominiums, serviced residences, and apartments.

    Each property type has its own set of terms and guidelines or considerations; thus, you need to determine what you are looking for in advance.

    4. Budget

    Your choice of property to invest in should not only be a good investment, but it should also fit within your budget.

    When calculating your budget, remember to factor in all initial costs such as downpayment, legal fee, stamp duty, bank processing fee, valuation fee (for subsale), as well as renovation expenses to get the property ready for use.

    Besides the monthly loan instalment, you also need to budget for recurring payments that come with owning a property such as monthly maintenance charges, annual quit rent and assessment tax.

    While most people buy directly from the developer and the secondary market, Chan says that there are some investors who focus only on picking up investment properties via public auctions. So, how do you find a profitable investment property in Malaysia post-pandemic?

    “Data is key,” says Chan.

    “Do your research on the type of property and the location you have your eye on. Although most hold the view that investing in property should not be an emotional affair, it is quite hard to separate the two.”

    According to Chan, if prices of properties within the area you are targeting have had a downward adjustment in asking prices – then it might be worth your while to put in an offer.

    With the rising cost of building materials and disruptions in the supply chain, Chan indicates that this might lead to higher property prices. This is favourable to property owners as real estate has historically been viewed as a good hedge against inflation—when housing prices rise with inflation, owners will see appreciation.

    Besides being a hedge against inflation, if done right, property investing can get you a substantial return through passive income and equity gains.
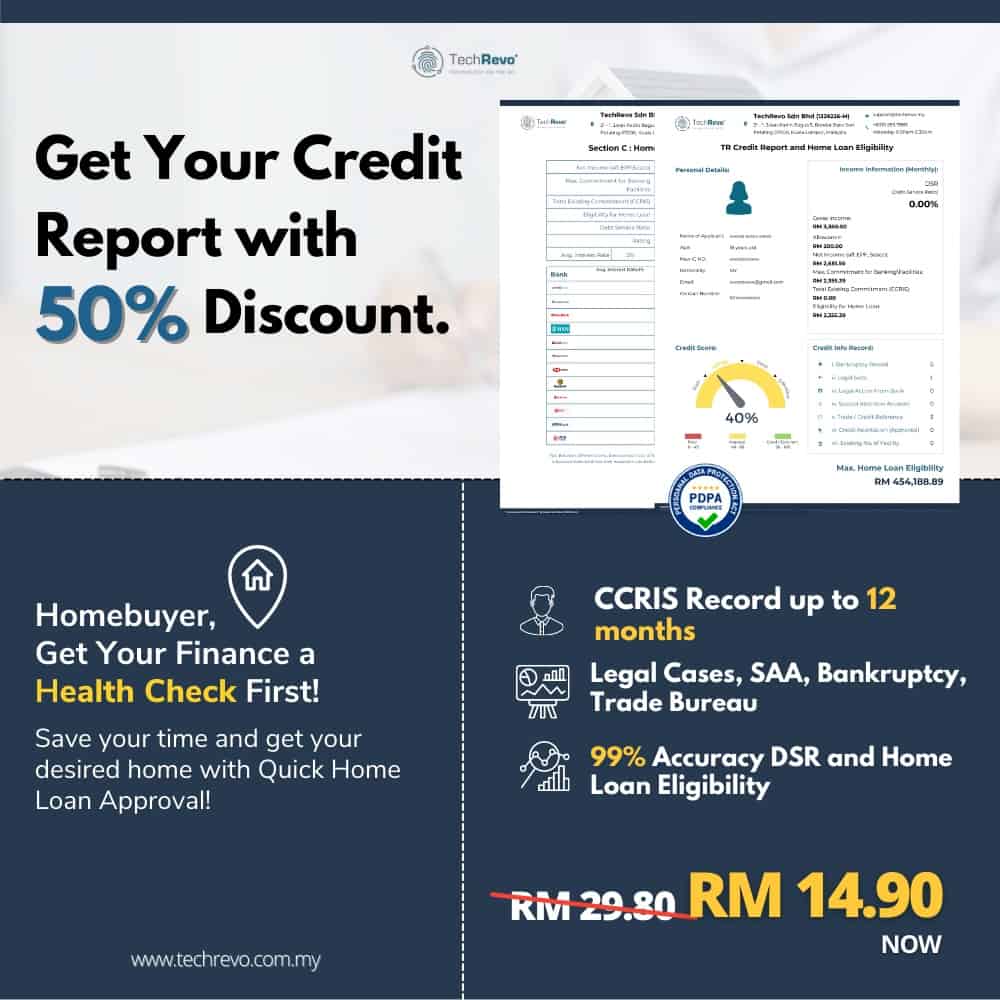
    Do you know how much is your Home Loan eligibility? Not sure how much you can borrow from the bank? 

    Get your TechRevo credit report + Home Loan Eligibility which includes:
    • Credit history up to the past 12 months [CCRIS] 
    • Bankruptcy, Legal Suits, Legal action from banks, SAA, and Trade Bureau (Section E)  
    • Max home loan eligibility calculation up to 12 mortgage favorable banks in Malaysia 
    • CCRIS + Credit report + Calculator 

    It only takes 5 minutes. Click here now to get 50% off -> https://www.smartinvestor.com.my/techrevo
     

  • The Importance Of Islamic Estate Administration

    The Importance Of Islamic Estate Administration

    For Muslims, Islamic estate planning can be key for the smooth distribution of assets to heirs.

    When a Muslim dies, the Islamic Law of Inheritance, namely Faraid, applies in respect of the distribution of the deceased’s estate. The main heirs entitled for his estate will be the father, mother, husband or wife, son and daughter. In other circumstances where there is no father or son, the siblings, paternal uncle or the child of paternal uncle, or Baitul Mal, will be entitled to the estate. The rights and portions of the heirs are protected and stated in al Quran, an Nisa’ verses 11 and 12. Those not under the above categories would not be entitled for the Faraid portion.

    In term of legal ownership, the rights of Faraid heirs would not be automatically transferred. However, such rights and portions must be claimed and vested through the legal process, or the estate will remain frozen under the name of the deceased and would not be of any benefit to the heirs. For a person who dies without a wasiat, a representative of the deceased shall be appointed as an administrator of the estate with the agreement of all legal heirs. He shall apply for a court order, namely a letter of administration to empower him to administer the deceased’s assets and liabilities subsequently to distribute the assets to the rightful heirs after making payment of the liabilities.

    Depending on the gross estate value, the letter of administration shall be applied at three agencies as follows:

    i) Department of Director General Lands and Mines (JKPTG) if the value of the estate does not exceed RM2,000,000 consists of movable and immovable assets
    ii) Amanah Raya Berhad for the movable assets worth not exceeding RM600,000
    iii) The Civil High Court for the estate value worth exceeding RM2,000,000

    In addition, the representative shall apply for a Faraid certification at the Syariah Court to ascertain who are the legal heirs and their share over the deceased’s estate. But for applications made at JKPTG, the Faraid certificate is not required.

    “It is advisable for a Muslim to have proper Islamic estate planning for the purpose of expediting the administration and liquidation of the estate.”

    Islamic estate planning instruments
    In consideration of the above issues, it is advisable for a Muslim to have proper Islamic estate planning for the purpose of expediting the administration and liquidation of the estate, as well as planning for a fair and balance distribution based on the wishes and needs of the testator and his family. Wasiat and Hibah are the two main instruments to be considered when preparing the Islamic estate planning.

    Wasiat
    Wasiat is an essential part of estate planning. Having a wasiat provides some advantages to the testator such as appointing an individual or a trust corporation as an executor to administer his assets and liabilities for distribution to his loved ones upon his demise. With the appointment of the executor, the tedious and lengthy process of getting an agreement from all legal heirs for the appointment of administrator can be avoided.

    Appointing a trusted and competent executor is crucial so the testator can rest assured that the administration and liquidation of the estate will be conducted smoothly in the proper manner and the rights of the beneficiary(s) are preserved. Unlike an individual, a trust corporation such as as-Salihin Trustee Berhad is a perpetual, competent, professional and governed under the Companies Act 2016, Trust Companies Act 1949 and Trustee Act 1949.

    In term of distribution, the testator is permitted to bequeath one third of his assets to his intended beneficiaries who are not his Faraid heirs. Therefore, wasiat is a good instrument for distributing assets to an adopted child, non-Muslim family member, orphanage, or charitable organisation.

    In addition, one third also can be allocated for sadaqah and waqaf for the purpose of getting rewards from Allah and his blessing in hereafter. The remaining two-thirds of the estate is to be distributed among the Faraid heirs. Faraid merely indicates the fraction of the heirs’ entitlement over the deceased’s estate as whole. This could result in the fragmentation of a property; for instance, if the ownership of a house is to be shared among many heirs such as father, mother, wife, son and daughter. Therefore, in his Wasiat, the testator may ascertain the manner of distribution.

    In other words, he may give specific assets to specific heirs within his Faraid entitlement or he will provide the executor with wide discretion to sell the asset without the necessity of obtaining consent from the beneficiaries. From the proceeds of sale, distribution of the estate can be divided without much delay. In brief, the executor may use his discretion and absolute power to execute the testator’s wishes provided that the wishes do not contravene Syariah law.


    Hibah
    Hibah is a gift made by a donor to a beneficiary(s) during his lifetime and effective immediately upon the setting up of the hibah. The hibah asset is not considered part of the donor’s estate and is not subject to Faraid. Of equal importance, hibah is used for distributing the asset to intended beneficiaries and avoiding fragmentation of the property. It is the most suitable estate planning instrument for a couple without children or only a daughter, a reverted Muslim, or a couple with a minor or special child.

    Business owners may consider hibah in a business succession plan to ensure the continuity of the business. Allowing the business to be run by all Faraid heirs and inexperienced heirs may lead to serious disruption or dispute within the management of the company. Thus, deciding on the right and capable candidate for taking over the business is a must as it can help to create a smooth transition and management of the company upon his demise.

    In conclusion, by drawing up an Islamic estate plan during his lifetime, the testator may determine who will be given the mandate to administer his estate and the manner of distribution of his assets upon his demise for the benefit of his family’s well-being.

    Article by : Amna Fazillah binti Ismail, Chief Business Officer of as-Salihin Trustee Berhad.
    as-Salihin Trustee Berhad offers full-fledged Islamic Estate Planning products and services such as Wasiat writing, declaration of Hibah, jointly acquired asset agreement, takaful trust and living trust.

  • Malaysia: Investment For Expatriates In A Global Context

    Malaysia: Investment For Expatriates In A Global Context

    There are many factors that expatriates must take into account when considering what to invest in.

    Whether you are risk-loving, or not, Malaysia has a lot to offer expatriates for work, pleasure or retirement. How much time you choose to spend in Malaysia may depend on your work schedule, family commitments and the availability of legal status as a foreigner.

    All these things change and so does the risk of investing in Malaysia. When you are deciding whether or not to invest in Malaysia, as an expatriate or a local, one way to make better decisions is to look at the risk and return on investment opportunities in Malaysia in a global context.

    Malaysia Country Risk

    Country risk is the uncertainty associated with investing in a particular country and, more specifically, the degree to which that uncertainty could lead to losses for you as an investor. Uncertainty can come from many different factors ranging from political and economic, to health and technological influences.

    A rule-of-thumb to use when assessing country risk is a global, or Asian, country risk ranking. For Malaysia the recent country risk rankings are varied and comparable to their Asian neighbours. Risk rankings are based on a variety of political, sovereign debt, perception of ethics indices and a combination of business specific factors, but how useful are they to the individual investor?

    Once you have taken the decision to invest yourself, your time and your hardearned money into Malaysia as an expatriate, then you can run through the list of assets that you might like to invest in and do a global comparison for each one.

    Your Time In Malaysia

    Is time more precious than money? It may be, depending on whether you have a busy job or are retired. Deciding how much of your time each year to spend in Malaysia and how much to spend in the rest of the world is a good way to assess your investment risk in Malaysia as an expatriate.

    With high growth rates in Asian countries and, until recently, ease of travel across Southeast Asia, Malaysia is the perfect hub from which to do due diligence on other Asian investment opportunities.

    Your Investment Portfolio

    Most investors, expatriate and local, diversify their investments amongst different asset classes. Malaysia offers the same, or similar, assets as most developed countries, which now includes cryptocurrency exchanges, but does that mean that Malaysia should be a large proportion of your investment portfolio? The answer to this depends on your personal investment journey.

    Entry, and exit, from Malaysia may be more complicated than you may have anticipated as an expatriate. If you are a Malaysian and see your future lying overseas, in Australia, the UK or elsewhere, then Malaysia may be a smaller part of your global investment portfolio.

    Short-, medium-, or long-term stays in any country does not necessarily equate to how much of your investment portfolio should be held there, but it could be an important factor. Analysing typical economic variables over time can inform your investment decision.

    The RINGGIT

    The first thing most visitors to a country look at is the exchange rate risk. If it is favourable, you may be pleased but it is not likely to cause you to extend your time in a country. Holidays, travel, work or living in a foreign country are usually motivated by more than one factor.

    In the case of Malaysia, the valuation of the ringgit against other foreign currencies is attractive for a holiday but does it make it a good investment for the medium- or long-term? Probably not; the Malaysian Ringgit is relatively weak, compared to major global currencies, and also volatile.

    Buying on dips may be good for speculation but long-term accumulation of currency in Malaysia, like many other countries, faces the risk of tightened global exchange and transfer controls.

    Real Estate

    Buying real estate in Malaysia is relatively easier for locals than for expatriates. Limits on purchase price for real estate for foreigners vary from state to state, and legal status as well. Compounding these risks, oversupply of property in Kuala Lumpur is palpable, but there are some real gems to pick up in good locations at affordable prices if you take expert, local real estate advice.

    Real estate in Kuala Lumpur is no longer below global market prices but there are many, great out-of-town locations still available at a fraction of global prices.

    Tax Rates

    Personal income tax and corporate tax rates are still relatively low in Malaysia. As an expatriate you can benefit from tax rates that are comparable to other neighbouring Asian countries and still below average global tax rates. A non-resident tax rate of 30% applies across Malaysia and 15% in Iskandar, Malaysia.

    This compares favourably to many countries in Europe where marginal rates of tax can be 40% or higher. Any good investment advisor will tell you that there is no point in making 100% if you have to pay 40% of it in tax. It also leaves you more to invest from your Malaysian income.

    Interest Rates

    Bank fixed deposit interest rates in Malaysia are still competitive, at more than 2% per annum, whereas globally interest rates can be as low as 0.1%. If you have built up a significant amount of savings, holding them in a riskless bank account in Malaysia could be a good investment in these turbulent times.

    Then there are higher interest saving options such as the EPF for salaried expatriates where annual interest rates, although variable in recent years, was a relatively attractive 5.2% per annum in 2020, with easy access to withdraw funds.

    Future Investments

    Crypto exchanges are nascent worldwide and Malaysia also has four regulated digital asset exchanges, namely Luno, MX Global, SINEGY and Tokenize. There is currently no capital gains tax on cryptocurrency profits in Malaysia, making it an attractive location to buy, hold and sell Bitcoin, Ethereum and other cryptocurrencies compared to other countries.

    If you are smart (and lucky), you may be able to realise large, speculative profits when you buy and sell cryptocurrency assets in Malaysia then invest for the longer term.

    Exit Strategies

    Exit from Malaysia may prove more difficult than you may expect, so do your homework and be prepared to face changing rules and regulations just like most other countries. A smart expatriate should think twice before he, or she, or they, make a long-term investment decision in Malaysia.

    One key country risk assessment that should be done before making an investment decision in Malaysia is your ability to transfer currency for foreign payments, or other uses. Such a country risk assessment involves weighing and assessing a variety of factors and potential, unforeseen future changes. If you are planning to retire in Malaysia, and never leave, then the only real risk is your inheritance. Due to the Covid-19 pandemic, and other factors, even this long-term view may need to be reassessed.

    A key question locals may ask you as an expatriate in Malaysia is ‘What are you doing here?’ It’s a good question, so why not ask yourself, as an expatriate investor, ‘What am I doing investing here?’ A good way to answer this is to put your Malaysia investments in a global context, then take it from there.

    Article by: Dr. Jonathan Di Rollo (PhD Econ)

    First published : Smart Investor Issue 369

  • The Basics of Forex Trading

    The Basics of Forex Trading

    The foreign exchange market, also known as the forex market, refers to a set of markets that facilitate the exchange of international currencies. According to Britannica Encyclopedia’s overview, the forex market is one of the oldest, biggest, and most liquid markets in the world. Today, most markets operate as over-the-counter (OTC) dealer’s markets, where two participants exchange assets over telecommunications channels.

    There are many reasons one might want to swap one currency for another: tourists, for instance, may buy local currencies while travelling, while international businesses may purchase foreign currencies to pay offshore employees. However, in the world of trading, investors exchange currencies with the goal of making a profit.

    If you’re interested in learning more about the complex world of foreign exchange trading, here are a few basic facts.

    How do traders profit from forex?

    Exchange rates can rise or fall by the minute. Traders profit from such changes by buying currencies while they’re undervalued, then selling them when their prices rise against other currencies.

    To illustrate: let’s say a trader predicts that the Great British Pound would become stronger than the US Dollar. Let’s also say that £1 was worth US$1.55. The trader then buys £1,000 for US$1,550. Later, his prediction comes true, and the GBP grows, with £1 becoming worth US$1.75. This time, when he sells his £1,000, he gets US$1,750, thus turning a profit of US$200.

    What is leverage?

    Traders can also increase their profits by making use of widely available leverage trading options. According to The Balance, leverage allows traders to invest a small amount of capital to use borrowed funds in large trades. Though the trader will still have to return the borrowed capital after the trade has been executed, they will receive the majority of the trade’s profits.

    Let’s say that the trader from the previous example wants to stake 15,500 USD in a trade. However, he only has 1,500 USD. Through leverage trading, he can use his 1,500 USD to borrow 14,000 USD, allowing him to purchase 10,000 GBP at 15,500 USD. If the exchange rate again shifts from 1 GBP for 1.55 USD to 1 GBP for 1.75, the trader can sell his 10,000 GBP for 17,500 USD. Returning the 14,000 USD he borrowed leaves him with a profit of 2000 USD.

    Of course, it goes both ways. If the trader’s prediction were incorrect, using borrowed funds would also amplify his losses. Thus, when trading on leverage, it’s important to only stake money you can risk losing.

    Where can I trade forex?

    To get started, traders must first create a trading account at a brokerage. These days, most transactions occur on forex trading platforms online, through websites, software, and mobile apps. According to an overview of trading platforms by FXCM, some of today’s most popular trading platforms include MetaTrader4, Ninja Trader, and FXCM’s Trading Station. These platforms are widely used because they offer resources that can help traders make smarter decisions. For example, some notable tools these platforms provide include access to advanced analytics, charting tools, and risk management applications.

    A note for beginners

    As with any financial endeavour, it’s best to enter forex trading with a plan in mind. As mentioned in our previous article The Importance of Financial Planning, a lack of understanding of financial risks and returns will make you vulnerable to errors of judgment, which can lead to bad trading decisions. Consequently, it’s important to take time to study the markets thoroughly before starting your trading journey. If you want some hands-on experience without putting your capital at risk, you can practice trading using virtual money on one of the many demo accounts available.

    Thanks to resources like leverage and helpful tools on trading platforms, forex trading has become more accessible. Beginners who want to try their hand at foreign exchange trading should study the market, its movements, and different trading strategies in order to safely engage in trading.

    This article was contributed by Alex Palmer.

  • Takaful Malaysia Launches Nation’s First Flexi Motor Takaful Plan with Pay As You Drive Daily Cover

    Takaful Malaysia Launches Nation’s First Flexi Motor Takaful Plan with Pay As You Drive Daily Cover

    Syarikat Takaful Malaysia Am Berhad (“STMAB” or “Takaful Malaysia”), the general takaful arm of Syarikat Takaful Malaysia Keluarga Berhad virtually launched Takaful myClick Motor FlexiSaver, the nation’s first flexi motor takaful plan with Pay As You Drive daily cover. Jointly organized by Takaful Malaysia and technology partner, Fusionex, the virtual launch was officiated by Dato’ Mohammed Hussein, Chairman of Syarikat Takaful Malaysia Keluarga Berhad.

    “Virtual launch of Takaful myClick Motor FlexiSaver signifies Takaful Malaysia’s unwavering commitment to driving product innovation and delivering superior customer value. Flexible protection plans are the future of the insurance and takaful sector. Offering insurance and takaful products in the new mobility space that are simple, flexible, and usage-based is revolutionising the industry. This means, consumers have the option to decide and pay for just the coverage they need, as and when they need it. With more people driving less these days, while some may face financial challenges due to the impact of the COVID-19 pandemic, Takaful myClick Motor FlexiSaver is the best option that suits the financial and protection needs of those who drive infrequently or own several cars and want to save more on motor takaful or insurance plan. The Pay As You Drive daily cover available under this plan is ideal and rewarding, as we give customers the flexibility to activate it the day before they want to drive and will only be charged for the days they drive. Suffice to say, Takaful myClick Motor FlexiSaver is a quick win for customers to enjoy great savings and peace of mind when they drive,” stated Dato’ Mohammed Hussein, Chairman of Syarikat Takaful Malaysia Keluarga Berhad.

    Takaful myClick Motor FlexiSaver is an online motor takaful plan that provides one-year coverage for loss or damage to your vehicle due to fire or theft, as well as third party bodily injury, death, or property damage. Offered through Takaful Malaysia’s online sales portal and Click for Cover mobile application, this plan provides a 24-hour roadside assistance program for unlimited breakdown towing service and minor roadside repairs, including tyre change, fuel delivery, battery change, and jump start. Featuring Pay As You Drive daily cover for accidental damage to your own vehicle and complimentary personal accident coverage of RM15,000 for the driver and all passengers as well as accident towing, Takaful myClick Motor FlexiSaver also offers add-on protection options for windscreen, personal accident, and key replacement. Customers can also enjoy an instant 10% discount when applying the base plan of Takaful myClick Motor FlexiSaver, and when activating Pay As You Drive daily cover.

    Chief Executive Officer of Syarikat Takaful Malaysia Am Berhad, Mohamed Sabri Ramli said, “In our continued efforts to meet ever-changing consumer expectations, and in line with the rapid pace of digital expansion in consumer purchases, it is timely that we introduce Takaful myClick Motor FlexiSaver with Pay As You Drive (“PAYD”) daily cover to better serve our customers with innovative takaful solutions while preserving consumer choice. The PAYD is the key differentiator, a unique feature that sets us apart from other motor insurance and takaful plans available in the market. Customers only need to sign up for the base plan of Takaful myClick Motor FlexiSaver via our online sales portal or Click for Cover mobile app, before activating PAYD through the mobile app. Eventually, we want to make it easy and hassle-free for customers to enrol in this motor takaful plan online, corresponding to our digital strategy to enhance product and service accessibility.”

    “Takaful myClick Motor FlexiSaver with PAYD not only provides a simple online application process along with an array of benefits and services offered to customers but also diversifies Takaful Malaysia’s product offerings and creates a value proposition for consumers at large. Takaful Malaysia’s strategic move to introduce this motor takaful plan will provide new revenue and value-producing opportunities for the company to stay ahead of the curve and remain competitive in the motor insurance and takaful market,” added Mohamed Sabri Ramli.

    Dato’ Seri Ivan Teh, Group Chief Executive Officer of Fusionex said, “Insurance, at its core, is a business that underwrites risks and helps people in times of need. As such, I applaud Takaful Malaysia for revolutionizing their offerings and empowering their customers to take more control over how they purchase insurance. As a long-term and fully-supportive technology partner, Fusionex pledges to lend our experience, expertise and cutting-edge technology to drive excellent user experience for Takaful Malaysia’s customers, and this partnership continues to innovate with the launch of Malaysia’s first pay-as-you-drive motor insurance.”

    “Together with Fusionex, which specializes in analytics, big data, and artificial intelligence, we leverage digital and social media platforms to actively promote this product. Ultimately, we want to ensure that our business is competitive and relevant to the growing consumer demands, particularly the tech-savvy generation. By embracing technology and digital tools to offer differentiated product offerings and services, we will be able to reach new customer segments through superior protection products and customer experience,” said Mohamed Sabri Ramli in conclusion.

    Takaful Malaysia was recently voted once again by Malaysians as the Best Motor Takaful Company in Malaysia for 2021/2022. The annual award clinched by Takaful Malaysia is based on the results of the online survey conducted by iBanding, an independent, knowledge-based company that provides transparent insights about the local insurance and takaful industry that ranks insurance and takaful companies in Malaysia according to the actual feedback from survey responses among motor vehicle drivers.

  • How to Choose the Right Investment Vehicle for Yourself?

    How to Choose the Right Investment Vehicle for Yourself?

    “Soo Yee, I saw someone on Instagram saying that stock investment is better than unit trust investment. What is your view?”

    This is one of the questions that I get from my client on investment.

    Everyday, we are bombarded by a myriad of information on social media. It’s especially important to process the information, rather than consuming it blindly. How can you take up a piece of investment advice from someone who does not understand your financial situation as a whole? Does the mentioned investment vehicle suit your investment plan?

    Is stock investment really better than unit trust investment? It depends. Stock investment might be good for that person, but it is not necessarily good for you.

    When it comes to investment vehicles that suit you, there are many factors to consider. Here are some of the questions to ask to find your preferred investment vehicle.

    1. Risk level of the investment

    • Is the investment low, moderate or high risk?
    • Does it match your risk appetite?

    2. Capital needed to start investing

    • Does the investment require low or high capital?

    3. Investment lock in period

    • Is there a lock in period for your investment?
    • Is the investment easy to sell?

    4. Guaranteed element of the investment & its income tax implication

    • Is there a minimum guaranteed return for this investment?
    • How does this investment affect your income tax?

    5. Other considerations on the investment

    • Do you enjoy handling property management?
    • Do you enjoy spending time doing stock research & analysis?
    • Are you skilled in stock picking or do you prefer getting professional fund managers to manage your investment?

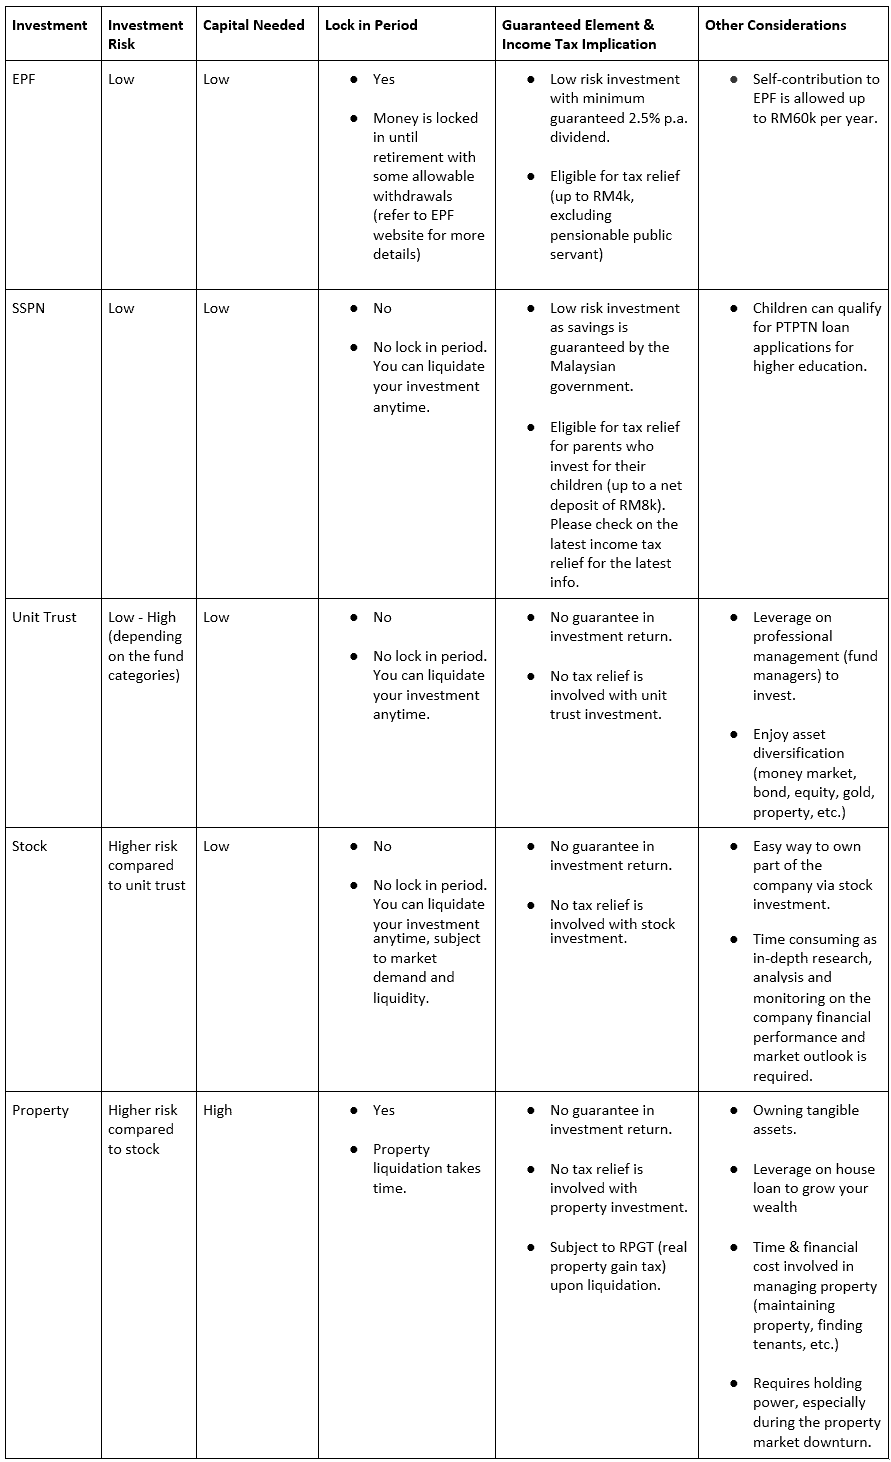
    There’s a multitude of investments available, so here are five of the more common investment types for your reference:

    How to Choose the Right Investment Vehicle

    If you’re a business person (without EPF contributions) and concerned about payable tax, some of the investments that can be considered are EPF and SSPN. Both EPF and SSPN will help to reduce your payable tax.

    If you’re a person who doesn’t have time or enjoy doing stock research & analysis, perhaps you can look into unit trust investment that leverages on professional management to invest your hard earned money.

    In short, a suitable investment vehicle for you should be tailored to your financial situation as a whole. If you’re clueless about your investment planning, you may consider investing in a licensed financial planner. A licensed financial planner will be able to look at your whole financial landscape and advise on the right investment vehicles to help you to reach your financial goals.

    About the author

    Kuah Soo Yee is a Licensed Financial Planner (CFP) who is passionate about helping people make sound financial decisions and achieve their financial goals, and recently launched her own app. Her personalised strategies and advice have helped many to gain better clarity and take firm control of their financial future. She can be contacted at soo.yee@ipp.com.my

    Website
    LinkedIn
    Facebook
    Instagram

  • SC Launches Five Year Capital Market Masterplan to Support Malaysia’s Next Stage of Growth

    SC Launches Five Year Capital Market Masterplan to Support Malaysia’s Next Stage of Growth

    Capital Market Masterplan (CMP3) strives to build a capital market that is relevant, efficient and diversified to enable the Malaysian economy to emerge fitter and stronger.

    The Securities Commission Malaysia (SC) launched the third Capital Market Masterplan (CMP3), which will serve as a strategic framework for the growth of Malaysia’s capital market over the next five years. It seeks to leverage on the strengths and potential of the Malaysian capital market to accelerate economic growth that is sustainable and inclusive.

    The CMP3 was unveiled at a virtual ceremony officiated by Finance Minister YB Senator Tengku Datuk Seri Utama Zafrul Tengku Abdul Aziz.

    Speaking at the launch, the Finance Minister said, “The CMP3 fits well into the nation’s aspirations as one of the key enablers that will pave the way for a wider population to participate in the nation’s growth by enabling more inclusive and accessible investment products and distribution channels. With the CMP3 as a strategic guide for our capital market over the next five years, I am confident that it will continue to play an important role in the Malaysian economy.”

    Datuk Syed Zaid Albar, Chairman of the SC said, “Malaysia is now at a critical juncture in our post-pandemic journey. It is imperative for the capital market to continue to support the economy as we transition into an inclusive and sustainable nation. The progress in the capital market cannot be measured solely by growth and size, as it also has to serve the underlying needs and aspirations of the country and its people.”

    The CMP3 takes into consideration global megatrends that will shape the recovery and growth of global and Malaysian economies as it steers the capital market towards three desired outcomes:

    i. Relevant to the development of the economy and its stakeholders;

    ii. Efficient in capital mobilisation and in achieving the desired regulatory outcomes; and

    iii. Diversified to create value for all participants.

    To achieve these desired outcomes, the CMP3 outlines six key development and regulatory thrusts that will collectively serve as pillars in developing strategic initiatives over the next five years.

    The first development thrust is facilitating fundraising for competitive businesses through a diverse market and intermediation ecosystem. The CMP3 also aims to empower all Malaysians to invest for their future and promote digital inclusion and protection for vulnerable investors. Furthermore, through the Sustainable and Responsible Investments (SRI) and Islamic Capital Market (ICM) pillars, the CMP3 aims to shape a stakeholder economy by mobilising more capital towards sustainable businesses.

    In tandem, the SC’s regulatory approach will also evolve in response to changing trends and market landscape. The CMP3 strives to embed greater shared accountability within the capital market, particularly corporate responsibility to stakeholders beyond short-term profitability. It also aims to achieve a more efficient regulatory outcome and greater efficiency in investor protection through swift, effective and targeted enforcement and supervision approaches. In addition, as the industry becomes more digital, the CMP3 envisions greater use of technology – both RegTech and SupTech – for greater efficiency and deeper insights.

    “It will be our collective responsibility to bring these strategic thrusts and desired outcomes to fruition, for us to achieve meaningful change. This is a shared journey for all of us to undertake. We will be stronger together,” concluded Datuk Syed Zaid.

    Over the last two decades, the Capital Market Masterplan 1 (2001 – 2010) and Capital Market Masterplan 2 (2011 – 2020) have successfully expanded the capital market while ensuring market stability and integrity. Malaysia now has a well-diversified capital market, with an equity market that has over 900 listed companies, a bond market that is the third largest in Asia, an Islamic capital market that is innovative and well-regarded globally, a derivatives market that leads in crude palm oil price discovery and a unit trust industry that is one of the largest in the region.

    In addition, governance strategies implemented during the previous masterplans have ensured robust regulatory oversight to enhance confidence in the integrity of Malaysia’s capital market. The Malaysian capital market regulatory framework is benchmarked and ranks highly internationally with regards to, amongst others, investor protection standards, corporate governance and enforcement capabilities.

    The CMP3 will build on this solid foundation to pave the way for the next stage of Malaysia’s market evolution and growth.

    To learn more about the CMP3, please visit https://www.sc.com.my/cmp3

  • AI : Automating Investing For A Better Future

    AI : Automating Investing For A Better Future

    Would you trust artificial intelligence to invest your hard-earned cash for you?

    Robo-advisors are fast gaining popularity in Malaysia, and while the concept of digital wealth management platforms have been around since 2008, it has taken much longer for such services to reach our shores.

    StashAway was the first robo-advisor to enter Malaysia in 2018, a year after it first launched in Singapore. Today, there are seven robo-advisors or digital investment managers (DIM) recognised by the Securities Commission Malaysia, suggesting that the industry is beginning to mature and grow exponentially. So what fuelled this sudden growth and how does it bode for the future of retail investors?

    A Time-Saving Option For Investors

    Contrary to a lot of investment products which tend to champion the rate of return, one of the main selling points of robo-advisors is the time that can be saved by using their services. The typical image of a full-time investor can often be one of multiple screens set up in a room, with hours spent analysing graphs and charts. In short, it is essentially a full-time job, especially for the most successful investors.

    “To build a case for investing, an individual would need time to learn the in’s and out’s of investing, which can be overwhelming for certain individuals,” says Wong Wai Ken, country manager, Malaysia of StashAway.

    “Robo-advisors offer individuals an alternative to this, as they are able to offer guidance to picking the right portfolio whilst charging much lower fees compared to traditional unit trusts. It is also a convenient manner to invest, as it gives investors a platform to get exposure to global markets.”

    With such convenience at investors’ fingertips, it appeals greatly to individuals that are keen to save time and have disposable income that they can invest, a notion that is backed by the demographics.

    “Our main demographic are white collar professionals in the financial services, tech, consulting, and oil and gas sectors,” shares Wong.

    “64% of our customers are the main financial decision-makers of their household, while 43% are male and 57% are female. The range of our demographic varies however, as StashAway is built for those focused on building long-term wealth.”

    And while a time-saving investment product may be thought of as appealing to the younger generation who are more tech savvy, it seems that seasoned working professionals are also coming round to the idea of alternative investments and are willing to explore. The time they save by leaving investing to algorithms can then be utilised elsewhere, be it into their careers, families or personal goals.

    Emotion-Free Investing

    One of the key tenets of robo-advisors is that it is not swayed by emotion, unlike humans who are often influenced by market movements in either direction. Regardless of market sentiment, the AI simple executes buy and sell orders as determined by its risk algorithms, which can provide peace of mind for more passive investors.

    [ You may read the full article HERE ]


  • How COVID-19 Affected Our Favoured Investment Themes

    How COVID-19 Affected Our Favoured Investment Themes

    Schroders identifies eight themes that could transform the world, but how are these being affected by the coronavirus?

    At the core of thematic investing at Schroders is the belief that the most powerful and persistent investment themes are those where human ingenuity ignites innovation to address imbalances in the world. These imbalances may be between populations and resources, or between supply and demand in individual industries.

    As we all know, necessity is the mother of invention. As coronavirus throws the whole world into turmoil, humanity’s ingenuity and powers of innovation are being mobilised to fight the disease, care for our populations and adapt our work and home lives to a new set of economic, political and social realities.

    Covid-19 is exacerbating existing tensions between populations and finite resources and dislocating supply and demand relationships in countless industries. Bearing this is mind, we examine the impact of this crisis on the eight investment themes that we think have the potential to transform the world we live in:

    1.HEALTHCARE INNOVATION

    “Crisis highlights importance of healthcare innovation”

    This pandemic underscores the critical societal importance of healthcare innovation as countries seek to prevent and cure disease while wrestling with ongoing demographic and budgetary challenges. Central to our investment thinking in this area is the belief that science and technology will be crucial as companies harness data, computing power and medical knowledge to meet these goals.

    We believe this will drive further breakthroughs in advanced therapies, medical technology, and healthcare services as well as in digital healthcare where technology in the form of ‘telehealth’ has shown its worth during this crisis as a means of making healthcare provision more responsive and efficient. As governments realise their vulnerability to pandemics, the drive to spend more on healthcare in the future can only intensify.

    2.SMART MANUFACTURING

    “Smart manufacturing essential as demand fluctuates”

    Amid the acute demand and supply shock experienced by the global economy, manufacturers are also having to innovate. We expect to see companies developing local supply lines alongside their existing global networks while investment in data analytics will be imperative as a means of understanding and managing volatile demand and disrupted procurement in the future.

    Investment will also take place in other smart manufacturing themes, including advanced manufacturing such as 3D printing, automation in the shape of robotics, sensors and controls, and advanced materials like lightweight composites as companies harness exciting innovations in hardware, software and materials to deliver greater agility.

    While manufacturers face undoubted short-term headwinds, the disruption caused by Covid-19 demonstrates the importance of manufacturing innovation to ensure responsiveness and productivity in both good times and bad

    3.CHANGING LIFESTYLE

    “E-commerce and well- being are growing lifestyle trends”

    […continue to read this full article HERE ]

  • Avoiding Investment SCAMS

    Avoiding Investment SCAMS

    What you should look out for and how to not fall for these malicious schemes.

    The economic impact brought on by Covid-19 has led many people into financial distress.

    Those looking for quick gains could easily fall into investment schemes that take advantage of their desperation and fears. Some of the victims might use all of their life savings or even obtain bank loans to participate in such schemes.

    For the perpetrators, their goal is simple: profit from the plight of their victims. While the stealing of private information and hard-earned savings are not new, such investment schemes are regularly updated and amended so as to portray a look and feel of legitimacy.

    People should educate themselves about the investments they are considering. Perhaps, start with being mindful about content and marketing scams. Here are some useful tips that help with identifying new scammer methods:

    TREND #1: MARKETING GURU SCAMS […]

    TREND #2: CRYPTOCURRENCY SCAMS […]

    TREND #3: VIRAL FAKE NEWS THAT CAN PHISH AND USE BEHAVIOURAL TRACKING […]

    [ …read the full article HERE ]