Category: business

  • How Drawdown Strategy Can Help Your Retirement Planning

    How Drawdown Strategy Can Help Your Retirement Planning

    Retirement. The “R” word that many would prefer to delay thinking about until it’s inevitable. I recently had the opportunity to discuss the meaning
    of retirement planning success with a client. Much of the thought process that she had undergone prior to our discussion was focused on the accumulation phase – making sure that there’s enough saved in the retirement nest egg.

    Want to know more about the drawdown strategy? OK, let’s go.

    But as one inches closer to the finishing line, the focus will need to shift towards the more interesting, albeit daunting, task of ensuring that whatever has been accumulated is sufficient to last the rest of our ever-increasing post retirement years.

    Looking at the environment that we’re facing today, where the cost of living seems to be escalating to worrying levels, one can’t help but to check and recheck their financial numbers before the income tap is finally switched off with retirement.

    If we want to increase the chances of our retirement planning success, a well thought-through drawdown strategy should be considered, at least 2-3 years before D-Day comes along. Here are some thoughts to get you going.

    Know Your Retirement Resources

    Before we’re able to effectively plan our retirement drawdown strategy, we will first need to be clear on what assets we have that can be earmarked for this purpose. As such, an asset listing and tagging exercise is the first step.

    Common assets that have been squirrelled away over many working years for retirement would include savings and investments in one’s Employee Provident Fund (EPF) account, bank deposits, properties, stocks, Amanah Saham, unit trust funds, endowment insurance policies and the like. A growing number of people are also investing in alternative assets like cryptocurrencies, private equity and peer-to-peer lending too.

    Having a complete listing of available assets and tagging them by financial goals will help us better understand the likelihood of achieving those desired objectives. Otherwise, there’s a chance that we might end up achieving certain goals at the expense of others.

    Read: Retirement Planning, Why It Is Important From An Islamic Point Of View

    Know Your Retirement Expenses

    To ensure what we have is enough to cover our expenses in retirement, we will fi rst need to know how much we incur today. If you haven’t already worked out your current expenses, this will be a good time to do so. In retirement, certain expenses will go up while others will decrease.

    You might spend less on work related travel or attire, but you might spend more on health supplements, holidays and social activities. If you find working this out a daunting task, then a simple rule of thumb is to budget 70% of your current expenses in retirement.

    Read: How a Trust Can Help You in Times of Need During Retirement

    Financial Goals In Retirement

    Retirement Planning

    It’s not all downhill upon retirement, especially for those among us who aspire to retire early. We may have a bucket list of places to go and things to do with all the time that we will have in retirement.

    Do you wish travel extensively or take up new hobbies? Do you have some long overdue home renovations or even a plan to relocate to a smaller home?

    Some of us might like to make some provisions to partially assist with the tertiary education funding for our grandchildren or help with some
    charitable causes. Add these goals to your list and put a fi nancial number and expected timeline to them.

    Read: Retirement Is No Joke, Here’s Why We Need Private Retirement Scheme

    Consider Potential Curve Balls

    Image by jcomp on Freepik

    A major concern for retirees is unexpected expenses. Some of these can be planned (with funding set aside accordingly), while others might need to be considered more carefully and risk mitigation steps may need to be put in place.

    Top of mind for most retirees would be medical funding, especially on the backdrop of the continuously high medical cost inflation these days. Do you have a comprehensive medical card in place with the appropriate daily room and board, annual and lifetime limits?

    If this is no longer an option (due to high premium cost or pre-existing medical conditions), you may need to be realistic and rely on government healthcare services as your primary medical provider.

    Another factor that is of concern to retirees is inflation. It’s unfortunate that inflation is rearing its ugly head the world over nowadays. Hence, the cost of living for retirees is going up quite drastically. As such, some adjustments to your retirement living expenses might be required to minimise this impact on your lifestyle where possible.

    Read: Debt-Free vs Retirement Savings: Which to Prioritise?

    Create Your Financial Buffer

    Once retired, you will need a buffer to ensure that the ups and downs associated with investments will not affect your lifestyle or ability to meet other short-term goals.

    Commonly termed as the cash reserve, these are funds set aside in stable assets such as bank deposits, capital protected accounts or short-term
    money market instruments. Ideally one should have between 2-3 years of annual expenses and the cost of any financial goals due during this period as cash reserves.

    Investing In Retirement

    Now that you’ve considered your financial goals, funding needs and potential risks, how do you continue to make the most of the assets you’ve
    accumulated to help you achieve your desired retirement?

    During retirement, most people tend to focus on income generated by the assets held. For example, an investment property can provide rental income while EPF savings will provide annual dividends. Similarly, stocks may be able to pay good dividends and bank fixed deposits will provide an interest income over the placement period.

    While income generation is important, it’s equally important to allow your investable assets the opportunity for capital growth to keep pace with inflation as well.

    Otherwise, you might end up relying heavily on the drawdown strategy of capital if income generated is insufficient. An accelerated drawdown strategy of principal, especially in your early retirement years, will have a long-term negative impact on your funding sustainability.

    When investing for retirement, you should continue to have a combination of different asset classes to help you ride out the different investment market cycles. Although it’s not the intention of this article to discuss safe withdrawal rates, it’s worth mentioning that commonly used assumptions include the 4% rule – ie one should invest equally in equities and bonds and can withdraw 4% of your investable amount yearly while adjusting for inflation.

    Do take note that these assumptions are US centric and might need to be adjusted to the local environment. As investment returns fluctuate, it’s worth to consider the retirement bucket approach to investing. In simple terms, you can think of investing in three buckets.

    Read: 5 Best Thing To Do When Your Retirement Funds Are Insufficient

    Drawdown Strategy: It’s About These 3 Buckets

    Bucket One in the drawdown strategy represents your cash reserves for the immediate 2-3 years of living expenses and funding of any short-term financial goals. Funds here are placed in safer assets with minimal price fluctuations.

    Bucket Two in the drawdown strategy will comprise of assets that can be held longer to cover the next 7-10 years of expenses, while generating income and capital growth that can be used to replenish Bucket One as you go along. Investments here would include EPF, stocks and high yield bonds, among others.

    Lastly, Bucket Three in the drawdown strategy comprises of long-term assets that can be held beyond 10 years and have good capital growth potential (think property assets, alternative assets and your own business). Income and capital growth from Bucket Three can then be utilised to replenish Bucket Two in the same way that Bucket Two replenishes Bucket One. In conclusion, most of us will spend anywhere between 20-30 years in retirement.

    As such, planning for this long journey should be given more attention. The sooner you start the process, the more time you have to make the necessary adjustments for the transition to be as smooth as possible.

    Remember that retirement is not a checkpoint but rather a lifestyle. As such, consider having something to retire into, rather than to retire from. That’s why it is important to plan for your retirement, and to know how the drawdown strategy is able to help you.

    Read: The Future of Retirement?

    About the Author

    Felix Neoh CFP CERT TM is Director of Financial Planning at Finwealth Management Sdn Bhd and can be contacted at felixneoh@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth
  • Takaful: More Than Just Islamic Insurance

    Takaful: More Than Just Islamic Insurance

    Malaysians are generally at a loss when it comes to being able to tell the difference between takaful and insurance. Some come to the conclusion that takaful is the Islamic version of insurance, while some perceive that takaful and insurance are just the same, hence the term Islamic insurance.

    What Is Insurance?

    Insurance is where a company undertakes the risk to provide a guarantee of compensation for specified loss, damage, illness, or death, in return for payment of a specified premium. There are two types of insurance namely, life insurance and general insurance. The coverage includes the insurance of life, personal, property, marine, fire, professional liability and guarantee.

    The purpose of insurance is to manage one’s risk. When the insurance is purchased, the participant buys protection against unexpected financial losses. In case an unexpected loss occurs, the insurance company will compensate the loss to the participant.

    Should the participant have no insurance coverage and an accident happens, they themselves shall be responsible for all related costs. In other words, the risk in insurance terms means the probability of something harmful or unexpected happening. This might involve the loss, theft, or damage of valuable property and belongings, or it may involve injury or harm.

    Read: Should I Give Up Paying Insurance Premiums In Difficult Times?

    What Is Takaful / Islamic Insurance?

    Image by tirachardz on Freepik

    Takaful is often referred to as ‘Islamic insurance’. It is strictly a business transaction to mitigate the financial risk of unforeseen events to the participants. Takaful is formed on the social solidarity and cooperation amongst a group of participants who mutually agree to jointly indemnify
    loss or damage from a fund they donate to collectively.

    In other words, takaful is a type of Islamic insurance where member participants contribute money into a pool system (tabarru’) to guarantee each other against loss or damage.

    There are two types of takaful, namely family takaful (mirror of life insurance) and general takaful (mirror of general insurance). A takaful contract which is called ta’awun must be based on principles of cooperation, protection and mutual responsibility. It must avoid acts of interest, gambling and uncertainty.

    The term Islamic insurance is popular, because it takes the insurance concept and turn it into shariah-compliant.

    Read: Takaful vs Conventional Insurance: What’s the Difference?

    The Shariah Aspect Of Islamic Insurance

    Islamic scholars differ in their opinion about conventional insurance. Some say insurance is permissible, some say only several types of insurance are prohibited but most of the Islamic scholars conclude that conventional insurance is unacceptable in Islam.

    The Shariah Advisory Council of Bank Negara Malaysia in its resolution states that the prohibition of conventional insurance is because it does not conform with Shariah law, particularly on the contractual agreement between the policyholder and insurance company.

    Conventional insurance uses a sale contract in their agreement but there is an element of gharar fahish (major uncertainty) in the contract since the essential element of the sale contract is not fulfilled. Furthermore, conventional insurance is also based on the concept and practice of charging interest.

    Islamic Fiqh Academy gave several reasons for the prohibition of conventional insurance:

    • The policyholder does not know about the time of the contract and the amount of what the policyholder gives or gets.
    • It is a contract based on probability.
    • It includes excess and delayed riba.
    • It can be considered a form of betting because of the existence of ignorance, uncertainty and probability.
    • The premium is taken for no consideration in exchange.
    • There is a compulsion that is not compelled by Shariah law such as the insurer does no specific work for the insured.

    Read: How to Protect Yourself at Different Stages in Life With Insurance

    The Importance Of Insurance And Takaful

    Both insurance and takaful are financial safety nets set to helping participants and their loved ones recover after something bad happens to them. Bad things may strike a participant at any time such as a fire, theft, lawsuit or car accident.

    When the participant joins in takaful or purchases insurance, they will receive a certificate or an insurance policy, which is a legal contract between them and the takaful operator or insurance company.

    Read: Insurance Affordability vs Need, 6 Factors You Should Consider

    The Differences Between Insurance And Takaful

    ‘Insurance’ and ‘takaful’ by name, are known as products. One is offered in the conventional financial system while the other is offered in the Islamic financial system. In Malaysia, insurance companies are under the jurisdiction of the Financial Services Act 2013 and takaful operators are
    under the jurisdiction of the Islamic Financial Services Act 2013.

    Payment to the insurance company are called ‘premiums’ and it is owned by the company. The payment to takaful is known as a ‘contribution’ and it is owned by the fund. The takaful operator just ‘manages’ the fund. The policyholder ‘buys’ insurance, and the participant ‘joins’ takaful.

    Takaful and conventional insurance companies share a common objective in providing protection to the participant, their loved ones and their valuable belongings. For Muslims, takaful is not the alternative to insurance.

    It is because takaful is based on the concept of social solidarity, cooperation and mutual indemnification of losses of members among the participants. It is a pact among a group of persons who agree to jointly indemnify the loss or damage that may be inflicted upon any of them, out of the fund they donate collectively.

    Business-wise, the main difference between conventional insurance and takaful is that the former is a risk-transfer model whereas the latter is a risk-sharing model. Mutual risk sharing is a transaction where instead of passing the risk on to an operator like conventional insurance, the risk in
    takaful is shared by every participant.

    The main concept of insurance is compensation of loss. Any insurance policyholder will be compensated once they lose something.

    In takaful, the concept is mutually helping each other (ta’awun). Members will get together to help other members should they incur any losses.

    Hope you now have a better understanding of takaful and insurance, and why the term Islamic insurance is often used.

    Read: Should I Nominate My Wife As Sole Beneficiary Of My Life Insurance Policy?

    About the Author

    Dr Haji Razli is a Senior Lecturer with Azman Hashim International Business School (AHIBS) at University of Technology Malaysia (UTM) and an Adjunct Fellow with IIUM Institute of Islamic Banking & Finance (IIiBF) at International Islamic University Malaysia. He is also the Honorary Secretary of the Association of Senior in Islamic Finance (ARIF).

  • Getting To Know Private Retirement Schemes (PRS)

    Getting To Know Private Retirement Schemes (PRS)

    For most people, the goal is to be able to retire comfortably. However, the effects of the Covid-19 pandemic have made achieving this goal a lot more challenging. But have you heard about Private Retirement Schemes?

    Various economists have warned that a retirement crisis is on the horizon. To insulate ourselves from this retirement crisis, the best time to act is now. The earlier you start saving for your retirement, or even growing your wealth again after it has taken a hit, the better.
    This time, we would like to explore a wealth-building option known as a “Private Retirement Scheme”, or more commonly known as “PRS”. This investment solution is offered and managed by PRS Providers and is governed by the Securities Commission Malaysia.

    As the name indicates, a PRS is a voluntary long-term investment scheme that is designed to help you save more for your retirement. First introduced in 2012, it is meant to help encourage people to contribute to their retirement savings.

    Investments in PRS are structured in the following manner: contributions are divided into two sub-accounts, and you can only make withdrawals once you reach retirement age. You are permitted to make partial withdrawals before then, but you will incur a penalty fee (there are exceptions, such as emigration).

    Contributions to PRS are entirely voluntary. It seeks to enhance choices available for all Malaysians, whether employed or self-employed, to supplement their retirement savings under a well-structured and regulated environment. Each PRS offers a wide range of retirement funds from which you may choose to invest in based on your retirement needs, goals and risk appetite.

    Why Invest In Private Retirement Schemes?

    Investing in PRS may be one of the best things you can do for your retirement. Here’s why:

    Designed for retirement

    As a scheme originally established to help investors accumulate more savings for their retirement, you can be assured that there is a selection of investment options to suit your specific goals and needs.

    Easy investments

    Anyone can invest in a PRS. There is a wide choice of PRS Providers and self-selected funds, as well as default option funds that have been pre-selected based on investors’ age.

    Affordable savings

    The minimum contribution varies depending on your chosen PRS Provider. While the flexible nature of the investment scheme means that there is less pressure on you to commit to a certain amount, just remember that the more you ‘save’, the better your potential returns can be.

    Tax incentive

    At the moment, the benefits of investing in PRS are not only for the future. In the short term, you can also enjoy a yearly personal tax relief of up to RM3,000 from your taxable income, for as long as you contribute to a PRS (the tax relief is available up to 2025). The earnings generated from a PRS will also be tax exempted, so that is even more reason to contribute!

    Factors To Consider Before Investing In Private Retirement Schemes

    When making your PRS contribution, you need to consider various factors such as your age, personal and household income, risk tolerance, retirement objectives as well as the suitability of the different funds offered under the various schemes to meet your retirement needs.

    The following chart offers suggestions on what you should take into consideration prior to investing in PRS. While the rule of thumb is that your investment strategy should be based upon the time you have until retirement (i.e. long-term investment strategies should focus more on capital growth, while short-term investment strategies should focus on income generation), remember that everyone’s situation is different, and that you should always consult an expert should you have any questions.

    Read: Who Are Unit Trust Consultants?

    Among the key items to note:

    Objectives: Based on your intended goals, you can choose to invest with the intention of growing your capital, generating income, or a combination of both. The goals of each person are different. As such, it is important to decide which option you wish to take.

    Your life stage: Those who are nearing retirement age should focus on investments that can provide them with a sustainable income, while younger people should be looking towards investments that have a higher potential for growth.

    Your risk appetite: Investors who can handle greater risks tend to be those with a long-term view as they are more able to weather any market volatility. Those who value stability tend to be those already nearing retirement age and therefore, would benefit more from investments that would allow them to preserve their initial capital.

    Additionally, it is important to review your PRS portfolio regularly. As your life progresses, your circumstances change and so do your needs and objectives. Hence, do ensure that your PRS portfolio continues to match your risk appetite and investment objectives.

    Investment Risks Associated With Private Retirement Schemes

    Investing in PRS is not risk-free. You will be exposed to some general investment risks as well as specific risks when investing in PRS. Therefore, you must consider the different type of risks that may affect you and the fund.

    These risks are disclosed in the PRS’ Disclosure Document and Product Highlights Sheet (PHS).

    How Do I Invest In Private Retirement Schemes?

    Your journey to save more for your retirement with PRS begins with these four simple steps:

    1. Select your PRS Provider.

    2. Choose a suitable fund.

    3. Open your PRS account.

    4. Top up your funds regularly.

    The Final Word About Private Retirement Schemes

    Remember that with careful planning, a PRS can be a useful tool to help you in your wealth-building journey. By staying focused, disciplined and investing wisely, you can be assured of a comfortable nest egg once you reach your golden years.

    Read: Getting To Know Unit Trust Schemes

    This article is in collaboration with The Federation of Investment Managers Malaysia (FIMM), a self-regulatory organization (SRO) that regulates the marketing and distribution of Unit Trust Schemes (UTS) and Private Retirement Schemes (PRS).

    Visit www.fimm.com.my for more information on PRS, Unit Trusts, and UTS & PRS Consultants.

  • Unfulfilled Wishes, Learn How To Protect Yourself

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. Hope we are able to learn a thing or two about unfulfilled wishes, and how to protect ourselves.

    She must find it, and fast! It’s a race against time for Jane as for the umpteenth time she is rummaging through her best friend, Esther’s apartment for the latter’s 20-year-old Will.

    It was surreal like playing out a heart-pounding scene from a movie – a now or never or the protagonist would lose out to greedy adversaries.
    The adversaries in this instance are the estranged siblings of Esther who are starting court proceedings to claim her estate after she died intestate (without a Will).

    “They can’t. They can’t…” Jane mumbled as she frantically searched for that elusive Will. “It’s not what Esther would want…”

    Tears rolled down her cheek as she slumped among the mountain of documents, feeling helpless. This was the last ditch effort in keeping alive Esther’s wish for continued acts of compassion for the unfortunate and underprivileged even after her death.

    Read: The Importance Of Estate Planning, Avoid Last Rites Drama

    Prior to this and in desperation, she had even gone to banks where she knew Esther had dealings with to enquire whether Esther had safe deposit box accounts. In hope against hope, she had prayed that by explaining the special circumstances, she would get help to check whether Esther’s Will was there. All she got were sympathetic ears and the same standard response that without a Grant of Representation from the courts, the banks could not allow the opening of the safe deposit boxes.

    “I have failed you Esther,” she sobbed. For the longest time that Jane had known Esther, she stood tall for her big heart and generosity, something that was nurtured from young by her late parents. They had inculcated in her that being able to give unconditionally to help the less fortunate without any expectation of anything in return is one of the highest blessings.

    She learned from the example of her parents unlike her siblings. She saw how both her parents continued to give to charitable causes after death through how the instructions they set in their Wills. She emulated them when she later prepared her own Will and apportioned her assets, including those that she inherited from her parents, to certain selected charities.

    But it was a recent benevolent wish to do much more for charities with her accumulated wealth that triggered a series of events that eventually led to the non-fulfilment of her lifelong passion and her wealth landing in wrong hands.
    Read: Decluttering Tips For Safekeeping Of Wills

    She had wanted to re-write her Will that was drafted and finalised 20 years back to include more charitable organisations she had come into contact with through her volunteer work. She also wanted to seek advice on how she could give to charities over extended period of time after her death, just like the recent publicised case of a woman who, year after year after her death, still donated to orphanages through clever estate planning.

    However, as she started the process of consultation with a professional estate planner, she was dealt a cruel blow. A diagnosis of Stage 4 cancer. It shocked her. That sudden knowledge took a toll on her. Her health deteriorated and just too soon as the cancer spread, she passed on.
    Being a benefactor to many charities in her life, many representatives of charitable organisations turned up at her funeral to pay their last respects and shared eulogies of Esther’s philanthropy and selfless service.

    Her long-estranged siblings did not hide their ill will for her being the sole inheritor of their parents’ estate and their renewed intention to claim back what they felt was rightfully theirs.

    Her brother rudely proclaimed after the eulogy by the last speaker that charitable organisations can dream on in thinking they can get any money from Esther’s estate as it belonged to the siblings. They sneered at Jane who told them that Esther had intended to leave all her material wealth to charitable organisations.

    Jane could not stomach that and defiantly told the siblings that under the circumstances, Esther’s Will 20 years ago was still valid.

    With that, Jane had thrown down the gauntlet. She had to find the Will before the siblings secure a Grant of Representation for Esther’s estate to be distributed in accordance with the law for intestacy.

    In the end, without the actual Will to show, Jane lost in her bid for get Esther’s unfulfilled wishes to materialise.

    It is not uncommon for many to consider it task accomplished having written a Will. Without safe keeping for easy retrieval upon death, all efforts in putting down one’s wishes in the Will comes to nothing.

    It isn’t over until the important Last Will and Testament is in safe custody! Unfulfilled wishes like that of Esther’s just can’t be undone.

    Read: Hard Facts About The Executor Of A Will In Malaysia

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.

  • Scam Awareness: Be Informed To Protect Yourself

    Scam Awareness: Be Informed To Protect Yourself

    Malaysians still have a low level of scam awareness, particularly when it comes to knowledge of investment and capital market products. This can be seen from the significant rise in online scams over the last two years – almost 72,000 scams and RM5.2 billion in losses was reported from 2020 to May 2022, according to the the Royal Malaysia Police’s (Polis Diraja Malaysia; PDRM) commercial crimes investigation department (CCID).

    The pandemic, rise of social media and rapid technological developments have all led to more retail participation in the capital market. The popularity of the Internet and social media has also provided fertile ground for fraud and scam activities by entities that are illegal or do not comply with the laws. There is also a low level of digital financial literacy in the country.

    A survey commission by Bank Negara Malaysia in 2021 revealed that one in three individuals stated they would be willing to share their bank account passwords or PINs with close friends. This increases the risk of online fraud and being used knowingly or unknowingly as ‘mule accounts’ to perpetrate fraud.

    Almost two-thirds of individuals surveyed do not pay attention to the security features of a website before they perform online transactions. As a result, individuals are far more likely to be deceived into providing their banking credentials through a fake website that enables scammers to use their information to commit fraud.

    Thus financial education is critical to the safe and effective use of digital financial services. Of the 72,000 scams reported over the last two years, 68% (or 48,850) were related to online scams, while loan and investment scams accounted for almost 12,000 of the overall scam cases.

    Read: RM5.2 Billion Lost To Scams In Malaysia Over Two Years

    In the first nine months this year, the Securities Commission of Malaysia (SC) received 1,800 complaints and enquiries related to investment scams and unlicensed activities. Last year, 275 names were added to the SC’s Investor Alert List, 143 websites were blocked and 35 social media pages were geo-restricted.

    So far, this year, 194 new names were added to the Alert List, with 143 websites and 26 Facebook pages blocked. The significant increase in scams and retail investor losses reported highlights the continued investor vulnerability and very low scam awareness.

    As long as our scam awareness is low, scammers will always find a way to trick us.

    Dato’ Seri Dr. Awang Adek Hussin, Executive Chairman, Securities Commission Malaysia

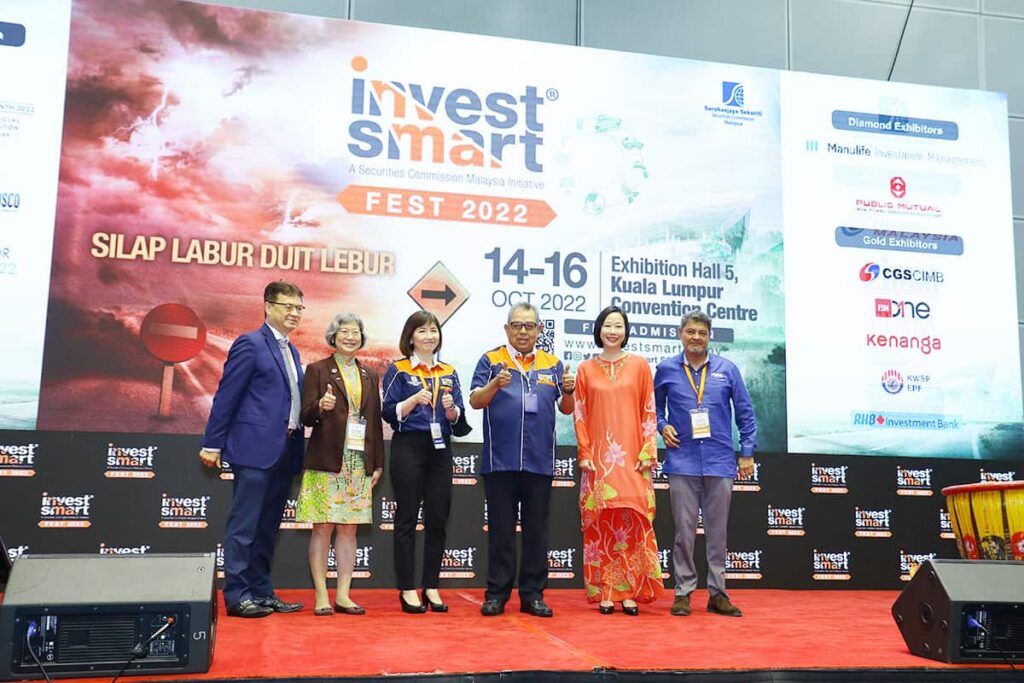
    “Most scams are spread through messaging apps and platforms like WhatsApp and Facebook. And we have recently noticed that they have started using Telegram as well. Many of these scams also claimed to be ‘syariah-compliant’ informed SC’s Chairman Dato’ Seri Dr. Awang during the SC’s flagship investor education fair InvestSmart® Fest (ISF 2022) held recently in conjunction with Financial Literacy Month 2022 and World Investor
    Week 2022.

    “Therefore, the best course of action investors can take to avoid falling prey to investment scams and unlicensed activities is to equip themselves with better financial knowledge,” he said in advising investors to safeguard themselves from the porous nature of the Internet.

    Surveys undertaken by the SC also found that Malaysian investors have unrealistic expectations about investment returns due to the misconception about risk and returns. Low financial literacy and low scam awareness makes investors vulnerable to unlicensed activities and scams.

    Scam Awareness: Unlicensed Activities And Scams

    Scammers are finding increasingly sophisticated ways to target investors, who range from the vulnerable at one end to those who invest primarily by the desire – or hope – to gain lots of money irrespective of the risks involved. Some would call this the ‘gambling instinct’.

    Under Malaysian law, any company or individual who wants to provide capital market products and services to Malaysian investors, such as unit trusts, stocks, digital investments, bonds, must be licensed or registered with the SC. This also applies to those who are or claim to be licensed overseas. As such, investors are putting themselves at risk when dealing with unlicensed or unregistered parties as the SC’s regulatory reach over these illegal entities is limited.

    “This is important because entities licensed or registered with the SC, must fulfil stringent regulatory requirements that are designed to protect investors. Investors who choose to trade on unlicensed platforms risk not being protected in the event of any dispute arising,” said the SC Chairman.

    In short, the SC cannot protect you if you choose to invest with unlicensed people. The SC Chairman also disclosed that there has been an increased use of celebrities or influencers on social media to endorse or promote investment advice and investment offerings.

    The public should also be wary of self-proclaimed investment gurus who offer questionable advice or use social media to spread false or misleading information, he said.

    Read: Beware of Investment Scams and Financial Gurus

    Investor Empowerment

    While pushing for greater adoption of digital innovation in the capital market to better serve the needs of investors, safeguarding investors’ trust and confidence is also important. Indeed, these digital services have widened access to the capital market for underserved investors at a lower cost. The availability of these platforms has made it possible to invest little amounts of money or spare change, some from as low as RM5.

    As the Malay proverb goes: “Sikit sikit, lama lama jadi bukit”.

    However, investors need to exercise vigilance against potential risk. “An informed investor is a protected investor. We need to cultivate a culture of enthusiastic, yet informed investor participation. One where the public is educated on the numerous investment options available, as well as their rights and responsibilities as investors.

    Armed with the right knowledge, investors are better positioned to safeguard their interests, and they can also become the SC’s ‘eyes and ears’ in detecting potential fraud or misconduct,” said Dato’ Seri Dr. Awang Adek Hussin, Executive Chairman, Securities Commission Malaysia.

    When it comes to investing, always remember this

    • Never deposit your money into someone else’s bank account; and
    • Deal only with licensed persons.

    Armed with the right tools and knowledge, investors will be able to capitalise on opportunities offered by our capital market. But first, let’s begin by raising the scam awareness campaign.

    Read: Combating The Rise Of Digital Fraud In Malaysia

  • Retirement Is No Joke, Here’s Why We Need Private Retirement Scheme

    Retirement Is No Joke, Here’s Why We Need Private Retirement Scheme

    When we are young, saving for retirement might not seem urgent. It feels like something that we can focus on later, especially since there are other more pressing and immediate financial commitments. However, we want to emphasise the hard truth: Retirement Is No Joke! That’s why we have the Private Retirement Scheme to help us all out.

    Why Should You Save For Retirement?

    We Malaysians are expected to live until we reach 75 years old. However, we retire at 60 years old. That means, we can expect to live at least 15 more years without receiving regular salaries.

    Some of us may be fortunate enough to receive monthly pensions or be able to rely on our EPF savings. Nonetheless, research has shown that merely having pensions or EPF savings may not be enough.

    Some of us may have children who are working and earning salaries. Although they can provide for us, do we really want to burden them, especially if they have children of their own to care for?

    Growing Your Retirement Savings 

    We don’t just want to save our money. We want it to grow. The way to do that is by investing our savings. A viable option is to invest in Unit Trust Schemes (UTS) or Private Retirement Schemes (PRS).

    Investing in UTS and PRS is one of the simplest forms of investing. It doesn’t require large amounts of money, time, or expertise.

    All you need to do is approach a UTS/PRS Consultant or Distributor. They will assist you to invest your savings into a UTS/PRS fund that is suitable for you. That fund’s investment will then be managed by a licensed professional fund manager.

    Read: Getting To Know Unit Trust Schemes

    Saving For Retirement 

    A Long-Term Activity 

    Remember that life is a marathon, not a sprint. If your retirement is still some time away, it will give you a lot more time to prepare for it. This means that your retirement fund can grow substantially simply by you putting aside some money consistently and invest them over a long period of time.

    To maximise your savings, the key is to start early. Just like in a marathon, every now and then, you should keep track of your progress and ‘refresh’ yourself. As your salary increases, revisit your periodic contributions, and adjust accordingly.

    After retirement, most of us will not have a fixed salary anymore. However, expenses remain. As such, your target savings should be one which can sustain your desired future lifestyle.

    How much should you save?

    You can refer to a retirement calculator. All you have to do is key in the requested details. Then, the retirement calculator will calculate for you the amount of savings you will need as well as the projected savings you will have based on your current savings amount.

    From there, you can calculate the shortfall and determine how much you should be saving on a regular basis.

    Consistency Is Key

    Remember to pay yourself first! Most of the time, once people receive their salary, they will save whatever remains after paying their bills, taxes, loans, groceries, and other expenses. However, this practice can lead to inconsistent savings. It is best that you allocate a fixed amount for your retirement savings first, before spending on your other commitments.

    Likewise, do NOT take ‘savings holidays’ or defer your savings contributions. You must be consistent!

    It would be ideal if you can consider signing up for a regular savings plan when investing in a UTS/PRS. This plan will, on a regular basis, automatically deduct money from your bank account and channel them towards investing in UTS/PRS. Hence, you can ensure that you will be consistent in your savings.

    Name A Nominee For Your Private Retirement Scheme

    Essentially, a nominee is the person who will inherit your savings/investments in the event something happens to you. Hence, it is essential that you elect a nominee.

    Even if you don’t name a nominee, your next-of-kin can still receive your monies from the Private Retirement Scheme. However, the process is a lot more difficult and expensive because he/she will need to prove his/her entitlement. By naming a nominee, the process is a lot easier and more cost effective.

    If you have not yet named a nominee, you can contact your authorised UTS/PRS Consultant and he/she will help you with the process of smoothening out the process of taking out the money from your Private Retirement Scheme.

    Read: Who Are Unit Trust Consultants?

    The Final Word

    Retirement is no joke! We want to enjoy our retirement comfortably and without any financial worries. As such, we must start saving for retirement early and doing so in a safe and disciplined way. Now you know why the Private Retirement Scheme is necessary to supplement your retirement funds.

    This article is in collaboration with The Federation of Investment Managers Malaysia (FIMM), a self-regulatory organization (SRO) that regulates the marketing and distribution of Unit Trust Schemes (UTS) and Private Retirement Schemes (PRS).

    Visit www.fimm.com.my for more information on PRS, Unit Trusts, and UTS & PRS Consultants.

  • Decluttering Tips For Safekeeping Of Wills

    Decluttering Tips For Safekeeping Of Wills

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. Hopefully by following this decluttering tips, you will be able to safeguard your wills so much better.

    Mama Lucy is so into Marie Kondo to the extent that she has been increasingly NOT sparking joy in her family members.

    Her obsession with decluttering tips has been annoying for her family members after she came to know of Marie Kondo who gained world fame for her Japanese art of decluttering and organising.

    This was especially so in the run up to her move from the family’s 3-storey house to a two-room condominium unit. A day did not go by before her daughter and son receive calls telling them that she is getting rid of their this and that as they no longer spark joy!

    Decluttering Tips: Don’t Overdo It

    Daughter Jane and son Jay, who have started families on their own and moved out, will then have to make trips that very day to their family home to take the items that they wanted, otherwise those would end up in the garbage bag.

    “Her OCD behaviour is eating me up,” Jay would gripe to Jane, whose tolerance of Mama Lucy’s obsessive-compulsive disorder too had reached her limit. Mama Lucy had even coined her own mantra, Mati Kosong, in an adaptation of the Marie Kondo acronym for her decluttering mission!

    The siblings hoped their worries about her Mati Kosong obsession would dissipate after their mum finally moved to her new condo. They were right until a week later after the move…

    Decluttering Tips: Safekeeping Of Wills

    estate planning will
    Photo by Scott Graham on Unsplash

    Jane received a frantic call one evening. Her mum at the other end went like a runaway train… “I can’t find my Will. I took it out from the Will Custody Centre. I wanted to make changes to the Will. I just remembered it and have been looking for it the whole afternoon…

    “I have looked into the boxes and everywhere. What should I do…?” her voice trailed off.

    It should be worrying. A Will that cannot be located is like not having a Will. Luckily for Mama Lucy the discovery of her loss of the Will was not after her demise which would put her children through a lengthy and arduous process of getting a Letter of Administration before the distribution of her assets could take place.

    Mama Lucy had been prudent in keeping her Will in a Will Custody Centre prior to taking it out for review. Now, having lost it, she needed to go through the process of writing a new Will and making sure that it is safely kept and easily retrieved at the crucial time.

    Read: Hard Facts About The Executor Of A Will In Malaysia

    Decluttering Tips: Let The Professionals Handle It

    Photo by regularguy.eth on Unsplash

    A professional Will custody company like Rockwills Corporation Sdn Bhd which specialises in providing custody and protection of Wills ensures that Wills are kept confidential, free from any tampering and safe from any accidental or deliberate destruction.

    A strong room with fire resistant walls and doors, motion and smoke detectors, non-explosive lightings, and humidity control safeguard such important documents from accidental damage or destruction as in fire or flood.

    Biometrics security features allowing access only through card and fingerprint and 24-hour security are part of the secure system that include tight security processes of regular audit to ensure Wills are kept secure at all times.

    The additional feature of security stamp embossing in each page of the Will also ensures Will in custody are tamper-proof.

    Easy location is another merit of a Custody Centre. Legal representatives of the testator simply needs to provide the custodian with the death certificate and proof of identity, for the Will to be released to execute the process of the distribution of the estate.

    Hope you enjoyed the decluttering tips, just make sure that you don’t overdo it.

    Read: The Importance Of Estate Planning, Avoid Last Rites Drama

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.

  • 5 Reasons Why You Shouldn’t Pay Off House Loan Early

    5 Reasons Why You Shouldn’t Pay Off House Loan Early

    If you have some extra cash lying around, we tend to use it to pay off house loan early so that we won’t be bogged down with loans well into our retirement. This is because housing loan can now go until 40 years or until we are aged 70.

    Isn’t it a good thing then to settle our debts earlier?

    Well I’m sure you have heard of the term, bad debt and good debt. Bad debt refers to debt that has a high interest rate, such as credit card and personal loan. It can reach double figures, with credit card interest in the range of 15% to 18% per annum, while personal loan is around the 10% range.

    The interest rates are kind of fixed, so if you have extra cash – it is better to clear off your credit card and personal loan. Unless you can find an investment that can give a return which is higher than 18%. And consistently giving out that kind of high returns.

    Whereas a good debt is having an interest rate that is low, but appreciates in value. Just like a house is. The current interest rate for loans in Malaysia is 4% to 6%, but your house value could go up by 10%.

    If you have bought a house in the 1990’s or 2000’s, the house price have increased several times over.

    So here’s a few reasons why you shouldn’t pay off house loan early.

    1. Low Interest Rates

    Yes, the primary reason is that the interest rate for housing loan is one of the lowest, if not the lowest. Compare that with the double digits that a credit card or personal loan, and you know that you are using loans for a good thing.

    You should just enjoy the facility that the banks have given you, and take full advantage of it.

    2. Invest For Higher Returns

    Let’s say you have extra cash around RM100,000 and are considering to dump it all in your housing loan. But there’s a potential to make 8% return on the investment, which gives you an extra RM8,000.

    In this case, you should go for that investment instead and let it compound annually. Using Rule of 72, the RM100,000 would have doubled to RM200,000 after nine years, provided that the 8% return is consistent throughout the years.

    You shouldn’t pay off house loan early, if you can find a good investment.

    3. Higher Return On Equity

    For example, a property worth RM1 million which gets a rental income of RM50,000 a year, is fetching a 5% yield. If you buy the property without a loan, your return rate is 5%. When you get 90% financing from banks, your equity is RM100,000. So your return on equity is 50% (RM50,000/RM100,000). 

    If your rental yield of 5% plus all future capital appreciation is higher than the mortgage interest, the leverage effect allows you to get a higher return.

    As you slowly pay down your outstanding principal, you build up the equity of the property. With a higher stake, your return rate comes down. That’s the reason that the more you pay down your mortgage, the return comes down too due to lower leverage.

    4. Extra Payment Not Liquid

    The equity value or extra funds that you put in your property is not liquid. You can’t take it out straight away, like you normally would when putting in your savings account. You might need to wait few days or weeks to cash out.

    Another way to unlock your property is by refinancing. But this would involve a new loan agreement, legal fees, admin fees etc. And by the time you get the money, it will be a few months later.

    That’s why you shouldn’t pay off house loan early, since you can’t take it out easily.

    5. Tax Benefit

    When you have rental income on a property that still has a loan, you can write off the mortgage interest when filing taxes. So the more you pay off the principal, the less interest you can deduct. Therefore, you might end up with more tax liability.

    That’s Why You Should Not Pay Off House Loan Early

    Now you understand why you should not pay off house loan early?

    Make sure you also read these:

  • 4 Money Personalities, Find Out Yours

    4 Money Personalities, Find Out Yours

    Have you ever met people with different money personalities? These can be your spouse, parents, colleagues or friends. Is there a single best money personality that each of us should adopt? During a recent wealth seminar that I attended, I learned about these four main types of money personalities.

    Come let’s check out your money personality.

    1. The Money Saver

    This person always feels insecure and wants to save as much as possible. It may be due to past experiences where these individuals have encountered financial difficulties, therefore they have this belief that it’s hard to earn money. Thus, it’s always good to set money aside for rainy days. I would agree that saving is a good habit to inculcate.

    However, if you just save money alone without spending appropriately, then you may miss out on some great experiences in life such as travelling or other fun activities. What’s the purpose of saving then, if we don’t spend it wisely on things that matter to us while still achieving our long-term goals?

    Read: Saving vs Investing, Should I Save Or Invest?

    2. The Money Spender

    This person always wants to buy things and must have the latest gadgets in town. They’ll buy whether they need those items or not and find fulfilment in spending their money. They may or may not have the money, but they’ll always have things to buy when they’re out for shopping. Now it’s even more convenient to spend money via various online shopping platforms available on our smart devices.

    On the contrary, some may have the “you only live once” (YOLO) mentality. This personality of people rather spend their money now rather than delaying it to their later years. However, spending without proper planning and budgeting will cause you to regret it down the line when you no longer have any in flow of funds, as many people don’t have enough retirement savings for their later stages.

    Read: How to Save Money in Malaysia – RM1 Million Goals

    3. The Money Avoider

    This person is not comfortable talking about money and never pays attention to their own personal finances. By not learning and understanding about personal finance or how to manage their money, these individuals may not be able to secure their financial future.

    Not learning about managing money will have serious consequences in life. These personality types often conclude that they’re not good at personal finance. It’s important for this group of individuals to learn about the basics of savings, investing and protection so that they can take more control of their life and be able to reach their own financial security or financial independence.

    Read: 6 Ways To Deal With Inflation

    4. The Money Monk

    investment

    Money monks are individuals that believe that money is the root of all evil or have preconceived negative beliefs about being rich. For example, they may have the belief that rich individuals are greedy and evil.

    However, these rich individuals can make a bigger impact on society by having businesses to solve problems that we’re facing. Some wealthy individuals also channel part of their wealth into philanthropy or contribute money and time to tackle major problems affecting the world.

    Read: Debt-Free vs Retirement Savings: Which to Prioritise?

    4 Money Personality, What’s Yours?

    Which of the above personalities is closest to your current habit of spending money? Personally, I don’t think that there’s one personality that is better than the rest. For me, it’s all about having that awareness of your current money personality.

    What do you need to change about your current money personality? Do you need to read more books about managing money? Or signing up for classes or to seek help from financial professionals to guide you in your money management?

    However, I think you should choose the right money personality that suits your current situation as it can change depending on your circumstances in life. It’s more important to have a balanced personality in managing your money so that you’re able to reach your financial goals and live the life that you desire!

    About the Author

    Goh Chee Yong is a Licensed Financial Planner under Capital Markets Services Representative License (CMSRL) and Bank Negara approved Financial Advisor Representative (FAR). Prior to becoming a financial advisor, he spent eight years working in Big 4 audit firms and multinational corporations. He can be contacted at cygoh@imaxfinancial.com.my

  • Emergence Of Tech-Based Financial Planning Solutions – Is It A Threat Or An Enabler?

    Emergence Of Tech-Based Financial Planning Solutions – Is It A Threat Or An Enabler?

    Islamic finance is growing at a remarkable rate. The impressive performance of Islamic finance is due to the vigorous development of infrastructures focusing on financial support in the industry. Malaysia is a hub for Islamic finance with the dominant sectors being Islamic banking, takaful and Islamic capital market, which includes Islamic financial planning solutions.

    With the growing demands for modern-day Islamic finance, Islamic financial planning solutions is seen as a service that best caters to these ever increasing needs and covers the wealth cycle to cater to the financial needs of individuals.

    Muslims may obtain advice and benefits from Islamic financial planning professionals on a wide range of issues, including cash flow and risk management, investment, self-managed retirement funds, zakat, taxation, takaful and legacy planning. All these tasks require specific knowledge and expertise in legislation, regulations, and market practices.

    Unnerving as it may sound, the importance of Islamic financial planning once again received sporadic attention when COVID-19 severely impacted many Malaysians, especially Muslims. The Movement Control Order (MCO) caused many people to contemplate having proper and structured emergency funds – prompting them to undertake financial planning.

    Technology – Emergent Requirement

    Technology is everywhere and evolving rapidly. Whether we are financial planners or consumers, it will become harder to thrive and survive without technology in constructing holistic financial planning solutions. According to McKinsey Global Survey, consumers have moved dramatically towards technology during the pandemic. The survey results confirm the rapid shift toward interacting with customers through digital channels.

    A piece of automated advice on financial planning solutions and applications is no longer (by right) a threat to financial planners, but rather an enabler for the industry to be competitive. The well-informed clients call for a wide selection of economical and practical financial planning solutions, whether online or through a mobile platform. Responding to this type of consumers, it is imperative to adopt financial technology as a channel for distribution.

    Technology is an agnostic tool that can significantly change the financial planning industry. By using technology, financial management’s efficiency and effectiveness will increase, making it easier for customers to deal with financial institutions through various activities and financial products.

    On the other hand, technology in the context of Islamic financial planning must be seen in compliance with Shariah guidelines.

    The Role Of Technology In Islamic Financial Planning Solutions

    It is essential to understand that financial planning solutions is not simply limited to the distribution of inheritance upon death, buying family takaful or investing in unit trusts. Developing a comprehensive financial plan is a personal journey for a true Muslim, and an excellent Islamic financial planner plays a critical role in this process.

    The client needs to have confidence that financial planners are up-to-date on the current financial planning landscape and current Shariah-compliant financial technology (fintech), diversification of halal investment selections via digital platforms, and other latest solutions to be considered.

    As technology advances, we have been able to automate parts of financial planning services, with vast improvements in the tracking of documents and records of advice. Access to information and keeping clients well-informed regarding their investments are part and parcel of technology’s role. However, without technology to complement, one might find things a little hard going as we drift deeper into the 4th Industrial Revolution.

    To overcome the industry’s technology disruption, financial planners must be nimbler to apprehend new technologies and employ them for innovation on existing solutions that are in great demand.

    For example, a few years back, the emergence of robo-advisor was regarded as a threat in the financial services sector. A robo-advisor is an automated platform running with a computer algorithm functioning to manage assets in investment. During that time, people were uncertain about the role future human advisors would fulfil as usage of robo-advisors gained traction.

    Threat Or Enabler?

    The COVID-19 pandemic is the most significant catalyst for digital transformation, and this change will lead to exciting insights into Islamic financial planning that will reshape its approaches. Technology can never entirely replace a human’s touch and skills.

    In years to come, both humans and technology are vital to serve clients better and modernise our financial planning profession. Technology exists to support, simplify, and create efficiency, instead of threatening the industry. Technology allows financial planners and clients to have a more engaging and meaningful advice conversations.

    A more robust framework of competency and consistent efforts for Islamic financial planners, including technical knowledge on the latest technology, would develop a more agile professional, who will safeguard the public’s interest, uphold the industry’s professionalism, and ultimately receive the rewards in the Hereafter.

    About the Author

    Dr Haji Shahizan Haji Md Noh is a licensed Islamic Financial Advisor (IFAR) for ASWA Advisory. He obtained his Doctor of Philosophy in Economics and Muamalat Administration from Universiti Sains Islam Malaysia (USIM). He also holds a Certified Qualification in Islamic Finance (CQIF) from IBFIM and Islamic Financial Planner (IFP) from the Financial Planning Association of Malaysia (FPAM). As an experienced practitioner, he has served numerous institutions in different aspects.