Category: business

  • The Importance Of Estate Planning, Avoid Last Rites Drama

    The Importance Of Estate Planning, Avoid Last Rites Drama

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. It can’t be emphasized enough on the importance of estate planning.

    The woman lunged forward, grabbed the hair of the man and screamed: “You influenced daddy to keep me out of the will!” That shattered the solemn atmosphere at the wake of the head of the family.

    What started with three sisters huddled together next to the casket listening to their brother-in-law holding court, turned chaotic. Their murmurs grew louder and louder as it turned into a heated argument.

    All eyes at the Funeral Parlour were now on the mourners. Daughter No 1, Cheng, held back by relatives from attacking her brother-in-law, continued berating the man. “I was in daddy’s will. He showed me…” she said in between sobs.

    Daughter No 2 countered for her shocked husband saying, “You deserve it! It’s all your own doing!”

    From a corner, a voice commanded: “Enough! We’ve not sent off daddy yet and you’re already fighting…”

    The voice trailed off. Tears streamed down her cheek as she watched unbelievably at how the family was starting to break apart.

    She was soon lost in her own thoughts as the altercation stopped. “Have we raised our children right?” she questioned herself.

    She looked at Cheng, who was now crying quietly. She was more of a problem among her three children. Probably being first born, and the apple of Daddy Hock’s eyes, she was spoilt. Her gambling habit and getting into debts were what got her father angry most of the time in the past one year.

    So, was disappointed Daddy Hock right in rewriting his will? Was Cheng right in saying Beng influenced Daddy Hock to leave her out of the will, she wondered.

    “Ah, that Beng, he likes to show off that he knows-it-all! How much of an influence did he have over my Hock?” her thoughts went racing. Out of the corner of her eye, she could see Beng smirking.

    She wondered why Hock ended up with making Beng the executor of his will and also letting Beng keep the will. The matriarch of the family was at a loss as to restoring the bonds between the daughters.

    This is crucial why we need to understand the importance of estate planning.

    The Importance Of Estate Planning

    This family drama at the wake highlighted several pertinent issues which are valuable pointers to note for in the importance of estate planning.

    Re-writing of Wills

    The Last Will and Testament is an important legal document giving clear instructions for wealth distribution.

    While the will can be re-written as many times as one wishes according to change in circumstances, it is nevertheless important that the document be kept private and confidential to avoid occurrences of tampering or being damaged and rendering the will invalid.

    In the case of Hock, he has divulged the contents to his Daughter No 1, giving rise to possibility of squabbles among family members even before he is gone.

    It is also prudent that the reading of the will be held at a conducive place and time. In the family drama above, Beng, a related party, who was appointed Executor and Custodian of the will, had – whether by design or coincidence – divulged the contents of the will at the wake. Stemming from this, things could get ugly.

    Executor

    Appointing the right Executor is crucial to ensure that the estate is administered professionally and efficiently to carry out the wishes of the deceased and avoid the bereaved family members and dependents having to deal with issues arising from the estate such as creditors chasing for payment and tedious administrative matters such as preparation of accounts and filing taxes.

    With the right Executor in place, the administration can be carried out efficiently where the beneficiaries would have fast and easy access to their inheritance.

    It is a common practice for testators to appoint, out of convenience, their spouses or children or trusted friends as executors to handle their estate administration. This is not wrong or prohibited but it could be counter-productive for the effective administration of the testator’s estate if the appointed executor is unfamiliar and inexperienced with the tasks at hand.

    A trust company is a recommended option as unlike the individual, the company will exist in perpetuity and has experienced and dedicated skilled staff with the time, capability and resources on hand to perform the function of the Executor.

    Custody

    It must be the borne in mind that equally as important in having a will is the safe custody of the will. A will that cannot be found is as good as not having a will. Safe custody from possibility of being tampered or damaged is also essential.

    Keeping the will in a Will Custody Centre is a recommended option to being in one’s locked cabinet or safe. Worse if the will is kept in a bank safe deposit box because it cannot be retrieved without probate, which cannot be obtained without the deposition of the will in court.

    A dedicated Will Custody Centre can ensure that the will is easily located and retrieved; is in safe storage in a humidity-controlled environment that ensures the document’s good condition over time; and is in secure vault with appropriate tight security system in place.

    It is hoped that we now understand the importance of estate planning and to avoid any last rites drama.

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.
  • Pre-Budget 2023: Expectations For A More Sustainable Tax

    Pre-Budget 2023: Expectations For A More Sustainable Tax

    The 2022 Budget was short on outlining any initiatives to enable Malaysia to build a more sustainable tax revenue base. The review of the tax incentives
    regime has yet to be finalised and hopefully, some progress will be announced in the coming Budget.

    We expect the 2023 Budget to outline a more structured mid to long term reform of the tax system, so that we can have a more sustainable tax system. Malaysia needs to, in the medium term, broaden the scope of the existing Sales and Service Tax (SST), and ultimately make it a broad-based
    consumption tax with added features such as tax invoicing similar to a Value-Added Tax.

    We should also have a more inclusive capital gains tax and move quickly on an efficient integrated national tax agency, in order to have a more sustainable tax.

    Tax Treatments To Review

    Currently, fees paid to tax advisers and company secretaries for the various services rendered on tax and corporate compliance matters are subject to restriction. Furthermore, the Inland Revenue Board of Malaysia (IRBM) recently issued the Corporate Tax Governance Framework (Framework) to enhance companies’ processes and governance on income tax matters.

    The Framework expects the involvement from the board of directors, audit committee and senior management to set up appropriate checks and balances on tax reporting.

    However, the IRBM states that costs incurred for advice and assistance to develop the Framework are considered to be capital in nature and therefore not tax deductible. This further irks businesses as such expenses are incurred to encourage corporate governance.

    For a more sustainable tax, another area to review is the exclusion of Intangible Assets from the definition of the term “Plant” in the 2021 Budget. This has resulted in cost incurred such as computer software, licences, trademarks, patents, films, copyrights etc are no longer eligible for capital allowances or tax depreciation, despite these being assets utilised in the production of taxable income.

    This is truly surprising, given the Government is leading the push from brick-and-mortar businesses to a digitalised and knowledge-intensive
    economy. Engagements have been held among various parties and it is hoped that in the upcoming Budget, the IRBM would review those tax treatments.

    A More Sustainable Tax Structure

    As a country, we cannot keep on borrowing and servicing debt. We should remove unnecessary exemptions and deductions, and simplify things
    to enable all to be part of the tax net. There is a need to push on towards a reliance on consumption taxes, in order to achieve a more sustainable tax.

    The Ministry of Finance (MOF) has stated in the Pre-Budget Statement in June that tax reform initiatives with the objective of broadening the
    tax base, as proposed by Tax Reform Committee, will continue to be implemented.

    The initiatives include:

    • a) Undertaking a review of broad-based incentives, reliefs and deductions
    • b) Improving tax administration through comprehensive registration of taxpayers
    • c) Better training of tax personnel
    • d) Improved registration of cross-border trade
    • e) Strengthening the tax audit and investigation
    • f) Enhancing legal certainty for taxpayers

    Necessary details on the aforementioned will need to be spelt out in the 2023 Budget.

    On the international front, Malaysia has committed to implement several agreed upon tax standards to create a competitive business environment for investors and to counteract cross-border tax evasion activities. To date, we have implemented four minimum standards of the Base Erosion and Profit Shifting (BEPS) Action Plans, while continuing to review the rest of the Action Plans under our domestic tax law.

    Domestically, the tax net can be widened by tracking down those who should be within the tax net. That means curtailing tax evasion, curtailing smuggling, registering those who should be registered as taxpayers, and devising strategies using the tonnes of data that various agencies
    accumulate to ensure that all who should be taxable are indeed taxed.

    In the Budget 2022, several initiatives were introduced to manage revenue leakages, including:

    • a) Removal of tax exemption on foreign-sourced income received in Malaysia by a Malaysian tax resident
    • b) Introduction of the Tax Compliance Certificate as a precondition for tenderers to participate in Government procurement
    • c) Implementation of a Tax Identification Number (TIN)

    It was a surprise when a five-year exemption of the tax on foreign income was announced subsequently. Even Singapore and Hong Kong, which have similar tax systems to Malaysia do not have such a time-based exemption period.

    However, the implementation of Tax Compliance Certificate and the TIN are very good compliance initiatives to reduce leakages, but more details are needed.

    In line with the 12th Malaysia Plan to strengthen digital services infrastructure, the digitalisation of the tax function will be implemented with e-Invoicing to be done in stages. This will enhance the efficiency of the country’s tax administration, reduce compliance costs to taxpayers, and
    increase the efficiency of business operations. E-Invoicing will also support the use of TIN as a measure to expand the income tax net.

    The Auditor General’s report has stated time and time again about losses and waste in the public sector. Greater accountability on where our tax ringgit goes and how it is utilised is essential to further narrow the trust deficit that exists, which is a factor why some are reluctant to pay their taxes.

    A more sustainable tax structure for the future is probably in the pipeline. But such matters can be excruciatingly slow in coming into fruition, due to the lack of political will and vested interests.

    All said, the 2023 Budget may turn out to be an election budget, with a slew of populist measures to score brownie points that may damage the country’s rather fragile fiscal momentum. Against this backdrop, debt and inevitably debt service charges, will rise.

    Given that Malaysia’s narrow tax base means high concentration revenue risk to the overall economy, its fiscal vulnerability could increasingly become a trigger factor for sovereign rating downgrades by international credit rating agencies. Here’s to a more sustainable tax structure for a better Malaysia.

    About the Author

    Dr Veerinderjeet Singh is a tax observer who is the Non-Executive Chairman of Tricor Malaysia. He is the Immediate Past President of the MIA and MICPA, and a Past President of CTIM. He is a strong advocate of tax reforms and sits on the boards of a few public entities. He is also an Adjunct Professor at Monash University Malaysia, as well as a Vice Chair of the Global Tax Commission at the International Chamber of Commerce based in Paris.

  • Fall of Family Business Empire, Why Family Business Fail?

    Fall of Family Business Empire, Why Family Business Fail?

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. With it, hope that we can understand more about why family business fail.

    It was unexpected for Jade. Her late husband, Chee’s family business empire had just fallen in the hands of others!

    How wrong Jade was with her assumption that when it came to the crunch, her late husband’s two partners would be sympathetic towards her. Instead they teamed up to make sure that not only she had no say in the business but also for her two estranged step-sons from her late husband’s first marriage.

    The two partners combined their equity holdings to ring-fence control and totally keep out the family of late founder Chee (Jade’s late husband) as they were worried and felt strongly that the ensuing family conflicts between Jade and her late husband’s family from his first marriage would be disruptive to the business.

    The partners had the advantage of the split equity holding of the Chee family members to stage a takeover of control of the business. Jade had never thought the partners would betray her as they were very supportive of founder Chee, and also empathised with her when they saw how terrible the step-sons treated her after their father passed on.

    The partners consoled Jade many times and offered to help in anything. She had the feeling that they would not be inclined to bring the step-sons into the business. She also reckoned that they would not be averse to appointing her as Director of the company so as to maintain the Chee family interest. However, all those so-called partners were fake. Eventually the partners took control of Chee’s family business empire and kicked her out.

    How Easily A Family Business Fail

    How could Jade’s late husband not foresee this? It became clear to Jade now that her late husband was good in running the business but he had failed miserably in ensuring continuity of the family business empire that he so capably built.

    While Jade’s late husband knew of Jade’s capabilities as a successor, he had not planned for it. He had not been communicative and shared with her anything to do with the business. He had been going about in the prime of his life as if he was immortal. And that probably was the reason why he didn’t even have a will!

    Only after the cruel blow of being killed in an accident following a drinking session with business associates that Jade found out that her late husband was actually not in control of things, especially his business empire. He was so ill prepared.

    Without a will, her late husband’s assets would, according to the intestacy law, be distributed to his parents, spouse and children. Effectively without surviving parents, his estate which included his majority shareholding in the family company is split between Jade and his two sons from the first marriage. That means not only his business but the house that Jade is staying is now co-owned by her step-sons too!

    But being on unfriendly terms, the fragmented shareholding of the Chee family members delegated them to be minority shareholders. By not combining their shareholding, they could not match, out-vote and block the combined controlling power of the two partners. What a tragedy!

    The Importance Of Succession Planning

    Proper succession planning would have ensured smooth continuity of management, control and ownership of a family business. If not, the chances for the family business fail will increase.

    It is prudent that succession planning starts as early as possible to avert a situation like the unwanted outcome of the Chee family business. Consult experts in estate planning to make sure a succession plan is achievable and will not have unforeseen pitfalls, even of tax and financial nature.

    A viable solution would be a Business Trust which creates a structure for family succession. Through instructions in the trust deed from the owner, the Business Trust can be designed to benefit the family members to ensure the continuity and preservation of the business within the family, even for those who are not on good terms with each other.

    Contentious issues such as successor -be it a family member or a business partner – and the delegation of powers could be pre-determined and stipulated in the Business Trust for the appointed Trustee, which is recommended to be a licensed trust company that operates in perpetuity, to carry out the instructions.

    Other relevant matters that could be addressed could include triggering event, for example, death, illness, incapacity or disappearance; or legal considerations that include exit arrangements or buy-sell arrangement of shares by other existing partners/shareholders from family shareholders; and also succession structure and process.

    With such proper estate planning that also encompasses protection of beneficiaries from unwarranted or future claims from creditors or ex-spouses, or takeover attempts by unfriendly parties, or even possibility of squandering of inheritance by beneficiaries, nothing is left to chance and the interest and future of one’s family business would be safeguarded.

    Such comprehensive estate planning solutions can be achieved by consulting an experienced estate planner working with an established company such as Rockwills Trustee Berhad.

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.

  • Financial Planning In The Crypto Age

    Financial Planning In The Crypto Age

    A very simple definition of Financial Planning is the process of managing our resources to help us achieve our life goals. Now that we are in the cryptocurrency age, how do embrace crypto in our financial planning?

    It is a process which we proactively look at our financial situation and determine the better routes which can allow us to use these resources to help us accomplish what we hope to have to call it a good life.

    Many people seem to think that when we have got a financial plan done, we have done financial planning, and hence we can then on our way to become richer, and retire early, or sending our children to study abroad.

    The truth is that financial planning is a process but not a touch-and-go activity that produces a document called financial plan. Life is full of changes, so any plan we make today will always be challenged or need to change in response to the actual situation in life.

    Financial Wreck Caused By The Pandemic

    For instance, no financial plan will have predicted COVID-19 and prepare everyone for the Movement Control Order (MCO) and all the consequences from having these shutdowns in the past two years.

    Our money is one of the resources we have that can be used to help us accomplish our goals, and money itself is not the goal.

    If our reason to invest in good deals or engage in financial planning conversation is to have more money, this reason itself invites more questions than being an answer.

    “More money for what?”

    “More money to do what?”

    “Why do you need to have more?”

    To have more, there’s a trade-off that we must accept.

    More Work = More Money = Less Rest

    For example, to earn more, one must work more, to work more, it could mean one has to let go of time for rest, or to not spend more time with loved ones, or not able to enjoy activities that they like.

    It could also means taking more risk so that we have a potential higher return from our investing activity.

    So, in our pursuit for more money, we may fare better if we adopt a big-picture view but not only focus on having more money.

    Sometimes, we decide to delay, or postpone doing things we really want or hope to because we are afraid to do it. And often, it is due to our feeling of afraid we don’ that enough to ‘just do it’, or the fear of “cannot afford to”.

    This is not abnormal, and I can totally understand this emotion. When we do not know how much we need for the rest of our life, how are we able to feel we have got enough, right?

    A good financial planning process is one where we spend more time to understand the person, identify the values (what’s important for this person), then take a look at their money management habit and their net worth (what they have left after minus what they owe), then we can have an idea if this person will have enough money for the rest of their life.

    What Are Your Life’s Goals?

    This process helps us understand a few important answers, such as:

    • Do I have to reduce my spending today?
    • Should I get a side hustle to boost up my income today?
    • Do I have to take more risk on my investment?
    • Can I change my car or house without affecting my future?
    • Can I quit the job I hate and accept a new job with lower pay?
    • At what age may have a huge cashflow deficit?
    • At what point (or age) will I run out of money in the future?
    • If I lose all my investment money today, how bad will my future looks like?

    Establishing a good financial planning process can help us to bring our future to the present, and by looking at this future we can assess what are the thing we do not like so that we can make the change to it today.

    Imagine having to wait for 20 years only to find out that we will still run out of money at a certain age, versus knowing this scenario is likely to happen 20 years earlier and we have 20 years of time to change something, which route would you prefer to take?

    Through proper financial planning, we get a ‘preview’ of our future today, but at the same time, we make some assumptions of what might happen, such as inflation, potential investment return, our spending and potential future income, taxes, etc.

    Hence, one of the things we will be thinking about is where or how should we allocate our money, to what kind of asset classes. And nowadays, it is likely most people have heard of and are quite keen to understand where cryptocurrency or crypto assets can fit into their plan.

    Dawn Of The Crypto Age

    Before the emergence of crypto assets, people have allocated their savings to various types of asset classes like stocks, debts, some keep most of their savings in cash or cash equivalent, businesses, real estates, arts, collectibles, gold or silver, to name a few.

    Some of the assets have a low risk and value tend to not fluctuate too much and are ‘predictable’, while some the value may deviate quite a lot, and are considered ‘risky’.

    One of the key considerations in determining our asset allocation, is to understand if we need the investment to generate additional income, or to have the value increase in future for us to have ‘gain’.

    Essentially, crypto assets are assets that are non-income generating but more for the investment objective for capital gain.

    While it is undeniable that crypto currency has helped make many new millionaires, for this wealth to be sustained into the future, one may want to explore how this new wealth can be protected or kept, so that even if the value of the asset class reverses its course, this person will not be knocked back to the ‘pre-crypto’ life.

    Of course, it is perfectly fine if we remain having our 100% of our wealth be invested in crypto assets. However, that will also mean we tie our future financial health and possibility in life to a single asset class.

    Imagine a person putting all their savings for old age to the stock of the single company they work at, and over the course of years for whatever reason, this company went out of business, or the company’s business dropped a lot due to new competition, or innovation.

    The above example is not just pure imagination, we have seen a few big company’s gone through such trajectory before. Will this person be better off ‘putting all the eggs in different basket’ instead of ‘in the only basket’?

    It does not matter what asset classes we are thinking about, it seems that it is not a bad idea to limit our downside risk and avoid over-concentration.

    What about people who have not experienced the explosive growth or have not invested in crypto assets before?

    Diversification Is Key

    Generally, crypto assets or digital assets are one new asset class for us to incorporate to our personal investment portfolio to achieve diversification beyond the common asset classes mentioned above.

    Depending on your tolerance for risk, and your investment objective, you will then understand how expose you can be, just like on every other asset classes. A person who is conservative or cannot sleep well even with a small up and down may want to limit exposure to volatile asset class, regarding the potential upside, and vice versa.

    For asset class that can have a large swing in value, non-income-generating, it is advisable that we limit our exposure and do not over commit our wealth to it.

    However, if one decides to do so, it will be prudent to ensure that we have prepare sufficient savings that can offer us liquidity and peace of mind during challenging time in life, or when the asset value is not at a good level for us to make withdrawal.

    It is also very important that people only invest into cryptocurrency via digital assets exchanges that are operated by operators approved by Securities Commission Malaysia [1]. This ensures your investment will not fall into schemes that are unregulated or hands of scammer.

    Regardless of what we do with our money, it is important that we understand why we want to do certain thing, and how this fit into the overall big picture of our life. By having a proper asset allocation that can support our future and lifestyle, we can avoid overexpose to certain asset classes, or certain asset.

    A good financial planning process is about setting a good foundation, and manage our risk, so that we can increase our chance of living a life we consider well lived.

    [1] https://www.sc.com.my/regulation/guidelines/recognizedmarkets/list-of-registered-digital-asset-exchanges

    About the Author

    kevin neoh

    Kevin works with people to transform their relationship with money and support them to use their money to live a meaningful life.

    He is a CFP professional, a certified member of Financial Planning Association Malaysia (FPAM). Kevin can be contacted at www.kevinneoh.my

  • Good Debt VS Bad Debt?

    Good Debt VS Bad Debt?

    Debt, in essence, is all about borrowing money from a third party, and having the means to pay it back. Debt is not always bad news; it really depends on the kind of debt you currently have and your ability to pay it back. Let’s take a closer look at ‘good debt vs bad debt’.

    Therefore, let’s start off with a self-assessment on debt. Referring to Table 1, kindly answer the statements with a “yes” or “no”. The more “no” in your replies, the higher your stress level in debt management.

    1My monthly loan servicing ratio over my monthly income is about 38% or below.
    2I am only investing my free money and never borrow to invest.
    3I have consistently (monthly) and/or fully paid my credit card debts.
    4I keep a track of my total debts annually and it is decreasing over the years.
    5I know the difference between good and bad debt, and only utilise the good debt to acquire appreciating assets like property.
    6I pay all my household bills on time.
    7I am current on all my debt payments.
    8I know who to look for help if any of my family members r I are in deep debt.
    9I know the risks of becoming a guarantor, co-loan owner and supplementary credit card owner.
    10I know the interest rate of each loan that I borrowed, and how the interest is charged on the loan amount.
    11I know how to restructure my debt wisely if needed, and clear the loan with the highest interest rate first.
    Table 1: Self-Assessment

    Good Devt VS Bad Debt?

    Did you know that debts can be categorised as “good” or “bad”? Good debts refer to the ones with low-interest rates (below 8%), and your borrowing is used to purchase appreciating assets such as residential or commercial properties, or investing in a business.

    A study on Malaysian property valuation between 1991 and 2014 showed that the compound annual growth rate (CAGR) for overall property in Malaysia is around 5.97%。No doubt that property is an appreciating asset, still location is key for greater return.

    Bad debt, on the other hand, is akin to borrowing money to buy a car, which is a depreciating asset, although the loan interest rate is considerably not high (around 4-6%). Every year, the car value will drop at an average of 10%.

    From Table 2, it is crystal clear that we shouldn’t borrow if the interest rate is more than 8%.

    Debt TypeAverage Interest Rate (Annual)
    Illegal Shark Loan60%
    Credit Card15-18%
    Personal Loan10-12% (Promotional 8.88%-9.99%)
    Education Loan8-10%
    House Loan4.5-6.5%
    Car Loan4-6%
    PTPTN1% (3% is the old rate)
    Table 2: Types of Debt and Average Interest Rate (Annually)

    Words Of Advice

    Healthy Debt Ratio – A key indicator on whether you have a healthy debt ratio is the Monthly Debt Servicing Over Monthly Income Ratio. It simply totals up your monthly debt repayment amount over your monthly income.

    This ratio should always be kept below 40% at all times, though a temporary spike is still acceptable. For those far below 40%, you have more room to gear on appreciating assets resulting in easier loan approvals.

    Never Borrow to Invest – The first rule of financial planning is not borrowing to invest, even in share margin investment, where the interest rate is low at about 4%.

    We should only invest free money. Don’t borrow money even from family members, relatives or friends to invest. Otherwise, it could cost you both money and relationship.

    Get the Longest Loan Period (if possible) – Forget affordability, will you apply for a 25-year loan (instalment: RM2,400) or 35-year loan (instalment: RM1,200) for a property purchase?

    Choosing 35 is a wiser strategy to deal with loan and cash flow. Even if you opt to pay RM2,400 (instead of RM1,200) monthly and consistently, the loan will end in 25 years.

    However, if you select the 25-year package, there is no way you can reduce your monthly repayment if you have cash flow problems in certain months.

    In the event you don’t pay consistently, banks will increase the interest rate causing the repayment amount to rise, lesser free cash in hand, and a whole lot more stress!

    If non-repayment continues for two months or more, you will be seen as failing to service your home loan, and worse, the bank might even auction your house. Therefore, why risk your financial position with a shorter period of loan which offers lesser flexibility?

    The longer the tenure of your home loan, you would have more cash in hand to actively invest into an investment instrument that can give you an annual return of more than 6%. This is smart financial planning.

    About the Author

    This article is written by Yong Chu Eu. He is the Founder, Principal, MFPC Shariah RFP, CPD/CPE, HRDF Certified Corporate Trainer of Money & Life, Financial Book Author, Licensed Financial Planner, E2E Financial Literacy Principal Coach & Local Media Guest.

  • Fighting Over Equity Distribution, The Importance Of Succession Planning

    Fighting Over Equity Distribution, The Importance Of Succession Planning

    The following story is based on an actual series of events with some names and circumstances fictionalised and any similarity to the name, character or history of any person is entirely coincidental and unintentional. Hopefully we can understand the importance of succession planning and make the necessary preparation.

    Elder Tan put down his chopsticks, looked up and smiled.

    His three sons and their spouses are seated together once again for a reunion dinner which the COVID-19 pandemic denied the family for two consecutive years. In the next table, the children are noisily tucking in their food and chattering away as well as occasionally peering into each other’s phones.

    Tan was a picture of contentment. He has raised his children well to be successful in their own right. He is proud of his eldest son Seong who is doing a good job taking charge of the hardware business that Tan had built from scratch. Danny, the No 2, is head of the engineering department in a construction firm while Chye, his street smart youngest son, is doing well in sales in his father-in-law’s spare parts company.

    “I want to tell all of you something…” Elder Tan interrupted the conversations at the reunion gathering.”

    Succession Planning Is About Being Prepared

    I want to retire and leave the family business to Seong,” he added. Seong looked at his father, beaming that he is getting just rewards for the hardwork that he had put in to run the business.

    “I’ll transfer the shares of the company to all three of you equally,” Tan said looking at his three sons. The expression in Seong changed on hearing that. He looked startled as he had expected the lion share for all his sweat, literally!

    “Equally with Danny and Chye! They didn’t lift a finger to help out in the business! And they now get equal share of the fruits of my toil? No way!!!” Seong now getting red faced with anger.

    He rose from his seat and smart-mouth Chye stopped him in his tracks with his remark: “What, you’re not happy?”

    The whole atmosphere changed as Seong lunged towards Chye. Danny stepped in between and after that, chaos broke out. A breakdown in family harmony over too-soon, unforeseen, unexpected equitable or inequitable distribution of family assets?

    Tan’s desire to be fair and thus, the equitable distribution of equity in the family business probably blindsided him from the possibility of a family feud erupting from it. Estate planning and succession planning needs to be skillfully handled and prudently managed to avert any unwarranted situation such as a family feud.

    Succession planning inevitably is critical for business, especially family-owned business. Business owners tend to underestimate and downplay its importance, ignoring possible downsides when they are no longer in charge. It holds true that failing to plan is planning to fail.

    A pre-planned succession such as through a Family Business Trust or a Family Foundation would be a prudent way to lay down instructions on conditions for ownership succession, management succession and rewards and conveyed impartially and professionally by an independent third-party such as a trustee would avert family feuds over inheritance.

    Three key areas need to be considered in setting up a business succession plan namely:

    • Ownership Succession. This will ensure that the shares of the family business will be protected and not likely to be fragmented over generations. The rightful heirs are clearly defined, thus enabling ring fencing against outsiders to own the family business
    • Management Succession. Successor is crucial for continuity of the family business. By having a capable candidate to be successor of the family business, it retains the goodwill of the family business and it improves the confidence of the investors, customers, and employees
    • Family Wealth Management. Proper planning and allocation of family resources effectively will maximise the benefit for each of the family members, such as in areas of financing family education, family medical and family reserves needs

    Business succession planning is an essential part of the risk planning for the business.

    About Rockwills International Group

    Rockwills International Group, now in its 27th year, pioneered professional will writing in 1995 and has since evolved into the leading estate planning specialist in the country. It is today the largest provider of solutions and support services in the areas of trusts, succession, management and distribution of wealth. It has shareholders’ funds exceeding RM50 million. It has done over 280,000 wills and 15,000 trusts and hold more than RM25 billion in assets under trust.

  • How Can A Licensed Financial Adviser Help You?

    How Can A Licensed Financial Adviser Help You?

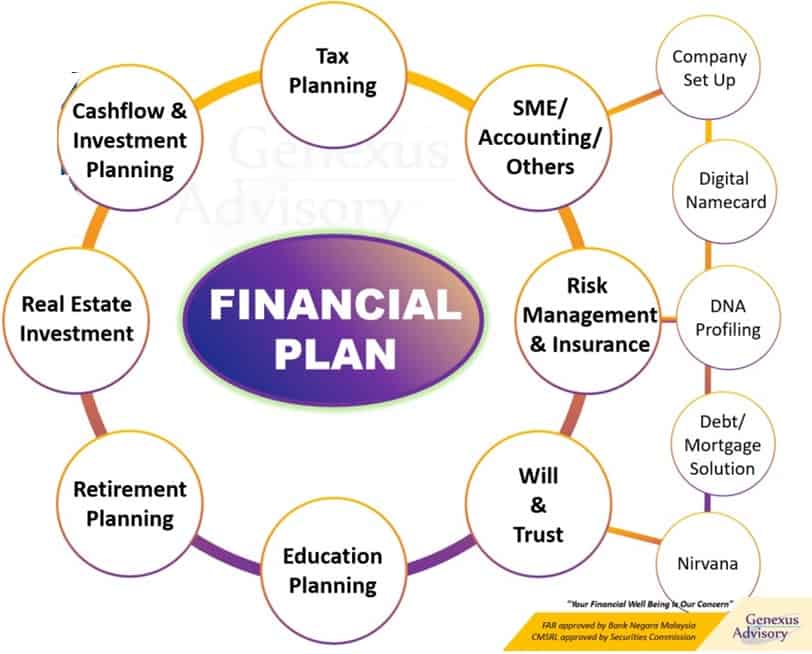
    Many people are always wondering what or who a “Licensed Financial Adviser”(LFA)” or a Financial Adviser’s Representative (FAR) is. Also, many do not understand what is a “Financial Plan”.

    Did you know that there’s only about 1,300 financial adviser in Malaysia, versus our population of 32 million?

    When their numbers are small and very little is known about them, surely a lot of myth and misconception that happens.

    How Can A Financial Adviser Help?

    Why do anybody need a financial adviser while we already have banks, insurance agents, unit trust consultants, estate planners, lawyers and accountants? What resources or values that an LFA/FAR could assist or deliver impact into their life?

    Most Malaysians have the impression that an LFA/FAR is “not focused” or “unprofessional” because he or she is able to provide financial services from multiple providers. For us Financial Advisers, financial providers are our resources and financial tools which are suggested to solve different individual or corporate needs.

    To clarify this misunderstanding, a Licensed Financial Adviser DOES NOT represent any company or financial providers. They represent you.

    All advice and solutions are solely based on your needs, and they will look into the financial market for the best financial tool to suit your life goals.

    Usually we are too busy earning money with our job or business, or too busy with family, that we barely have time to deal with their financial planning. People who are too busy making money for them to make a living, paying off debts and liabilities, is hardly able to get the latest investment updates, market outlook, insurance plans and taxes.

    Due to the lack of financial literacy and knowledge, many have become the victim of ponzi schemes or get-rich-quick schemes. This resulted in many Malaysians losing their wealth.

    Some went into huge debts, by applying personal loans, credit card cash outs, or even loan sharks and ended up a bankrupt. This is one of the reasons why bankruptcy statistics increase gradually every year. It is human nature to take risk and gamble, but why gamble when a Licensed Financial Adviser can help you better manage your finances and investments?

    Most of us gets mixed up with “investment” and “gambling”. Many Malaysians thought that investing in high-risk instruments like stocks, forex, crypto or private equities are similar to gambling. Whereas gambling is purely based on luck or a probability of winning chance.

    A good investment is when you have the knowledge and understand clearly about the instrument along with the risks and rewards. You can predict the results, whether it is an instrument that comes with low risk with low return, or high risk with high potential return. Also the time frame and financial goal or purpose of a particular investment.

    What’s even more important is to make sure that it is being regulated by by Bank Negara Malaysia, Securities Commissions Malaysia or Bursa Malaysia.

    A wise man once said, “Fast is actually slow. Slow is actually fast.” Deep thoughts, deep wisdom.

    A Licensed Financial Adviser is specialising in the Finance industry. They are well-trained professionals that are focused on Financial Planning. To deliver value to your family and businesses, solely based on your needs in order to achieve your life goals.

    Don’t wait no more, get in touch with a licensed financial adviser today.

    About the Author:

    Cheong Kwang Siang, CFP Cert TM
    FAR, CMSRL
    Genexus Advisory Sdn Bhd
    He can be contacted at cheongks@genexus.com.my

  • 3 Most Popular E-Wallet in Malaysia

    3 Most Popular E-Wallet in Malaysia

    An e-wallet or also known as digital wallet, is an electronic device, online service, or software program that allows one party to make electronic transactions with another party for buying goods and services. With the rise of smartphone usage, so does the popularity of e-wallet in Malaysia.

    Let’s check out the 3 most popular 3 e-wallet in Malaysia.

    Boost

    • Backed by Axiata Group
    • One of the pioneers in the Malaysian e-wallet market
    • Accepted at any UnionPay QR merchants
    • BoostUp Reward Programme and CashUp Cashback Programme

    GrabPay

    • Backed by Grab
    • Leverages the Grab Ecosystem for GrabFood, GrabRide and other provided services
    • Partnership with Maybank for cross platform use
    • Earn GrabRewards Points from every transaction

    Touch ‘n Go e-Wallet

    • Backed by Alipay and Touch ‘n Go
    • Taps into the large existing user base of Touch ‘n Go cards
    • PayDirect: link your Touch ‘n Go Card and pay toll fare directly with your e-wallet balance at participating highways
    • Money-back guarantee: full refund within five working days if your e-wallet is charged erroneously

    Each e-wallet in Malaysia comes with its own uniqueness. You should look at which is more convenient and brings the most benefits to you as a user.

    In terms of benefits, here’s what you can expect from the 3 e-wallet in Malaysia as per below:

    1. Convenience And Safety

    What is the first thing you take when you head out? Your wallet or phone? Frankly speaking, I will often forget my wallet, but never my phone. We heavily rely on smartphones today and with the high adoption of e-wallets among merchants, we can easily make payments without cash on hand. Besides, I think everyone has faced the awkward situation of having to squeeze the notes and “syiling” back into your wallet after receiving your change. With an e-wallet, problem solved!

    The safety of digital payments is also a concern for some, but data in the e-wallets are encrypted and some providers even provide money back guarantee features to ensure the safety of using their services. It can be also argued that e-wallets have helped to reduce theft cases, which usually occurs with physical cash!

    2. Spending Tracker

    Do you always get shocked when checking your bank balance? Clueless on where the money has gone? You can easily check your e-wallet where all transactions made are recorded. Gone are the days of forgetting where you spent your money. Keeping track of your daily spending is crucial to cultivating good financial habits. This provides an overview of your spending patterns and insight as to where you could improve.

    3. Promotions And Rewards

    While having many e-wallets has been confusing for some, the war to acquire users has been beneficial for us consumers. All e-wallets offer their own rewards, and it’s up to you to make the most of it:

    • Boost allows you to earn BoostUp coins with every transaction and exchange for gifts
    • GrabRewards Points comes with an extendable validity feature which technically makes it technically a “never expiring” points system (every point-earning transaction will extend the expiry date of your GrabRewards points till the last day of the 3rd month)
    • Touch n’ Go e-wallet rewards frequent user with cashback vouchers for selected merchants 

    All the e-wallet players partner with various merchants to provide attractive promotions to users in a bid to increase their market share. So look out for where you can save and earn through regular activities like refueling your car, buying groceries or even reloading your mobile credit. But please don’t use these promotions as an excuse to spend more than you need to!

    4. Private Assistant

    Paying your utility bills? Use e-wallet!

    Topping up your mobile credit? Use e-wallet!

    Sending money to your spouse? Use e-wallet!

    The utility of e-wallets is increasing by the day, and are no longer just avenues for sending or receiving money. Many can be used to pay for your parking, buy insurance, settling utility bills and more! There will be definitely more that an e-wallet can do in the near future.

    About the Author

    Ocean Pon is a Licensed Financial Planner and likes to help millennials make wiser financial decisions to achieve financial independence. He can be contacted at oceanpon@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth

  • Banking For Expats In Malaysia, 6 Things You Should Know

    Banking For Expats In Malaysia, 6 Things You Should Know

    It has become increasingly difficult to move money anywhere around the world, and it is set to get tougher. Fraud, cyber security, tax and compliance procedures, amongst other rising trends, are creating obstacles. Traditional banks are being marginalised by digital transformation in banking and non-banking sectors, with the ease of moving money around with crypto wallets, in Malaysia, and worldwide being a prime example.

    So, if you are an expatriate in Malaysia, or thinking of moving to Malaysia, you may be left wondering what’s the best option for banking.

    Let’s check out banking for expats in Malaysia.

    1. Setting Up A Bank Account

    Abstract blur and defocused hotel lobby interior for background

    Opening a bank account as an expatriate in Malaysia is straightforward and fast, if you have the relevant paperwork. If you do not then it is not possible. If you are employed in Malaysia, then you will be able to open a bank account at a local Malaysian, or international, bank.

    If you are not employed in Malaysia but own a residential property, then you should also be able to open a bank account. If you are considering starting up your own company in Malaysia then it is best to check that it will be possible to open a corporate bank account in Malaysia before you take the time and expense to establish a legal identity.

    Due diligence on several aspects of opening a company should be done in Malaysia, and in any other Asian countries, before you decide to proceed. You may find that it is possible to open a company but not possible to open a corporate bank account in Malaysia, or elsewhere. Check before you get started on the incorporation to avoid wasted effort and expenses.

    2. Banking For Expats: Multi-Currencies

    Caution should be exercised when you open a multi-currency account in Malaysia, or anywhere in the world. You may find that, despite having a choice of accounts to keep your hard-earned currencies in, when you transfer foreign currency from abroad your bank in Malaysia will convert all currencies into Malaysian Ringgit initially.

    This is fine if you intend to spend most of your money in Malaysia, but if you want to hedge against currency volatility then you may lose out on any initial transfer on the exchange rate and on currency risk.

    3. Digital Wallets

    ebelia rm300 million e-wallet credit

    Digital wallets are hot. They are useful too. If you have not already tried using one, or more, digital wallets, then what is stopping you exploring? There are currently over 40 similar providers but this space is likely to reduce to a few niche players in the future.

    The Covid-19 pandemic has accelerated the adoption of e-money payments in Malaysia, and globally, with transaction value crossing RM30 billion (between January and September so far in 2021, according to data from Bank Negara Malaysia.*

    Points earned from spending through your e-wallet may be going to waste and if you look at the amount of money you, and your family, will save in a whole year using e-wallets then this may be a good motivator. E-wallets also mean you do not have to handle cash for shopping and small purchases.

    Read: What are The Many Benefits of E-Wallets in Malaysia?

    4. Fraud And Cyber Attacks

    The two major security issues a local or an expatriate faces with their bank account in Malaysia, or anywhere in the world, are fraud and cyber risks. Malaysia is reportedly a leader in cyber security amongst Asian countries. Does this really mean your bank account is safer in Malaysia than somewhere else?

    Reportedly, Malaysia leverages policy capacity with a broad network of international intelligence alliances to rate highly in the cyber-power rankings. Malaysia came in fifth out of 194 states in the 2020 Global Cybersecurity Index constructed by the International Telecoms Union, a United Nations agency.

    With 98.06 out of a possible 100 points, Malaysia was only fractionally behind Singapore and South Korea, and equal with Russia and the United Arab Emirates. It has been in the top 10 since the first report was released in 2014. However, the best way for you, and your family to prevent losses through cyber attacks is to be vigilant when banking online.

    5. Benefits Of Domestic And Overseas Credit Cards

    credit card 101 rules

    Cashback is one benefit of shopping with a local Malaysian credit card. If you are an expatriate and want to make the most of your earnings in Malaysian Ringgit then it is probably a good idea to spend most of what you earn in Malaysia. From time to time, a few countries may not allow you to exchange your hard-earned Malaysian Ringgit for foreign currency when you travel overseas, or the exchange rate may be unfavourable.

    If you are sending Malaysian Ringgit savings back home, or to an overseas investment, then you may also be caught by a dip in the value of the Malaysian Ringgit. Remember, it is usually best to have more than one credit card just in case there are simultaneous cyber and fraud attacks on both your credit cards at the same time, leaving you stranded overseas without means to pay for a night out or accommodation.

    Some international credit cards offer no international currency charges, as well as favourable exchange rates, so take a look around at what is on offer. You may find that using an overseas credit card in Malaysia is low on cost and favourable on exchange rates.

    Read: How Credit Card Works in Malaysia: Credit Card 101-Know the Rules Before Playing The Game

    6. Money Transfers

    Most banks around the world now require that you give a reason for any money transfer from your own bank account to a third party. Any bank transfers of a substantial sum must be investigated by the bank and a report made to the central bank, Bank Negara.

    You can save yourself time, money and stress by making money transfers of small amounts, less than US$10,000 or foreign currency equivalent, if you want to avoid unnecessary hassle. Some crypto currency wallets do not require you to state a reason for your money transfer and, if you have not already tried, you may be interested to transfer funds around the world using cryptocurrencies.

    It is not as difficult as you may think with many transfers simply requiring you to cut and paste an ‘address’ into their portal, then press send.

    A lot of wasted time and money is not down to banks, it is down to you. Becoming more aware of the benefits of non-bank and digital banking options, and their associated risks, could save you pennies or earn you pounds.

    So there you have it, the available options on banking for expats in Malaysia.

    About the Author

    Dr. Jonathan Di Rollo (PhD Econ) has been actively and passively investing in Asian markets for more than 20 years.

  • The New Heir: Managing Your Inheritance

    The New Heir: Managing Your Inheritance

    Managing an inheritance can be life-changing and for many people, as it can open up many new possibilities. The biggest question one would probably face, therefore, is how your new inheritance should be managed to benefit you the most.

    Whether wealth management is something that you are familiar with or whether your inheritance suddenly puts you in an entirely new financial situation, receiving a substantial amount of money or a property can be overwhelming if you don’t know what to do with it.

    With that in mind, Smart Investor spoke with experts to give you a clearer understanding on managing your inheritance.

    Set Up a Trust

    Azhar Iskandar Hew, Group Chief Executive Officer of Rockwills Trustee Berhad

    If your inheritance comes in the form of cash or property, the best way to handle an inheritance from the perspective of the heir, would be to cooperate with the executor or trustee on obtaining details required for probate application and to track the progress of the estate.

    Upon receiving the inheritance and if the inheritance comes in the form of cash, one option is to set up a trust with a professional trust company. You then execute a trust deed in which the terms for the use of the cash can be clearly written down.

    At the same time, the heir can also mention who should inherit the cash and how it is to be distributed, should anything happen to him. This way, the heir or settlor of the trust would have control over the distribution or usage of the cash.

    Some of the main instructions in the trust can include directing the trustee to pay for the settlor’s maintenance, medical bills, children’s education and family’s living expenses on a regular basis. By doing so, the money will not be given to anyone in one lump sum which can be wrongly invested or misused.

    Of course, another advantage of a trust is that unauthorised persons will not be able to touch the cash, as only the named beneficiaries can receive the money.

    It’s All About Priorities

    inheritance

    Kenney Khew, CFP
    Philip Wealth Planners

    Upon receiving your inheritance, you should first of all, list down all your financial goals and prioritise them according to your preferences.

    Put aside an amount (at least 6 months of your gross salary) into an Emergency Fund. This is recommended, as you would then have money to fall back on in the event of an urgent matter that is out of your control.

    With the cash you should also pay off your debts, including your credit card debts, outstanding housing loan, car loan, student loan and any other personal loans.

    It is also recommended that you put aside an amount of money for your children’s education fund according to the calculations made based on future values of tuition, transportation, living, and course fees. In this case, you must also take into consideration the inflation, as well as exchange rates.

    Be sure to also purchase a term life insurance of up to 80 years old. The rule of thumb is for the sum insured to be 10 times your annual income. A medical insurance plan is also important in this context. By doing so, you will be able to protect your assets against mishaps as to not affect your future plans.

    The remaining money can further be used to invest in properties. You can rent out these properties to earn extra income and what’s more, this is a form of passive income that would benefit you in your golden years.

    I Just Inherited a Property – Now What?

    inheritance

    Gor Sheau Shuenn, CFP
    Blueprint Planning

    If you’re lucky enough to receive an inheritance, you should consider what the assets are and how much you will be receiving. If cash is the legacy you’ve received, it should be invested in a proper mixture of different portfolios, as otherwise, liquid assets are bound to be spent too frivolously.

    However, if the inheritance you will receive comes in the form of a property, there are a few factors that need to be considered:

    1. Has the mortgage of the property been paid off in full; if not, what is the loan repayment amount?
    2. Is the property currently being rented out? If so, is the rental yield positive?
    3. What are the appreciation possibilities of the property in the future?
    4. Who is going to manage the property, and will the return be able to cover the maintenance cost?             

    If all answers to the above questions point to a resounding ‘yes’, the property will be all the more attractive as you will receive rental income and capital gain for the disposal of the property.

    At the end of the day, it doesn’t really matter whether the legacy you’d inherited comes in the form of cash or property. All that matters is how the legacy can assist you in shortening the period of time you will need to achieve your financial goals.

    The Financial Planning Factor

    inheritance

    Kevin K.M. Neoh, CFP CERT TM
    MBA, VKA Wealth Planners Sdn Bhd

    It is perfectly normal to do nothing while you consider what to do with your inheritance. Ride out the emotional period and contemplate what you hope to achieve from this fund or inheritance with a clear mind to avoid mishandling or making poor decisions. Even if it means waiting for a couple of years as you do some soul-searching, go for it.

    Should you be the sole beneficiary of this inheritance, why not consider investing or managing it based on your financial plan, or in a manner that will support your life goals and values? Proper management and budgeting is important to ensure that the windfall will not be squandered unnecessarily.

    While you sit on your inheritance, it is also important to note that inflation will erode the purchasing power. Therefore, the need to find an instrument that can yield at least above inflation rate is important because it tends to shield the inheritance from being eroded by inflation.

    Don’t change your plan or your spending habits just because you have received an inheritance. In fact, try to use this as an added advantage to help you realise your life and financial goals.

    Making the Most of Your Inheritance Money

    inheritance

    Yong Chu Eu, FAR, CMSRL, CFP®, Shariah RFP
    Founder, managing director and principal trainer of Money & Life Academy

    Your inheritance can be divided into 3 parts:

    a) Untouched – This portion of your inheritance money can be put into liquid investments (property, insurance, PRS or EPF) and locked down

    b) Investment – Done according to your risk profile and availability of knowledge and time. You can also purchase stocks or unit trusts with the purpose of growing the money, or use it to start a business in a field that you are passionate about

    c) Spend – upgrade your lifestyle with comfort, quality and safety in mind, further your studies, clear off your debts, travel, or give back to the community