Having an early, secure retirement is a dream of many, and a small, but growing number of people are striving to turn this dream into reality. The FIRE movement, acronym for Financial Independence, Retire Early, is essentially about aggressively tightening belts, and finding multiple sources of income in order to achieve early financial freedom.
Milieu Insight released the results of their ‘Financial Independent, Retire Early’ study, which aimed to find out how common the FIRE movement is among Southeast Asians, and the steps they are taking to achieve their goal. The survey was conducted in May 2022 with N=1500 employed respondents, aged 18-49 years old, each from Thailand, Singapore, Malaysia, Indonesia, and the Philippines.
Do Southeast Asians want early retirement?
The bulk of respondents expect to retire in their 50s or 60s (62%); Indonesians tend to expect earlier retirement, with only 52% expecting to retire in their 50s or 60s
Retiring early (defined as retiring before 50s) is a possibility for 60% of respondents, but only 14% think that they are on track for early retirement – Singaporeans seem most pessimistic about being able to do so, with only 9% indicating that they are on track
Steps towards early retirement
Most common strategy towards early retirement is regular saving (71%), followed by ‘being careful with how I spend my money’ (63%) and ‘investing’ (63%).
Finding additional employment is much less common (37%) as part of strategy to retire early, but tends to skew towards Thais (54%)
Insurance – one way of investing – is also more common among Singaporeans (56%) and Filipinos (53%)
Perhaps due to vast amount of resources on the Internet, most people are hands-on for retirement planning, with only 31% of those who plan to retire early saying that they have a financial consultant to help plan for retirement
A look at the most common strategies for early retirement: Saving and investing
Among those who save regularly for early retirement, 43% save more than 20% of their incomes
Among those who invest, 36% indicated that more than 20% of their incomes go towards investments
The most common investment types are:
Investment funds (56%)
Stocks (53%)
Real estate (52%)
Cryptocurrency and NFTs, which are gaining momentum but have yet to enter mainstream investing due to their volatility, registers at 41%, and seem to be more popular in Thailand (57%) and the Philippines (54%)
How do people feel about FIRE?
57% feel very or somewhat positive about their journey towards achieving early retirement
Comparing those who are on track to early retirement, and those who are planning to retire early but don’t think they are able to, the former tends to feel more positive about it (83% vs 49% who selected very/somewhat positive)
Methodology
Based on Milieu Insight surveys with N=1500 employed respondents, aged 18-49 years old, each from Thailand, Singapore, Malaysia, Indonesia, and the Philippines, conducted in May 2022.
About Milieu Insight
Milieu Insight is a consumer data and analytics company that connects businesses directly with their target audience. Milieu’s platform offers businesses a wide range of tools for accessing, analyzing, and visualizing high-value and timely consumer opinion data to help power better decision-making and strategy. For more information about Milieu Insight visit: www.mili.eu
Are you worried about your teenage children’s safety, health, social life, future, and education? In addition, they are constantly bombarded by advertisements, online shopping, peer pressure and “Instagram culture”.
Various surveys have shown that Malaysian millennials (aged from mid-20s to 40) have a tough time when it comes to money management:
70% of Malaysian millennials do not live within their means – Asian Institute of Finance, 2015
74% of millennials in Malaysia are struggling to meet day-to-day expenses during the Covid-19 pandemic
53% of Malaysian millennials cannot survive with their savings beyond three months
Lower income millennials spend 48% on food, 27% on entertainment
Looking at the situation above, we should plan forward and ensure that the next generation – our teenagers – will have a better start in money management. Here are three alternative ways parents can teach their teenagers about money management.
1. Joining Them Instead Of Stopping Them
Online shopping has enabled spending like never before, especially during the pandemic. Most teenagers will want to buy and own things if they have the means, although more often than not, such purchases are due to peer influences.
Being the financial provider for teenage children, it is important that as parents, we instill the importance of self-control and wisdom about leisure shopping. Yet, this is the phase where teenagers become more rebellious, it is simply not enough to just tell or nag them. The old saying has never been truer – “If you cannot beat them, join them”.
Go on Shopee or Lazada with them. Teach them about vouchers, free shipping and sales. Or maybe it will be them teaching you instead! Shopping online with them has its benefits, such as:
Bonding time and relationship building with your child
Slotting in some advice about quality vs quantity, self-control and impulsive buying behaviour
Monitor your teenagers’ shopping behaviour, what is in their shopping cart, wishlist and their shopping history
Share your experience and mistakes about shopping and spending
2. Give Praise And Advice
It is so true, that it must be repeated again. Teenagers are rebellious creatures!
Nagging and telling them what to do just will not cut it. It did not work for teenagers during the 80s, 90s, and 2,000s and it certainly will not work today. However, they do seek your approval and appreciation, especially on things of importance to them. We often hear “my parents do not understand me” or “my parents are just not cool”. One way to avoid such comments are to acknowledge and sometimes praise what they are doing right (or vaguely right) financially.
“Boy, it looks like you did not spend too much money at the mall today. Good job!”
“Girl, you really found a real bargain with the dress you bought online. You certainly know how to shop.”
After praise is given, teenagers will be more receptive towards advice. The acknowledgement that they did something right, gives them a sense of pride, and the urge to do it better.
3. Let Them Make Mistakes
If you recall how you sharpened your money management skills, more often than not, it was not taught or told by your own parents. You learnt them either by experience, hardships, or through mistakes that you have made. Depending on your generation, we grew up in a different time and culture than the teenagers of today.
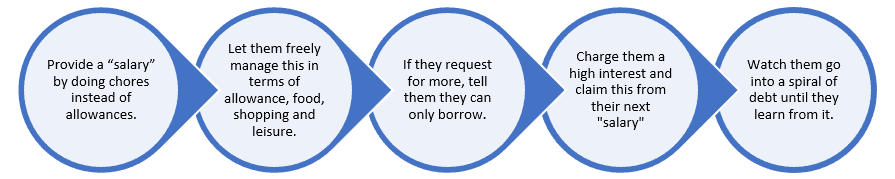
One way that we can teach our teenage children about money management is not by teaching or telling, but by letting them experience mistakes of their own. Here are ways you can set the stage for your teenagers to learn some money management:
The salary and lending method
The delayed gratification lesson
We are spoilt with instant gratification. What we want, we can get it very fast, if not, almost instantly. Think Netflix (movies), Grab (food/transport), Shopee/Lazada (shopping) and WhatsApp (communication). The Generation-Z of today are born into a life of instant gratification. However, the culture of savings and investments are more often than not, a slow and disciplined process.
Thus, it is even more crucial that parents practice delayed gratification with teenagers and resist buying things they want versus what they really need. For example, if they ask you to buy something they want (big or small), try and ask them to wait for a few weeks or months. Suggest that if they want it sooner, they have to contribute part of the cost too. You may even notice a change that as time passes, they will realise that the purchase is not worth their allowance, and their desire may even fade.
The compounding interest lesson
Open a bank account for your teenager with some sort of interest element and allocate your teenager’s allowance in it. Alternatively, some e-wallets currently have an interest element as well. This allows them to learn about the compounding effect of interest on interest.
With this method, you can teach them about saving their allowances, and watch their savings grow every month. Take this opportunity to teach them about inflation and other forms of investments that can make their savings grow even faster, such as fixed deposit or a bond fund. Although they are too young to invest into unit trusts themselves as a primary applicant, you can create a joint unit trust account with your teenager being the secondary account holder.
As parents, we do our best to teach our child the important elements in life. Early money management is something that is important and should be deeply rooted into their young minds. However, this is easier said than done as there is only so much we can do as parents.
Their personalities and spending patterns are an amalgamation of a variety of influences, from friends, to TV, to the internet and also by observing their parents’ money behaviour. That said, as parents, we should learn and practice what we preach about healthy money management.
About the Author
Alvin Kwan, CFP CERT TM is the executive director and head of financial planning at Redvest Wealth & Asset Management. He has over 12 years industrial experience in the financial industry, specifically in wealth advisory, private banking and stock broking. He was also a lecturer in areas of investment management, derivatives, and financial markets.
We at Smart Investor and Redvest is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxRedvest
Wealth preservation is about managing your assets in such a way to make sure that it does not decrease in value. And after a lifetime of hard work, you want to ensure that as much of your wealth is protected.
Of course, optimising and growing your existing wealth is also a key task unless you plan to work for money all the time.
Wealth, just like your health, must be carefully preserved, and successful planning will help make your wealth last for you and your future generations – in case the unexpected happens.
One of the means that we can ensure our wealth is preserved in case something happens to us is insurance.
Demand for insurance as a low risk wealth management tool has seen a spike in recent years. The approach to insurance is also changing, with people from the middle-income group to wealthy families shifting perceptions on the need to protect their potential future income, as well as preserving their wealth for their next of kin.
When you read that insurance is a good instrument to preserve wealth, what exactly can it help you preserve?
Preserving Your Current And Future Income
The Covid-19 pandemic has made a strong case on the notion that nobody really knows what is coming around the corner.
Just imagine that if you pass away during your good earning years, your family could suffer a severe economic loss as a result of losing your current and future income to support them. In this unfortunate ‘fictional scenario’, your family would still have to pay their regular bills, including mortgage(s) and your outstanding debts.
They will also still have to continue accumulate funds for your family life goals, such as children’s education and retirement funds for your spouse. If you did not insure against this, you may leave your spouse or children in a very tight spot.
Preserving Your Dreams / Life Goals
For some people, this is also as good as preserving your family dreams. In this instance, insurance acts as a financial safety net that helps you financially protect your loved ones.
It also enables them to continue living with minimal worry, especially when large financial burdens like medical bills, mortgage, debts and others would easily change the financial status of your family.
Preserve Lifestyle During Difficult Times
We never know what life has in store for us especially while we are still feeling fit and healthy. No one likes to think that something bad will happen to us, and when something bad does happen, the first thing we usually say is “Oh no, he / she is so young”.
Illnesses and accidents are not age-specific. These are random events that could affect anyone.
But if you could not work due to a serious illness or accident, how would you manage financially? If the worst does happen, insurance helps you to minimise the financial impact on you and your family.
For example, if you need to give up work to recover from illness or if you are permanent disabled, the insurance could be used to help pay the household bills, mortgage, or even supplements, giving you and your family a peace of mind when you need it the most.
Recovery Takes Time
In a good ending, a person who is seriously ill may triumph in the fight against the illness, but, this person may not able to return to work immediately. All of these could incur many costs.
It is kind of heart-breaking to contemplate a situation where you survive a serious illness but fail to survive the financial hardship. This may be a time this person might have hoped he or she did not conquer the illness.
Obviously, you do not want an unexpected event that could easily change the financial status of you and your family. Preparing for the worst is not something we want to think about when we are feeling fit and healthy.
However, you will not suffer for thinking about it and preparing for it first. It is much better to be prepared, than to be in despair.
Preserve Your Legacy And Wealth
People are also promoting insurance as a tool to ‘create’ wealth, not just preserving it. Having adequate insurance that can help to repay your debt the moment you kick the bucket, can help ensure your assets get to pass down to the rightful beneficiaries.
Your family do not have to lose the assets such as your house due to their inability to redeem the loan from the financier. In time when the estate of the deceased is frozen pending the estate administration procedure, the proceed from insurance can help ensure life goes on for the surviving family.
If you are concerned your family may mis-handled the insurance claim, you can also have a proper legal structure to preserve this wealth. Through an insurance trust, you can decide the way how and when you distribute your wealth without actually physically transferring to your next of kin in a lump sum payment.
The trust assets are actually placed under trust to avoid your next of kin spending all of your wealth in few years when it took a lifetime to accumulate it.
Insurance And Your Life Stage
As you move on to different stages or wealth status in your life, the need for insurance will inevitably change.
One of the common questions people usually ask is “How much insurance I need?”
It really depends on your circumstances. There is no one size fits all solution and the amount of cover and how long it lasts for, all these will vary from person to person.
There are some events when you should consider reviewing your insurance needs:
Buying new house with your partner;
Building a family;
Having children;
Change of lifestyle i.e. salary increases;
Covering loans;
Reaching retirement;
Starting a new business;
Entering into a civil partnership;
Changes in business ownership;
Creating wealth to next generation;
Transferring wealth; and
Others
Clarify What Insurance You Need
Safeguard and preserve your wealth and then look at what types of insurance that you need to preserve your financial status.
It is important to manage your wealth and ensure you set aside a portion of your income to buy insurance, but don’t overcommit too.
It is advisable to seek for advice on how to optimally insure yourself and preserve your wealth against all the possible events that could disrupt your life.
About the Author
Keah EeWen is a licensed financial planner with VKA Wealth Planners Sdn Bhd
It is very easy to get financial advice nowadays, especially with the boom of the internet and social media. If you visit financial related Facebook groups or forums, everyone is eager to give their opinion on the best ways to manage your money.
However, one downside of these free online advice is bypassing of important safeguards such as ensuring the person seeking advice is subject to a detailed financial health check and understanding their current financial position.
So, choosing your personal financial planner can be one of the most important decisions you can make. Your financial planner is your partner to guide you through many decisions about handling major financial and life decisions.
To find the best financial planner who is right for you, here are five important factors to keep in mind:
1. Make A List Of Financial Planners
Start by creating a list of potential financial planners. Ask your friends or family if they have engaged with any financial planners. Take the time to check if the planners have the required license from Securities Commission Malaysia’s database (). Then, call each financial planner to see if he or she is accepting new clients and arrange a meeting with the planner.
2. Research The Financial Planner’s Credentials And Experience
In Malaysia, most financial planners do not start their career as a financial planner. Some are trained lawyers and accountants. Knowing the background of the financial planner allows you to understand whether the financial planner has the resources to help you in your financial decisions. The more experience a planner has, the better your results are likely to be.
If you need a specific form of planning, such as the involvement of business or family offices, ask the financial planner if he or she has any experience handling the matter.
3. Evaluate The Financial Planner’s Communication Style
Choose a financial planner with whom you are comfortable talking to. Do you feel that the financial planner understands your situation? Find a planner who shows an interest in getting to know you and will respect your decision-making process.
Also think of the convenience of meeting your financial planner. In the beginning of the financial planning process, you may need to meet your financial planner several times in a month. Can you reach your planner online, especially during the COVID-19 pandemic?
4. Evaluate The Financial Planner’s Company/Team
Take the time to research the company and team behind the financial planner. Is the financial planner working alone? What are the credentials of the team behind the financial planner?
As finance is a very broad topic, a good financial planner usually specialises in a particular field and works with another financial planner or other professionals (such as lawyers and accountants) to handle other parts of the planning and solution implementation. Think of it like the case of a hospital, where a patient may get treatment from different specialists.
5. Understand How The Financial Planner Is Getting Paid
There are 3 main types of fee-structure when it comes to financial planners:
Commission only;
Fee-based; and
Fee-only.
In Malaysia, we usually see commission only and fee-based planners. Fee-only financial planners are extremely rare.
A financial planner that receives commissions only works great with someone that wants a product that they already have some idea in mind. The relationship is usually transactional in nature and heavily focused on advice with a product-based solution.
A fee-based financial planner earns a fee for developing a financial plan for you, while also earning a commission if you require him or her to service your insurance policies or investment portfolios.
Make sure that your financial planner is transparent on the fee for their services.
Summary
Just like when making any major purchases, it is important to do your homework when it comes to choosing your financial adviser. Not every financial planner has the same level of training or offer the same range of services. It is important to talk to several financial planners and choose someone that meets all the above-mentioned criteria.
Finally, it is important to understand that financial planning takes a long process. Find a financial planner that you feel comfortable talking to and feel he or she is helping you work through your problems.
About the Author
Marshall Wong is a financial planner holding licenses from the Securities Commission Malaysia and Bank Negara Malaysia. He can be contacted via email at Marshall@plannerd.io
Since childhood, parents advise us to study hard, get good grades, go to college and graduate so that we can land a job with great benefits. It has been our only concrete financial plan until we faced the reality of adulthood. here are many types of income which easy.
We became students of financial matters ever since and have begun to explore many types of income from books, workshops, online media, and casual chats over coffee. It has led us to build multiple streams of income, instead of relying solely on a single job for pay.
In this article, let’s explore these income types. Each has its unique attributes, requirements, and usages to build wealth for the long term. We’ll examine five different types of income, discuss their pros and cons, and how they can contribute progression towards your financial life.
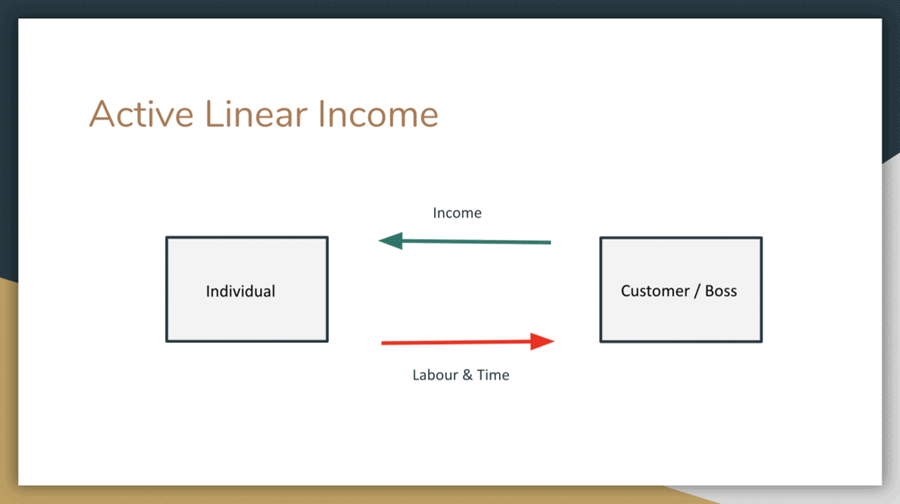
1. Active Linear Income
It is income derived from an exchange of physical labour and time with a single paymaster. This type of income is most common for it is the fastest means that one uses to make money as it requires the least time, effort and investments to establish this source of income.
For instance:
You are an employee working for $ xxx per period (hour, day, week, month, shift, etc.).
You are a freelancer who charges a fixed fee of $ xxx per project.
This type of income is useful when one is starting off. After all, everyone has bills to pay. With that being said, this income is dependent solely on your effort physically.
So, it may be limiting in terms of growth for all of us possess only one physical body, 24 hours a day, 365 days a year, and can only be at one place at a time. As such, this leads us to explore our next few sources of income.
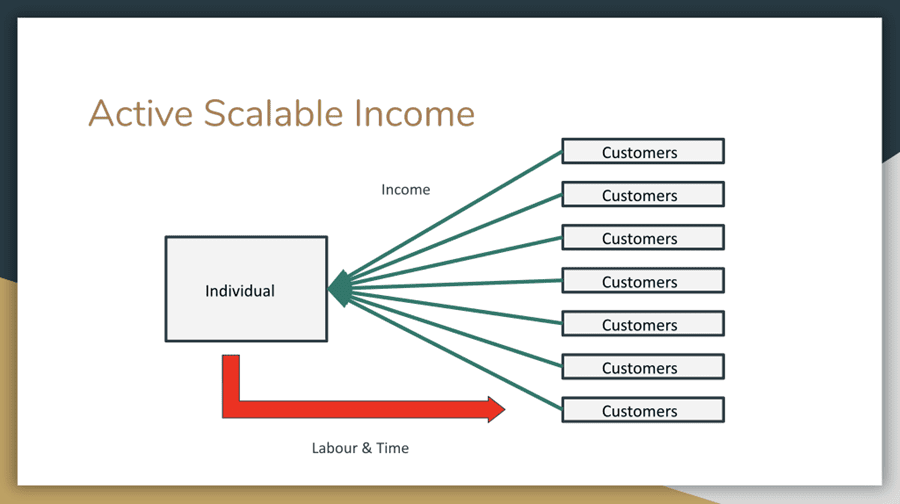
Likewise, it is also income earned from an exchange of physical labour and time but to a network of paymasters. It involves one having built a system or a team or multiples of both to increase income exponentially via scale.
It includes:
You earn x% in overriding commission from sales generated from your sales team.
You are a freelancer who makes x% profit share from project undertakings.
You sell products or services via a network of distributors and retailers.
You sell digital products to an online community consisting of xxx people.
This type of income is expandable because the number of clients you serve can increase significantly without you substantially increasing your efforts at work. In other words, a 100% growth in your customer base may bring 100% more income without you increasing your workload by 100%.
This is usually the type of income that propels one from earning 4-figures to 5, 6, or, 7-figures per month, hence, raising more significant capital faster for investments.
But, if it is that good, why not more people earn this type of income?
This is because it requires people to invest time, effort, and money to first learn about marketing, branding, leadership, and system building. Upon which, there might be no immediate payoffs.
For instance, you may have a desire to make millions from pitching your products to a broad audience in a mega preview event. The money sounds enticing. But, you would need first to master effective public speaking and closing.
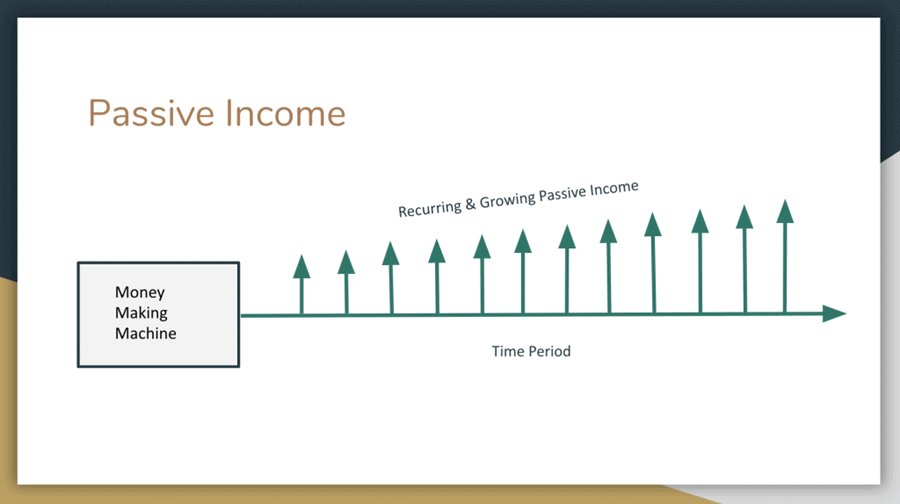
3. Passive Income
It is recurring income derived from ownership of profitable assets. It includes:
Interest income from fixed deposits, P2P lending, and other forms of credits.
Coupons from bonds.
Dividend income from a portfolio of stocks that pay dividends.
Rental income from tenanted properties.
Royalty income from intellectual properties.
Passive income from owning businesses that you don’t physically manage.
This type of income is awesome because cash is flowing into your bank account without physical labour. In essence, receiving passive income is earning time as it frees your time to pursue what you like. Besides, there are many tax benefits if you have any of the above sources of passive income.
If you are earning $ 100,000 in active income, you will be paying more income tax on as compared to another person who makes $ 100,000 in passive income. He may even pay literally zero in income taxes in Malaysia.
However, you need higher financial intelligence to create passive income effectively. One inevitably has to learn about investing and be a skillful investor with a great temperament.
Therefore, although passive income doesn’t require much physical labour, you need to study a lot (mental labour) before being good at it. Besides, without huge capital, you can’t survive on meagre passive income to do it fulltime.
4. Portfolio Income
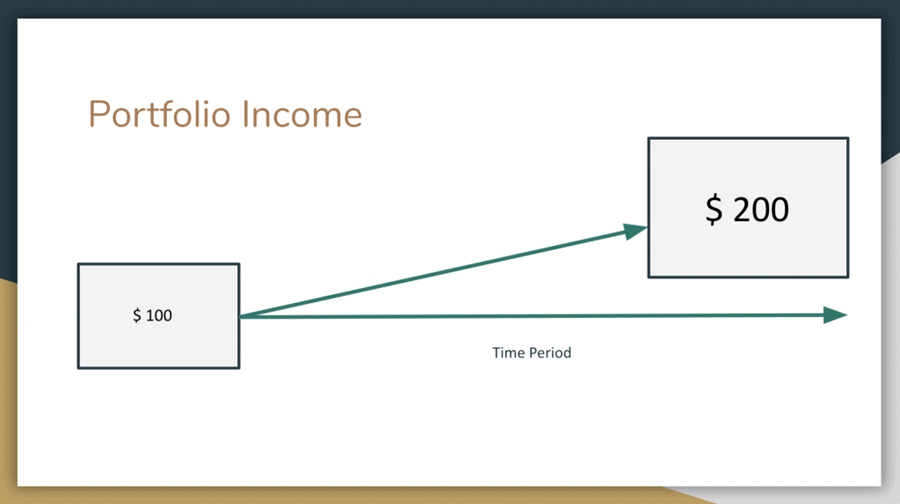
It is income derived from market value appreciation of your assets, also known as a capital gain. Alternatively, you can earn this profit via investing in assets at prices below their market valuation. Some examples include:
Your stock has appreciated from $1.00 to $2.00 in x period of time.
You bought a property for $80,000. Now, it is worth $100,000.
The value of your home is $200,000. You bought it for $80,000 7 years ago.
Many people find investing appealing because of the prospects of earning portfolio income or capital gains. It is even more attractive as compared to making passive income for the money is more significant. After all, eating steak immediately is more appealing than having milk every day.
I find there are two types of people who want to earn portfolio income.
First, it is people who are focused on money. They intend to make more money via selling assets at higher prices than their cost of purchasing them. This group of people are either traders if they can make money consistently or speculators and gamblers if they lose money consistently from their activities.
Second, it is people who are focused on accumulating assets. They are not ones who will kill their golden goose as they treasure them. For instance, they would invest in stocks or properties and hold onto them for long-term capital growth. Their mindset is to keep them and not sell them for a profit. In most cases, they would build massive net worth from their investments over time.
5. Phantom Income
It is income derived through the leverage of tax benefits, corporate entities and debt. It is known as Phantom Income as the income is not receivable via cash. It is an income of the rich as it requires a higher degree of financial intelligence to grasp the concept and utilise it fully.
We won’t list down its examples for its explanation is more technical. Here, suffice to say, the best way to use this income efficiently is to surround yourself with a team of advisors such as investors, consultants, accountants, lawyers, bankers and other related professionals.
There you go, the five different types of income that one could earn for himself to increase financial wealth.
If you think about it, the five types of income is an income progression of most wealthy people who began with very little. You would begin with earning active linear income first to survive, expand your income through scale, invest your capital for passive income and portfolio income and roped in a team of advisors to make phantom income by setting up corporations to save on tax payments and use low interest rate debt to accumulate more assets that would build even more wealth.
Now you know how it works. Go work on it!
About the author
This article is co-written by KCLau and Ian Tai
Ian Tai is the founder of DividendVault.com, a platform that analyse and filter stocks that pay increasing dividends year after year.
KCLau is a financial educator. He had published 6 books and co-created a dozen online financial courses. After conducting more than 461 hours of free webinar and 2000 articles published online, he gives away his popular Money Tips e-book volumes absolutely free at his website: https://KCLau.com
The global pandemic that hit the world has changed all aspects of our life. Besides the health and human loss that is caused by COVID-19, it has also impacted the economy quite severely.
Efforts by the government to curb the pandemic by imposing Movement Control Order (MCO) have a great impact on businesses and individuals. Many companies have closed shop and many individuals saw their income greatly reduced.
To help Malaysians, the Employees Provident Fund (EPF) rolled out three withdrawal retirement income initiatives namely i-Lestari, i-Sinar and i-Citra. The pandemic has clearly disrupted the cash flow of individuals affected by lockdown and economic slowdown.
A total of RM101.1 billion EPF withdrawals have been made and there are now 54% or 4.4 million members who have less than RM10,000 savings in their EPF.
This leads us to the question; can we save for retirement in this post-pandemic era?
A Long Term Game
Saving for retirement is a lifelong journey. Many Malaysians put their savings for retirement plans on-hold as they struggle for the past few years.
A survey conducted by the Private Pension Administrator (PPA) highlighted that 80.1% of respondents who are facing financial challenges were rethinking their retirement plans and goals, while 19.2% of respondents want to resume saving once they have achieved financial stability.
Government approval on EPF withdrawals should not be the only solution to ease an individual’s burden. To alleviate the difficulties of the rakyat, the government must create more funding schemes or come out with other forms of assistance rather than approving the withdrawals from retirement funds.
This will be a huge problem in the future, as many are left with very little once they retire.
The country is now rebuilding its economy, our borders have reopened, and many people are going back to work. Even the traffic jams are getting worse.
If you are badly affected and have exhausted the means from your EPF, it is about time to start filling in your retirement funds. We can see the light at the end of the tunnel, just need to persevere a little bit more.
About the Author
Nur Aiziera Sukmancompleted her Masters in Quality & Productivity Improvement from Universiti Kebangsaan Malaysia in 2007. She has more than 10 years of experience in the Financial Services industry and specializes in understanding financial planning needs and develop customized plans to suit retail and corporate client.
In 2019 she pursued her professional certificate in Certified Financial Planner from Financial Planning Association of Malaysia and continued her study in Islamic Financial Planner from IFBIM and received the IFP Certificate in 2021. She can be reached at aiziera@aswaadvisory.com.
Aswa Advisory is your preferred one-stop center for Shariah Independent Financial Advisory. Get a free consultation from an Islamic Financial Adviser Representative by filling in your details here:https://www.smartinvestor.com.my/SIxAswa
In order to become financially independent, the need to track your net worth is a crucial step. And for our net worth to grow, we need to have good cash flow management where part of our income is retained and converted into financial assets. Can we spend or can we not?
However, when I say good cash flow management, this does not mean you have to track what you spend every day. Usually, people associate this with not spending money or cutting back on their lifestyle, which is inaccurate.
Rather than doing that, I believe that we should not suppress our urge to live our life the way we want it. We work so hard every day, so why shouldn’t we live the lifestyle that we would like to have?
Why it’s OK to spend?
I’m not here to tell you not spend money, and I’m not here to tell you that you should save x% of your income either. With our lives surrounded by advertisements that promote consumerism, it’s not easy to resist the temptation to spend. Instead, I’m here to tell you that it’s okay to spend money.
Generally, there are three types of spenders – which category do you belong to?
Type 1: Spend More Than You Earn
Despite enjoying and living on our own terms to the max as a Type 1 spender, it comes with consequences. Since the additional spending is funded by money that is not ours, there will be time when you will need to pay it back, and it will not be fun when that time comes.
Immediate gratification is common for Type 1 spenders, as their wants and needs get fulfilled. Over time, however, this may become a habit and if you are trying to adjust or change this habit later, it may already be too difficult, and the process may not be easy.
Type 2: Spend What You Earn
Those in this category are usually smart enough to avoid the painful journey of paying back what they owe the bank, and so they spend within their means. If they bring home RM1, they spend RM1. This seems slightly more attractive than the first type, as this is living in the present without having to worry about payback.
However, this has its downsides too.
The downside comes from you having to continuously earn an income to pay for the food and services you need. It means that you cannot stop working. The day you stop working is the day you stop earning an income, and you’ll then no longer be able to pay for what you need.
That said, this category isn’t entirely ideal either. On the flipside, if you are a salaried employee, you are automatically made to save at least 11% of your gross salary in anticipation of your golden age.
However, this can only be enjoyed after your retirement. What about the other life priorities and goals that you would like to pursue between now and when you retire? If we spend all that we take home now, we will never have the ability to pursue these life goals.
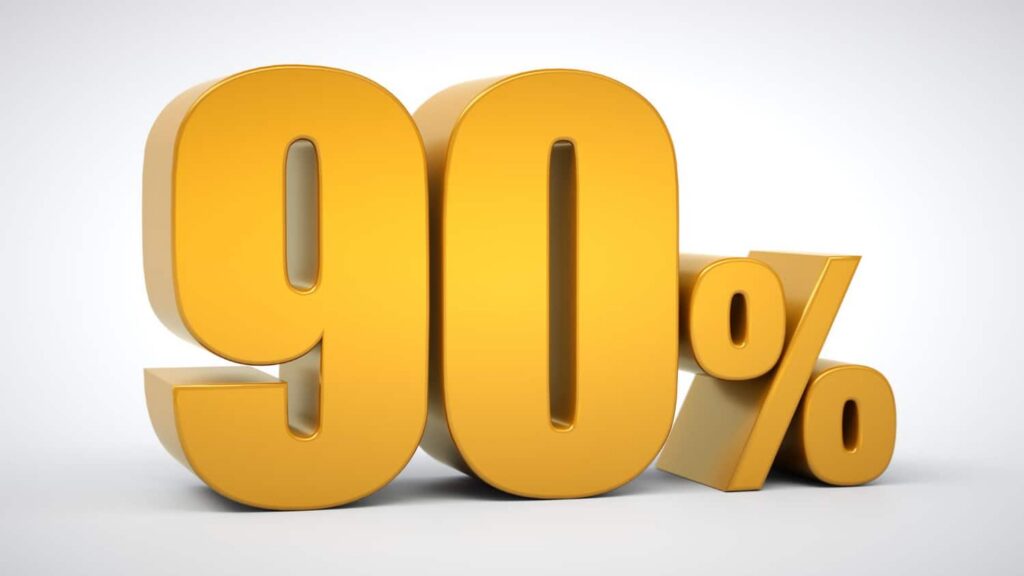
Type 3: Spend Not More Than 90% Of What You Earn
This type of spender acknowledges the irony of the need to spend and to save, and makes it a point to set aside part of their take-home income to prepare for their future.
While living in the present, they also prepare for the future. This group of spenders understand that it is better to prepare than to repair. With the goal of spending not more than 90% of the take-home income, they practice what is referred to as ‘pay-yourself-first’.
You can decide how to spend as you like, so long you keep the maximum available for spending at 90%. If you can lower that spending amount, you will have more control over your quest towards financial independence.
By doing so, you have choices for your future. You are not just saving money; you are giving yourself more flexibility and options.
Honest Self Review
So, which type of spender are you now? If it’s up to you, which type of spender would you want to be? If you are not there yet, what is stopping you from getting there?
Usually, people who have insufficient monies to spend every month would say that they have to spend all their monies because they are not making enough. For these people, their mantra is ‘I will start saving when my income increases”.
Do you have these same thoughts too? My advice to you is to not wait – we can start making an effort to not spend all your take-home income today.
However, despite its benefits and advantages, just being a Type 3 spender is not going to promise you financial independence. Without managing the monies that you save in an efficient manner that supports your personal values, chances are you are not making full use of your financial muscles.
If you are unsure about your current spending behaviors and how to manage your personal finance, let’s chat.
Kevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my.
C: Women have inherent qualities that enable them to plan their own and their family’s finances
In my financial planning practice, I have observed that female clients, whether they be single career women or married with children, tend to face similar dilemmas and challenges when it comes to planning their personal finances.
But why is that happening to them? They should and they must have their roles in family finances.
Lack Of Time Due To Multiple Roles
There is no denying that the modern-day woman is highly adept at multi-tasking – from her job, her family, her children’s education to other social obligations and so forth. The downside of assuming so many roles and responsibilities is that it leaves hardly any time for herself at all.
Any precious moments of “me-time” that ladies can manage to squeeze out of their packed schedule goes towards rest and de-stressing to rejuvenate themselves. Financial planning issues will hardly be on their minds after a long day.
Tendency To Priorities Family Rather Than Themselves
Being selfless and filial are undoubtedly noble characteristics that every parent, husband or sibling would want their daughter, spouse or sister to have. However, when putting the interests of family members ahead of your own, more often than not, your own needs may be neglected.
A Senses Of Apprehension When It Comes To Managing Money
This can be real, imagined or selective. Numbers and calculations can be intimidating to certain individuals regardless of gender or age. Others tend to shy away from money matters because they find it too complicated and confusing, preferring to let their spouse handle it so that they can focus on other responsibilities.
My wife is happy to help our son with his algebra and trigonometry, but she claims to make no sense out of a financial spreadsheet.
Female clients sometimes base their decisions on how they “feel” about something. While having a keen financial gut instinct has made many billionaires, it is another thing when the heart overrides the mind in making investment decisions.
Examples would be putting money in investment plans because a friend “strongly recommended” it, or out of sympathy for your banker whom you known for ages and needs to meet his/her sales target.
Choosing To Save Rather Than Invest
Some individuals consciously decide to continue saving in cash, preferring to keep the bulk of their money in fixed deposits despite the dismal returns. They are in fact aware and reasonably well informed of their options but due to their position in the family (for example, being the only daughter or the only unmarried sibling), they feel a sense of duty or responsibility to have funds on hand to assist other family members should they require it urgently.
Taking on the status of the family’s “standby banker” no matter how well-meaning, denies some women the opportunity to plan for their own financial future. Instead of viewing these challenges as barriers, turn them into catalysts for your personal financial growth instead. There are many ways to empower oneself to take control and own your financial destiny.
Reprogramming The Mindset And Be Prepared
While you may currently have the luxury of someone else handling the household’s financial matters for you, i.e. your spouse, there may come a time when you need to take over or assist in those duties. If you are already prepared, well and good. If not, take time to increase your own financial literacy so that assuming the role of the home’s financial manager will be a comfortable transition.
Be Heard And Be More Involved
Suppose money matters are not exactly your cup of tea. It may be tempting to leave all the family finances to someone else, especially if things are running smoothly and the party handling it has the necessary expertise and experience and doesn’t seem to mind doing it. However, you may have insights and suggestions for improvements, so share your thoughts rather than keep them to yourself.
Make It A Learning Process
If your financial matters are currently delegated or outsourced to other parties, there is the danger that you may one day find yourself in a situation where this party is unable or unwilling to continue the responsibility. Thus, it is important to get yourself educated on how to handle your own personal finances rather than leaving such a crucial task entirely to someone else.
Leverage On Other People’s Time
If you find yourself already overwhelmed with work and other obligations, learning to put your personal financial matters in order from ground zero may seem like a mammoth task. Under these circumstances, a licensed financial planner would be able to work together with you and assist you through the entire process while ensuring your involvement every step of the way.
Individuals are not born with good personal financial skills, but everyone can learn how to be competent at it. Due to personal and family circumstances, women are often unable to take advantage of the opportunities present to improve their financial knowledge and be as hands-on in their personal financial matters as possible.
Nevertheless, women already have a natural advantage in taking on the role, thanks to two critical attributes that play a huge part in successful financial planning.
Firstly, regardless of age group, education level or social strata, almost all women are inclined toward a long-term mindset in whatever course of action is decided upon. This is usually more evident when it comes to buying a vehicle for example, or renovating a home or planning for the children’s education. Rarely are decisions made by women in the household without thinking two or more steps ahead about the effects and implications, contrasted with men like many of us who are more prone to “act first, think later”.
Secondly, women tend to err on the conservative side of men by questioning downside risks before taking action, which is actually a good thing. While profit and returns are typically top on the list of male investors, having a woman jointly involved in the investment decision would help to temper any hasty actions and mitigate potential financial risks.
As such, these inherent qualities in women make them suitable candidates to plan their own and their family’s finances. With guidance and financial education, they have the potential to surprise even themselves.
A household may have mixed styles of financial management as both men and women are good in personal finances in their own ways, therefore by complementing one another and learning from one another, amazing results can be achieved.
About the Author:
Felix Neoh CFP CERT TM is the Director of Financial Planning at Finwealth Management Sdn Bhd and is a certified member of FPAM. He can be contacted at enquiry@finwealth.com.my
We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth
For us to pursue our multiple life goals, we will need to have financial resources, which is like our ‘financial muscle’. We will need to have muscles to do the weight-lifting, which is to turn our life goals into reality. Therefore, we need to have the know how.
This, essentially, is financial literacy.
The Organization of Economic Co-operation and Development has defined financial literacy as a combination of awareness, knowledge, skill, attitude and behaviour necessary to make sound financial decisions and ultimately achieve individual financial wellbeing.
Why Is Financial Literacy Important?
Obviously, the decision we make today has a long-term impact on our financial wellness in the future. Hence, a poorly made decision may have a very detrimental impact on our future.
If a person is not financially literate, then this person may face multiple challenges in respect to managing his or her own wealth. Potential consequences can be:
Not protecting savings and assets adequately;
Not prudent in borrowings and ending up with too much debt;
Not investing to inflation-proof your purchasing power;
Not having a will; and
Not having financial safety net like an emergency fund and health insurance.
The list can go on and on.
When a person is in a situation as above, it’ll be rather difficult person to attain financial independence as well as pursue his or her life goals.
How Financially Literate Are We?
The following statistics from the National Strategy for Financial Literacy 2019-2023 Report gives us a picture of where we stand as a nation in terms of financial literacy.
43% of Malaysians understand that growth of money is compounded over time, while 22% believe money grows on linear basis;
75% of Malaysians understand that inflation means cost of living is rising, only 38% can relate the effect of inflation on their own purchasing power;
84% of Malaysians who claim to save regularly typically withdraw it at month-end to cover daily subsistence expenses;
Three in 10 of working adults need to borrow money to buy essential goods;
52% have difficulty raising RM1,000 as an emergency fund;
Only 24% are able to sustain their living expenses for at least three months if they lose their main source of income, and only 10% can sustain for more than six months;
Six in 10 adults are self-employed and hence not covered by a social security system or any formal retirement fund; and
About 60% of investors were found to have unrealistic expectations on potential annual return from investment in capital market products.
A Financially Responsible Person
When a person is financially literate, he or she will be more capable in understanding how his or her decision can impact their financial future, hence becoming a responsible person financially.
When we are financially responsible, we will be careful about adding financial responsibility to our finances. We will ensure that we do not spend all we make but make provision for our future, and for emergencies.
In fact, most people are aware of this but somehow, fail to take action.
What Is Missing?
Since most of us who are working adults have not been taught about financial literacy in school, we need to learn it from somewhere.
Learning is a passive thing – you can continue to read, learn, listen to podcasts or attend workshops for years. However, it is not the learning that matters but the doing that makes a difference.
To ensure that we do what is in our best interests, not only do we need financial education, we also need financial accountability. I truly think this is the key missing piece of the puzzle.
That is why we are unable to behave rationally and stick to our plans, fail to save what we plan to save every month, all because of a lack of accountability.
I will define accountability as having a sense of ownership over your work and accepting consequences for your actions and behaviours.
Many times, we are aware that if we don’t save, it will leave us in a worse shape compared to when we save. But we spend anyway.
So to increase your financial accountability, it’s best if you work with someone interested to help you stay true to your own words, and be accountable for your own actions.
Financial Accountability Partner
An accountability partner is someone who coaches another person to keep a commitment. Getting a right accountability partner is known to be a highly effective strategy for goal-setting and achievement.
The good news is that If we want to stick with our action plan, we just need an accountability partner. The bad news is that we cannot be our own accountability partner.
And if you have selected a candidate who is not so suitable, your accountability partner may well turn into your partner in crime.
What To Look For In Your Accountability Partner?
Ideally, this person should be able to complement you in terms of knowledge, skills, expertise. Since this is a financial accountability need, your candidate should possess extensive knowledge on this subject matter. Otherwise, coaching you to do the wrong thing will eventually send you down a path that is cursed as well.
However, you should look beyond things that are measurable such as knowledge. Will this person be willing to challenge you to out-grow your limit?
Your main objective of getting an accountability partner is to outperform your own set objectives. Therefore, you need someone who has the courage and discipline to tell you what you need to hear, not what you want to hear.
Your accountability partner should also be able to make sure you follow through on your commitments, monitor and review your action plans with you so that you can find ways to improve on it.
When you are in doubt, he should also be able to provide you with independent feedback and show you the next step so that you will not be stuck at status quo.
Who Can Be Your Ideal Financial Accountability Partner?
Most of us have friends, and family members who we care a lot for. Are we their financial accountability partner?
Did any of our friends or family members volunteer to talk to us about our financial successes and planning? Has anyone have taken the time or initiative to tell us the importance of save-first, spend later, or the importance of having an emergency fund?
I guess the common answer to these questions will be a string of “no’s”.
That is also why I volunteer myself to be your financial accountability partner by devoting my lifework to be a licensed financial planner. I have a strong sense of fulfilment whenever people feedback to me that they are seeing progress and happy because they are sticking to their own plans and are seeing results.
That sense of fulfilment is even stronger when I get credit for the success my client is having.
Personally, I believe that it is important for us to work at something we love to do and are passionate about. I’m just glad I’m under this category.
I think someone who is doing what they are doing when not motivated by monetary reward alone, will be the right person to do the best work.
So, get an accountability partner to make sure you are accountable for your financial independence.
About the author
Kevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at kevin@nextgenadvisors.my and www.kevinneoh.my.
As a counsellor, I have seen many young adults come in claiming that they are depressed. From my perspective what they might actually be experiencing can be termed as ‘’quarter life crisis’’
Then the question arises “What is quarter-life crisis?’’
This is a new phenomenon that is happening to young adults who are in their twenties and thirties. Fresh graduates who are entering the ‘real world’, suddenly find themselves under a lot of pressure to succeed vocationally, relationally and financially even before hitting their thirties!
Signs That Young Adults are Facing a Quarter Life Crisis
They are confused about what their next step in life should be – Questions like these would appear in their minds: Is this what I want in life? Will I be stuck here? What can I do next? There are tons of questions that they don’t seem to be able to answer.
They are overwhelmed by all the possibilities out there – The modern economy is fast and dynamic; it’s in a constant state of change. Adapting or succumbing to change is the only option. This creates high stress and anxiety effect on them.
They feel stuck in terms of their life choices and feel like not having control over their own future – Some may feel pressured to marry and have children before the age of 30 as some of their friends may already be married and have a high-paying job to accommodate their luxurious lifestyle whereas they are still questioning the decisions they made for their life.They keep jumping from one career to another. They spend a lot of time wondering if they should work for money or follow their passion and do what they love. They would second-guess their choice of career field and be probably wondering if they should go abroad to explore the opportunities or stay where their family and friends are.
Finding the Right Ways to Cope
Become aware
Identify which aspects of their life they struggle with and break them down into smaller segment. Look at it one by one; don’t mix relationship issues with career, and don’t compartmentalise them either.
Don’t be hard on them
Remember that they are a beginner and it takes time to adjust. Venturing into something new is a tough transition so be patient.
Don’t be afraid to let them try new things
It is okay to make mistakes as they journey through this phase in their life. They will slowly gain experience as they go along and this will be their priceless assets. It is like learning how to ride a bicycle and once they master it, they will be able to do it without having to think of it much.
Recognise their achievements
Recognise their accomplishments. Take pride in them. Be grateful for them. It will provide them with the energy to keep moving forward. Take comfort in knowing that through hard work and determination, everything else will fall into place.
Seek help from a counsellor or a mentor
Find a counsellor/career mentor to help them strategise what their next move should be. Counsellors/career mentors are trained to identify problems people face and will be able to empower a person who is facing difficulties find practical solutions to their problems.
Lastly, quarter-life crisis is not a crisis! It is an expected development of personal growth and evolution of an individual. Young adults are growing, learning and noticing new talents as they grow. It is not a crisis if they have not achieved greatness by their late twenties and it is okay to make mistakes as it helps them become better human beings.
As long as they continue to love themselves, discover their potentials, and evolve into their authentic self just remember that every step they take in life is helping them become something better.
So, if at any point of time you come across a young adult who is facing a hurdle in their path, don’t let it overturn them, just encourage them to keep going as this is just a small dent in the road, to the beginning of the rest of their life. After all this is what is called LIFE.
About the author
Faith Foo (MA Counselling) is aRegistered & Licensed Counsellor at Rekindle Therapy (www.rekindletherapy.com)










 Kevin Neoh is a NextGen Money Coach who works with people to help them transform their relationship with money to improve their lives with the money they have. Kevin can be contacted at