Category: business

  • 3 Values Of Financial Planning: Here’s Why You Need To Start Early

    3 Values Of Financial Planning: Here’s Why You Need To Start Early

    Anwar reached out to me in 2018 as he needed help with his personal finances. As the only son in his family, he was the executor of his late father’s inheritance. His father passed away many years ago due to cancer, and he remembered clearly the financial drain from cancer treatment.

    34-year-old Anwar is a lecturer at one of Malaysia’s largest universities. His wife is a housewife taking care of their two children, aged 7 and 4.

    “Although my father’s death hit us badly, we were thankful that he did not leave us with massive medical bills. This is because our prudent father had a healthy emergency fund,” shared Anwar.

    Being the main breadwinner of his own growing family, he needed to prepare for such emergencies. Just like his father, he wanted to ensure that his wife and children are well-provided for in case anything happened to him.

    Anwar’s father was a banker and had taught his children about saving money. Anwar also has a keen interest in personal finance and investment, and had read books and attended a Do-It-Yourself (DIY) course from a financial guru.

    However, he found that the information was too overwhelming and didn’t know where to start with regards to his own personal finances. Having been approached by unit trust and insurance agents, he was wary as he recalled, “They were more interested in pushing their products for commission rather than to put a roadmap and direction for me to achieve my financial goals”.

    Here are the 3 values of a full financial planning.

    1. An Expression Of Love

    Anwar and his wife know how dire their financial situation will be if Anwar passes away prematurely. People tend to forget verbal reminders easily. But if it is written in the form of a will, wishes, hopes and dreams; it helps tremendously.

    Furthermore, the engagement allows him to translate his expression of love, his long-term and short-term goals into actions, and not just a wish. During our discussion, one of Anwar’s goals is to support his wife’s pastry business once his financial situation has improved.

    After the third year of our advisory engagement, Anwar manages to make his wife’s goal into a reality. (You can check it out on Instagram Pastreen; it’s really delicious)

    2. Aligning Strategy With Financial Goals

    We provided insights to help him map out the strategies to reduce the Debt-to-Service Ratio (DSR), ideal asset allocations for his financial resources and guidance on financial products he should consider getting with the time horizon he needed in order to achieve his financial goals.

    Since he was willing to start early, he will have more options and opportunities to optimise his wealth. As his financial planner, my role is to guide him with the options available so that he can take ownership in his financial planning by making an informed decision.

    Anwar now understands the importance of building a healthy cashflow, and how to lead his ideal life within his means.

    3. Financial Needs And Wants

    A common situation is the relationship between savings for building cash reserves and other goals in life such as buying an asset. Many are unsure if they are over-committing one financial goal at the expense of another.

    With a holistic financial plan, we can see how extra commitments will affect other financial goals. It helps to adjust our actions, weighing the pros and cons before deciding. Most importantly, it is a tool to effectively communicate your financial situations and life goals.

    Conclusion

    Anwar is a real-life story of “It is not about how much income you make, but how well you manage your income”. Without a roadmap and direction, we might spend unnecessarily and make poor financial decisions. Financial mistakes are painful.

    Similar to inflation, financial goals and financial freedom are a challenge to understand and to manage, because it is intangible. Only after acknowledging what an ideal life is, you can move on to support your goals in life.

    About the Author

    Saidah Asilah started her career as a graduate trainee with Securities Commission Malaysia. Then, with a deep interest in investments, she furthered her studies in MSc in International Business and Emerging Markets, graduating in 2013 from The University of Edinburgh, UK. She is a Licensed Financial Planner, CFP Professional & IFP Certificant and describes herself as a multi-talented adventurer with a positive impact to whomever she meets. She can be contacted at saidah@wealthvantage.com.my.

    We at Smart Investor and Wealth Vantage is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxWealthVantage

  • 3 Mistakes To Avoid In Your Financial Planning Journey

    3 Mistakes To Avoid In Your Financial Planning Journey

    Based on the OECD/INFE 2020 International Survey of Adult Financial Literacy that included 26 countries, Malaysia was ranked third highest behaviour score after Slovenia and Indonesia. This ranking was achieved thanks to three common, prudent financial planning behaviours that emerged in the survey answers, including saving and long-term planning, making considered purchases and keeping track of cash flow.

    However, Malaysia was also placed in the bottom tier in the section of financial knowledge. The report also highlighted that globally, youths (defined as those aged 18-29) have a lower financial literacy score compared to middle-aged individuals (30-59 years old), of which a similar trend was seen in Malaysia as well.

    Thus, I would like to take some time to share about costly mistakes that you should avoid in your financial planning journey, especially for the younger generation to take note of!

    1. Ignorance

    Ignoring the basic knowledge about invest and power of compounding is like ignoring the blinking fuel light on your dashboard while driving! In the worst scenario, ignoring this indicator may result in your car inadvertently stopping in the middle of nowhere after running out of fuel. Not a pleasant situation to be in!

    In financial planning, you may end up paying a huge price in the future because you will not be able to get back time which is essential to growing your personal financial assets through your active income period, either via employment, business or investments.

    The first step you must take is to accept your current financial situation, no matter what level you are currently at. This is just like the example above, where you can drive your car to the nearest petrol station to refuel before continuing your journey. Just do not run out of fuel!

    Once your financial situation is assessed either by doing it yourself or getting professional assistance, identify several steps you can take towards your goal such as starting to put aside savings regularly, monitoring your cashflows, and identifying investment assets that are suitable for your risk appetite in order to build and grow your wealth.

    2. Procrastination

    yo

    Procrastination tends to occur when we would rather do other things instead of what we actually need to do. Thinking that reviewing and planning your finances is something that can be delayed or put off to a later date is actually a very common problem.

    In investing, this will translate to you needing to save a higher amount each month due to the shorter investment horizon, compared to another individual who started earlier than you. The cost of procrastination may not bite you early on, but its effects can be far reaching in the future!

    This can also apply to insurance planning – some individuals may have certain conditions excluded or charged more on their premiums should they want to apply for and purchase health insurance at a later stage. As their health is not in as good a condition as it was when they were much younger, naturally the price will increase.

    Therefore, it is advisable to get insurance early on with appropriate coverage when you are young. Review your insurance needs annually or whenever there are changes to your lifestyle. After all, any medical emergency can wipe out your savings in an instant so always be prepared!

    3. Fear

    Some individuals may have adopted the wrong beliefs or have misconceptions about investing, creating their own meaning out of their own experiences or that of others. That may also be the reason why some of them tend to keep most of their wealth in their bank accounts, or at best, fixed deposits. Although they would rather opt for certainty in life, the only thing that is certain is change.

    What is more important for you is to implement proper diversification in your portfolio, being disciplined and focused on consistent savings, and growing your wealth in order to reach your long-term financial goals.

    Do you worry that you might not have enough financial resources to fund your retirement in 320 years’ time? Or would you rather worry about the short-term fluctuations in your investment portfolio during periods of market volatility?

    You cannot turn back the clock if you do not have enough savings in your retirement age, so it is wise to maintain a long-term perspective when looking at investing.

    Give yourself a head start. Learn how to gain the right knowledge through reading, attending seminars or seeking out financial professionals such as licensed financial planner to guide you. These avenues will greatly help you with overcoming fear of volatility and taking advantage of it to grow your retirement nest egg or reaching other financial goals you may have.

    In conclusion, the three mistakes to avoid in your financial planning journey (especially among the younger generation) is to get rid of your ignorance, overcome procrastination and conquer your fears.

    It is important to start taking smaller steps as early as possible to improve your financial literacy, and start to save and invest regularly to enjoy your financial planning journey with more confidence. Your future self will be very grateful!

    About the Author

    Goh Chee Yong is a licensed financial planner under Capital Markets Services Representative License (CMSRL) and Bank Negara approved Financial Advisor Representative (FAR). Prior to becoming a financial advisor, he spent eight years working in Big 4 audit firms and multinational corporations. He can be contacted at cygoh@imaxfinancial.com.my

  • Here’s Why You Need To Plan For Your Retirement

    Here’s Why You Need To Plan For Your Retirement

    In the traditional context, the word “retirement” means withdrawing from one’s active working life. However, in today’s modern world, the concept of retirement goes beyond its literal interpretation, with more individuals now viewing retirement as the dawn of a new chapter in their lives.

    A meaningful retirement should be one that affords you peace of mind without the worries of financial concerns. Only then would you be able to relax and enjoy the fruits of your labour.

    However, an ideal retirement does not happen overnight. Just as building strong body muscles requires us to work out in a dedicated and consistent manner over time, the same principle applies to retirement too. When we want to build strong wealth muscles, there needs to be a continuous effort over a long period of time.

    What is the right long-term strategy for our retirement planning to achieve our desired retirement lifestyle? The answer will form a clear blueprint to lead us towards a successful retirement path.

    If it sounds straightforward, why aren’t more people committing towards this?

    Financial Planning: The Starting Point For Retirement Planning

    The biggest mistake one can make in retirement planning is thinking that we do not need to have a plan. Contrary to common belief, financial planning is not exclusively for the wealthy alone. Our financial planning journey is a lifelong marathon to uncover different needs, new opportunities and specific challenges that may arise at different stages of life. 

    A comprehensive financial roadmap will give us more clarity on our current financial situation so that we are able to identify the gaps and address them as we work towards achieving our financial goals.

    Time Waits For No Man

    People have all sorts of reasons for not planning retirement properly, with the most common excuse being – “I am too busy and have no time!”

    I’m sure all of us are guilty of spending time on unproductive pursuits such as our social media activities or watching too much TV. Doesn’t it seem like a sorry excuse that we cannot plan for the rest of our lives because we have no time?

    When we let retirement happen on its own, there is a real risk of running out of money before our time is up! Do we really want to live our golden years tightening our belts and scrimping on every sen daily?

    The Sooner, The Better

    It’s time to face reality and not let excuses hold us back any longer. If you are in your mid-20s, this is the best time to start as your young age affords the benefit of the compounding effect. If you are in your 30s, it is all the more critical to commence your retirement planning without further delay.

    Once you are in your 40s, you will need to work harder to reach your retirement goals which will get increasingly challenging to execute if you wait until your 50s. Financial mistakes may still have a chance to be fixed even at this critical stage. 

    As a baby step, we can start by tracking our own expenses as we need to know where our money goes before we can have better control of our finances. As the saying goes “if we do not manage money, money will end up managing us instead”.

    The Sandwich Generation

    The dilemma faced by many Malaysians nowadays is that parents jeopardise their retirement for the sake of their children’s education, while the younger generation also risk their financial security to fund their parents’ retirement in return. This is an unhealthy financial cycle, leaving parents at an increased risk of a stressful retired life.

    The younger generation themselves are struggling with the burdens of financial commitments brought about by the escalating cost of living and high levels of debt.

    Mindsets need to change so that aging parents do not place excessive financial expectations on their children. At the same time, young adults need to have better financial literacy to plan their money matters better.

    Many Hands Make Light Work

    If the task at hand gets too overwhelming for us to tackle on our own, it is always a good idea to seek assistance. Many people already have their hands full managing their day-to-day or monthly financial affairs, what more to sit down and seriously plan for their retirement!

    Help is always readily available in the form of professional advice and proper guidance to achieve your financial goals. Everyone has their own special skills and abilities; focus on your expertise to continue earning your active income while leveraging on a licensed financial planner’s know-how to help you grow your wealth.

    In the past, retirement planning was hardly the norm and people went about their lives rarely thinking about it, only to deal with the situation when it happens. We cannot afford to adopt this outlook in this day and age where things around us are changing at a rapid pace, and taking a passive stance on our retirement is a huge gamble.

    It is never too early to have a solid plan and a clear vision on how to work towards it with the right strategies.

    One small step for our retirement, a giant leap for financial independence.

    About the Author

    Chan Li Yun is a Licensed Financial Planner with Finwealth Management Sdn Bhd and would like to assist others to improve their standard of living with proper wealth management planning. She can be contacted at liyun@finwealth.com.my

    We at Smart Investor and Finwealth is committed to help you better manage your financials. Get a free consultation from an expert by filling in your details here: https://www.smartinvestor.com.my/SIxFinwealth

  • Is Takaful Not Attractive For Most Malaysians?

    Is Takaful Not Attractive For Most Malaysians?

    “Wisdom is not measured by appearance.”

    As a husband, father, son, and even brother, I am the breadwinner and main contributor to the family finances. I work hard to give my best to my loved ones. The pressure is on to make sure I can leave my loved ones in the same or even better state when I am gone

    As a Chief Agency Officer, I am aware of the need for takaful protection in life. It can alleviate unexpected situations Takaful benefits provide for its participants in times when emergency funds are required because of a disaster resulting in death, accident, critical illness, or hospitalisation.

    The adage preparing for a rainy day holds true with a comprehensive takaful plan that can maintain our, or our beneficiaries’ lifestyles in times of disaster.

    I am often asked what is takaful and how is it different from conventional insurance.

    Takaful vs Conventional Insurance?


    Conventional insurance and takaful share the objective of protecting against financial loss. However, closer inspection reveals some clear differences.

    Takaful is based on Islamic principles of mutual cooperation (taawun). Participants (customers) fulfil their obligations by contributing a certain amount of donation (tabarru’) into a fund to protect one another against losses or damages covering life, general (assets) and medical. A takaful operator manages this fund.

    The takaful operator disburses the funds according to its participants in the event of loss or damage suffered. Surplus monies will be distributed between customers and operator at the end of the financial term based on an agreed ratio. This will only be done after all obligations of assisting customers has been fulfilled.

    Despite being based on Islamic principles, anyone can obtain takaful protection.

    Factors Affecting Takaful Contribution Amount

    Like conventional insurance, lifestyle factors affect the contribution amount each participant is required to make. These include occupation, age, family history, and underlying health factors.

    As takaful is based on the basis of donation, if the tabarru’ fund is insufficient, there may be a revision in the contribution amount. For example, the tabarru’ fund can be short due to volume of claims or medical inflation.

    A responsible takaful operator must monitor and revise the fund if necessary, to ensure it s contributors are always adequately protected. It is important in sustaining the tabarru’ fund for the long term. If a revision to contribution amount is necessary, the operator will notify customers beforehand so contributors are never caught unaware.

    What Can I Do If I Cannot Afford To Fulfil My Contribution?

    If personal circumstances change, let your takaful agent know so that a customised plan can be worked out based on your affordability. There are two main options provided to customers.

    Firstly, there is the option of reducing some of the benefits while maintaining the same amount of contribution. Another option is to remove certain riders (add-ons) and replace them with other benefits that may be more relevant to the customer’s needs in life.

    This is where a knowledgeable agent is invaluable. A good agent can advise you on the available options, and what may be best for your situation. Everybody’s protection needs differs from person to person. This is why Bank Negara Malaysia requires agents to conduct thorough fact finding to assess customers’ needs and provide recommendations.

    Do I Still Need Takaful When My Employer Already Provides Protection?

    Many overlook the importance of having their own personal protection plan. They think t heir employers will provide coverage for them until they retire. But work situations can change. Some may receive better offers or choose to work for themselves. When this happens, the protection afforded to them by their employer ceases. The level of protection can also cease or change upon retirement.

    Participation in takaful is for future needs. It is not only for one time use. Nobody can guarantee our health throughout life.
    Separating your takaful plans to cover different scenarios and needs is advisable.

    The rule of thumb is to differentiate existing plans for specific purposes, such as medical, savings, and retirement.

    Nowadays, there are plenty of plans with competitive and flexible riders. This allows users to choose add-ons based on their lifestyle needs. It minimises the need for multiple plans as one plan can cover different things. It is recommended to seek professional advice from a knowledge agent to get a better understanding.

    How Can I Tell If The Agent Is Right For Me?

    Agents are dutybound to ensure they do not bring disrepute to the takaful company, which seeks to help individuals, businesses, and community from financial loss. All agents must be licensed. You can and should ask to see the agent’s credentials before signing o n the dotted line. To obtain the license, the agent is required to pass a high integrity and closely supervised Pre Contract Examination organized by Malaysian Insurance Institute (MII).

    Takaful agents are subject to an additional Takaful Basic Exam (TBE) by the Islamic Banking and Finance Institute Malaysia (IBFIM). Many agents now opt to sit for TBE so they have wider breadth of knowledge to better serve customers.

    Beyond this, good agents must have solid fundamentals on different plans available. Investing time in the Customer Fact Finding (CFF) form will enable agents to understand the lifestyle and needs of the customer. Only then can agents propose a suitable plan within the customers’ budget, with adequate protection and savings.

    What Makes A Great Agent Stand Out From The Rest?

    Simply put it is their effort to upskill and improve themselves. Agents must complete the Continuous Professional Development (CPD) training yearly. The minimum is 30 hours. Dedicated agents typically undertake up to 60-70 hours of learning per year to upgrade and upskill themselves with knowledge in providing professional service and advice to help their customers better.

    Great agents prioritise customers. They consider customers’ future needs and explain how the recommended plan ca n help address customers’ concerns and provide peace of mind. The agent must also be honest in what the plan can or cannot do for the customer.

    Customers may have other concerns as well such as the processing of claims, plan maturity or even lapsation of policies. A well trained agent must be able to answer and address these concerns.

    Can Agents Help Me Get Claims Approved?

    A common complaint about the industry is the difficulty in getting claims when required. It does not help matters if the agent is absent or not helpful at all. Claims may be denied due to plans not covering certain aspects, or in other cases it may be due to anti-selections. This is where a person does not declare their health conditions when subscribing to a plan. Upon filing a claim, their case is studied and if found to have not declared, their claim could be denied.

    Good agents will advise customers to be honest and the onus is also on customers to do so. Customers must make timely contributions to ensure their takaful certificates do not lapse. To this end, agents will also advise customers to go through available online portals to avoid delays which could leave the customer unprotected.

    In the case where genuine takaful claims are denied, the customer can write to the takaful provider to appeal or dispute the denial. All takaful providers will act in a fair manner and review the case thoroughly before rejection. The providers are careful to ensure all legitimate claims are honoured.

    Investing into protection is a critical life decision. It is wise to engage a certified and knowledgeable person on different plans and coverage. Seeking advice from multiple agents to make more informed decisions is also good.

    About the Author

    Nazrul Namizan is Chief Agency Officer of Zurich Takaful Malaysia Berhad.

  • IRB Tax Audits And Investigations

    IRB Tax Audits And Investigations

    The Inland Revenue Board of Malaysia (IRB) conducts tax audits to ensure that taxpayers have declared the right amount of income in their income tax returns in accordance with current tax laws and regulations.

    There are two types of tax audits that can be carried out by the IRB, namely, desk audits and field audits.

    Desk audits are conducted on the supporting documents requested by the IRB from selected taxpayers in relation to the taxpayers’ business transactions and income tax paid. As the name suggests, field audits are usually carried out at the taxpayers’ premises. However, during the Covid-19 pandemic, the IRB officers have been mainly conducting desk audits to comply with the standard procedures enforced by the Malaysian government.

    The period of review for the tax audit ranges from three to five years of assessment. Cases selected for tax audits are mainly based on risk assessment, third party information, specific industries targeted by the IRB, specific issues related to taxpayers, etc.

    A tax investigation is another approach adopted by the IRB to examine documents relating to taxpayers’ business and financial matters, including their personal documents.  While there is a limited period of review for tax audits, there is no limitation as to the investigation period, but it normally covers five years of assessment based on the IRB’s current practice.

    The modus operandi of the IRB investigation officers is to carry out an inspection visit to taxpayers’ business premises, residences, tax agents’ premises and other related premises. Taxpayers may be chosen through a random selection and computer screening process.

    The basis of selection of investigation cases includes risk analysis, insider information, intelligence information and information from other law enforcement agencies. During the Covid-19 situation, the IRB investigation officers have cancelled inspection visits. As an alternative, desk investigations which are similar to desk audits are carried out.    

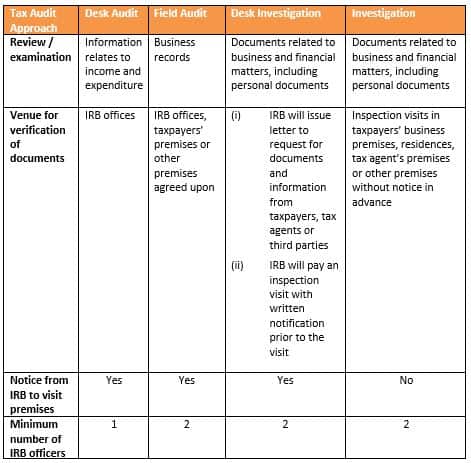
    A comparison between tax audits and tax investigations conducted by the IRB officers is as follows:

    Source: Crowe KL Tax Sdn Bhd.

    Taxpayers should be aware that a tax audit is merely an examination of records and does not imply that taxpayers have intentionally made errors in their income tax returns. Having said that, one should be prepared for a potential tax audit or investigation by keeping in mind the following information.

    Keep Sufficient Records For Seven Years

    Taxpayers are required to keep sufficient records for a period of seven years from the end of the year to which any income from the business or operations relates. This means keeping records in manual or electronic form to explain each transaction, that have enabled a true and fair profit and loss account and balance sheet to be prepared.

    Although tax audits or investigations may only involve examination of accounting records for a period of three to five years of assessment, it is mandatory for taxpayers to keep sufficient records to avoid a penalty of RM300 to RM10,000, or imprisonment of up to a term not exceeding 12 months, or both.

    Supporting Documents For Any Payments Made


    During a tax audit or investigation, the IRB officers will request for supporting documents for expenses incurred or payments made. Invoices, purchase orders, receipts or any proof of payment are essential to substantiate the expenses claimed in the tax computation.

    Otherwise, the expenses claimed will be disallowed for deduction.

    Payments Made To Non-Residents

    The payments made to non-residents such as royalty or contract payments may be subject to withholding tax. If the payment is subject to withholding tax but no withholding tax had been deducted and remitted to the IRB previously, taxpayers are not allowed to claim tax deduction for these payments.

    As such, taxpayers are advised to determine the withholding tax implications for any payments made to non-residents.

    Accruals Or Provisions For Expenses

    The deductibility of expenses depends on the nature of expenses. If an expense is an accrual amount (an amount set aside for a known expense) and taxpayers are able to provide the relevant invoices or other supporting documents, i.e. the final amounts are ascertainable, the expense will be allowed as a deduction. However, if the amount is merely an estimate and no supporting documents from a third party are available to prove the expense, the expense may be disallowed.

    Segregation Of Expenses Between Separate Business Sources

    If a business entity carries out several business activities which are distinctly different from one another and therefore treated as separate business sources for tax purposes during a year of assessment, taxpayers should be able to segregate the expenses incurred in respect of the different business sources with proper justifications.

    Taxpayers should take note that different expenses may be allocated by using different bases of apportionment to ensure that allocation of expenses between different business sources is fair and reasonable.

    Capital vs Revenue

    Tax authorities and taxpayers frequently have major contentions about whether a receipt is capital or revenue in nature. If a taxpayer has received a large lump sum of income during a year of assessment, it is important for the taxpayer to determine the taxability of the income received or obtain a tax opinion from a reputable tax consultant as to its tax position.

    An assessment of the income received based on the badges of trade or other tax principles may provide the relevant indications as to the taxability of the receipts.

    Allowance For Doubtful Debts Or Bad Debts

    It is common for business entities to make provisions for doubtful debts or write off bad debts if the trade debtors fail to settle their amounts owing due to various commercial reasons. Based on Public Ruling No. 4/2019, Tax Treatment of Wholly or Partly Irrecoverable Debts and Debt Recoveries, taxpayers are required to take reasonable steps to recover the doubtful debts or bad debts, e.g. issue letters of demand, reminder letters or other correspondences.

    Otherwise, the IRB may disallow the doubtful debts or bad debts recorded in the financial statements.

    Direct Expenses Incurred In Respect Of Other Income

    Taxpayers may receive other income in addition to the business income from their business operations. To gain maximum deduction, taxpayers may need to identify the direct expenses incurred to generate the other income as these expenses are not allowed for set-off against business income. Any adjusted loss (income less allowable expenses) derived from the other income is a permanent loss for taxpayers.

    Taxpayers will need to keep the supporting documents for direct expenses incurred because the IRB may verify these documents during a tax audit or investigation.

    If the above cannot be properly substantiated during an IRB’s tax audit, any adjustments made by the IRB would result in additional tax payable and penalties being imposed under Section 113(2) of ITA. Therefore, taxpayers should consult their licenced tax agents on the taxability or deductibility of income or expenses prior to the transaction taking place or prior to submission of income tax returns.

    About the Author

    Dr. Voon Yuen Hoong is an Executive Director of Crowe KL Tax Sdn Bhd.

  • Are Malaysian Millennials Really That Bad At Managing Money?

    Are Malaysian Millennials Really That Bad At Managing Money?

    The young and broke millennial was cast in the spotlight several months ago following comments from Finance Minister Tengku Zafrul who said that over 40% of millennials in the country are spending beyond their means. A slow but perilous path to financial ruin strewn with avocado toast, online shopping splurges and syrupy frappuccinos. 

    As a millennial myself, I’d be lying if I said I wasn’t slightly triggered by these headlines. I’d like to think that I’m a functioning young adult who is responsible. But I guess what irked most millennials was to be painted with a broad brush.

    Still, it’s something I ruminated over and asked if we’re really that terrible at managing our finances. And what I realised is that millennials as well as any generation really (e.g. Gen X, baby boomers) are products of their environment and the times they lived in.

    Our relationship with money goes beyond the personal, shaped by experiences that are distinctly our own. A millennial like myself who grew up around low interest rates and relatively benign inflation (despite our protests of price increases at the local mamak) will certainly not be conditioned to save as much as someone who grew up in 1974 when inflation was at its highest in Malaysia at over 17%. 

    If we go further back to a generation who lived through World War II and the Malayan Emergency, during times of great scarcity the need for savings was even greater. My late grandfather was frugal to a fault and never spent anything on himself beyond the bare necessities.  

    Debt Trap

    Whether anyone wants to admit it, millennials are also inheriting a fractured capitalist and hyper commercialised system that encourages debt and excess. Easy access to credit and ‘attractive’ low interest rates are pushing millennials off a cliff into a debt spiral with multiple credit cards, smartphone instalment plans and personal loans.

    There are obvious commercial reasons why credit cards and personal loans are pushed as much as possible because of the higher margins and fees. From an economic perspective, some thinkers also see the increase in household debt as positive to fuel consumption and growth.

    But for millennials growing up in the digital age being fed a constant diet of marketing ads and WhatsApp messages on the latest deals, it can be tricky terrain to manoeuvre. Financial language has evolved and marketers are more sophisticated in their targeting now.

    It is a stretch to expect all millennials with different levels of financial literacy to understand what a debt covenant or the base rate (BR) is, many of whom are unlikely to stand a chance against entrenched business and commercial interests.

    YOLO to FOMO

    Another stark difference that separates millennials from past generations is the ubiquity of technology and social media which has changed behavioural norms. The study of digital anthropology has been neatly summarised into two internet slangs over the years.

    First it was YOLO, which stands for “you only live once”. Now it’s FOMO or the “fear of missing out” which is that crippling feeling of anxiety you get from not being with the ‘in’ crowd.

    It sounds petty, but the significance of FOMO is more than just cultural. It has real meaning for millennials to be seen and accepted as well as intrinsic properties of validation. Friends would gawk and tell me how jealous they were about someone on holiday in France or the Caribbean. 

    Of course, keeping up with appearances is not something unique only to the millennial generation. However, it has certainly been magnified to pixel proportions where anything that is not picture-perfect is unacceptable.

    This often translates to bad money decisions that millennials end up spending to please others as opposed to for themselves. And you end up with unnecessary purchases without realising that most influencers on social media are sponsored by corporations with deep pockets.

    It is indirect, but cultural attitudes and how society views money is also shifting. It used to have a primarily utilitarian purpose as a medium of exchange to buy goods or services. But now we cannot even see money with the advent of online payments.

    So, what is money for now then? Unfortunately, years of generational baggage and past obsession with wealth has not led to great examples. Materialism and excess have become idealised models of success throughout the course of history.

    Money gets things done. And you do not need to be successful, but rather just look successful. These are deemed as accepted ‘realities’ of life where someone on the street is literally invisible if they do not have a cent to their name. Money makes you seen and noticed. This allure of wealth then leads many of us astray through rash investment decisions with promises of a quick buck. Even worse, some take the crooked path because they are too greedy.

    The world is changing but most millennials I know are adapting well. We are tough, savvy and have become more empowered consumers. Importantly, our values are also changing with a new generation of investors more conscious about aligning purpose and profits.

    Obviously, my experience with money is not definitive and can apply to anyone especially those living on the fringes. There are very real systemic issues concerning inequality, access and education that has to be considered towards policy formulation to ensure every young Malaysian gets a fair shot in life. But certainly, some empathy and understanding of the unique socio-cultural and technological changes that millennials go through is needed, as opposed to common wealth platitudes.

    About the Author

    Lee Sheung Un is a communications officer at Affin Hwang Asset Management. A millennial, he is still finding that balance between wealth, freedom and purpose. Views expressed are his own.

  • Will You Write A Will?

    Will You Write A Will?

    According to MWD Wills Depository Sdn Bhd, only two million (or about 28%) of the total seven million people that make up the Malaysian working population have a will.

    (Source: https://www.thestar.com.my/business/business-news/2019/06/18/only-28-of-malaysian-workers-have-a-will)

    Just like how it is never too early to plan for retirement, it is also never too early to look into writing your will – especially if you have dependents and beneficiaries. When planning your retirement, it could be worth looking into drawing up your will.

    Unlike the anxiety around continuing family legacy and providing for future generations, a will does not require extensive discussions and plans. At best, it is a legal safety net that protects assets and gives full control to you to disseminate as you please.

    Furthermore, passing on the wealth of a generation does not need to come at the expense of its retirement.

    “Caring for yourself (and not the younger generation) would be the most financially responsible thing to do,” advises Felix Neoh of Finwealth Management. However, with any excess should you outlive your wealth, this can be easily passed on with the right estate planning,” he adds.


    It is always difficult to stare down the topic of death, and most of us are reluctant to face the morbid subject of our mortality. Samantha Lim of FA Advisory believes there are plenty of benefits and considerations to writing a will.

    “If insurance and EPF nomination is important to you, why not your estate?” she questions. 

    With a proper will, you can articulate all your wishes, which can run the gamut from what you wish to give to each of your loved ones; and whether they are to benefit from the gift immediately or over a period of time.

    You can express the apportionment of your assets to each of them – whether as a measure or endorsement of your love for each of them, or a reflection of your intention to cater to their special needs or nurture their nascent talents, adds Lim.

    According to Lim, other benefits of having a will and trust includes, but is not limited to:

    • Being clear about who will get your assets, and you can work out the details down to who gets what and how much
    • Keeping your assets out of the hands of people you do not want to have them (like an estranged relative)
    • Setting up a monthly maintenance allowance for children with special needs or an aged spouse who are not capable or no longer fit to handle their own financials – by setting up a trust
    • Setting conditions such as to leave the house or property unsold until the passing of spouse or children
    • Your heirs having a faster or easier time getting access to your assets
    • Transferring of immovable assets (real property, land) to beneficiaries by way of the will, which only costs RM10 stamping for each property, saving thousands on stamp duty as compared to not having a will
    • The Declaration of Trust to handover businesses can be done in the safest and fastest way. Imagine when you are no longer around and creditors start to demand for payment. On the other hand, banks will be concerned if the key shareholder has no proper succession planning, which may affect business operation and growth. They may eventually want to review their existing lending to the business. All this may be a disaster to the business’ cashflow if credit facilities were to clawback or reduce, especially if business risk is exposed to this.

    Note: A will facilitates distribution of estate only upon death, while a trust, on the other hand, ensures access of funds without waiting for probate and can be effective immediately.

    “We should start to think about estate planning when we start owning an asset of value like property or investment, have someone financially dependent on us like a spouse, children and ageing parents,” advises Jessie Ooi, Senior Estate Planner of Rockwills.

    She also notes that when there are significant changes like marriage, birth, death, divorce or when there will be major changes to your financial situation, the Will needs to be reviewed.

    “A divorce will not revoke the existing will. So if one passes on after divorce without re-writing the will, the ex-spouse can also inherit your assets according to the will.”

     “Not all assets grow at the same pace, sometimes you might need to review and re-allocate the asset among the beneficiaries. If you want fairness in the estate distribution among the beneficiaries, you need to regularly review your estate plan,” adds Ooi.

    What Happens If I Die Without A Will?

    Lim informs that there are contingency plans set in place for Malaysians that do not have a will drawn up to ensure a legal safety net for their assets as below:

    • Assets will be distributed according to the formulas set out in the Distribution Act 1958, and not according to your wishes or the needs of family members;
    • The court will appoint a trustee and executor to administer the estate, and this may give rise to disputes between family members or beneficiaries on who should be appointed; and,
    • The distribution process will take longer and cost more, ordinarily requiring a bond and the appointment of two sureties to guarantee the proper administration of the estate, as well as further court orders to effect the transfer of real property.


  • Tax For The 6 Common Investments In Malaysia

    Tax For The 6 Common Investments In Malaysia

    Most investors swear by the saying “Never put all your eggs in one basket”. They usually invest in various types of investment vehicles by putting more money into safer types of investments rather than the riskier ones. Previously, most Malaysians chose shares, unit trusts, real estates, fixed deposits and bonds as the main vehicle to grow their money.

    Over the last few years, a range of new investment vehicles have emerged in Malaysia, namely, cryptocurrencies, peer-to-peer (P2P) financing, robo-advisors and equity crowdfunding.

    As the saying goes, there are two things you cannot avoid in life – death and taxes. This article aims to explore the tax concerns when investing into certain types of investment vehicles in Malaysia, with a greater focus on these popular, emerging investment vehicles:

    1. Shares

    Over the shoulder view of and stock broker trading online while accepting orders by phone. Multiple computer screens ful of charts and data analyses in background.

    When investing in shares or stocks, investors may focus on investing either for dividend yields or capital gains. Any capital gains on shares are not subject to tax under the Malaysian Income Tax Act, 1967 (ITA).

    However, if the activity of trading in shares is frequent enough, the Malaysian Inland Revenue Board (IRB) may treat the gain as a revenue gain which will be taxable. Alternatively, dividends distributed by a company is taxed at the company’s level as a final tax. Hence, dividend yields are exempted from tax in the hands of the shareholders.

    2. Unit Trusts

    The return on investment for unit trust holders is usually in the form of income distribution or capital appreciation which is derived from the pool of assets supporting the unit trust fund. Generally, unit holders are subject to tax on their share of the total taxable income of the unit trust.

    The distribution received by the unit holders are net of tax. In this regard, unit holders are advised to check their dividend statements to identify the Section 110 tax credit. Unit holders are entitled to utilise this tax credit to offset against any income tax payable by them. In the event the tax credit exceeds the tax liability of the unit holder, the excess will be refunded to the unit holders.

    3. Equity Crowdfunding

    Happy young Asia businessmen and businesswomen meeting brainstorming some new ideas about project to his partner working together planning success strategy enjoy teamwork in small modern home office.

    Start-ups and small-to-medium enterprises often use equity crowdfunding to raise funds from the public. The term “angel investor” is usually related to equity crowdfunding. An angel investor is generally a high net-worth individual who invests in start-ups.

    In Malaysia, angel investors are accorded tax incentives in terms of a tax exemption of up to RM500,000 per year in the second year of assessment following the year of assessment in which an investment is made. Prospective angel investors are required to apply to the Malaysian Business Angel Network (MBAN) to ensure that the eligibility criteria are met and to accredit them as angel investors (see Public Ruling 12/2020, IRB).

    4. Cryptocurrencies

    The IRB has mentioned that all cryptocurrency transactions will fall within the ambit of the ITA. The IRB referred to Section 3 of the ITA where any gains from trading in cryptocurrencies will be taxed if it is revenue in nature for the investor.

    Therefore, gains made by occasional trading in cryptocurrencies should be viewed as capital gains and under the local tax law, capital gains are not taxed.

    With that said, the Malaysian tax authorities have recently updated its Guideline on Taxation of Electronic Commerce Transactions in 2019 to include digital currency under its scope of charge. This now effectively allows the IRB to collect revenues generated by cryptocurrency trading.

    With the absence of any provisions in the Malaysian tax law on taxing virtual assets, investors involved in digital currency activities are strongly advised to keep their transaction records and any relevant documents for seven years in case of a tax audit.

    5. P2P Financing

    Millennial Asia businessmen and businesswomen having conference video call meeting brainstorming ideas about new project colleagues working together planning strategy enjoy teamwork in modern office.

    P2P financing is akin to traditional borrowing with the exception of a financial intermediary such as a bank or financial institution. Therefore, the subject of concern in P2P financing will be the interest earned. So will the interest income be subject to tax? Yes, the interest earned is taxable for both Malaysian resident and non-resident investors.  

    What is the tax treatment on your P2P interest earned? While Malaysian resident investors will need to declare the interest earned as interest in their annual income tax returns, the P2P financing operators will directly deduct 15% withholding tax at source for non-resident investors.

    6. Robo-Advisors

    Certain investors prefer to simply let a third party handle the investment aspect of their money. This is possible with the existence of robo-advisory platforms which use algorithms to allow an investor’s portfolio management to be automated.

    Robo-advisor platforms typically invest in exchange traded funds (ETFs) which are a compilation of stocks, bonds and other investments. Furthermore, most robo-advisor platforms in Malaysia tend to focus on foreign ETFs.

    Investors should be aware that the dividend yields from trading in foreign ETFs may be subject to withholding tax depending on the jurisdiction of the ETF. The distributions received from the foreign ETFs will be exempted from tax in Malaysia as it is considered a foreign source of income.

    About the Author

    Shanthini Parama Dorai is a Tax Senior Manager at Crowe Malaysia PLT. Crowe Malaysia PLT is a member firm of the Crowe Global network of independent accounting and advisory services firms. She can be contacted at shanthini.dorai@crowe.my.

  • What Cooking Taught Me About Financial Planning

    What Cooking Taught Me About Financial Planning

    During the COVID-19 lockdown period, I took charge of cooking meals for my family as a measure to keep me sane, as well as to further explore my interests. In the process of thinking about what to eat every day, prepping meals, and getting feedback from my ‘patrons’. I observed there are parallels between cooking and financial planning. 

    Here are some of my findings listed down below:

    Prepare With The End In Mind

    Allow me to quote a little something from one of my favourite fairy tales: – 

    “Alice asked the Cheshire Cat, who was sitting in a tree, “What road do I take?”

    The cat asked, “Where do you want to go?”

    “I don’t know,” Alice answered.

    “Then,” said the Cat, “it really doesn’t matter, does it?”

    ― Lewis Carroll, Alice’s Adventures in Wonderland

    If you do not have a clue about what to cook next, you might as well just order takeaway. You need not plan for a grand Turkish all-day breakfast, or a Han Banquet unless you are in the mood for it. Knowing what to cook can be as simple as saying we will be having fish, vegetables, and tofu for our meal.

    If you can say we will be having chorizo con patatas (Mexican style sausage with potatoes), even better!

    The same goes for financial planning, as without an end goal, you might end up in some place you may not like. With a goal in mind, there is a good chance, you may actually like the destination. It is always better to have a general sense of where you are heading towards. Once the destination is clearly defined in your mind, the rest of the puzzle will fall into place. 

    Get The Right Tools For The Job

    Have you ever tried frying eggs with a non-stick pan, or cutting meat with a serrated blade? An amateur chef in the home kitchen should be aware what is the best tool to use for the task at hand. You would only need to improvise if you do not have the right device needed in your arsenal for a specific dish.

    In financial planning, planners often match the tools to the objective – liquid short-term tools for funds that need to be accessed within a reasonable time frame. For every purpose, there will be something that matches your needs.

    The challenge here is whether you know someone trustworthy that has your best interests at heart that you can refer to. Knowing this, I am sure you would not choose to buy life insurance plans for the purpose of retirement savings, right?

    Ask The Professionals

    When I am dealing with an unfamiliar ingredient or new method of cooking, I seek help from the pros. In my case, this would be my lovely grandmother. Her years of experience in the kitchen is a blessing for young budding cooks like myself. As you cook, you realise there are a lot of variables like how thick the meat must be sliced, how long to steam the fish, how much salt to add into the soup etc.

    Often, I must interrupt her TV viewing session to get her into the kitchen to ask questions or help me with a taste test. Even if I bring in exotic ingredients like Thai vermicelli or guanciale (cured pig’s cheek), she would have an idea about how to prep it for cooking.

    Professionals know best about how to handle certain situations that pop up and will guide us accordingly on what to do next. It is the same with financial planning; it would be good to have a panel of professionals in your contact list that you can always refer to.  

    Do Your Research

    When inspiration strikes me for what to cook next, I do not just buy the ingredients and get down to business. I will always watch a few videos and search online for an ingredient list. It would be courting disaster if I just jump over the proverbial cliff and wing it without any prior knowledge of what I am attempting.

    As we do our research, especially from online sources, we may also find many ways and methods to produce a dish. Not all will carry the same experience and cost, or require the same amount of time. Likewise, when we try to learn about personal finance online, we also need to be mindful about the source, and if it is comprehensive or contains any limitation in points of view.

    Before committing to any financial products, it is good to always do some research about what you are buying. There will always be a product disclosure sheet or a similar document to read through in a language we can all understand – government institutions like Bank Negara Malaysia or Securities Commission Malaysia makes sure of that! We can also read articles or watch video reviews about these same products by service or education providers.

    Review, Review, and Review

    Every time I serve a dish, I would get feedback from my family members on what they think about it. I would do so even if I am serving the dish for the fourth time! This helps me further refine my recipe over time.

    Usually, when clients buy a financial product, they then quickly forget about it. I believe a yearly review of finances is required to refresh what was discussed previously, and whether the current action plan is sufficient or not. A review will not necessarily mean there will be a need to buy or do something new. However, it keeps you aware of the progress made over the years. 

    What other similarities can you see between cooking and financial planning?

    About the Author

    Raymond Chan, CFP CERT TM is a licensed financial planner that believes with the right guidance anyone can achieve what they set out to do. All they need is to have a goal in mind and a nudge in the right direction. He can be reached at raymondchan@vka.com.my.

  • What Protection Does A High-Net-Worth Individual Needs?

    What Protection Does A High-Net-Worth Individual Needs?

    Insurance plans for high-net worth individuals are often beyond what is available to the everyday man.

    For many Malaysians, the importance of insurance is drilled into their minds early on in their lives or careers, and it is likely that most have a friend or relative that is an insurance agent. However, in terms of pure numbers, insurance penetration in the country is still low.

    A survey commissioned by Zurich Malaysia last year showed that 38% of Malaysians remain uninsured; another survey conducted by the Health Ministry in 2020 found that only 22% of Malaysians had personal health insurance.

    According to Dennis Chin, director at Harveston Wealth Management, life insurance needs usually start with self-protection such as medical cost and critical illnesses, which is then followed by financial security for family such as family income protection and credit protection.

    And while it may be the norm to be uninsured, for high-net-worth individuals (HNWI), this is likely to border on sacrilege!

    “For HNWI, the abovementioned is essential as well even though they have more financial resources to take care of the medical bills and family income need,” says Chin.

    He adds that the typical insurance planning for such individuals goes beyond personal risk as there are often other assets and collateral that may be used as guarantors in business borrowings, for example if a key person in the business suddenly leaves.

    “These borrowings will risk their personal assets being used for paying off in the event of sudden departure of the key person in the business or guarantor for the loan.”

    Protection For HNWI

    The main difference when it comes to insurance coverage for HNWI usually comes down to two things – the required sum assured and the type of risk.

    If the person requires RM10 million in life coverage, insurance plans can come in the form of offshore universal life policies denominated in US dollars while also being more cost efficient. Such offshore policies are not accessible to lower/middle income individuals as the minimum sum assured is usually beyond reach, often starting at US$500,000 and above.

    dennis chin harveston hnwi“This type of plan may offer different health and financial underwriting requirements which are offered differently by insurance companies locally,” says Chin.

    He shares that “asset protection is also essential” for HNWI as they tend to own wide varieties and classes of assets. Typically, such assets would include real estate, jewellery, or art collections to name just three. Often, these may also make up the bulk of their net worth.

    For example, a standard house insurance will not hack it when it comes to covering a bungalow that is constructed with exotic woods and expensive, custom-made furniture and fittings. Special coverage will be required for such a home in the event of fire or burglary explains Chin.

    “Therefore, the scope of insurance needs for HNWI is much wider than lower- and middle-income individuals,” he adds.

    Healthcare is another area in which HNWI are usually well-covered in. For those that travel regularly around the world, international medical coverage is key in order to counter the risk of being forced to seek medical services in a foreign country.

    “This type of medical plan comes with high medical limit in US dollars and the premium is also payable in US dollars as well,” he shares.

    “It also provides peace of mind while travelling globally as usually it comes with services on international consultation for medical services and evacuation back to their home country.”

    For The Next Generation

    HNWI with highly sought-after professional skills may also choose to take “future economic value” into consideration when setting up their life coverage. For example, in the event that a person is no longer able to work through total or permanent disability, or death, this will ensure that his or her projected earnings over a set number of years will be paid out to the family.

    There are notable examples of celebrities doing this, such as footballer Cristiano Ronaldo getting insured for £90 million in 2009, while singer Taylor Swift reportedly insured her legs for US$40 million in 2015.

    Chin explains that utilising insurance as a tool for wealth management is not a foreign concept to HNWI, with family trusts and family offices usually set up for wealth preservation for the benefit of the next generation and even beyond.

    Insurance For Wealth Creation

    Once the basic protection needs covering medical costs or critical illnesses are in place to ensure future financial security for HNWI, “a large sum assured is usually a tool in wealth management for wealth creation” Chin says.

    Alvin Yap, managing director at A.D. Financial, adds, “For family offices, insurance is also treated as a tool for estate planning, risk diversification and even wealth creation.”

    He gives an example on how a patriarch owning several offshore real properties may purchase life insurance with proceeds to cover any tax liabilities (e.g. inheritance tax, etc.) upon his demise, ensuring that the offshore real properties will be transferred to his family office smoothly after his passing.

    Using another example, he says, “Let us assume a matriarch purchases life insurance and makes it a point that the family office will manage and invest the insurance proceeds which will be treated as an education fund for many generations to come. She bequeaths her personal wealth to her children and her family office manages the insurance proceeds (education fund) upon her demise.”

    The mechanics of a family trust makes it useful for liquidity purposes as “insurance proceeds will be paid directly to the family trust”, providing an immediate source of cash flow to beneficiaries of the trust as opposed to individual nominees.

    “This is because in the event the nominee does not survive as well, the insurance paid out will fall into estate which can only be used after obtaining grant of probate,” highlights Chin.

    This can also help to prevent any squabbles among beneficiaries when the head of the family passes on. It is not uncommon to hear of huge lawsuits which entail siblings and other family members fighting in court to claim their piece of the pie. Hence, in most families, there will be a need for such a structure to be in place.

    To illustrate this point, Chin uses a scenario where there are multiple properties to be passed down to several beneficiaries.

    “What if these properties are not identical and each of them carries a different value? This might create some issues about fairness whereby the value of inheritance of each beneficiary is not the same,” he says.

    “In this case, a method of wealth equalisation can be adopted by buying life insurance that eventually creates the cash to compensate those beneficiaries that inherited lower value properties.”

    Charitable Endeavours

    Apart from taking care of their families, many HNWIs also engage in the practice of philanthropy through monetary gifts or donations to those in need, utilising the mechanics of life insurance to achieve this purpose.

    “Apart from donating existing resources and funds, such as allocating a pre-determined amount of profit from businesses, one can plan by using life insurance proceeds to make charitable donations,” explains Chin.

    “There are many family offices which have a foundation in place for philanthropy purposes, consisting of existing assets and cash, as well as life insurance.”

    “By paying premiums from existing resources every year, this eventually increases the assets in the 

    foundation by claiming the sum assured for charity purposes which can help more people,” he adds.

    What Are Family Offices?

    HNWI often have a family office to manage their financial affairs, but not much is known to the general public. We speak to Alvin Yap, managing director at A.D. Financial, to learn more.

    alvin yap a.d. financial hnwi

    Smart Investor: Can you describe how the various structures of family offices work?
    Alvin Yap: Family office is originally from the concept of preserving generational family wealth for European royalty and it is increasingly popular among high and ultra-high net worth Asian families. However, there is still much puzzlement as to what defines them and their primary functions.

    Briefly, a family office is about effectively preserving, growing and transferring wealth across generations. It can be treated as a legal entity that houses professionals in various areas such as administration, legal, investment, corporate finance, real estates and so forth to achieve the abovementioned primary functions. Some family offices are more investment oriented; others could be driven by philanthropic causes. In terms of establishments, there is single-family office servicing one individual family and also, multi-family office that service several families benefiting from economies of scale.
    SI: Can you explain the role that insurance plays in family offices as a form of generational wealth management or preservation?
    AY: Primarily, insurance is used to mitigate financial damages caused by loss of life or properties. For family offices, insurance is also treated as a tool for estate planning, risk diversification and even wealth creation.
    SI: How do you determine the type and amount of insurance coverage that different family offices require?
    AY: It can be complex but it all boils down to family business needs and family lifestyle.

    In Malaysia, term life insurance can be purchased as keyman insurance, meaning insuring the key person such as the owner or someone who is critical to the business; some family offices will source for offshore term life insurance that comes with a lower premium. There is also a variety of universal life insurance that offer very low initial cash outlay for insurance premium or options to fund the premium with movable/ immovable assets and many other flexible premium financing features. Family offices take advantage of these features and purchase universal life with very high insurance coverage.