The much-publicised ‘Great Resignation’ appears to be more muted in Southeast Asia, based on the latest survey from global recruitment firm Robert Walters.
Professionals in the region are valuing job security during uncertain times, with more than half (59%) indicating that they are uncomfortable to quit without a new job offer, and 81% of those who have thought of resigning are willing to change their minds, if conditions are right.
In addition to job security, professionals in Malaysia highly value salary package, good leadership and healthy workplace culture. These are contributing factors that will retain talent.
Hiring new talent remains challenging in Southeast Asia, especially in Malaysia which saw 83% of companies finding it more difficult to do so in the past year. High expectation on salary and benefits was cited as one of the biggest challenges for sourcing talent, at 66%.
These are among the key findings of the Robert Walters Great Resignation Reality Check that canvassed the insights of over 2,600 professionals and more than 1,100 companies, to better understand the attitudes held towards resignations, staff turnover situations, and unlock retention motivators. It was conducted in June 2022 and spanned six Southeast Asian countries (Singapore, Malaysia, the Philippines, Thailand, Indonesia and Vietnam).
Job-switching instead of resignations While 79% of professionals surveyed across Southeast Asia had the intention to resign in 2021, close to half (42%) have yet to do so.
Malaysia saw the most professionals (82%) who have thought of quitting their job in the past year, followed by Singapore (80%) and Thailand (80%). However, 62% of professionals in Malaysia will not quit without a better opportunity lined up, just slightly behind Singapore (64%).
“Rather than a ‘Great Resignation’, businesses can expect an accelerated hiring market across Southeast Asia in the coming year. Professionals are not quitting on a whim, but rather, they are looking to move between jobs. In the face of a possible recession, we expect more cautious professionals, who would only move when they have another job offer on hand,” said Gerrit Bouckaert, Managing Director, SEA, Robert Walters.
Malaysia: Positive work culture including good leadership, and flexible work arrangements are highly favoured by employees
Of the 82% professionals in Malaysia who considered resigning in the past year, 39% eventually stayed on because they have not found a new job yet (58%), are uncertain over new workplace’s culture and suitability (26%), and are concerned about job security at a new company (25%).
About 4 in 5 professionals (81%) would reconsider their intention of resigning if conditions are right. While salary increment continues to be the main determinant, changed job responsibilities (26%) and a change of leadership (24%) are the other crucial factors that will make them change their minds.
In view of this, employers have stepped up efforts in taking necessary measures to retain staff, such as matching or increasing salaries (58%), offering training and upskilling opportunities (56%) and providing a clear pathway for career development (44%). However, almost half of the professionals (45%) mentioned that they were not aware of changes made by their employers, indicating a gap in the retention initiatives by employers.
A staggering 86% professionals also revealed that they have re-evaluated their other life aspects when it comes to career, now prioritising their mental and physical wellbeing (76%). Other notable areas include time spent with their loved ones (70%), and the meaning/fulfillment of their jobs (68%).
This corresponds to this year’s findings by Malaysian Employers Federation, noting that many employers are now adopting Flexible Work Arrangements (FWAs) to cater to employees’ evolving needs such as having work-life balance, physical and emotional health.
Apart from work flexibility, colleagues and culture that inspire employees to do their best are what professionals value most in an employer (43%). This ranked slightly above compensation and perks (41%).
Other findings include:
In addition to high salary and benefit expectations (66%), high competition for candidates (55%) and lacking industry experience (44%) are the biggest challenges employers face when hiring talent.
87% of companies think employee turnover/resignations in their organisations have increased in the past year.
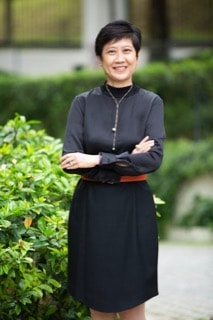
Ai Rene Tan, Country Manager of Robert Walters Malaysia
Ai Rene Tan, Country Manager of Robert Walters Malaysia comments:
“Positive employee experiences have never been more important in today’s work environment. Recognising and rewarding strong talent, job security and meeting employees’ desire for better well-being are important to attract and retain talent. Good leadership and positive workplace culture will also make a critical difference in the hiring of new talent.”
Robert Walters is one of the world’s leading specialist professional recruitment consultancies and focuses on placing high-calibre professionals into permanent, contract and temporary positions at all levels of seniority. The Malaysia office specialises in placing candidates on a permanent basis in the following disciplines and industries: accountancy & finance, banking & financial services, executive search & senior management, engineering & manufacturing, human resources, tech & transformation, legal & corporate secretarial, sales & marketing, healthcare & life sciences and supply chain, procurement & logistics. Established in 1985, the Group has built a global presence spanning 31 countries and regions.
We always hear about the rich helping out the poor and it is normally done out of compassion and as a way to express gratitude for all the blessings that one receives throughout his life.
Rather than getting rich and enjoying the wealth on your own, sharing it with others will put a smile on others and alleviate whatever ills and hardship that they are currently facing.
Are you still confused with the terms Zakat, Sadaqah and Waqf?
What Is Zakat, Sadaqah And Waqf?
Zakat
As one of the pillars of Islam, Zakat is a form of obligatory charity that has the potential to ease the suffering of others. With the literal meaning of the word being ‘to cleanse,’ Muslims believe that paying Zakat purifies, increases and blesses the remainder of their wealth.
It is a wealth tax and a means of wealth distribution, harmonizing the relationship between the individual and public interest. Each year, Muslims are required to donate 2.5% of one year’s total cumulative wealth to the poor in the form of Zakat.
There are eight categories of zakat recepients as stated in the Al-Quran.
Those living without means of livelihood
Those who cannot meet their basic needs
To zakat collectors
To persuade those sympathetic to or expected to convert to Islam, recent converts to Islam, and potential allies in the cause of Islam
To free from slavery or servitude, slaves of Muslims who have or intend to free from their master
Those who have incurred overwhelming debts while attempting to satisfy their basic needs, debtors who in pursuit of a worthy goal incurred a debt
Those fighting for a religious cause or a cause of God, or for Jihad in the way of Allah by means of pen, word, or sword, or for Islamic warriors who fight against the unbelievers but are not salaried soldiers.
Wayfarers, stranded travellers, travellers who are traveling with a worthy goal but cannot reach their destination without financial assistance
Waqf
It involves donating a fixed asset which can produce a financial return or provide a benefit. Is is an endowment to a religious, educational or charitable cause, most frequently used to build schools, hospitals or religious institutions. Given its communitarian nature, Waqf is often used to fund social projects and services.
It literally means to stop, contain, or to preserve. This philanthropic activity has become one of the catalysts for Muslims’ economic activities over the centuries including Malaysia.
Sadaqah
Sadaqah means voluntary offering, whose amount is at the will of the “benefactor”. It is voluntary charity given on an ad-hoc basis; a concept similar to putting coins into a charity donation box.
Giving Sadaqah does not mean being rich and able to give money to the poor and needy. There are many types of Sadaqah.
Spreading knowledge is Sadaqah
Sharing food is Sadaqah
Giving your time and energy to a good cause is Sadaqah
Saying a kind word, even smiling is also considered as Sadaqah
Still Confused With Zakat, Sadaqah And Waqf?
Zakat is the obligatory form of charity, whereas Sadaqah is voluntary.
For example you make a profit of RM50,000 from your investment for the year 2021, therefore you need to pay zakat of 2.5% of the total profit, which is equals to RM2,500.
But it is up to you how much you want to give for Sadaqah. You can also choose not to give Sadaqah.
Whereas Waqf is losing the ownership and management of the property/wealth from the giver to be used for a good purpose or the profit from it, to be used for a good purpose.
For example you have a empty house. You give permission for an administrator to manage the house to rent it out for free to students. Or if you allow the administrator to rent out the house, then the monthly rent is being used for a good cause.
Hope you now have a better understanding of what Zakat, Sadaqah and Waqf is all about, as well as its differences.
Over the years, Malaysian corporations have grown and expanded their business footprint, not only to neighbouring countries, but also to other continents in many parts of the world. It is not uncommon to see many Malaysian companies receiving income from their business and investment ventures in foreign countries, hence we need to understand about the issue of tax on foreign income.
These income sources include sales from exports of goods and services, dividends and interest income from foreign investments, royalty fees from licensing of intangible assets, rental from properties located overseas, and commission from acting as agents.
Generally, income received from out of Malaysia has been exempted from tax. However, in the Budget 2022, the Government announced removal of the tax exemptions on such income.
The rationale quoted for the removal, other than a measure by the Government to raise revenue collection, is that it is a step taken by the country to comply with the global tax standards on harmful tax practices.
Tax On Foreign Income
Malaysia adopts a territorial principle of taxation in that only income accruing in or derived from or received in Malaysia from outside Malaysia, is subject to income tax in Malaysia pursuant to Section 3 of the Income Tax Act, 1967 (ITA). Nevertheless, Malaysian tax residents enjoy tax exemption on the “income received in Malaysia, from outside Malaysia”, also called foreign sourced income (FSI), under Paragraph 28, Schedule 6 of the ITA (Para 8).
In short, while the FSI received by Malaysian tax residents are taxable under the Section 3 of ITA, the amount are exempted under Para 28. (Note: the exemption excludes those engaged in banking, insurance or sea or air transport businesses)
However, not all FSI income received are exempted as it has to be truly “sourced from outside Malaysia”.
Generally, whether the income is sourced within or outside Malaysia would depend on the location where the related income-generating activities had taken place. For example, export sales of goods by a trader are not exempted because the personnel who carried out the various business functions are located in Malaysia.
In contrast, it is argued that interest income from investment funds placed and managed outside the country is foreign sourced and thus, exempt under Para 28.
Tax Treatment On FSI From 1 January 2022
Effective 1 January 2022, the tax exemption for FSI received by Malaysian residents provided for under Para 28 was removed, following the Budget 2022 made on 29 October 2021. The implementation of the legislation is staggered into two remittance timeline of FSI into Malaysia:
January to June 2022 @ 3%:
Taxpayers are given this 6-months transitional period to remit their foreign sourced income in order to enjoy the lower tax on foreign income rate of 3% calculated on the gross income remitted (Part XX, Schedule 1 of the ITA)
Subsequent to 30 June 2022:
Remittance will be subjected to the normal tax rates.
In summary, the tax treatments for the income of a person residing in Malaysia are depicted as follows:
Special Remittance Programme Terminated
In November 2021, the Inland Revenue Board of Malaysia (IRBM) introduced the Special Income Remittance Programme (Program Khas Peremitan Pendapatan or PKPP) to help taxpayers in the transition to the new FSI regime.
The FSI remitted during the PKPP period (between 1 January 2022 and 30 June 2022) would be accepted in good faith by the IRB without any audit nor investigation be conducted on the taxpayer. In addition, there will be no penalties imposed for the remittance during the PKPP period.
However, this programme is shortlived and was revoked on 11 March 2022, as it is deemed not relevant, after the Ministry of Finance (MOF) announced in December 2021 on a concession to exempt certain categories of FSI for a period of five years from 2022 to 2026.
Concession: 1 January 2022 – 31 December 2026
The removal of exemption under Para 28 has been highly debated and criticised with regard to, among others, its timeliness of implementation, vagueness on the scope of FSI, and lack of clarity on claiming of double tax relief if the income had suffered foreign tax.
It is also seen as a stumbling block to attract foreign direct investment (FDI) in Malaysia, thus affecting Malaysia’s competitive position in the global trade map.
On 30 December 2021, MOF made an announcement to defer the full implementation of the new Para 28 to 1 January 2027. The official rules were issued by the Government by way of exemption orders dated 19 July 2022, in the Income Tax (Exemption) (No.5) Order 2022 and Income Tax (Exemption) (No.6) Order 2022 (“Exemption Orders”), applicable to individuals, partners in conventional partnerships, limited liability partnerships (LLP) and companies.
The exemption period granted is from 1 January 2022 to 31 December 2026.
Individuals are exempted on all categories of income including income from employment, dividend, rental and interest. Meanwhile companies and LLPs are exempted on foreign dividend income only.
However, there are the preconditions set in the Exemption Orders to qualify for the exemption during the fi ve years concession period, whereby:
FSIs received by individuals, LLPs and companies “shall have been subjected to tax of a similar character to income tax under the law of the territory which the income arises”.
For foreign dividends received by individuals from conventional partnerships, LLPs and companies, the added condition is that “the highest rate of tax of a similar character to income tax charged under the law of the territory which the income arises at that time is not less than 15%”.
IRBM is to issue the relevant guidelines on the applicable tax treatments, which are yet available at the time of writing. Clearly, taxpayers will need to meet certain conditions to enjoy the tax exemption during the five years concession period as it may not be as straight forward to qualify.
The limelight is now on the IRBM to expedite the issuance of the relevant guidelines, which are expected to provide the much-needed administrative details surrounding the reporting of FSI, including documents required to provide evidence for exemption of FSI, tax calculations of non-exempt FSI, the claiming of double taxation relief on FSI, especially foreign dividends, etc.
Tax Exemption Of FSI From 1 January 2022 To 31 December 2026
Taxable FSI Received By Corporate Investors
For now, FSI other than dividend income received by Malaysian corporate tax residents will be subject to tax in Malaysia. Notably, where the foreign dividends are received by a legal corporate structure other than a company incorporated under the Companies Act 2016, there is no exemption provided during the 5 years period on the income.
A list of the more common situations of tax on foreign income is set out below:
Common Situation Of Taxable FSI
Double Tax Relief On Foreign Tax Suffered
The tax on foreign income received in Malaysia may be reduced by the foreign tax credit paid. Where a Malaysia tax resident has suffered foreign tax on the FSI, the taxpayer is given bilateral or unilateral tax credit relief against the Malaysian tax payable on the same FSI.
Bilateral relief is given under Section 132 of the ITA when the foreign country has a double tax agreement with Malaysia eg Singapore, Indonesia, Japan, China, Australia, South Africa, United Kingdom, France, etc. Under a double tax agreement, a full relief may be possible based on the calculation of a prescribed formula, but the relief amount is only up to the Malaysian tax suffered.
On the other hand, unilateral relief is given under Section 133 of the ITA when there is no or limited double tax agreement by Malaysia with the foreign country eg British Virgin Islands, Taiwan, United States of America, etc. For such relief, the foreign tax recognised is automatically halved.
One is required to substantiate the amount of tax paid overseas with the relevant supporting documents from the tax authorities in the foreign countries, in order to claim the aforementioned tax relief in their tax return.
Capital Receipts Are Non-Taxable
The tax on foreign income will only affect gains that are “income” in nature. Receipts that are “capital” in nature (also known as capital gains) will not be subject to Malaysian tax. Capital gains include proceeds from the disposal of foreign stocks, foreign properties, foreign assets, foreign currencies, and foreign investment papers. However, these assets have been held as long-term investments.
Whether the gains are “income” or “capital” in nature, the onus of proof lies with the taxpayers. If the remittances are found to be income in nature instead of capital as claimed by the taxpayers, the same shall be subject to income tax.
Action Plan
The year 2022 marks an impact on investors with foreign asset holdings, in navigating a new tax landscape going forward with the removal of tax exemption under Para 28. The imminent measures include evaluation of the financial returns on their existing overseas investments, net of all tax costs. In sourcing new investment opportunities overseas, such investors shall need to factor in the additional tax costs in Malaysia.
Here are a few suggestions on the action that affected investors should look into:
1) Review the Malaysian tax impacts on all taxable FSI from investments outside Malaysia- tax simulations may be useful for the investment selection process.
2) Maintain proper records of the foreign assets, including tracking of the funds retained in foreign bank accounts vis-à-vis those repatriated to Malaysia. On the amount remitted into Malaysia, ascertain the nature as to whether they belong to “income” or “capital”, which will have different tax implications.
3) Where the funds are mixed, distinguish between foreign source income and domestic source income for proper reporting of taxable income for Malaysian tax purposes.
4) Conduct a comprehensive review of the current investment structure and strategise the most optimal approach to undertake future investments. This review may involve international tax planning to mitigate tax exposure involving multiple countries.
5) Examine the existing intercompany loans and undertake possible steps, including debt restructuring exercises, or rescheduling repayments to reduce the tax impact on remittance of interest income into Malaysia. On this note, any proposed changes will need to include transfer pricing considerations to avoid tax pitfalls in the future.
If guidance is required on the issue of tax on foreign income, consider seeking professional advice from a tax consultant. This would help you avoid stepping into potential tax landmines that could be uncovered in the future, when the company is audited by the IRBM.
The renminbi has depreciated by about 8% against the US dollar so far this year and, at RMB6.96 per US dollar, is already homing in on our year-end target of RMB7 per US dollar.
China’s central bank, the People’s Bank of China (PBoC), has begun to resist further depreciation, cutting its reserve requirement by two percentage points to 6% last week and setting the daily fix for the official exchange rate at stronger-than-expected rates in recent days. But with the US dollar still surging and probable recessions in most developed markets set to weigh heavily on external demand, there is a clear risk that the exchange will overshoot to somewhere in the region of RMB 7.10-7.20 per US dollar.
A weaker renminbi is often associated with delivering a deflationary impulse to the rest of the world. After all, as the currency depreciates, imports of Chinese goods become cheaper for the rest of the world. So has the recent depreciation of the renminbi relieved pressure on global central banks in their quest to tame inflation?
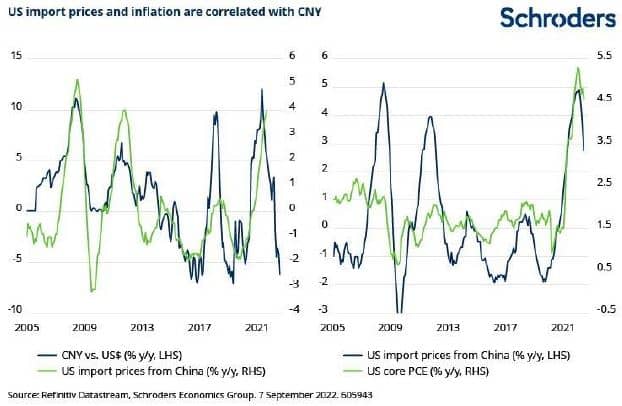
There certainly does appear to be a link between movements in the renminbi and rates of inflation experienced by its trading partners. For example, as the charts below show, US import prices from China fluctuate with the exchange rate. And these import prices are closely correlated with core goods inflation in the US. This makes intuitive sense, and similar relationships are observed in other economies, such as the eurozone.
However, there are a couple of reasons to doubt that renminbi depreciation has solved the global inflation crisis.
For a start, the correlation between currency movements and prices only applies to the core goods portion of inflation in other countries.
The renminbi has no major impact on other key drivers such as owners equivalent rent, local services or indeed international commodity prices, all of which account for the bulk of inflation in markets such as the US.
As such, the relationship between the renminbi and headline inflation, in this instance in the US, is relatively weak, with several periods of currency volatility failing to follow through into headline inflation.
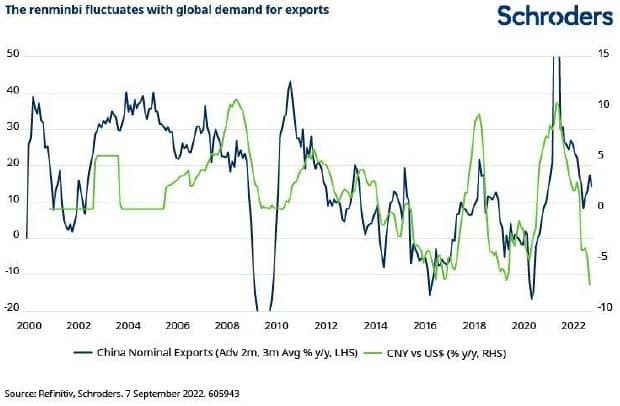
More generally, we need to be careful about assuming that correlation means causation. After all, the renminbi tends to be very cyclical. When exports are growing strongly, the currency tends to appreciate, and when exports are coming off – as is the case now – the currency tends to depreciate. And, of course, when global demand is strong, China’s exports are performing well, and the renminbi appreciates, firms can pass on higher costs to consumers and fuel inflation.
On this basis, global inflation dynamics are still a function of the strength of demand and movements in the renminbi are largely a by-product of its impact on trade. Indeed, an expected slowdown in exports as demand for manufactured goods softened has been a key reason for our bearish view of the renminbi since the start of the year.
The upshot is that, barring an unlikely large one-off depreciation, the weaker renminbi neither significantly changes global inflation dynamics nor needs developed market central banks to keep raising interest rates.
About the Author
David Rees, Senior Emerging Markets Economist, Schroders
As more consumers embrace digital banking and faster, simpler ways to send money, it has created opportunities for fraudsters and increased the risk of digital fraud in Malaysia, particularly fuelled by the adoption of real-time payments.
Smart Investor recently got in touch with CK Leo, FICO’s lead for fraud, security and financial crime in Asia Pacific to find out his views.
CK Leo, FICO’s lead for fraud, security and financial crime in Asia Pacific
Smart Investor: What are some of the growing fraud threats that consumers need to be more aware of?
CK Leo: According to Malaysia’s Commercial Crime Investigation Department, the top fraud threats reported this year include impersonation scams, e-commerce crime, and phishing, which could lead to account takeovers and unauthorized transactions. At the same time, consumers should be mindful of Authorized Push Payment (APP) fraud, where fraudsters manipulate consumers or individuals at a business to transfer money to a bank account controlled by the fraudster.
APP fraud is rising globally, fueled by the adoption of real-time payments, such as DuitNow in Malaysia, which enables fraudsters to flee with the money at speed.
Threats such as APP fraud are particularly difficult to detect and prevent, and show how traditional safeguards such as authentication checks, a common security measure used by banks in Malaysia, are insufficient in protecting customers.
One tool that can be used to help protect real-time payments is to use analytics that look for changes in customer behavior, such as using accounts or devices outside of their usual habits, as well as standard anomalies, such as time-of-day or frequency of a transfer. FICO has found that the use of targeted profiling of customer behavior to spot scams has yielded some impressive results, with 50 percent more scam transactions detected.
SI: Why do we still fall for investment scams, when there are a lot of legitimate investments out there?
CKL: The answer is that people want to believe that there are easy ways to make money. We are influenced by social proof in the media and online with stories of overnight crypto millionaires, stock wizards and real estate moguls. The pandemic helped to super charge the problem, as people spent a lot more time online, unable to go anywhere or spend money.
While in this state many were enticed by greed and schemes peddled by scammers that promised easy money. It is, however, worth remembering that with a clever amount of social engineering used against us, anyone can become a victim of fraud. Some schemes out there are very sophisticated at mimicry of real investment companies, setting up spoof websites and advertising on Google to attract potential victims.
Although banks and authorities are in a constant race to update and upgrade their security measures, this is simply not enough to prevent all investment fraud. There is a paramount need to educate consumers on new and emerging threats and what checks to make before investing.
SI: What are the driving factors for the rise in fraud in recent years?
CKL: Today’s technology has enabled fraudsters to undertake globally pervasive scams with shocking ease, constantly shifting in approach to find new vulnerabilities. Malaysia’s digitally savvy population and banking penetration of 92%, is expected to grow significantly in the coming years and along with it the opportunities for scammers. Criminals are attracted to both the increase in money flows and the growth in the number of inexperienced users.
Fraudsters have also been making use of technology to scale up both the complexities and the scope of their operations. Automation and bots, for example, have been exploited by criminals to gain data and create fake consumer identities for application and card fraud. In Malaysia, scammers have even created their own applications to trick consumers into giving up valuable personal information.
So, the driving factors in fraud growth are that technology has enabled the reach, scope, volume and low cost of creating scams. While a growth in digital services has increased the attack surface and the number of less educated users as well. Plus, the honeypot, or the sheer amount of money that can be made from online crime means there is an arms race going on.
For banks, this means staying on top of their banking security game and evolving to prevent new fraud types like the growth in real-time payment fraud.
SI: How must banks’ fraud detection and prevention strategies change to minimize fraud risks?
However, this verification method can be easily compromised, through scams like SIM swap fraud. Banks will need to consider more robust or multiple factors of authentication for a layered approach to security. This includes tools available to them, such as biometric authentication, a method FICO found a preference for among Malaysians.
The reduction of information silos is equally key. Banks with different solutions for transaction monitoring and fraud must remove these separate silos and work collaboratively to create an integrated solution able to read data holistically, leading to timely detection and the prevention of fraud.
Thirdly, consumer education must remain a top priority for banks. Banks must maintain regular communications with their customers to assist them in preventing fraudulent transactions. They can do this by encouraging customers to keep their contact information updated to receive timely fraud alerts.
These three approaches can be realized through advanced analytics which enable real-time decision-making to prevent fraudulent attacks from taking place.
In contrast to siloed, single-focus solutions, an integrated, enterprise-wide fraud platform enables banks to have a more comprehensive approach to minimizing fraud risks. Banks will be able to dynamically adapt to emerging fraud types, while using machine learning models based on targeted profiling of customer behavior to separate between fraud, scam and normal behavior.
This shift away from siloed solutions also enables banks to choose the best channel when communicating with customers to ensure that they are safe and aware of possible fraudulent activities.
SI: What are some steps consumers can take to protect themselves from fraud and scams as they increase use of real-time digital payments?
CKL: Consumers need to be aware of the risks of APP fraud. They should always stop and think if something unusual happens, like someone messaging to say their bank account has changed. It is always worth contacting the person directly to check things like this to minimize the risk of fraud. Consumers should also be wary of downloading new applications, and scanning QR codes, which scammers are increasingly exploiting for fraud.
Above all, consumers should always be diligent about performing background checks before revealing their personal information and credentials, and always keep track and check their transactions.
SI: What’s your view on the adoption of digital currency (crypto) in the next few years?
CKL: While the technology behind digital currency has seen interesting developments over the past few years, the region has understandably been apprehensive about its adoption, especially considering the recent cryptocurrency crash and bad actors that use it to try and support criminal activity.
No matter where digital currency is headed in the next few years, stronger security and trust will need to precede its wider adoption.
SI: What makes FICO unique from others?
CKL: When it comes to fraud protection, we believe in an integrated approach that combines industry-proven advanced machine learning and artificial intelligence with real-time cross-channel fraud prevention. Our decades of investment in fraud research and innovation have yielded over 100 patents for fraud-specific machine learning innovation.
Our analytics expertise is trusted to protect 3 billion global payment cards and 65 percent of the world’s credit cards.
About FICO
FICO (NYSE: FICO) is a leading analytics software company, helping businesses in 90+ countries make better decisions that drive higher levels of growth, profitability and customer satisfaction. FICO’s groundbreaking use of Big Data and mathematical algorithms to predict consumer behavior has transformed entire industries. The company provides analytics software and tools used across multiple industries to manage risk, fight fraud, build more profitable customer relationships, optimize operations and meet strict government regulations.
When it comes to investing, you can either do it yourself (DIY) or you can rely on a professional.
The DIY approach requires you to take the time to study each investment asset and search for a brokerage firm or platform that will allow you to build your own portfolio.
However, the DIY approach can be very time-consuming. It also comes with increased responsibilities and worries. On your own, you will be more sensitive to shifts in the market and you may feel pressured into buying or selling the wrong asset at the wrong time, which can lead to heavy investment losses.
Additionally, certain investment products may be out of your reach. You may also be required to put up more capital than you are comfortable with.
The second option, relying on a professional, offers a safer investment experience. For investing in Unit Trusts, this means engaging the services of a Unit Trust Consultant, or a professional fund manager at a Unit Trust Management Company (UTMC) or at a funds distributor, such as at an Institutional Unit Trust Adviser (IUTA) or Corporate Unit Trust Adviser (CUTA).
What Can A Consultant Do For You?
Generally, Unit Trust Consultants are there to assist investor/client in establishing his/her investment objectives and to propose Unit Trusts products that are suitable to the investor/client based on his/her risk appetite. Additionally, Consultants are expected to provide prompt, efficient and continuous service to their investors/clients.
In short, Consultants have the necessary skills, relevant experience and dedicated resources to help you with your Unit Trust investments. They can help guide you towards your financial goals by helping you choose the right funds that suit your needs.
In addition, they can introduce investors to Unit Trusts that invests in assets/options that would otherwise not be accessible to an average DIY investor, vastly increasing your investment opportunities.
If you feel any hesitation about placing your trust – and your money – in the hands of another person, you can rest assured that legitimate Consultants are bound by FIMM’s Code of Ethics.
A good Consultant should have the following characteristics: honesty and integrity, professionalism, acting in the best interest of investors, deal with investors in good faith, comply with all requirements, avoid any conflicts of interest, provide accurate, timely and adequate information, and maintain investor confidentiality.
All these are meant to ensure that the Consultants’ ultimate duty is to help you reach your financial goals in the best way possible. Similar requirements are also applicable to the Private Retirement Scheme (PRS) Consultants.
The Benefits Of Choosing A Consultant
First-time investors, or those who have a particular financial goal in mind, would especially benefit from the advice that a Consultant can provide. The Consultant’s job is to educate you and help guide you along your investment journey.
A Consultant can also deliver a more personal touch, especially for investors that are new to or less familiar with Unit Trusts and Private Retirement Scheme (PRS).
Investors can engage a Consultant via the UTMC, IUTA, CUTA or even search for one themselves on the internet or through social media.
However, it is important to keep in mind that all Unit Trust and PRS Consultants are required to be registered with FIMM prior to them being able to market and distribute Unit Trusts and PRS. And it is easy to find out if your Consultant is legitimate.
By visiting FIMM’s website, anyone can check if a Consultant is authorised by FIMM or not. All he/she has to do is search the Consultant’s name or registration number. Additionally, anyone can reach out to FIMM – just send an email to info@fimm.com.my to make enquiries or to complaints@fimm.com.my to lodge a complaint.
This allows you to have a safety net while you embark on your investment journey. It also assures you that all your interests are safeguarded.
Bring Confidence To Investors
There are various channels to buy Unit Trusts, and investors who feel that they do not need advice may choose the DIY option without having to pay a sales charge or advisory fee.
One of the most common reasons for people not wanting to engage a Consultant has to do with the increasing amount of freely-available investment information over the internet.
Nonetheless, Consultants can provide a wealth of resources that investors doing DIY may lack. As investors become more aware of personal wealth management, continuous efforts in upskilling Consultants in advisory (goal-based investing) and client servicing (after-sales service) will add value and bring confidence to investors.
Regarding the issue of costs, in the form of consultant fees, it should be noted that all fees are clearly disclosed in the funds’ offering documents (i.e. prospectus), which is lodged with the Securities Commission Malaysia. Consultants cannot simply charge any fee that is not disclosed in the offering documents.
Furthermore, ongoing after-sales services from Consultants can also help investors achieve their financial goals by monitoring and keeping the investor informed of their progress, and reviewing the investment portfolio regularly and recommending changes where necessary.
The Final Word
Ultimately, the decision on how you wish to proceed with your investment is in your hands. Nonetheless, you must understand your investment objective and equip yourself with basic investment knowledge before you start investing.
Visit www.fimm.com.my for more information on Unit Trusts and Unit Trust Consultants.
The 2022 Budget was short on outlining any initiatives to enable Malaysia to build a more sustainable tax revenue base. The review of the tax incentives regime has yet to be finalised and hopefully, some progress will be announced in the coming Budget.
We expect the 2023 Budget to outline a more structured mid to long term reform of the tax system, so that we can have a more sustainable tax system. Malaysia needs to, in the medium term, broaden the scope of the existing Sales and Service Tax (SST), and ultimately make it a broad-based consumption tax with added features such as tax invoicing similar to a Value-Added Tax.
We should also have a more inclusive capital gains tax and move quickly on an efficient integrated national tax agency, in order to have a more sustainable tax.
Tax Treatments To Review
Currently, fees paid to tax advisers and company secretaries for the various services rendered on tax and corporate compliance matters are subject to restriction. Furthermore, the Inland Revenue Board of Malaysia (IRBM) recently issued the Corporate Tax Governance Framework (Framework) to enhance companies’ processes and governance on income tax matters.
The Framework expects the involvement from the board of directors, audit committee and senior management to set up appropriate checks and balances on tax reporting.
However, the IRBM states that costs incurred for advice and assistance to develop the Framework are considered to be capital in nature and therefore not tax deductible. This further irks businesses as such expenses are incurred to encourage corporate governance.
For a more sustainable tax, another area to review is the exclusion of Intangible Assets from the definition of the term “Plant” in the 2021 Budget. This has resulted in cost incurred such as computer software, licences, trademarks, patents, films, copyrights etc are no longer eligible for capital allowances or tax depreciation, despite these being assets utilised in the production of taxable income.
This is truly surprising, given the Government is leading the push from brick-and-mortar businesses to a digitalised and knowledge-intensive economy. Engagements have been held among various parties and it is hoped that in the upcoming Budget, the IRBM would review those tax treatments.
A More Sustainable Tax Structure
As a country, we cannot keep on borrowing and servicing debt. We should remove unnecessary exemptions and deductions, and simplify things to enable all to be part of the tax net. There is a need to push on towards a reliance on consumption taxes, in order to achieve a more sustainable tax.
The Ministry of Finance (MOF) has stated in the Pre-Budget Statement in June that tax reform initiatives with the objective of broadening the tax base, as proposed by Tax Reform Committee, will continue to be implemented.
The initiatives include:
a) Undertaking a review of broad-based incentives, reliefs and deductions
b) Improving tax administration through comprehensive registration of taxpayers
c) Better training of tax personnel
d) Improved registration of cross-border trade
e) Strengthening the tax audit and investigation
f) Enhancing legal certainty for taxpayers
Necessary details on the aforementioned will need to be spelt out in the 2023 Budget.
On the international front, Malaysia has committed to implement several agreed upon tax standards to create a competitive business environment for investors and to counteract cross-border tax evasion activities. To date, we have implemented four minimum standards of the Base Erosion and Profit Shifting (BEPS) Action Plans, while continuing to review the rest of the Action Plans under our domestic tax law.
Domestically, the tax net can be widened by tracking down those who should be within the tax net. That means curtailing tax evasion, curtailing smuggling, registering those who should be registered as taxpayers, and devising strategies using the tonnes of data that various agencies accumulate to ensure that all who should be taxable are indeed taxed.
In the Budget 2022, several initiatives were introduced to manage revenue leakages, including:
a) Removal of tax exemption on foreign-sourced income received in Malaysia by a Malaysian tax resident
b) Introduction of the Tax Compliance Certificate as a precondition for tenderers to participate in Government procurement
c) Implementation of a Tax Identification Number (TIN)
It was a surprise when a five-year exemption of the tax on foreign income was announced subsequently. Even Singapore and Hong Kong, which have similar tax systems to Malaysia do not have such a time-based exemption period.
However, the implementation of Tax Compliance Certificate and the TIN are very good compliance initiatives to reduce leakages, but more details are needed.
In line with the 12th Malaysia Plan to strengthen digital services infrastructure, the digitalisation of the tax function will be implemented with e-Invoicing to be done in stages. This will enhance the efficiency of the country’s tax administration, reduce compliance costs to taxpayers, and increase the efficiency of business operations. E-Invoicing will also support the use of TIN as a measure to expand the income tax net.
The Auditor General’s report has stated time and time again about losses and waste in the public sector. Greater accountability on where our tax ringgit goes and how it is utilised is essential to further narrow the trust deficit that exists, which is a factor why some are reluctant to pay their taxes.
A more sustainable tax structure for the future is probably in the pipeline. But such matters can be excruciatingly slow in coming into fruition, due to the lack of political will and vested interests.
All said, the 2023 Budget may turn out to be an election budget, with a slew of populist measures to score brownie points that may damage the country’s rather fragile fiscal momentum. Against this backdrop, debt and inevitably debt service charges, will rise.
Given that Malaysia’s narrow tax base means high concentration revenue risk to the overall economy, its fiscal vulnerability could increasingly become a trigger factor for sovereign rating downgrades by international credit rating agencies. Here’s to a more sustainable tax structure for a better Malaysia.
About the Author
Dr Veerinderjeet Singh is a tax observer who is the Non-Executive Chairman of Tricor Malaysia. He is the Immediate Past President of the MIA and MICPA, and a Past President of CTIM. He is a strong advocate of tax reforms and sits on the boards of a few public entities. He is also an Adjunct Professor at Monash University Malaysia, as well as a Vice Chair of the Global Tax Commission at the International Chamber of Commerce based in Paris.
In the midst of recovery, many sectors that were battered by the COVID-19 lockdowns, are looking to the government for further aid to strengthen and iron out obstacles in their path – more specifically for some help to be included in the pre-budget 2023 wishlists.
Small and medium-sized enterprises (SMEs), which had been the backbone of the economy but suffered greatly in the last two years, are looking for a stronger future in the new, digitalised economy.
The high incidence of death and loss of jobs during the earlier phase of the pandemic had also highlighted the importance of financial protection and planning. The current economic recovery had been boosted by, among other things, pent-up demand and a severely impacted base in the last two years of COVID-19 lockdowns.
Industries are now finding ways to sustain that recovery, with a much-needed assistance from the government.
Pre-Budget 2023 Wishlist: The SME Sector
In gauging the sentiment of SMEs, a survey was carried out by the Small & Medium Enterprises Association Malaysia (SAMENTA) with Affin Bank. Of the 613 SMEs responses received from the SAMENTA-AFFIN Survey on Business Conditions and Economic Outlook for SMEs 2022-2023, it showed that about 63% have cash reserves of less than four months, and 26% reported a revenue decline of 11%-30%.
The survey which was published in July 2022 noted that about 50% had expected a turnaround to pre-COVID 19 performance from 2023 onwards, around 4% have recovered and achieved pre-COVID 19 results and 2% do not expect to recover.
Almost 50% have moved part of their processes online, while 21% are performing better, while around 10% are fully digitalised.
The re-introduction of the Goods and Services Tax (GST) was favoured by 47% of respondents, while 25% are uncertain. Of those favouring the GST, 85% supported the initial rate of 4% and below, to be implemented beyond the second half of 2023.
In their digital transformation, SMEs subscribing to Software as a Service, which is a service infrastructure platform, are unhappy that they have to bear the costs instead of the foreign providers.
In this regard, they also want the digital tax to be suspended until a solution is found, said SME Association of Malaysia president, H.S. Ding.
SME Association of Malaysia president, H.S. Ding
To expedite the process of digitalisation, the Industry4WRD Intervention Fund should be extended to 2023. The current allocation of RM45 million is insufficient, as there are more than 500,000 SME manufacturing companies and related services sectors looking for a simpler and shorter approval process, informed Ding.
To promote and nurture the 5,000 start-ups and five Malaysian unicorns under the Malaysian Digital Blueprint, a RM10 million funding should be allocated for 2023, said Ding.
A ten-year tax exemption is sought for local manufacturers with a majority share of 70% and planning business expansion. A waiver or discount of 50% is also sought for business permits, licenses and assessments in 2023, as the COVID-19 lockdowns had caused Malaysian businesses to face losses and disruptions.
To assist SMEs and companies with reduced profits, corporate tax should be lowered. Higher tariffs for electricity lead to higher costs of doing business, SMEs are seeking to maintain the status quo in electricity surcharge or reduction in electricity and fuel tariffs in 2023.
The tenor for the SME Recapitalisation Fund of five years, or a repayment of 20% per year, should be lengthened to 10-15 years, as most SMEs do not have the cash flow to support that repayment period.
SAMENTA also proposes double capital allowance for companies that invest in research & development of orchards, as well as food or fruit related downstream activities.
For SMEs involved in domestic tourism, the tourism tax exemption should be extended to 2023. Under sustainable development, the Low Carbon Transition Facility for capital expenditure or working capital is proposed to be increased to a maximum of RM20 million from RM10 million.
The Business Recapitalisation Facility should also be increased to RM2 billion from RM1 billion, to cater for the 1.3 million SMEs in Malaysia. There should be more automation loans, and 120% loans are sought for SMEs to update the standard of factories to Industry 4.0.
For SMEs with profits of up to RM1 million, corporate tax should be lowered to 15%, suggested SAMENTA honorary secretary general, Yeoh Seng Hooi.
SAMENTA honorary secretary general, Yeoh Seng Hooi
Other budget recommendations by SAMENTA to help the SMEs to thrive include grants and workshops on ESG compliance, and double deduction on remuneration for the hiring of skilled workers and professionals (to enable SMEs to pay higher salary to attract talents), reintroduction of pre-shipment funding as per the Export Credit Refinancing and reduction in statutory fees by 50% for the first half of 2023, as post-recovery incentive to alleviate SME cost of doing business.
Pre-Budget 2023 Wishlist: Property Sector
Various measures have been taken to increase home ownership among Malaysians, but more needs to be done to address the problems of the housing and construction industries.
“We must ensure a smooth recovery from the pandemic lockdowns, and that all cylinders of the economy are firing. “It is tempting for stakeholders such as state and local authorities, as well as utility companies, to impose additional requirements on these industries. “But these temptations must be resisted,’’ said Real Estate and Housing Developers Association (REHDA) president Datuk N.K. Tong.
From right to left: Real Estate and Housing Developers Association (REHDA) president Datuk N.K. Tong, REHDA deputy president Datuk Ho Hon Sang
To mitigate the rising prices of building materials, REHDA proposes a waiver or reduction of duties on certain construction materials until prices normalise or become more manageable. Lifting of taxes and levies imposed on import materials as well as review and/or reduction of unnecessary charges will also help the industries.
To assist first-time homebuyers on properties priced up to RM500,000, REHDA proposes among others, a tax deduction on interest incurred during construction, personal tax relief (of RM20,000) and a one-off grant (of RM30,000) as well as a rent-to-own scheme to be considered.
The cooling measure since 2010, under Loan-to-Value, which compares the amount of the mortgage to the appraised value of the property, should be removed. REHDA also urged the government to review or relax the new and stricter conditions for participants of Malaysia My Second Home.
“A strong secondary market is crucial, as there will be more interest to invest in the primary market when buyers see property prices or rentals going up,” said Malaysian Institute of Real Estate Agents (MIEA) president, Chan Ai Cheng.
Malaysian Institute of Real Estate Agents (MIEA) president, Chan Ai Cheng
Stamp duty exemption for buyers in the secondary market and Real Property Gains Tax (RPGT) relief for sellers are proposed. Under a Home Ownership Campaign for Secondary Properties, MIEA proposes that buyers service the interest portion of the loan instalment for a certain period, instead of principal plus interest.
Pre-Budget 2023 Wishlist: Hotel, Tourism And Retail Sectors
As long as international leisure tourism is still restricted, the hotel industry will suffer a direct loss in revenue. Based on the Tourism Malaysia annual report 2019, receipts for accommodation from international arrivals had hit RM20 billion but currently, many are still on the road to recovery.
With the re-opening of interstate travel and domestic tourism, the Malaysian Association of Hotels (MAH) is asking for a lower wage subsidy, than previously requested, of 30% for employees with wages up to RM4,000, and 15% for those with wages up to RM8,000.
A minimum wage mechanism across the board does not encourage productivity or efficiency, instead, MAH proposes for an industry-based wage mechanism that is based on productivity, skills and tasks performed.
For reliable supply and demand of tourism-related data, a live on-demand, centralised tourism platform should be set up, to plan for the sustainable growth of the hotel and tourism industry.
In terms of tourism industry support as well as integrity and delivery of tourism data, the data should be released in a timely manner, in consultation with the industry.
In view of the massive upgrading and reinvestment required, the investment and reinvestment tax incentives for tourism and hotels should be extended for all categories up to 2025.
After suffering losses for two years, MAH is also seeking tourism recovery funding via soft loans that are interest-free or with low interest for reinvestment, upgrading, repair and maintenance of hotel properties as well as for operating expenses.
To drive domestic tourism, individual tax relief for travel and hotel expenditure within the country is proposed at RM5,000 per year. Exemption of the sales and service tax for hotels are to be extended till December 2022. The counter-productive tourism tax should be abolished to encourage high yield and long stay international arrivals.
To help address Malaysia’s weakness in international business events, a special budget should be allocated to the Malaysia Convention & Exhibition Bureau and Tourism Malaysia to pitch for international events. As the tourism industry invests heavily into international promotions, a special marketing grant for domestic and international marketing activities is proposed for business-to-business and business-to-consumer trade shows.
With the tourism industry just recovering from the lockdowns, there are very few group tours that hire 40-seater buses, many of which have not even had their road tax renewed. A conversion incentive should be given for normal tour buses to be converted into recreation or luxury vehicles, said Malaysian Inbound Tourists Association (MITA) president, Uzaidi Udanis.
A tourism bank can be set up to help expand the industry which does not just involve the provision of hotels and chalets for tourists, as there is also potential in medical, agriculture, youth and education tourism.
Retail Group Malaysia (RGM) hopes there will not be another movement restriction at the end of 2022, or early 2023.
“Malaysian retailers do not have the resources to deal with this crisis again,’’ said RGM managing director, Tan Hai Hsin.
RGM managing director, Tan Hai Hsin
The government has to resolve the problem of rising prices and its impact especially on the B40 and M40, and not allow these price shocks to linger until 2023.
Shortage of staff along the entire retail chain, and especially in Johor which faces competition from Singapore employers, also needs to be addressed soon, as this problem will slow down the economic recovery.
Against the threat of a looming recession, the government needs to take swift action to cushion the negative impact of a possible reduction in take-home pay and consumer spending.
Malaysia needs to attract more foreign tourists for the next one year, as foreign tourist arrivals of more than two million as of June, 2022 (with a target of 4.5 million by year-end, set by the Ministry of Tourism, Arts & Culture), is way below that of 26.1 million in 2019.
Pre-Budget 2023 Wishlist: Insurance And Financial Planning Sectors
The COVID-19 pandemic is a wake-up call, reminding us of how uncertain life can be. To encourage take-up of life insurance, the personal tax relief for life insurance premium should be increased from RM3,000 to RM5,000, said Life Insurance Association of Malaysia (LIAM) president, Loh Guat Lan.
Life Insurance Association of Malaysia (LIAM) president, Loh Guat Lan
Currently, there is a RM3,000 tax relief on insurance premium paid for medical and education insurance policies combined.
The tax relief for education, medical and health insurance (MHI) as well as MHI plans with co-share benefits should be raised from RM3,000 to RM6,000.
In Budget 2021, the tax relief limit on medical expenses for self, spouse and children for serious diseases, was increased from RM6,000 to RM8,000. This tax relief should be extended to include medical insurance premiums for self, spouse and children, said Loh.
LIAM informed that in 2021, RM11.9 billion in benefit payouts were made in the life insurance industry while RM4.6 billion were paid out for medical insurance.
The RM50 Perlindungan Tenang Voucher program for the B40 Bantuan Prihatin Rakyat group, which received encouraging responses but will end in December 2022, should continue for at least another year.
Many in this category do not have any form of insurance or takaful coverage. Having a second premium that is subsidised will be necessary in the midst of an uncertain recovery from COVID-19.
Data shows that less than half of employees, especially B40 workers, are being covered by some form of group insurance which is a cheaper form of insurance. LIAM therefore seeks a waiver of the 6% service tax for group insurance schemes.
The COVID-19 pandemic had caused many people to lose their jobs and also eroded their savings. Thus, to help Malaysians better manage their personal finances, Financial Planning Association of Malaysia (FPAM) proposed that a new tax relief of RM3,000 be given to Malaysians who engage licensed financial planners, said FPAM vice president, Rafiq Hidayat.
FPAM vice president, Rafiq Hidayat
As many Malaysians no longer have enough savings when they reach retirement age, tax relief on the private retirement scheme should be increased from RM3,000 to RM10,000 to attract more people to put aside their money for retirement.
With medical insurance premiums rising regularly due to the high inflation of medical expenses, FPAM also agrees with LIAM that this tax relief should be raised from RM3,000 to RM5,000.
Now that we’ve seen the Pre-Budget 2023 wishlist by the industries, let’s hope that their voices are heard.
Perkataan persaraan adalah merujuk kepada berhenti melakukan kerja aktif dalam kehidupan. Namun dalam dunia serba moden hari ini, konsep rancang persaraan sering dipandang sepi dan seolah-olah tak penting.
Persaraan yang bermakna adalah di mana seseorang itu mampu untuk menghadapinya tanpa perlu risau tentang kewangan. Barulah anda boleh berehat dan menikmati kerja keras anda selama ini.
Walaubagaimanapun, persaraan yang ideal tidak berlaku sekelip mata. Sama seperti membina otot yang kuat memerlukan latihan yang konsisten, prinsip yang sama juga terlibat dalam persaraan. Apabila kita ingin bangunkan otot kewangan yang kuat, kita perlu melakukan usaha yang berterusan untuk satu tempoh jangka masa yang panjang.
Sekiranya merancang untuk bersara adalah mudah, kenapa tak ramai yang melakukannya?
Perancangan Kewangan: Titik Mula Untuk Rancang Persaraan
Kesilapan terbesar seseorang dalam perancangan kewangan adalah dengan merasakan bahawa kita tidak perlu rancang persaraan mereka. Secara umumnya, orang ramai merasakan bahawa perancangan kewangan adalah untuk mereka yang kaya-raya saja.
Sedangkan rancang persaraan diperlukan oleh semua orang, tidak kira tua muda atau miskin kaya. Pelan kewangan yang lengkap akan memberikan kita kejelasan mengenai situasi kewangan semasa dan membolehkan kita mengenalpasti kekurangan yang ada, dan berusaha untuk mencapai sasaran kewangan.
Masa Takkan Tunggu Kita
Ada pelbagai alasan yang diberikan berkenaan tidak merancang kewangan dengan baik, dengan alasan paling biasa didengari “Saya terlalu sibuk dan tiada masa!”
Saya pasti kebanyakan daripada kita menghabiskan masa melakukan kerja yang tidak produktif seperti banyak masa dibazirkan di media sosial atau menonton terlalu banyak televisyen. Tetapi bukankah ianya merugikan kita sendiri apabila kita tidak merancang untuk masa depan kerana kesuntukan masa?
Sekiranya kita membiarkan saja persaraan untuk terjadi dengan sendirinya, kita berisiko wang kita akan habis sebelum nyawa kita yang habis! Adakah kita nak hidup di usia emas dengan berjimat cermat setiap masa?
Lebih Cepat, Lebih Bagus
Masa untuk anda berpijak di bumi yang nyata dan usah biarkan alasan menghalang anda. Sekiranya anda berusia pertengahan 20-an, ianya merupakan masa terbaik kerana usia yang muda akan beri banyak manfaat berganda. Sekiranya anda berusia 30-an, ianya lebih kritikal untuk mulakan perancangan persaraan dengan kadar segera.
Sebaik saja anda mencecah usia 40 tahun, anda perlu bekerja lebih keras untuk mencapai sasaran persaraan dan semakin mencabar untuk melaksanakannya ketika berusia 50 tahun.
Mula dengan mengira perbelanjaan peribadi untuk mengenalpasti ke mana duit anda dihabiskan sebelum anda mempunyai kawalan yang lebih ketat ke atas kewangan anda. Bak kata pepatah, “Sekiranya kita tak urus wang, wang yang akan mengurus kita”.
Generasi Sandwic
Dilema yang dihadapi kebanyakan rakyat Malaysia adalah ibubapa yang mempertaruhkan persaraan mereka demi masa depan pendidikan anak-anak, sementara itu terpaksa pula menjaga orang tua mereka. Ini merupakan kitaran kewangan yang tidak sihat, menyebabkan ramai yang berdepan dengan risiko persaraan yang tertekan.
Generasi muda sendiri berdepan dengan pelbagai bebanan disebabkan komitmen tinggi disebabkan oleh kos sara hidup yang tinggi dan tahap hutang yang menggunung.
Mindset perlu berubah bahawa ibubapa yang semakin berusia tidak meletakkan harapan kewangan yang tinggi ke atas anak-anak mereka. Pada masa yang sama, anak muda perlu lebih celik kewangan dan merancang duit mereka dengan lebih baik.
Dapatkan Bantuan Untuk Rancangan Persaraan
Sekiranya sesuatu masalah itu terlalu berat untuk diselesaikan seorang diri, ianya merupakan idea yang baik untuk meminta pertolongan. Ramai orang sibuk dengan kerja hakiki sehinggakan tak mampu untuk uruskan kewangan peribadi dan merancang secara serius tentang persaraan.
Sebenarnya bantuan sentiasa ada di dalam bentuk nasihat profesional dan bimbingan yang betul untuk mencapai sasaran kewangan anda. Semua orang ada kelebihan dan kemahiran sendiri, anda perlu fokus terhadap kepakaran anda untuk memperolehi pendapatan aktif di samping menggunakan khidmat perancang kewangan untuk mengembangkan kekayaan anda.
Sebelum ini, perancangan kewangan adalah sesuatu yang janggal dan orang ramai jarang berfikir mengenainya. Tetapi hari ini kita tidak mampu untuk berdiam diri sedangkan dunia bergerak dengan amat laju, dan mengambil pendekatan yang pasif adalah merugikan.
Masih belum terlambat untuk mempunyai rancangan yang kukuh dan pandangan yang jelas tentang bagaimana untuk berusaha dengan strategi yang betul.
Satu langkah kecil ke arah persaraan, satu langkah besar ke arah kebebasan kewangan.
Mengenai Penulis
Chan Li Yun merupakan seorang Perancang Kewangan berlesen dengan Finwealth Management Sdn Bhd dan ingin membantu orang ramai untuk meningkatkan taraf hidup dengan perancangan kekayaan yang betul. Beliau boleh dihubungi di liyun@finwealth.com.my.
Kami di Smart Investor dan Finwealth komited untuk bantu anda mengurus kewangan dengan lebih baik. Dapatkan sesi rundingan daripada seorang pakar secara percuma, dengan mengisi butiran anda di sini: https://www.smartinvestor.com.my/SIxFinwealth
I have over the last couple of years worked with entrepreneurs in start-up businesses. The one thing that continually stands out is that most of my clients do not consider the “legal aspects” as an important facet to their business. If they do seek advice, it may sometimes appear as if the advice expected is a quick solution to a long-term problem, which is never good for any type of business. That’s why it is important to know some of the legal tips, especially for start-ups.
Most start-up entrepreneurs use the reason that legal advice is costly and as such, it is an expenditure they do not want to invest in. I can assure you that once legal proceedings are initiated against you either personally or against your company, the cost you would incur in getting good legal counsel would be a lot more than what you may be incurring now.
In the long run, the fees will be higher, and the process a lot more time-consuming and protracted. It will be a detrimental lesson to learn. My advice is to always be aware of your legal rights and duties under the Companies Act 2016 if you wish to be in business.
I have always said that laying the foundation right from the beginning is key to any successful business. Here are legal tips, where you have to yourself these questions if you are in the start-up business or wish to start one:
1. Do I Have Partnership And/Or Founder Agreement In Place?
Oftentimes, people get so excited about a business plan that they forget to discuss the nitty-gritty. It is important to have regular meetings with your co-founders or investors about the terms of your partnership.
Some questions you may wish to ask and set out clearly in your partnership and/or founder agreement are:
What are your specific roles and responsibilities as founders?
What if one founder wishes to exit? What happens to his shares?
What is the agreed percentage that each founder will get?
What are the overall goals and expectations for the business?
What are the consequences if the founders do not hit their specific KPIs?
What are the pay-outs for allowances, dividends or salaries for co-founders?
2. Will The Start-up Be Registered As A Private Limited Company, Enterprise Or A Limited Liability Partnership?
This question is pivotal as there are tax implications as well as other accounting and auditing requirements that the start-up will need to comply with. Over and above that, personal liabilities of the partners and founders will also need to be considered.
For example, if an enterprise is set up, then there will be personal liability involved as opposed to a private limited company, where the company will take on that liability as a legal entity.
Do speak to your lawyer and accountant on a structure that would best suit you and your business.
3. Employment Issues
Image of business documents, pen and glasses on workplace during meeting of partners
Having employment contracts in place for the people you hire whether they are freelancers or full-time employees is vital. This will reduce the risk of having a labour court dispute arise in the event you wish to terminate a particular employee who is not performing as expected.
Do ensure that your employment contracts have a confidentiality clause that binds your employees so as to ensure that your client and your confidential information are not divulged or disseminated to any third party.
4. Data Protection Matters
When your start-up business involves managing someone else’s personal data, there are legal standards that you must comply with in managing and handling such personal data. For example, obtaining the consent of the Data Subjects before you obtain their personal data, storing of the said personal data, giving access of the personal data you have in your possession to the Data Subjects when they ask for it.
Recently, the Personal Data Protection Commissioner has indicated her intention to carry out inspection on data users that are not registered or not required to be registered under the Personal Data Protection Act in order to ensure compliance with the general provisions of the Act as well as the minimum security, retention and data integrity standards set out under the Personal Data Protection Standards 2015.
5. Intellectual Property Matters
It is important to check with the Intellectual Property Corporation of Malaysia (“MyIPO”) whether some other company or person has already trademarked your startup business name. Please do the necessary searches to ensure that you are not using someone else’s business name or logo. This will ultimately relieve you of any hassle of being sued for trademark infringement.
And what a pity that would be if you have already gained traction in your startup business and people are starting to recognise your brand name not to mention the unnecessary legal cost of having to defend a suit for trademark infringement.
What I have set out here are just a few of the areas you may wish to consider in your own startup business. However, each and every business will have different needs or requirements so it would be best to speak to a legal advisor on setting your foundation right.
Even if you are already a successful start-up, I believe it is never too late to do a legal audit to check if everything has been set right, to avoid any unnecessary legal repercussions.
About the author
SHARMILA RAVENDRAN is the founder of the law firm, Messrs Ravindran located in Mont Kiara, Kuala Lumpur. She has more than 14 years of experience in the legal industry servicing clients that include local and foreign companies. She is now actively involved in corporate advisory work and commercial litigation and is a Panel Adjudicator with the Kuala Lumpur Regional Centre for Arbitration. She also sits on the Bar Council Child Rights Committee and is the Legal Director for Lean in Malaysia. She can be contacted at sharm@ravindran.com.my.